
 India Diagnostic Imaging Equipment Market | 2026-2036
India Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
India Diagnostic Imaging Equipment Market Foresight
Solid-state detector materials are replacing legacy image intensifiers and is recalibrating unit economics across radiography and fluoroscopy systems. Siemens Healthineers leverages in-house photon-counting detector fabrication to command premium positioning in CT modalities. Wipro GE Healthcare anchors its India strategy through localized manufacturing at its Bengaluru facility, reducing import duty exposure on finished systems. Fujifilm Holdings Corporation differentiates through synthetic silica-based scintillator plates that improve dose efficiency in general radiography.
Diagnostic imaging equipment encompasses electromagnetic and acoustic energy-based systems engineered to visualize internal anatomical structures for clinical diagnosis, with spatial resolution ranging from sub-millimeter (CT/MRI) to sub-wavelength (ultrasound) depending on modality. These systems serve primarily to detect pathology, guide interventional procedures, and monitor therapeutic response across hospital and ambulatory settings. MRI systems capture the highest margin pools in India's product mix due to superconducting magnet import dependencies and specialized service contracts. Ultrasound dominates unit volumes through portable digital imaging deployments in primary health centers and obstetric clinics. Hybrid systems integrating PET-CT and SPECT-CT represent the fastest-growing technology tier as oncology networks expand molecular imaging capabilities.
CDSCO regulates medical device import and manufacturing licensing under the Medical Device Rules, while BIS certification mandates electrical safety and electromagnetic compatibility compliance for domestically assembled units. The PLI scheme for medical devices is reshaping capital allocation by offsetting 5-20% of incremental sales value for manufacturers achieving domestic value-addition thresholds. Stakeholders must monitor state-level public procurement aggregations under the Government e-Marketplace, where tender bundling of imaging systems with 10-year maintenance contracts is consolidating vendor selection criteria.
Market Dynamics
Photon-counting CT detector technology is recalibrating procurement criteria across India's hospital networks, compressing upgrade cycles for legacy energy-integrating systems while elevating service contract premiums for specialized maintenance.
Growth Catalysts
- PLI Scheme Incentives:The Production Linked Incentive scheme for medical devices offsets 5-20% of incremental sales value for manufacturers achieving domestic value-addition thresholds, redirecting capital toward Bengaluru and Hyderabad assembly facilities.
- Ayushman Bharat Infrastructure Expansion:Tier-II and Tier-III city hospitals are installing digital radiography and ultrasound systems under the national health mission, creating anchor demand outside metropolitan clusters.
- AI-Assisted Image Analysis:Machine learning algorithms embedded in PACS workstations are shortening radiologist reporting times, driving replacement demand for imaging systems with native AI integration.
Market Restraints
- Superconducting Magnet Import Dependency:MRI systems require niobium-titanium magnet coils sourced from Germany, Japan, and the United States, exposing installed base expansion to currency volatility and shipping bottlenecks.
- CDSCO Licensing Timelines:Medical Device Rules compliance for new modality introductions requires 18-24 month clearance cycles, delaying product launches relative to competitor markets with mutual recognition agreements.
- Trained Radiologist Density:India operates below WHO-recommended radiologist-to-population ratios, constraining effective utilization of installed high-end CT and MRI capacity in government medical colleges.
Strategic Opportunities
- Mobile Diagnostic Units:Containerized CT and mammography systems mounted on heavy-duty chassis are penetrating rural Maharashtra and Uttar Pradesh, bypassing fixed infrastructure gaps through pay-per-scan revenue models.
- Hybrid PET-CT Oncology Networks:Molecular imaging capabilities are expanding across tier-I city cancer centers, with FDG radiopharmaceutical distribution networks now reaching Chennai, Mumbai, and Delhi NCR.
- BIS Certification Streamlining:Revised electrical safety and electromagnetic compatibility standards for domestically assembled units are reducing compliance costs for manufacturers with captive Bengaluru or Pune fabrication facilities.
Industry Challenges
- Biomedical Engineer Shortage:Cryogen handling certification for superconducting MRI maintenance remains concentrated among Siemens Healthineers and Wipro GE Healthcare service teams, extending mean time to repair for third-party serviced systems.
- Legacy PACS Integration:Government medical colleges operating decade-old DICOM archives face data migration complexity when upgrading to cloud-native imaging platforms, delaying procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Diagnostic Imaging Equipment Market |
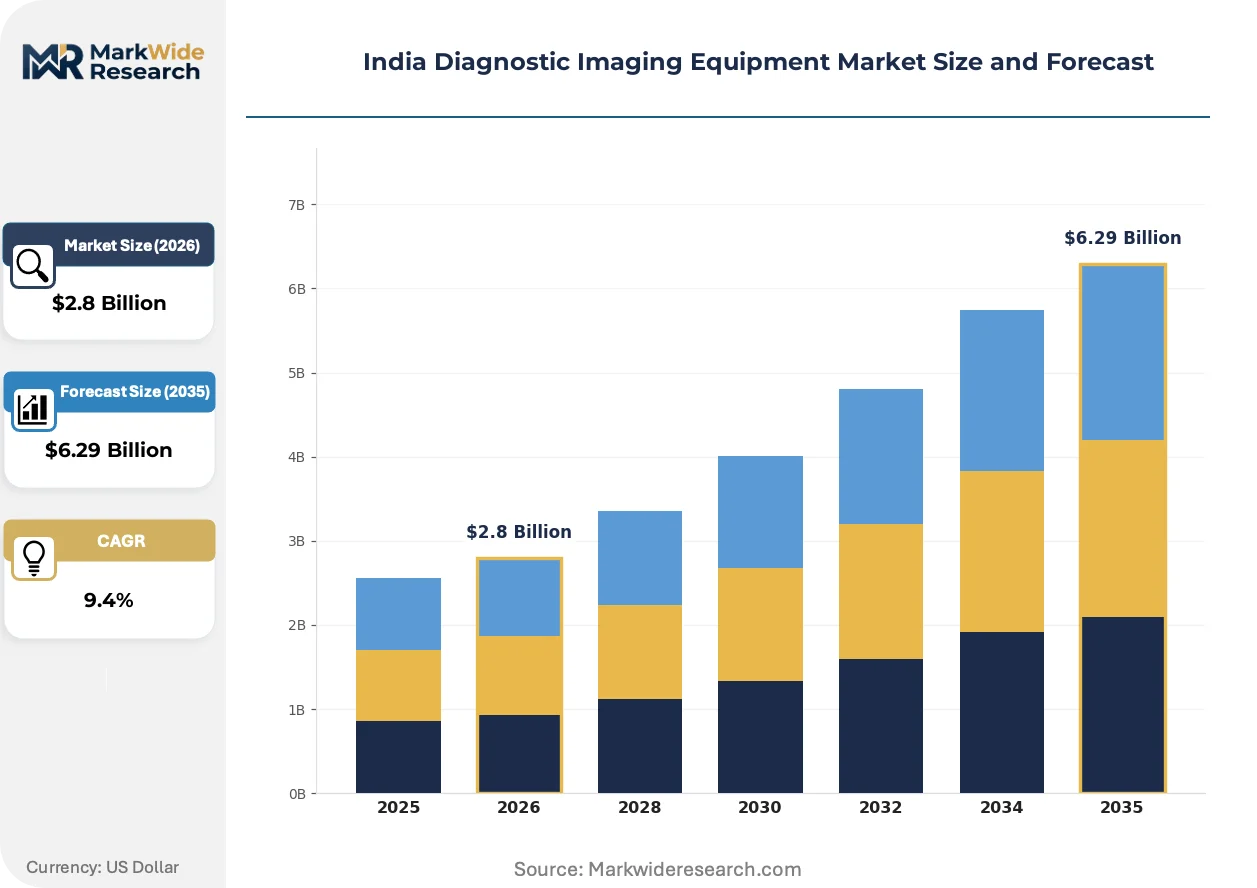
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scanner, Ultrasound Technology: Digital Imaging, 3D Imaging, Portable Devices, Hybrid Systems End User: Hospitals, Imaging Centers, Clinics, Research Institutions Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | Canon Medical Systems, Shimadzu Corporation, GE Healthcare, Esaote SpA, Mindray Medical International, Siemens Healthineers, Fujifilm Holdings Corporation, Wipro GE Healthcare, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Diagnostic Imaging Equipment Market Shifts & Advancements
Digital detector materials and computational imaging pipelines are compressing hardware replacement cycles while elevating software and service contract value capture across India's diagnostic imaging value chain.
Photon-counting detector arrays are consolidating market positioning in premium CT installations. These solid-state sensors directly convert X-ray photons to electrical signals, eliminating noise-inducing conversion steps inherent in scintillator-photodiode stacks. Corporate hospital chains in Mumbai and Delhi are prioritizing photon-counting systems for cardiac and pediatric protocols, where dose reduction commands procurement committee attention. The technology is consolidating vendor differentiation around in-house semiconductor fabrication capabilities rather than system integration alone.
CDSCO's tightened Medical Device Rules enforcement is accelerating quality management system investments among import-dependent distributors. Post-market surveillance obligations now mandate adverse event reporting within 30 days, compelling multinational manufacturers to establish dedicated Indian pharmacovigilance teams. Domestic assemblers with BIS-certified Bengaluru facilities are capturing tender preference in Government e-Marketplace aggregations, where electrical safety documentation carries weighted scoring.
Radiology departments are unbundling equipment procurement from decade-long maintenance contracts, compressing vendor lock-in duration. Corporate hospital chains now negotiate separate technical service agreements with third-party biomedical engineering firms, particularly for ultrasound and digital radiography modalities with standardized component architectures. This pattern is most visible in Karnataka and Tamil Nadu, where independent service organizations have accumulated spare parts inventory and trained technician pools.
India Diagnostic Imaging Equipment Market Segmentation
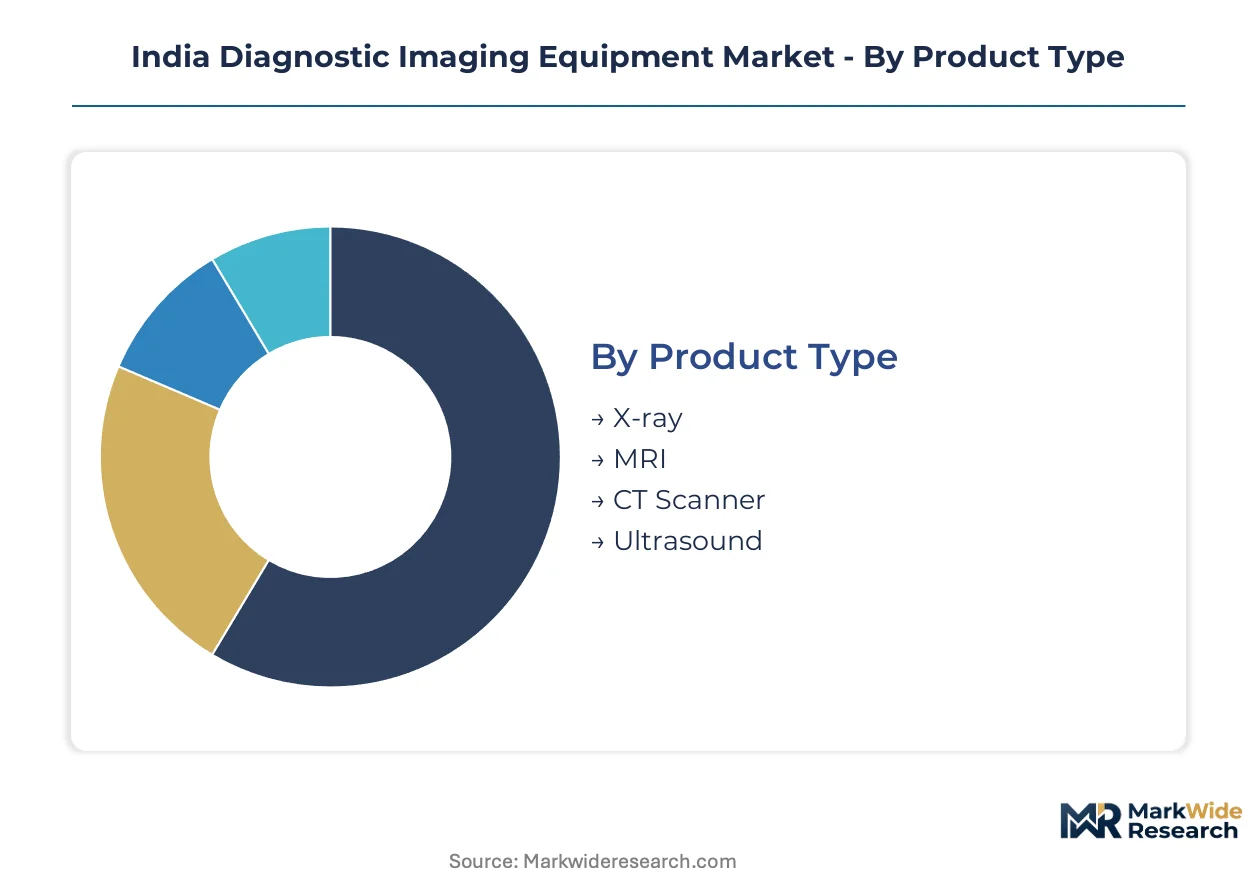
Diagnostic imaging procurement in India bifurcates sharply between high-margin imported systems requiring CDSCO licensing and domestically assembled units qualifying for PLI incentives. Understanding these segment boundaries clarifies where capital allocation concentrates and which regulatory pathways govern market entry.
Product Type:
CDSCO Medical Device Rules classify MRI and CT systems as Class C/D devices demanding 18-24 month import licensing, while digital X-ray and ultrasound face lighter Class B scrutiny with faster BIS certification pathways.
- X-ray:Solid-state detector arrays are displacing computed radiography cassettes in Maharashtra and Karnataka hospital networks. Tier-II city installations under Ayushman Bharat prioritize digital radiography for tuberculosis screening programs.
- MRI:Superconducting niobium-titanium magnet systems require specialized cryogen handling protocols. Demand concentrates in Delhi NCR and Mumbai corporate hospital chains where cardiac and neuroimaging protocols justify premium procurement.
- CT Scanner:Photon-counting detector configurations are elevating service contract premiums. Tamil Nadu government medical colleges are expanding installed capacity for trauma and oncology staging applications.
- Ultrasound:Portable digital systems dominate primary health center deployments. Obstetric clinics across Uttar Pradesh and Bihar drive volume procurement through compact cart-based configurations.
Leading the category by volume: Ultrasound. Growing fastest: CT Scanner.
Technology:
Capital deployment intensity varies threefold across technology tiers, with hybrid systems demanding dedicated shielding infrastructure and FDG radiopharmaceutical logistics while portable devices operate through distributor working capital financing.
- Digital Imaging:Direct radiography panels with cesium iodide scintillators are standardizing general radiography workflows. Karnataka-based assembly facilities are capturing tender preference through BIS-certified domestic production.
- 3D Imaging:Cone-beam CT reconstruction algorithms are penetrating dental and maxillofacial specialist clinics. Mumbai and Chennai imaging centers are prioritizing volumetric acquisition for implant planning.
- Portable Devices:Battery-powered ultrasound and digital X-ray systems enable point-of-care deployment. Mobile diagnostic units in rural Maharashtra operate these technologies through pay-per-scan revenue models.
- Hybrid Systems:PET-CT and SPECT-CT configurations require cyclotron-linked radiopharmaceutical supply chains. Oncology networks in Delhi NCR and Hyderabad are expanding molecular imaging capabilities fastest.
Dominating capital allocation: Hybrid Systems. Expanding most quickly: Portable Devices.
End User:
Procurement authority and maintenance contract duration diverge sharply across end-user categories, with corporate hospital chains unbundling equipment from service agreements while government tenders bundle decade-long maintenance.
- Hospitals:Tertiary care institutions in tier-I cities drive premium modality adoption. Corporate chains in Bengaluru and Hyderabad are prioritizing AI-native imaging platforms for radiologist workflow compression.
- Imaging Centers:Standalone diagnostic facilities concentrate on high-throughput CT and MRI services. Tamil Nadu and Maharashtra have witnessed rapid chain consolidation around standardized equipment platforms.
- Clinics:Specialist obstetric and orthopedic practices anchor ultrasound and mini-C-arm demand. Tier-II city clinics are upgrading from analog to digital radiography under government subsidy programs.
- Research Institutions:AIIMS and government medical colleges operate preclinical imaging and high-field MRI for protocol development. CDSCO licensing exemptions for research use accelerate technology evaluation cycles.
Commanding highest equipment spend per site: Hospitals. Penetrating underserved geographies fastest: Clinics.
Application:
Reimbursement density and procedure volume concentration shape application-level procurement, with oncology and cardiology justifying hybrid system investments while orthopedics drives portable C-arm and digital radiography demand.
- Oncology:Staging and treatment response monitoring require PET-CT and multiparametric MRI capabilities. Mumbai and Delhi NCR cancer centers are expanding molecular imaging networks with FDG distribution infrastructure.
- Cardiology:Coronary CT angiography and cardiac MRI protocols demand sub-millimeter spatial resolution. Kerala and Tamil Nadu hospital chains are prioritizing photon-counting CT for calcium scoring applications.
- Neurology:Functional MRI and perfusion imaging concentrate in academic medical centers. Government medical colleges in Karnataka and Maharashtra are upgrading 1.5T to 3T MRI platforms for epilepsy and stroke protocols.
- Orthopedics:Weight-bearing digital radiography and intraoperative 3D C-arms serve joint replacement workflows. Tier-II city hospitals are installing mini-C-arm systems for trauma and sports medicine expansion.
Generating highest revenue per procedure: Oncology. Expanding installed base fastest: Orthopedics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement clusters concentrate in Maharashtra, Karnataka, and Tamil Nadu where private hospital chains and government medical colleges drive bulk installations of CT and MRI systems.
Maharashtra
Mumbai and Pune anchor corporate hospital chain expansion for cardiac CT angiography and oncology staging protocols. CDSCO licensing timelines for imported Class C devices compress procurement cycles to 18-24 months. The Mumbai-Pune corridor hosts the densest concentration of PET-CT installations serving western India's cancer networks.
Karnataka
Bengaluru's medical device manufacturing ecosystem leverages PLI scheme offsets for domestic value-addition in digital radiography assembly. BIS certification for electrical safety compliance accelerates tender participation in Government e-Marketplace aggregations. The city's private hospital chains prioritize AI-native imaging platforms for radiologist workflow compression.
Tamil Nadu
Chennai's government medical colleges expand trauma and oncology staging CT capacity under state public health mission allocations. CDSCO post-market surveillance obligations mandate 30-day adverse event reporting for installed base maintenance. The Chennai-Coimbatore belt concentrates standalone diagnostic imaging center consolidation.
Delhi-NCR
AIIMS and government medical colleges drive high-field MRI procurement for epilepsy and stroke protocol development. CDSCO research use licensing exemptions accelerate technology evaluation cycles for preclinical imaging. The region's cancer centers anchor FDG radiopharmaceutical distribution network expansion.
Telangana
Hyderabad's oncology networks invest in hybrid PET-CT molecular imaging capabilities linked to cyclotron infrastructure. PLI scheme incentives redirect capital toward assembly facilities achieving domestic value-addition thresholds. The city's diagnostic chains standardize on photon-counting CT configurations for dose-sensitive pediatric protocols.
India Diagnostic Imaging Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational system integrators commanding premium positioning in superconducting MRI and photon-counting CT modalities while domestic assemblers capture tender preference through BIS-certified production. The vendor landscape organizes around three archetypes: semiconductor fabrication specialists controlling detector supply chains, diversified conglomerates with captive medical device divisions, and independent imaging center operators consolidating through standardized equipment platforms. Competitive moves concentrate on strategic partnerships for FDG radiopharmaceutical logistics and capacity expansion in Bengaluru and Hyderabad assembly corridors.
Among diversified healthcare conglomerates, Siemens Healthineers and Wipro GE Healthcare occupy positions anchored by in-house detector fabrication and localized manufacturing respectively. Fujifilm Holdings Corporation represents the materials-science archetype leveraging synthetic silica-based scintillator differentiation. These three exemplify distinct competitive vectors: captive semiconductor supply, import duty mitigation through domestic assembly, and dose-efficiency materials innovation.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Shimadzu Corporation |
| GE Healthcare |
| Esaote SpA |
| Mindray Medical International |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Wipro GE Healthcare |
| Koninklijke Philips |
| Others |
Supply & Pricing Matrix
Ayushman Bharat procurement bundling of imaging systems with decade-long maintenance contracts is forcing vendors to absorb upfront cost compression while recouping margin through service contract premiums. This demand-side structure elevates the importance of captive spare parts logistics and certified biomedical engineering networks as pricing levers.
Pricing Analysis
Volume-margins split sharply across the installed base: ultrasound and digital radiography systems ship at scale through distributor financing with compressed hardware margins, while superconducting MRI and photon-counting CT command premium positioning through specialized service contracts and import dependency. Three-tier pricing structure across premium, standard, and economy levels reflects CDSCO certification tiers, with Class C/D devices carrying 18-24 month licensing cost absorption. Pricing pressure stems from PLI scheme incentives redirecting procurement toward BIS-certified domestic assemblies. Government medical colleges exhibit highest price sensitivity due to fixed-budget tender processes; corporate hospital chains in Mumbai and Delhi NCR demonstrate lowest sensitivity where AI-native workflow integration justifies premium procurement.
Supply Chain Analysis
Refurbishment and remanufacturing flows for CT gantries and MRI magnets create secondary supply channels that compete with new equipment pricing in tier-II city markets. Manufacturing concentration rests on Germany, Japan, and the United States for superconducting niobium-titanium magnet coils, while South Korea and Taiwan anchor solid-state detector semiconductor fabrication. Cryogen handling infrastructure, helium supply logistics, and specialized shipping containers for superconducting systems constitute critical input dependencies. Single-source vulnerability concentrates in photon-counting detector arrays where in-house semiconductor fabrication capabilities remain limited to two multinational vendors. Distribution runs through Government e-Marketplace aggregations for public procurement alongside direct hospital system partnerships for private corporate chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Superconducting magnet import bottlenecks and cryogen handling certification scarcity prop pricing power for incumbents with captive service networks, constraining effective capacity expansion regardless of capital availability.
For Market Incumbents: Cement positioning through backward integration into detector semiconductor fabrication and captive Bengaluru or Hyderabad assembly facilities qualifying for PLI scheme offsets. Deepen service contract capture by building cryogen handling certification programs that third-party biomedical engineers cannot replicate, defending against independent service organization encroachment in ultrasound and digital radiography segments. For New Entrants and Emerging Players: AI-native image analysis algorithms embedded in PACS workstations offer the most penetrable wedge for market entry, targeting tier-II city imaging centers and government medical colleges seeking radiologist workflow compression without full system replacement. Focus initial deployment on portable ultrasound and digital radiography modalities with standardized component architectures that minimize specialized maintenance dependencies, leveraging distributor working capital financing rather than direct hospital capital expenditure cycles. For Investors and Strategic Acquirers: The window for entry favors domestic assembly specialists with BIS-certified facilities and established Government e-Marketplace tender participation. Long-term viability hinges on PLI scheme incentive continuity and radiopharmaceutical distribution network access for hybrid PET-CT expansion. Monitor CDSCO licensing timeline compression and mutual recognition agreement negotiations as inflection indicators for import-dependent premium modality entrants.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Licensing Streamlining | Reduced clearance cycles for Class C/D devices accelerate product launch velocity relative to competitor markets. |
| PLI Scheme Capacity Expansion | Domestic value-addition thresholds in Bengaluru and Hyderabad assembly corridors offset import duty exposure. |
| AI-Native Platform Integration | Machine learning embedded in PACS workstations shortens radiologist reporting times for corporate hospital chains. |
| Radiopharmaceutical Distribution Buildout | FDG logistics networks reaching Chennai, Mumbai, and Delhi NCR enable hybrid PET-CT oncology network expansion. |
| Mobile Diagnostic Unit Deployment | Containerized CT and mammography systems mounted on heavy-duty chassis penetrate rural Maharashtra and Uttar Pradesh. |
Research Methodology
Document review covered CDSCO Medical Device Rules filings, BIS certification records, Government e-Marketplace tender aggregations, and PLI scheme participant disclosures, complemented by interviews with hospital procurement committee members, biomedical engineering directors, radiology department heads, and medical device distributor operations managers. Secondary validation drew from import-export customs data, state public health mission budget allocations, and medical college infrastructure expansion records. Bottom-up equipment installation tracking and top-down healthcare expenditure modeling were triangulated against manufacturer production disclosures.
Installed base projections by modality and technology tier were generated across the analysis window, with segmentation dimensions spanning product type, technology class, end-user category, and application area. CAGRs were derived from equipment replacement cycle compression, infrastructure expansion under Ayushman Bharat, and PLI scheme incentive phase-in schedules. Model inputs incorporated radiologist density constraints, superconducting magnet import lead times, and FDG radiopharmaceutical distribution network reach.
Several conditions sit outside the modeled scope, including currency volatility effects on import-dependent systems, CDSCO mutual recognition agreement negotiations, and cyclotron infrastructure buildout timelines for radiopharmaceutical production. Forecasts reflect assumptions regarding PLI scheme continuity and state-level public procurement aggregation persistence. Practitioners should monitor CDSCO licensing timeline announcements, BIS standard revision schedules, and trained radiologist pipeline expansion for early signals of capacity constraint relaxation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
South America CT Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
India Mammography Market