
 Industrial Radiography Market | 2026-2036
Industrial Radiography Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Radiography Market Analysis
The capability gap between digitally integrated radiography providers and legacy film-dependent operators is collapsing as real-time imaging and automated defect recognition become baseline requirements. Baker Hughes Company leverages its energy-sector installed base to sustain long-term service contracts across pipeline and refinery inspection networks. General Electric Company anchors its position through in-house manufacturing of high-voltage X-ray tubes and proprietary image reconstruction algorithms. Fujifilm Holdings Corporation differentiates by controlling both analog film supply and digital detector fabrication, occupying a unique hybrid position in transitional markets.
Industrial radiography encompasses the use of penetrating electromagnetic radiation—X-rays generated at 10–450 kV or gamma rays from iridium-192 and cobalt-60 isotopes—to visualize internal structures of welds, castings, and composite materials without destruction. The technique relies on differential attenuation through dense and porous regions, producing contrast images that reveal cracks, voids, or inclusions critical to structural integrity assessment. Digital radiography leads among technology segments as flat-panel detectors and linear diode arrays displace silver-halide film in high-throughput manufacturing environments. Non-destructive testing anchors the largest end-user commitment across aerospace and energy sectors where regulatory mandates enforce periodic inspection intervals. Computed radiography occupies a shrinking middle ground as facilities defer phosphor-plate investments in favor of direct digital capture systems.
The U.S. Nuclear Regulatory Commission enforces strict source material licensing and exposure limits under 10 CFR Part 34, compelling radiography providers to adopt electronic dosimetry and remote-controlled exposure devices. ASME Section V and ISO 17636-2 establish image quality thresholds that favor digital systems with higher dynamic range and automated measurement capabilities. In Europe, the EU F-Gas Regulation and REACH restrictions on chemical processing agents accelerate the phase-out of wet-film development chemistry in favor of solvent-free digital workflows. Stakeholders must monitor evolving harmonization between national radiation safety codes and international equipment qualification standards to anticipate certification barriers and sourcing requirements.
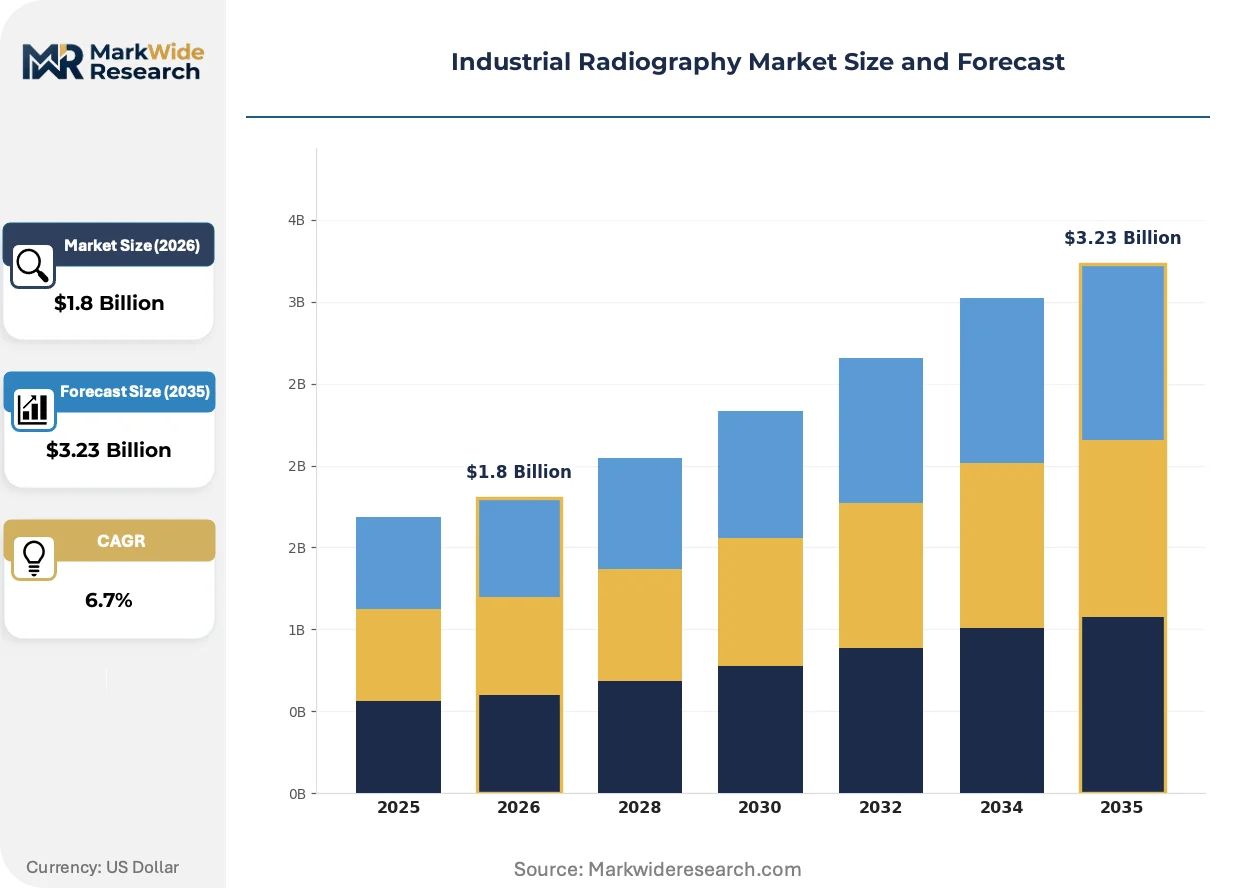
Market Dynamics
The transition from analog film to digital detector systems is compressing inspection cycle times and forcing capital reallocation across radiography service providers. ISO 17636-2 compliance deadlines and ASME Boiler and Pressure Vessel Code revisions are accelerating obsolescence of wet-chemistry workflows.
Growth Catalysts
- ASME Section V Updates:Revised image quality standards mandate higher dynamic range capture, compelling North American pipeline operators to replace aging film-based systems with flat-panel detectors.
- Aerospace NDT Expansion:Engine component inspection programs at airframe manufacturers in the United States, Germany, and Japan are scaling automated defect recognition for turbine blade casting verification.
- Gamma Source Demand:Refinery turnaround schedules in South Korea and China sustain iridium-192 deployment for pressure vessel weld assessment where portable digital units remain cost-prohibitive.
Market Restraints
- Isotope Supply Concentration:Cobalt-60 production concentrates at four commercial irradiation facilities globally, exposing radiography providers to source material allocation disruptions.
- Detector Cost Structure:Amorphous silicon flat-panel arrays require rare-earth scintillator materials subject to export licensing volatility from Chinese suppliers.
- Regulatory Friction:10 CFR Part 34 licensing timelines in the United States extend 14-18 months for new radiography operations, constraining service capacity expansion.
Strategic Opportunities
- India Infrastructure Buildout:National highway bridge inspection mandates and thermal power capacity additions create first-mover positioning for digital radiography deployment in Mumbai and Delhi industrial corridors.
- Battery Cell Inspection:Lithium-ion electrode lamination defects demand micron-resolution X-ray systems as electric vehicle manufacturing scales in Germany and Japan.
- EU F-Gas Phase-Out:Solvent-free digital workflows gain regulatory preference as wet-film chemistry faces REACH restriction, accelerating service provider margin recovery.
Industry Challenges
- Radiation Safety Certification:Level II radiographer qualification requirements under ASNT SNT-TC-1A create persistent talent bottlenecks as experienced technicians exit the workforce.
- Legacy System Integration:Phosphor-plate computed radiography investments from 2015-2019 resist full depreciation, delaying capital release for direct digital capture migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Radiography Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, Gamma Ray Systems, Computed Radiography, Film Radiography Technology: Digital Radiography, Analog Radiography, Fluoroscopy, Non-Destructive Testing End User: Aerospace, Energy, Manufacturing, Automotive Application: Inspection, Quality Control, Research, Maintenance |
| Companies Covered | Baker Hughes Company, Comet Holding AG, General Electric Company, 3DX-RAY Ltd., Rigaku Corporation, Fujifilm Holdings Corporation, Shimadzu Corporation, PerkinElmer, Inc., Nikon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Radiography Market Emerging Trajectories
Real-time imaging capabilities are collapsing the feedback loop between inspection execution and defect disposition, compressing quality assurance timelines from days to minutes. Automated defect recognition algorithms trained on weld geometry datasets are displacing human interpretation in high-throughput manufacturing environments.
Linear diode array detectors paired with high-energy X-ray sources are displacing cobalt-60 gamma radiography in thick-wall pressure vessel applications. Pipeline operators in Alberta and Texas are deploying these systems for girth weld inspection during construction phases. The displacement is compressing source material logistics costs while eliminating radioactive transport compliance burdens.
EU F-Gas Regulation restrictions on solvent-based film processing chemicals are mandating digital workflow adoption across European pressure equipment inspection networks. The regulation eliminates wet-chemistry alternatives for facilities seeking CE marking compliance under PED 2014/68/EU. German TÜV and French ASME-authorized inspection agencies are consolidating digital certification protocols to maintain cross-border service mobility.
Equipment-as-a-service contracting is fragmenting capital ownership from inspection capability among mid-sized fabrication shops. Third-party radiography providers in Ohio and Bavaria are unbundling hardware, software, and interpretation services into consumption-based billing. The model spreads most rapidly among automotive stamping plants facing cyclical volume volatility and balance-sheet constraints.
Industrial Radiography Market Segmentation
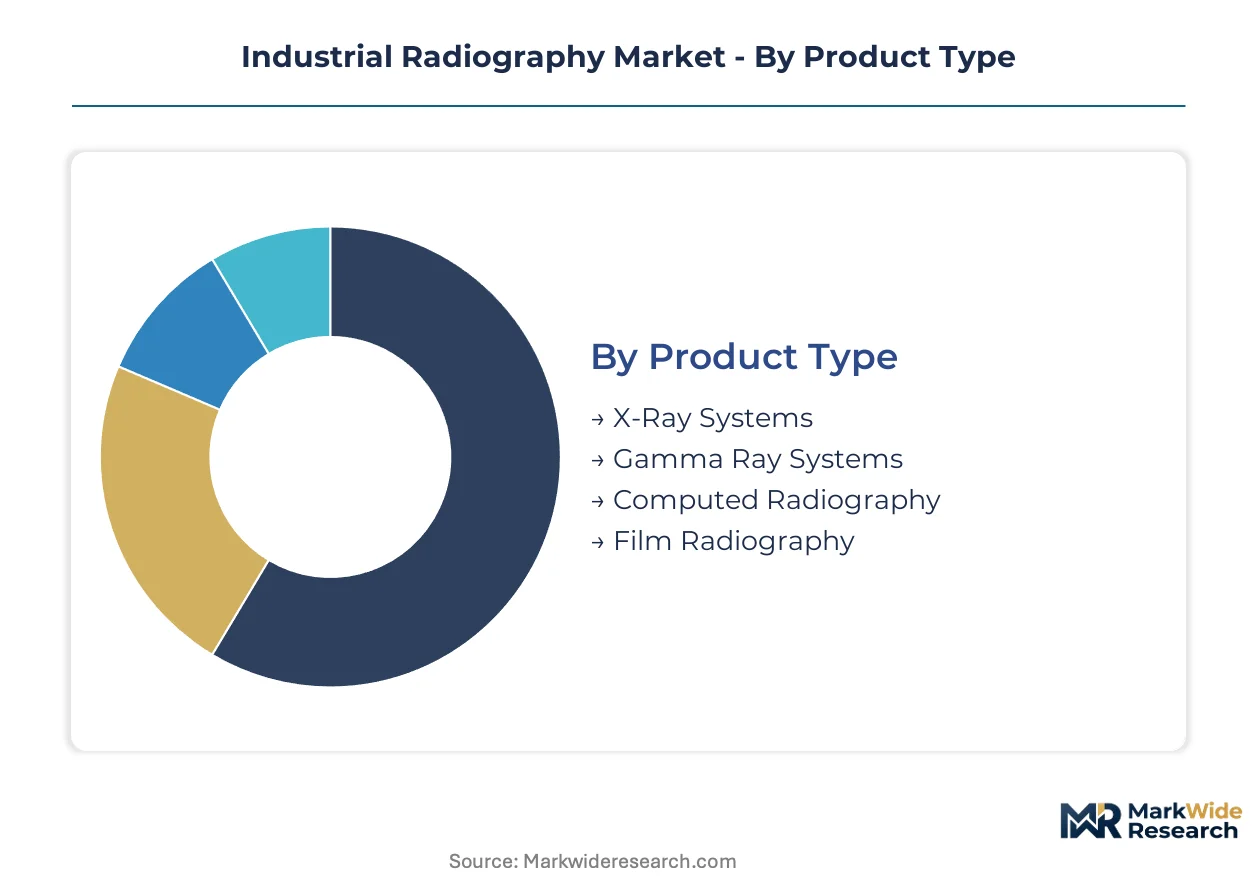
Industrial radiography segments map directly to distinct procurement channels and service delivery models. Equipment manufacturers, specialized NDT service providers, and in-house inspection departments each concentrate demand in specific technology tiers with divergent capital intensity and recurring revenue profiles.
Product Type:
X-Ray systems flow predominantly through direct manufacturer channels serving high-volume aerospace and energy clients, while gamma ray equipment concentrates in rental and service-provider networks where source material logistics dominate operational economics.
- X-Ray Systems:These systems generate penetrating radiation through high-voltage electron acceleration, typically operating between 10–450 kV for weld inspection and casting verification. Demand clusters at Boeing and Airbus tier-one suppliers in the United States and Germany, where ASME Section V compliance deadlines are compressing replacement cycles for aging film-based units.
- Gamma Ray Systems:Portable isotope-based units deploy iridium-192 and cobalt-60 sources for field inspection of thick-wall pressure vessels and pipeline girth welds. Refinery turnaround schedules in South Korea and China sustain deployment where digital alternatives remain cost-prohibitive for intermittent use.
- Computed Radiography:Phosphor-plate systems occupy a transitional position, capturing residual demand from facilities that invested in 2015–2019 CR infrastructure before direct digital capture matured. Deferred depreciation timelines delay full migration to flat-panel detectors.
- Film Radiography:Silver-halide wet-chemistry workflows persist in regulatory-lagging jurisdictions and small fabrication shops with minimal inspection volumes. REACH restrictions and EU F-Gas Regulation are accelerating phase-out across European pressure equipment networks.
By volume, X-Ray systems lead procurement tallies across manufacturing and energy sectors. By growth pace, computed radiography is contracting fastest as facilities bypass the intermediate technology tier entirely.
Technology:
Technology selection tracks customer sophistication tiers, with digital systems commanding premium pricing at certified aerospace suppliers while analog methods retain footholds in price-sensitive emerging markets.
- Digital Radiography:Flat-panel detectors and linear diode arrays deliver real-time imaging with automated defect recognition capabilities. Japanese automotive stamping plants in Toyota City and Nagoya are scaling deployment for high-throughput quality assurance.
- Analog Radiography:Film-based capture with chemical processing retains residual share in regions with limited capital access and permissive regulatory timelines. Wet-chemistry infrastructure investments create switching costs that delay digital migration.
- Fluoroscopy:Continuous X-ray imaging enables dynamic inspection of moving components and real-time weld monitoring. Specialized applications in pipeline construction and in-service pressure vessel assessment drive niche demand.
- Non-Destructive Testing:Integrated inspection protocols combining radiography with ultrasonic and eddy current methods. Major energy infrastructure operators in Alberta and Texas bundle multi-modal NDT contracts to reduce vendor management overhead.
Digital radiography dominates value capture in developed markets. Fluoroscopy is expanding most quickly in construction-phase pipeline applications where real-time feedback compresses project timelines.
End User:
End-user concentration determines service contracting structures, with aerospace and energy favoring long-term managed inspection agreements while automotive and general manufacturing prefer equipment-as-a-service or per-inspection billing.
- Aerospace:Airframe manufacturers and engine producers mandate certified inspection workflows for turbine blade castings and structural welds. United States and German facilities face the most stringent AS9100 and NADCAP accreditation requirements.
- Energy:Pipeline operators, refineries, and nuclear power plants enforce periodic inspection intervals under 10 CFR Part 34 and ASME Boiler and Pressure Vessel Code. Source material licensing and exposure documentation create high barriers to service entry.
- Manufacturing:General fabrication shops and metalworking facilities deploy radiography for casting verification and weld quality assurance. Cyclical volume patterns favor flexible procurement models over capital ownership.
- Automotive:Stamping plants and powertrain manufacturers inspect critical safety components including suspension forgings and transmission housings. Electric vehicle battery cell inspection is emerging as a specialized sub-segment in Germany and Japan.
Energy sector procurement leads in absolute spending on radiography services. Automotive applications are gaining share fastest as battery manufacturing quality requirements intensify.
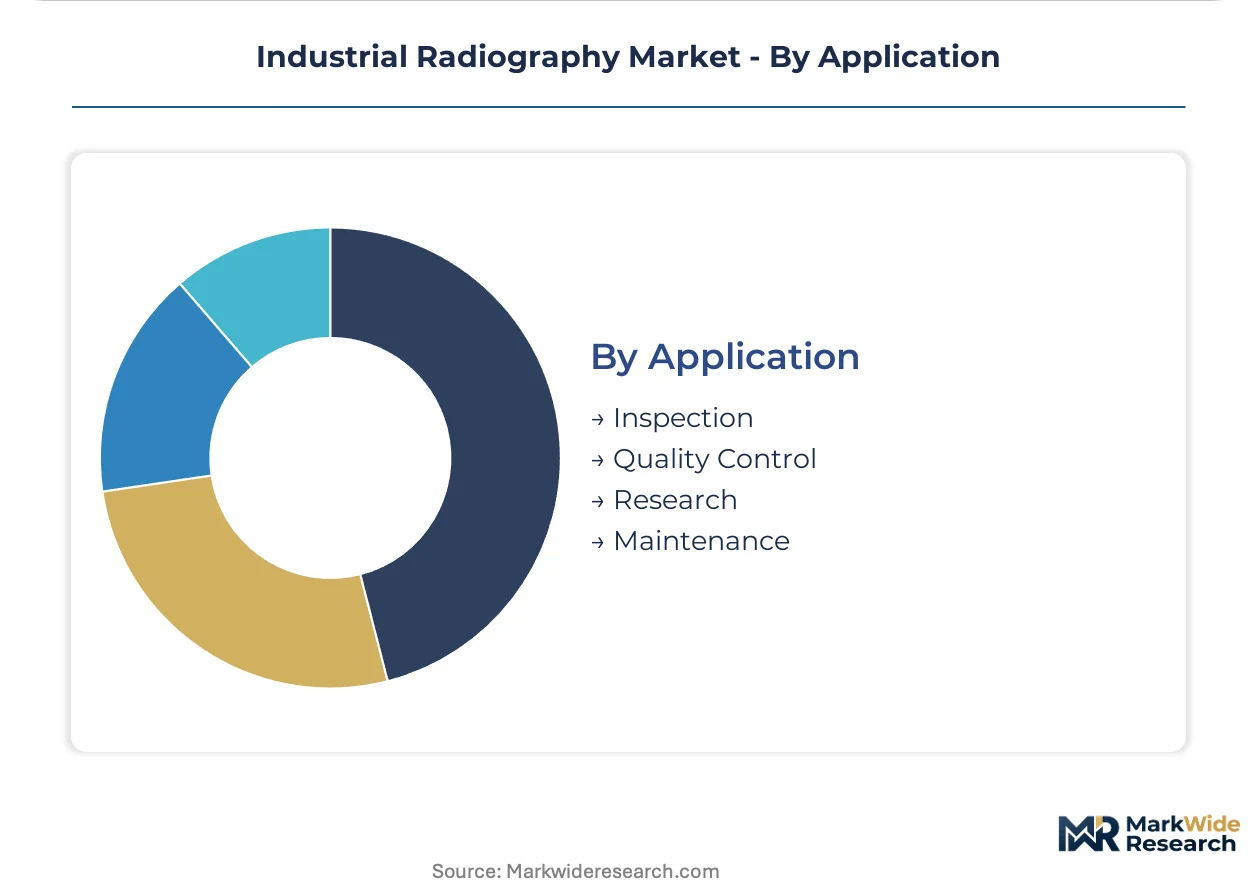
Application:
Application purpose shapes equipment specification, with inspection and quality control demanding certified traceability while research and maintenance applications tolerate greater flexibility in imaging protocols.
- Inspection:Regulatory-mandated periodic assessment of welds, castings, and pressure-retaining equipment. Nuclear power plants in the United States, France, and Japan operate under strict inspection calendars defined by national regulators.
- Quality Control:In-process verification of manufacturing output against dimensional and defect tolerances. High-volume automotive and aerospace production lines integrate automated digital radiography into continuous workflows.
- Research:Materials science and failure analysis applications requiring specialized imaging protocols and custom detector configurations. University and national laboratory procurement concentrates in Germany, Japan, and the United States.
- Maintenance:In-service assessment of aging infrastructure to determine remaining useful life and repair priorities. Pipeline operators in Alberta and Texas deploy portable gamma and digital X-ray systems for corrosion monitoring.
Inspection applications generate the largest service revenue pool. Research spending is climbing the fastest as additive manufacturing and advanced alloys demand new characterization methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in industrial radiography procurement varies sharply by end-use maturity. Aerospace manufacturers in Germany and Japan absorb premium pricing for certified digital systems, while general fabrication shops in India and Southeast Asia defer capital outlays until regulatory deadlines force compliance.
United States
Nuclear power plant inspection mandates under 10 CFR Part 34 sustain recurring demand for gamma source logistics and electronic dosimetry systems. The NRC's extended licensing timelines create capacity bottlenecks that favor incumbent service providers with established radiation safety programs. Houston and the Gulf Coast corridor concentrate refinery turnaround inspection activity where Baker Hughes maintains long-term pipeline service contracts.
Germany
Automotive stamping plants in Baden-Württemberg and Bavaria deploy flat-panel detectors for high-throughput quality assurance on suspension forgings and transmission housings. EU F-Gas Regulation and REACH restrictions on wet-film chemistry accelerate digital workflow adoption across TÜV-certified inspection networks. Munich and Stuttgart industrial clusters lead battery cell inspection deployment for electric vehicle manufacturing.
China
Thermal power capacity additions and national highway bridge inspection mandates create first-mover positioning for digital radiography in the Yangtze River Delta and Pearl River Delta. The country's national radiation safety regulator enforces source material licensing that concentrates gamma ray deployment among state-affiliated service providers. Shanghai and Shenzhen manufacturing corridors scale automated defect recognition for weld verification in shipbuilding and pressure equipment.
Japan
Toyota City and Nagoya automotive clusters integrate real-time digital radiography into continuous production workflows for powertrain quality control. METI industrial standards favor higher dynamic range capture systems that displace residual film-based methods. Nuclear reactor inspection programs under national regulator oversight sustain specialized service contracts for in-vessel component assessment.
South Korea
Refinery turnaround schedules in Ulsan and Yeosu sustain iridium-192 deployment for pressure vessel weld assessment where portable digital units remain cost-prohibitive for intermittent use. The national nuclear safety commission enforces exposure documentation requirements that favor established radiography contractors. Busan shipbuilding yards accelerate digital detector adoption for classification society certification of hull welds.
Industrial Radiography Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in industrial radiography equipment supply. The upper tier combines in-house X-ray tube manufacturing with proprietary image reconstruction software and long-term service contracting capabilities. Mid-tier specialists concentrate on detector fabrication, isotope logistics, or regional inspection services without full vertical integration. Competitive positioning hinges on backward integration into scintillator materials and strategic partnerships with aerospace OEMs for certified workflow integration.
Among diversified industrial conglomerates, General Electric Company and Baker Hughes Company exemplify the integrated service model, anchoring positions through captive energy-sector relationships and multi-year inspection agreements. Fujifilm Holdings Corporation occupies a distinctive hybrid position spanning analog film supply and digital detector fabrication, reflecting transitional market exposure. Comet Holding AG represents the specialized equipment fabricator archetype, with Swiss-based structural focus on high-voltage X-ray source technology.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Comet Holding AG |
| General Electric Company |
| 3DX-RAY Ltd. |
| Rigaku Corporation |
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| PerkinElmer, Inc. |
| Nikon Corporation |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-month NRC licensing timelines for new radiography operations compress service capacity expansion and concentrate pricing power among incumbent providers with established radiation safety programs. This lead-time bottleneck reinforces tiered pricing stratification across certified aerospace suppliers, energy infrastructure operators, and price-sensitive general fabrication shops.
Pricing Analysis
After-sales service contracts and long-term inspection agreements drive lifetime value capture more than equipment margins alone. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified aerospace workflows from refinery turnaround services and small-shop per-inspection billing. Price differentiation rests on certification grade and source material licensing status. Cost compression in the standard tier intensifies because phosphor-plate computed radiography facilities defer full depreciation before migrating to flat-panel detectors. General fabrication shops exhibit highest price sensitivity, while nuclear power plant operators absorb premium pricing for gamma source logistics and electronic dosimetry systems.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints on transpacific routes elevate inbound logistics costs for amorphous silicon flat-panel arrays and rare-earth scintillator materials. Manufacturing concentrates in Japan, South Korea, and China for detector fabrication, with Germany and the United States anchoring high-voltage X-ray tube production. Raw material dependencies include iridium-192 and cobalt-60 isotopes, rare-earth phosphors, and specialized semiconductor substrates. Single-source vulnerability concentrates at four commercial cobalt-60 irradiation facilities globally. Distribution runs through direct manufacturer channels for aerospace tier-one suppliers and rental-service networks for intermittent gamma ray deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
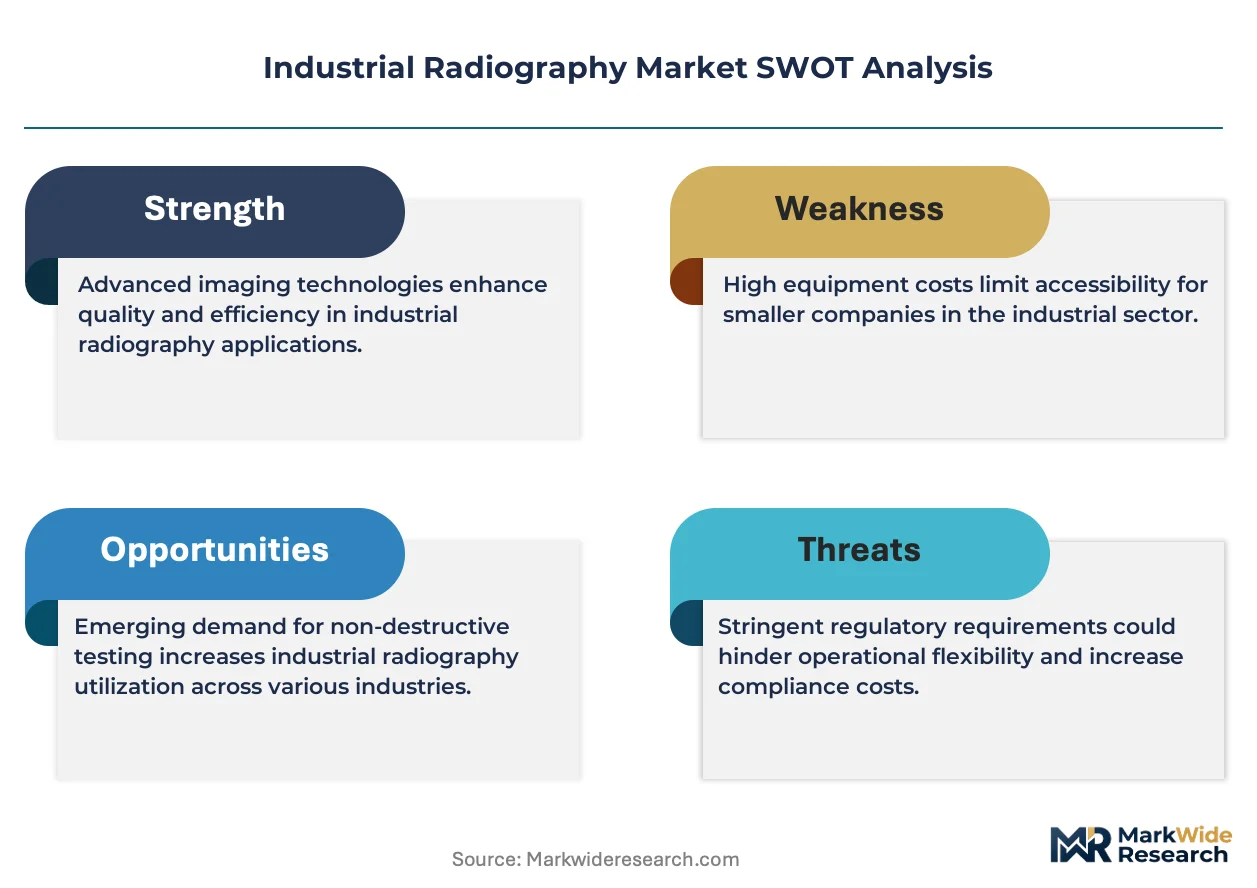
Regulatory entrenchment creates durable defensive moats in industrial radiography, as 10 CFR Part 34 licensing timelines and ASNT SNT-TC-1A qualification requirements erect structural barriers to service capacity expansion.
For Market Incumbents: Compound certification investments by deepening backward integration into scintillator materials and securing long-term isotope supply agreements before cobalt-60 allocation disruptions intensify. Expand service contracting capabilities in the Gulf Coast corridor to capture refinery turnaround demand. Threat substitution from linear diode array detectors displacing gamma radiography in thick-wall pressure vessel applications demands preemptive positioning in high-energy X-ray system portfolios. For New Entrants and Emerging Players: Differentiate on battery cell inspection specialization for electric vehicle manufacturing corridors in Germany and Japan, where micron-resolution X-ray demand outpaces established service capacity. Target first-mover positioning in Mumbai and Delhi industrial corridors for national highway bridge inspection mandates. White-space penetration runs through equipment-as-a-service contracting models that unbundle hardware, software, and interpretation for cyclical automotive stamping plants. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core NDT service divisions with captive energy-sector relationships. Long-term viability favors providers with integrated digital detector fabrication and proprietary automated defect recognition algorithms. Watch linear diode array displacement rates in Alberta and Texas pipeline construction as inflection indicator for gamma source demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scintillator Materials | Captive supply of rare-earth phosphors insulates against Chinese export licensing volatility. |
| Long-term Isotope Supply Agreement | Secured cobalt-60 allocation hedges against four-facility production concentration risk. |
| Automated Defect Recognition Algorithm Development | Proprietary weld geometry datasets displace human interpretation in high-throughput environments. |
| Equipment-as-a-Service Contracting Model | Consumption-based billing spreads cyclical automotive volume risk across provider balance sheets. |
| Battery Cell Inspection Specialization | Micron-resolution X-ray capability captures electric vehicle electrode lamination demand in Germany and Japan. |
Methodological Framework
A spread of perspectives from NDT service operations directors, plant engineers at aerospace tier-one suppliers, radiation safety officers, OEM procurement teams, and aftermarket service heads converged on the working assumptions. Primary interviews combined with secondary validation from ASME Section V documentation, NRC 10 CFR Part 34 filings, ISO 17636-2 standards records, EU F-Gas Regulation impact assessments, and customs trade data for radiography equipment imports. Bottom-up equipment procurement tallies and top-down service revenue estimates underwent triangulation to anchor volume and value outputs.
Segmentation dimensions modeled include product type, technology tier, end-user industry, and application purpose across the projection horizon. Analytical framework deployment tracked X-ray system, gamma ray system, computed radiography, and film radiography categories with digital, analog, fluoroscopy, and integrated NDT technology splits. CAGRs derived from historical replacement cycle analysis and regulatory compliance deadline clustering. Forecast inputs incorporated refinery turnaround schedule intensity and aerospace NDT program expansion trajectories without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside sustained nuclear power plant inspection mandates, stable isotope supply allocation, and ASME Section V compliance deadline adherence would require recalibration. Forecasts reflect assumptions regarding digital detector cost curves and qualified radiographer workforce availability. Specific risk factors including cobalt-60 production facility disruptions, rare-earth export restriction escalations, and Level II certification pipeline constraints could revise trajectory outcomes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Open System MRI Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
US Interventional Radiology Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
United States Nuclear Imaging Market