
 Vascular Screening Devices Market | 2026-2036
Vascular Screening Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Screening Devices Market Analytics
Software-defined imaging analytics is broadening what vascular screening vendors monetize beyond hardware sales. Fukuda sustains manufacturing scale across Asian markets through integrated transducer production. OMRON HEALTHCARE Co. Ltd leverages its consumer health channel to push portable vascular monitors into retail and pharmacy networks. Viasonix specializes in advanced Doppler systems that anchor its position in specialized vascular laboratories.
Vascular screening devices comprise non-invasive and minimally invasive diagnostic instruments that detect arterial stenosis, aneurysms, and venous insufficiency using ultrasonic waves, magnetic fields, or computed tomography contrast protocols, typically operating at frequencies between 2–15 MHz for peripheral vascular assessment. Ultrasound dominates installed base volumes due to lower capital requirements and real-time operational feedback, while CT angiography captures premium margin pools in acute care settings where spatial resolution below 0.5 mm drives clinical decision-making. AI integration represents the fastest-expanding technology segment as algorithmic plaque characterization reduces interpretation variability across operator skill levels.
FDA 510(k) premarket notification and EU MDR conformity assessment shape product development timelines and commercial access for vascular screening manufacturers in North America and Europe, with Japan's PMDA adding a third gate for Asia-Pacific entry. The WHO's noncommunicable disease monitoring frameworks and ISO 13485 quality management standards further constrain design controls and post-market surveillance obligations. Stakeholders must monitor reimbursement coding shifts for AI-augmented reads versus standard interpretation as payors recalibrate coverage policies.
Market Dynamics
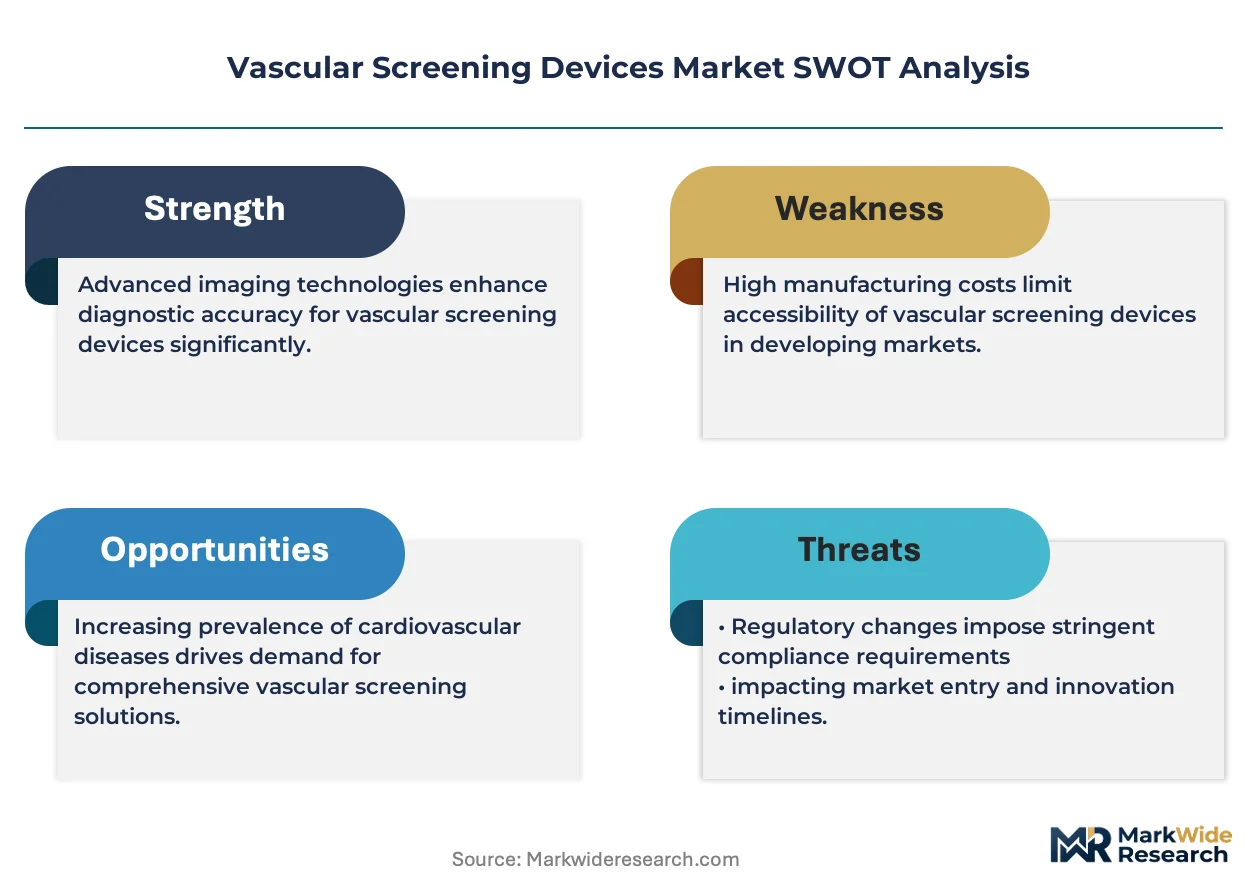
AI-augmented interpretation algorithms are compressing diagnostic variability across operator skill levels, forcing device vendors to restructure value capture from hardware toward software-enabled recurring revenue streams.
Growth Catalysts
- EU MDR conformity pathways:Stricter post-market surveillance obligations for Class IIa and IIb devices accelerate replacement cycles in European vascular laboratories seeking upgraded certification portfolios.
- Outpatient clinic expansion:Ambulatory surgical centers in the United States deploy portable Doppler systems to capture fee-for-service imaging volumes previously routed to hospital radiology departments.
- Plaque characterization algorithms:Machine learning models trained on multicenter ultrasound datasets reduce inter-reader disagreement in carotid stenosis grading, expanding addressable demand among mid-tier diagnostic facilities.
Market Restraints
- Transducer supply concentration:Piezoelectric crystal fabrication for high-frequency vascular probes clusters in East Asian component suppliers, exposing finished device manufacturers to input bottlenecks.
- CT angiography substitution:Hospital systems with installed CT capacity favor contrast-enhanced angiography for acute limb ischemia workups, limiting ultrasound penetration in tertiary emergency settings.
- FDA 510(k) timeline variability:Predicate device identification disputes for AI-embedded screening tools extend premarket notification review periods, delaying commercial launches.
Strategic Opportunities
- Pharmacy retail channel development:Consumer health networks in Japan deploy compact ankle-brachial index monitors for asymptomatic peripheral artery disease screening, creating new point-of-care access points.
- ISO 13485 quality management integration:Vendors aligning design controls with harmonized international standards gain accelerated regulatory reciprocity across multiple national markets.
- Telemedicine workflow convergence:Cloud-native Doppler systems paired with remote interpretation platforms enable vascular screening in rural German primary care practices lacking on-site sonography expertise.
Industry Challenges
- Sonographer training deficits:Vascular laboratory accreditation bodies report widening gaps between certified technologist supply and outpatient clinic expansion rates, constraining device utilization.
- Legacy PACS interoperability:Hospital information systems built on DICOM variants without AI metadata fields require middleware investments to integrate algorithmic screening outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Screening Devices Market |
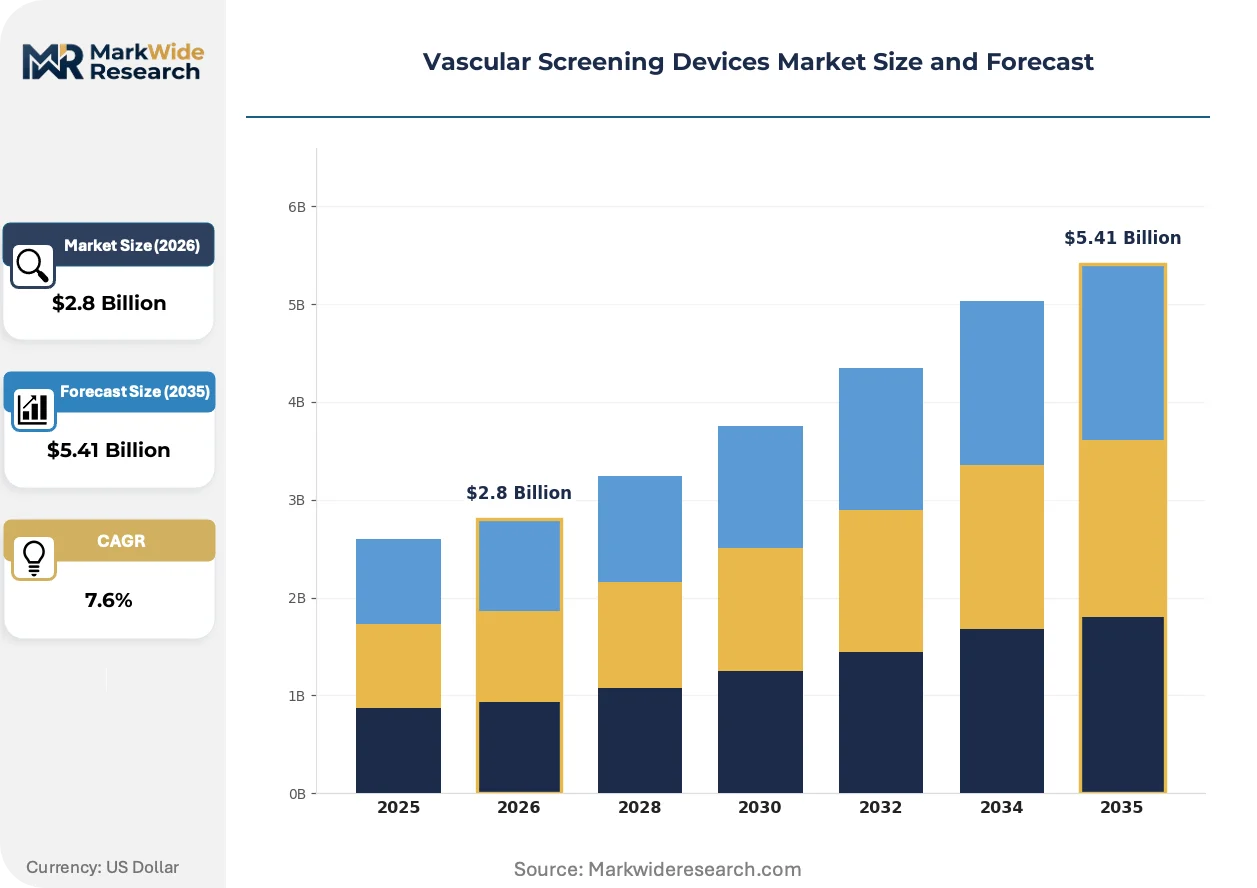
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, CT Angiography, MRI, DSA Technology: 3D Imaging, Portable Devices, Non-Invasive Methods, AI Integration End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Home Care Application: Atherosclerosis Detection, Peripheral Artery Disease Screening, Thrombosis Assessment, Vascular Malformation |
| Companies Covered | Fukuda, Unetixs Vascular Inc., Collaborative Care Diagnostics LLC, CorVascular Diagnostics LLC, Koven Technology Inc., D.E. Hokanson Inc., enverdis GmbH, OMRON HEALTHCARE Co. Ltd, Viasonix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Screening Devices Market Evolving Landscape
Software-defined analytics layers are redefining competitive differentiation in vascular diagnostics, compressing hardware commoditization timelines while opening subscription-based monetization pathways.
Shear wave elastography for arterial wall stiffness quantification is consolidating technical validation across European research consortia. Tertiary care centers in Germany and France adopt the modality for early atherosclerosis monitoring. The technology is consolidating multiple functional assessments into single-procedure workflows, reducing per-patient scan durations.
Japan's PMDA has tightened software-as-a-medical-device classification criteria for AI-powered stenosis detection algorithms. Domestic manufacturers now face supplementary clinical evidence requirements for training dataset provenance. Vascular screening vendors targeting Japanese market entry prioritize prospective validation studies over retrospective algorithm development.
Point-of-care purchasing committees increasingly unbundle device procurement from long-term service agreements. Hospital systems in the United States negotiate separate contracts for hardware, software licenses, and preventive maintenance. This pattern concentrates negotiating leverage among integrated delivery networks with centralized supply chain functions.
Vascular Screening Devices Market Segmentation
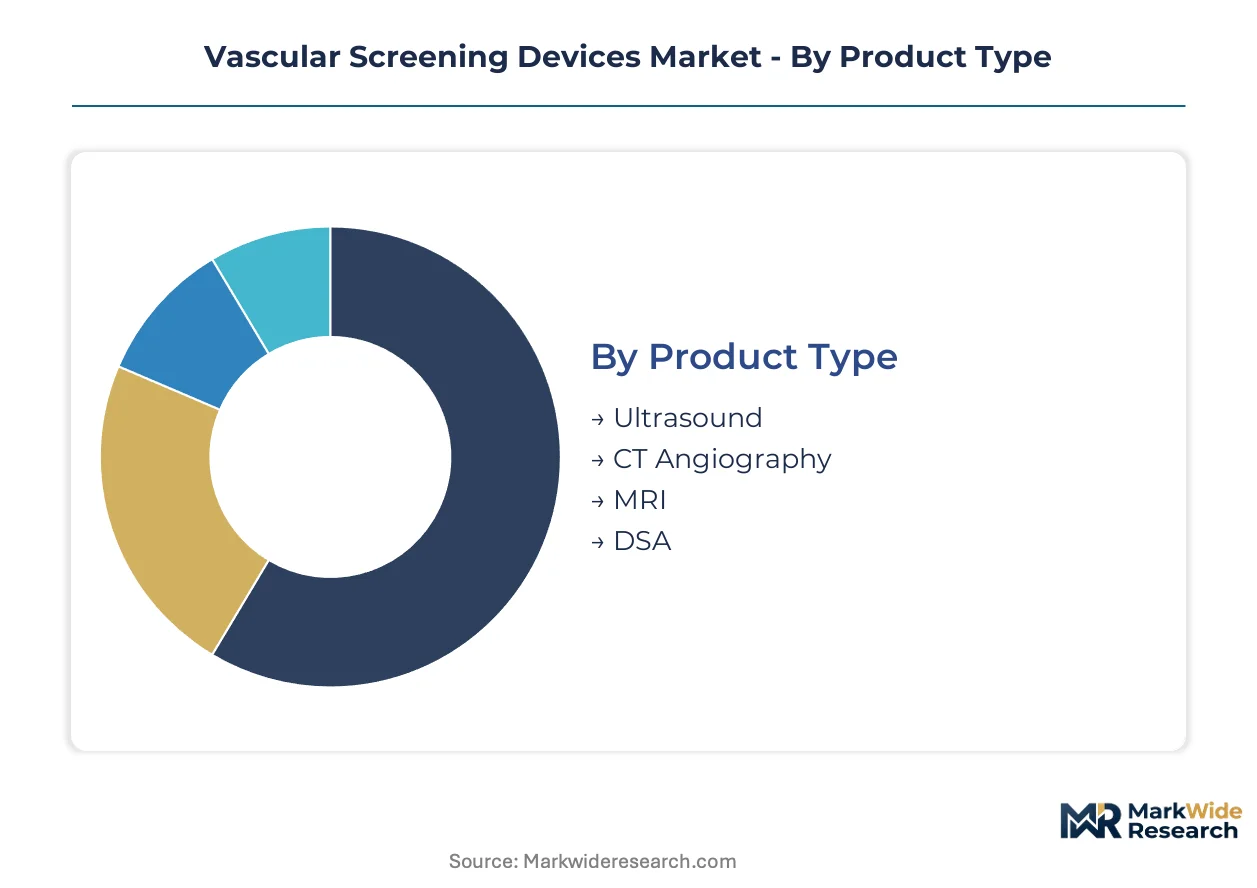
Vascular screening devices fragment across multiple technical and operational axes that determine reimbursement pathways, capital deployment cycles, and regulatory classification burdens. Understanding these segment boundaries clarifies where hardware commoditization pressures concentrate versus where software-enabled differentiation sustains margin capture.
Product Type:
Technical specifications around spatial resolution, contrast mechanism, and ionizing radiation exposure define the capital intensity and clinical workflow integration for each modality.
- Ultrasound:Operates at 2–15 MHz frequencies for peripheral vascular assessment with real-time Doppler feedback and zero ionizing radiation. Demand concentrates in United States outpatient clinics where lower capital requirements enable decentralized deployment and fee-for-service capture outside hospital radiology departments.
- CT Angiography:Delivers sub-0.5 mm spatial resolution through contrast-enhanced protocols, commanding premium positioning in German tertiary emergency settings where acute limb ischemia workups require rapid anatomical certainty despite higher procedure costs and radiation exposure.
- MRI:Magnetic resonance angiography avoids iodinated contrast in renal-compromised populations through gadolinium-based or non-contrast protocols.
- DSA:Digital subtraction angiography remains the reference standard for interventional planning despite its invasive catheter-based delivery.
Mature deployment sits with Ultrasound across primary care networks. Newer deployment is concentrated in CT Angiography within integrated stroke centers and trauma hubs.
Technology:
Cost tier stratification separates installed-base hardware from incremental software layers that vendors monetize through recurring licensing.
- AI Integration:Algorithmic plaque characterization and automated stenosis grading reduce inter-reader variability across operator skill levels. Demand concentrates in Japanese diagnostic centers where PMDA's tightened software-as-a-medical-device classification has elevated clinical evidence requirements for training dataset provenance.
- 3D Imaging:Volume-rendered vascular reconstructions enable surgical planning and patient communication through intuitive anatomical visualization.
- Portable Devices:Compact Doppler systems and battery-powered ultrasound units extend screening access to pharmacy retail networks and rural primary care practices lacking fixed imaging infrastructure.
- Non-Invasive Methods:Ankle-brachial index monitors and photoplethysmography sensors target asymptomatic population screening with minimal operator dependency.
Volume leadership belongs to Non-Invasive Methods in community screening programs. Value expansion is climbing the fastest through AI Integration as vendors restructure revenue from hardware sales toward subscription-based analytics.
End User:
Customer type determines procurement authority, service contract structures, and the balance between capital purchase versus operational lease arrangements.
- Outpatient Clinics:Ambulatory surgical centers in the United States deploy portable Doppler systems to capture imaging volumes previously routed to hospital radiology departments, unbundling device procurement from long-term service agreements to concentrate negotiating leverage.
- Diagnostic Centers:Dedicated vascular laboratories in Germany and France consolidate multiple functional assessments into single-procedure workflows using shear wave elastography for arterial wall stiffness quantification.
- Hospitals:Tertiary institutions with installed CT capacity favor contrast-enhanced angiography for acute presentations, limiting ultrasound penetration in emergency settings despite lower per-procedure costs.
- Home Care:Consumer health channels in Japan push compact ABI monitors into retail and pharmacy networks for asymptomatic peripheral artery disease detection.
Procurement sophistication peaks with Diagnostic Centers pursuing ISO 13485-aligned quality management. Accessibility expansion is gaining share fastest through Home Care as consumer health companies leverage existing retail distribution.
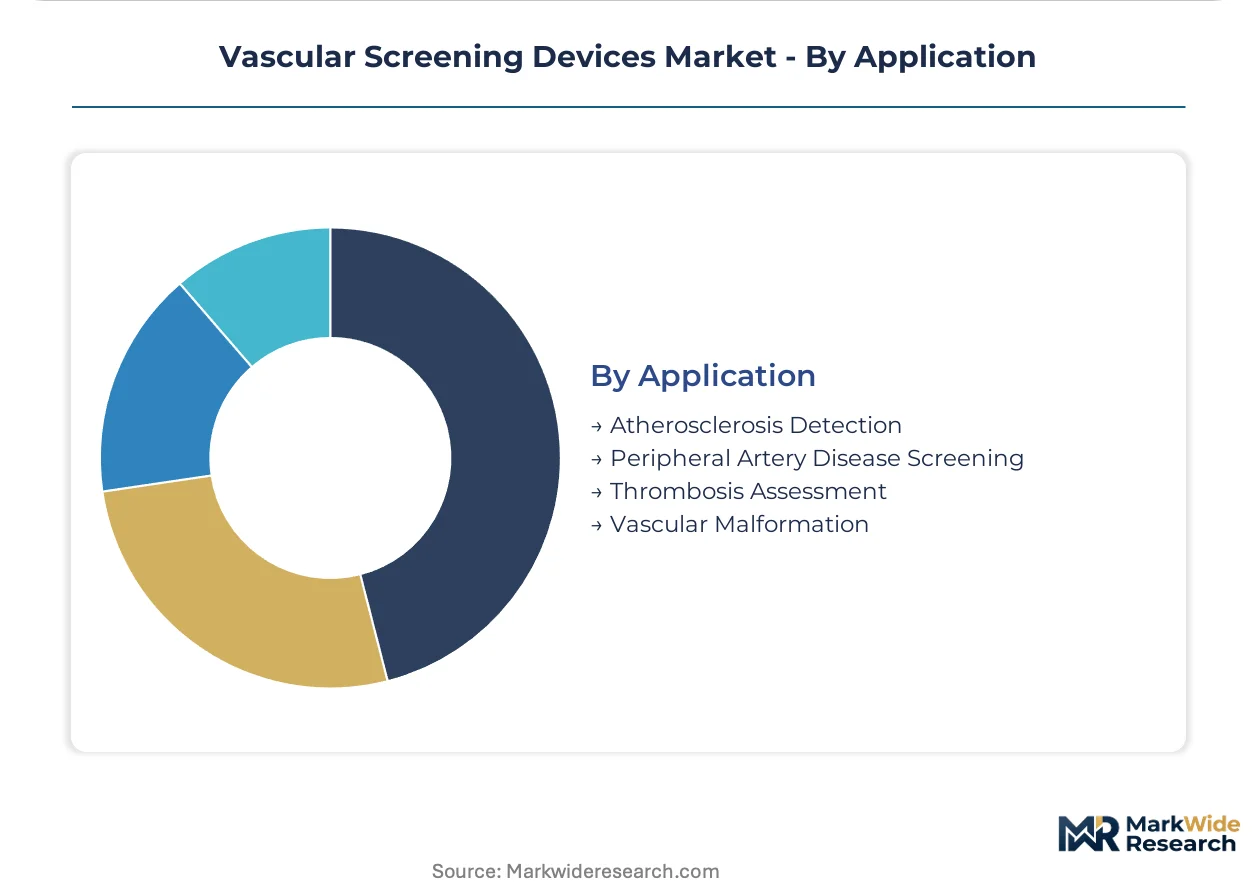
Application:
Clinical indication drives reimbursement coding specificity and the regulatory evidence burden required for diagnostic claim substantiation.
- Peripheral Artery Disease Screening:Ankle-brachial index measurement and segmental pressure studies dominate volume due to asymptomatic population targeting and alignment with cardiovascular risk reduction programs. Demand concentrates in United States Medicare-eligible populations where preventive service coverage incentivizes systematic detection.
- Atherosclerosis Detection:Carotid intima-media thickness and plaque burden quantification support cardiovascular risk stratification beyond traditional Framingham scores.
- Thrombosis Assessment:Compression ultrasound and D-dimer algorithms guide anticoagulation decisions in suspected deep vein thrombosis.
- Vascular Malformation:Congenital and acquired anomaly characterization requires multimodal imaging correlation for treatment planning.
Reimbursement stability favors Atherosclerosis Detection within established cardiovascular risk protocols. Screening penetration is expanding most quickly through Peripheral Artery Disease Screening as payors recalibrate coverage for asymptomatic detection programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device fabrication clusters concentrate in East Asian component suppliers while consumption tilts toward North American and European healthcare systems with established reimbursement pathways for preventive vascular screening.
United States
Medicare preventive service coverage for ankle-brachial index testing drives systematic peripheral artery disease detection in fee-for-service outpatient settings. FDA 510(k) premarket notification pathways shape commercial launch timelines for algorithm-embedded screening tools. Ambulatory surgical centers in Texas and Florida deploy portable Doppler systems to capture imaging volumes previously routed to hospital radiology departments.
Germany
Shear wave elastography adoption for arterial wall stiffness quantification concentrates in tertiary care centers across Bavaria and Baden-Württemberg. EU MDR conformity assessment requirements for Class IIa and IIb devices accelerate replacement cycles in vascular laboratories seeking upgraded certification portfolios. The Stuttgart-Mannheim corridor hosts specialized diagnostic centers consolidating multiple functional assessments into single-procedure workflows.
Japan
PMDA's tightened software-as-a-medical-device classification elevates clinical evidence requirements for AI-powered stenosis detection algorithms in domestic diagnostic centers. METI-supported cardiovascular risk reduction programs expand asymptomatic screening access through retail pharmacy networks. Tokyo and Osaka metropolitan areas concentrate demand for compact ABI monitors targeting consumer health channels.
China
NMPA medical device registration requirements constrain import timelines for foreign vascular screening manufacturers while domestic production scales in the Yangtze River Delta. Hospital procurement reform shifts purchasing authority toward centralized provincial platforms. Shanghai and Suzhou industrial clusters house piezoelectric crystal fabrication facilities supplying high-frequency vascular probe components.
United Kingdom
NHS England cardiovascular disease prevention contracts create volume commitments for community-based vascular screening programs in primary care networks. MHRA post-Brexit regulatory divergence from EU MDR introduces parallel conformity assessment burdens for device vendors. The Oxford-Cambridge-London triangle concentrates academic research consortia validating novel elastography protocols for early atherosclerosis monitoring.
Vascular Screening Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the vascular screening landscape. Integrated device manufacturers with captive transducer fabrication capabilities face competition from specialized software developers licensing algorithmic modules to third-party hardware platforms. Three strategic archetypes dominate: diversified medical technology conglomerates with consumer health distribution, specialized vascular diagnostic pure-plays with laboratory-focused portfolios, and component suppliers with backward integration into finished device assembly. Competitive moves concentrate on regulatory reciprocity alignment across FDA, EU MDR, and PMDA jurisdictions, plus unbundling of hardware procurement from software subscription agreements.
Within the diversified medical technology tier, OMRON HEALTHCARE Co. Ltd exemplifies players leveraging consumer health channel infrastructure to push portable vascular monitors into retail and pharmacy networks. Fukuda represents East Asian manufacturers sustaining fabrication scale through integrated transducer production across domestic and export markets. Viasonix occupies a specialist position among advanced Doppler system developers anchoring presence in dedicated vascular laboratories rather than generalist diagnostic settings.
| Leading Market Players |
|---|
| Fukuda |
| Unetixs Vascular Inc. |
| Collaborative Care Diagnostics LLC |
| CorVascular Diagnostics LLC |
| Koven Technology Inc. |
| D.E. Hokanson Inc. |
| enverdis GmbH |
| OMRON HEALTHCARE Co. Ltd |
| Viasonix |
| Others |
Value Network & Pricing Analysis
AI-augmented software layers are displacing hardware-centric revenue models, simultaneously compressing capital equipment margins and concentrating value capture among vendors with captive algorithm development pipelines.
Pricing Analysis
Cost-down pressure on portable ultrasound systems accelerates because outpatient clinics in the United States unbundle device procurement from long-term service agreements. Three-tier pricing structure across premium, standard, and economy levels separates AI-embedded platforms from basic Doppler units and refurbished legacy systems. Price differentiation traces to FDA 510(k) clearance tier and ISO 13485 certification status. Diagnostic centers show least price sensitivity due to reimbursement stability, while ambulatory surgical centers negotiate aggressively on hardware costs.
Supply Chain Analysis
China's NMPA domestic-content mandates for hospital procurement are reshaping sourcing patterns for foreign vascular screening manufacturers. Piezoelectric crystal fabrication concentrates in China, Japan, and South Korea, with high-frequency transducer assembly drawing from Yangtze River Delta component clusters. Single-source vulnerability sits with East Asian suppliers of specialized ceramic substrates. Distribution runs through integrated delivery networks in North America, specialized diagnostic distributors in Europe, and consumer health retail channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with algorithm development and transducer fabrication emerging as the decisive upstream levers for sustainable margin capture.
For Market Incumbents: Anticipate CT angiography substitution threats in tertiary emergency settings by deepening software subscription attach rates. Prioritize backward integration into piezoelectric crystal supply through joint ventures with East Asian component specialists. Lock in ISO 13485-aligned quality management to accelerate regulatory reciprocity across FDA, EU MDR, and PMDA jurisdictions. For New Entrants and Emerging Players: Telemedicine-enabled remote interpretation platforms offer the most penetrable entry vector for rural primary care practices lacking on-site sonography expertise. Target pharmacy retail networks in Japan and ambulatory surgical centers in Texas and Florida. Pursue cloud-native Doppler system licensing to bypass capital-intensive hardware fabrication. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking consumer health channel expansion. Long-term viability favors vendors with demonstrated algorithmic plaque characterization validation across multicenter datasets. Watch PMDA software-as-a-medical-device classification enforcement as the signal for AI-embedded device commercial timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | Accelerates replacement cycles in German and French vascular laboratories seeking upgraded certification portfolios. |
| AI Companion Development | Enables subscription revenue streams beyond hardware sales for algorithmic stenosis grading tools. |
| Hospital System Partnership | Secures preferred vendor status with integrated delivery networks unbundling procurement contracts. |
| Reimbursement Strategy | Aligns AI-augmented read coding with Medicare preventive service coverage for peripheral artery disease screening. |
| CE Marking Pathway | Opens European market access for shear wave elastography systems in arterial wall stiffness quantification. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR conformity assessment completion rates, and PMDA software-as-a-medical-device registration patterns anchored the trend analysis, supplemented by interviews with vascular laboratory directors, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and diagnostic imaging specialists. Secondary validation drew from FDA premarket notification databases, EUDAMED device registrations, CMS Medicare reimbursement coding updates, and hospital procurement records. Bottom-up installed base modeling and top-down expenditure flow analysis were triangulated.
Segment-weighting across product type, technology tier, end-user category, and application indication shaped the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to modality-specific expenditure patterns. Shear wave elastography adoption velocity in German tertiary centers and portable Doppler deployment rates in United States ambulatory surgical centers served as industry-specific forecast inputs.
The model holds under stable reimbursement coding for AI-augmented interpretations; deviation in FDA 510(k) review timeline variability or EU MDR post-market surveillance enforcement intensity would shift commercial launch assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wireless Breast Pump Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Kirschner Wires Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Oxygenator Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
Radiofrequency (RF) Ablation System Market