
 Global Dental Radiology and Dental Imaging Devices Market | 2026-2036
Global Dental Radiology and Dental Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Radiology and Dental Imaging Devices Market Foresight
Aftermarket service revenue is rewriting profitability expectations across the installed base of panoramic and CBCT units. Planmeca Oy leverages its Nordic manufacturing footprint to sustain premium positioning in 3D imaging hardware. Envista Holdings Corporation anchors North American distribution through dense dental dealer networks. DENTSPLY SIRONA competes on integrated workflow software that ties imaging to chairside restorative systems.
Dental radiology and dental imaging devices encompass ionizing and non-ionizing systems that capture anatomical structures at resolutions from 20 line pairs per millimeter in intraoral sensors to sub-millimeter isotropic voxels in cone beam computed tomography, primarily serving diagnosis, treatment planning, and procedural guidance in oral healthcare. Digital radiography now dominates new unit shipments as film-based systems retreat to price-sensitive replacement cycles in rural and developing markets. Cone beam computed tomography commands the highest per-unit margins among product types, while imaging software captures recurring licensing streams that expand lifetime customer value. Orthodontics and oral surgery applications drive the fastest technology refresh cycles due to procedural complexity and litigation exposure.
FDA 510(k) clearance pathways and CE marking under the EU MDR shape product development timelines and clinical evidence requirements for manufacturers seeking market access in the United States and European Union. Japan's PMDA and South Korea's MFDS impose additional localization testing that filters out smaller competitors lacking regulatory infrastructure. China's NMPA has accelerated review timelines for domestically manufactured CBCT units, redirecting competitive investment toward in-country production partnerships. Stakeholders must monitor how harmonization between FDA digital health guidance and EU AI Act risk classification affects imaging software embedded with automated diagnostic algorithms.
Market Dynamics
Aftermarket service revenue is rewriting profitability expectations across the installed base of panoramic and CBCT units. Planmeca Oy leverages its Nordic manufacturing footprint to sustain premium positioning in 3D imaging hardware. Envista Holdings Corporation anchors North American distribution through dense dental dealer networks. DENTSPLY SIRONA competes on integrated workflow software that ties imaging to chairside restorative systems.
Growth Catalysts
- Digital radiography adoption:Dental clinics in emerging economies are expanding digital radiography adoption as FDA and CE marking requirements tighten for diagnostic accuracy.
- Cone beam computed tomography demand:China, India, and Brazil concentrate demand growth for cone beam computed tomography systems.
- EU MDR harmonization:CE marking under the EU MDR shapes product development timelines and clinical evidence requirements for manufacturers seeking market access in the European Union.
Market Restraints
- Regulatory infrastructure costs:Japan's PMDA and South Korea's MFDS impose additional localization testing that filters out smaller competitors lacking regulatory infrastructure.
- Input concentration in sensors:CMOS sensor fabrication concentrates among East Asian foundries, exposing manufacturers to geopolitical supply disruption.
- Film-based system persistence:Film-based systems retreat to price-sensitive replacement cycles in rural and developing markets, fragmenting service standardization.
Strategic Opportunities
- Domestic production partnerships:China's NMPA has accelerated review timelines for domestically manufactured CBCT units, redirecting competitive investment toward in-country production partnerships.
- AI-embedded imaging software:Harmonization between FDA digital health guidance and EU AI Act risk classification affects imaging software embedded with automated diagnostic algorithms.
- Orthodontics refresh cycles:Orthodontics and oral surgery applications drive the fastest technology refresh cycles due to procedural complexity and litigation exposure.
Industry Challenges
- Regulatory evidence generation:FDA 510(k) clearance pathways require clinical evidence that extends product development timelines for novel reconstruction algorithms.
- Legacy system integration:Imaging software must maintain backward compatibility with decade-old panoramic units while delivering cloud-native analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Radiology and Dental Imaging Devices Market |
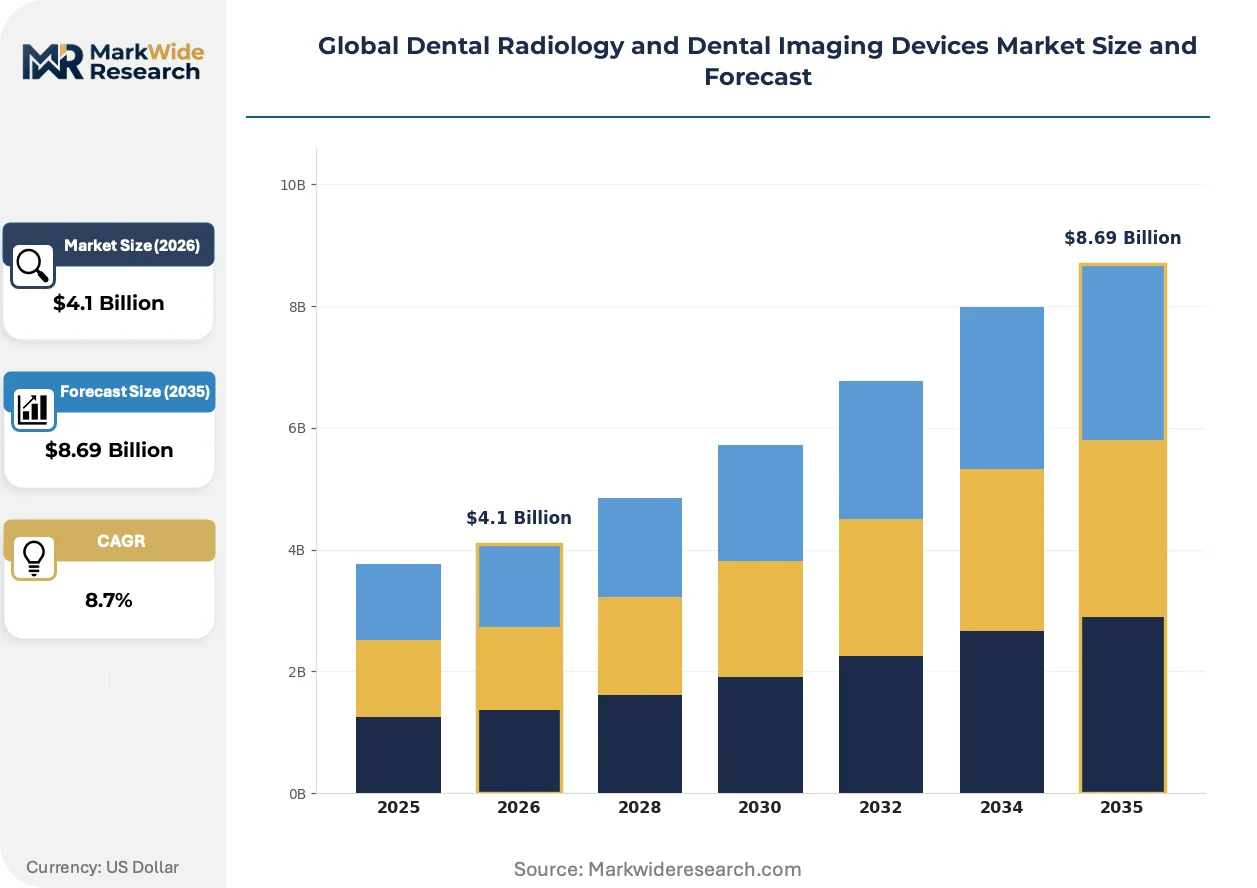
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral X-Ray, Panoramic X-Ray, Cone Beam Computed Tomography, Digital Sensors, Imaging Software Technology: Film-Based Radiography, Digital Radiography, Computed Tomography, 3D Imaging, Cephalometric Imaging Application: Orthodontics, Endodontics, Periodontology, Oral Surgery, Prosthodontics End User: Dental Clinics, Diagnostic Centers, Academic Institutions, Research Laboratories |
| Companies Covered | Planmeca Oy, ACTEON Group, Envista Holdings Corporation, 3Shape A/S, DÜRR DENTAL, DENTSPLY SIRONA, Carestream Dental LLC, Genoray Co., Ltd., VATECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Radiology and Dental Imaging Devices Market Shifts & Advancements
Digital radiography now dominates new unit shipments as film-based systems retreat to price-sensitive replacement cycles in rural and developing markets. Cone beam computed tomography commands the highest per-unit margins among product types, while imaging software captures recurring licensing streams that expand lifetime customer value.
Photon-counting detectors are migrating from experimental physics installations into commercial dental CBCT architectures. Oral surgery centers in Germany and Japan are piloting these systems for sub-micron trabecular bone assessment. The technology is migrating from research-grade synchrotron facilities to compact clinical platforms, compressing the resolution gap between medical CT and dental specialty imaging.
The EU AI Act risk classification framework is reshaping how manufacturers validate diagnostic algorithms embedded in panoramic analysis software. High-risk classification for automated pathology detection now mandates notified body involvement in conformity assessment. European orthodontic chains are restructuring procurement specifications to prioritize CE-marked AI modules over uncertified cloud analytics.
Subscription licensing for reconstruction software is displacing perpetual seat licenses among multi-location dental service organizations. United States-based DSOs now negotiate enterprise agreements that bundle hardware depreciation with software access fees. This model concentrates vendor switching costs and locks in aftermarket service revenue across five-to-seven year fleet replacement horizons.
Global Dental Radiology and Dental Imaging Devices Market Segmentation
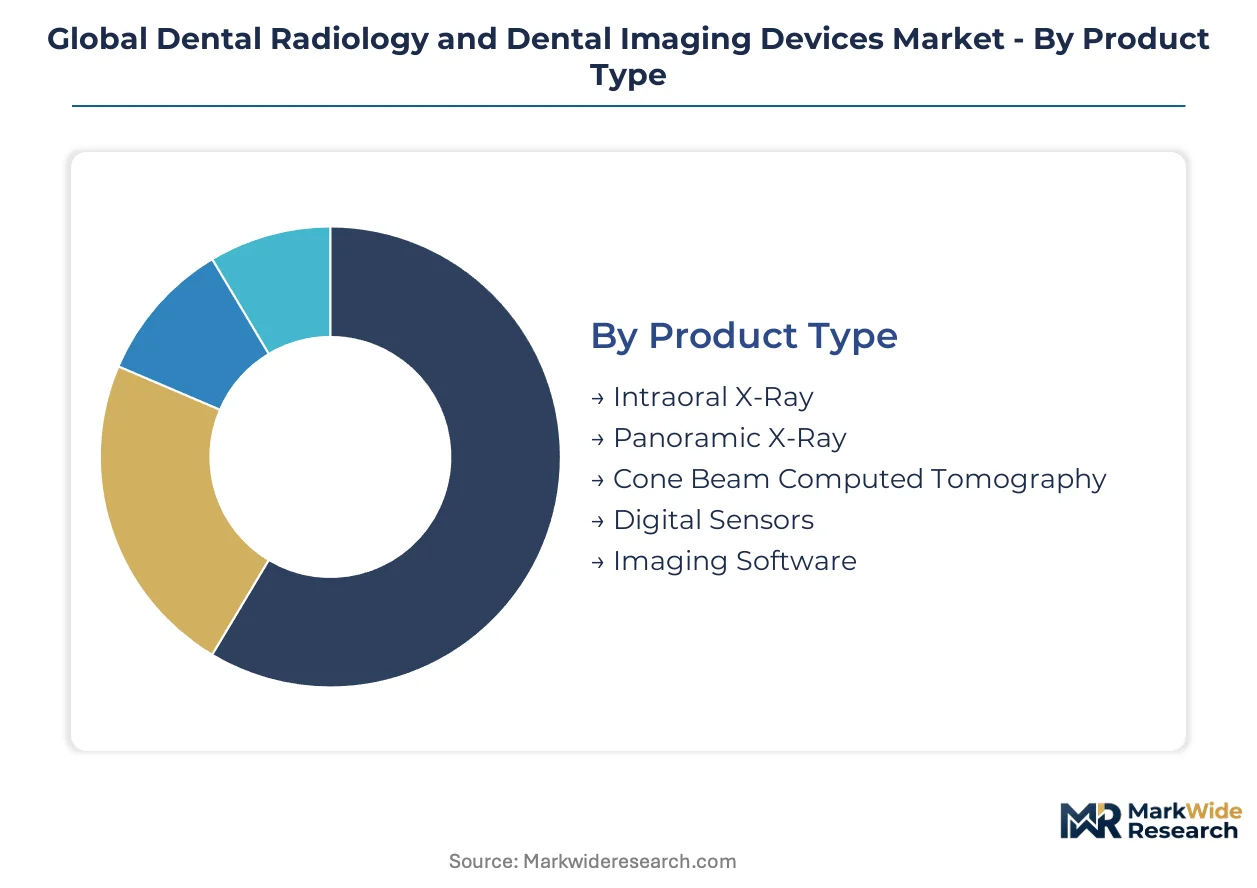
Segmentation in dental imaging determines service contract structures, software licensing models, and hardware refresh cycles. Manufacturers calibrate aftermarket revenue streams differently across product tiers and end-user categories.
Product Type:
After-sales-service intensity varies dramatically across hardware categories, with 3D systems commanding multi-year service agreements and software segments relying on recurring license renewals.
- Cone Beam Computed Tomography:Sub-millimeter isotropic voxel resolution enables precise implant planning and airway analysis. Oral surgery centers in Germany and Japan drive replacement demand as litigation exposure accelerates technology refresh. Highest per-unit margins and longest service contract durations anchor vendor profitability.
- Digital Sensors:CMOS and photodiode arrays capture 20 line pairs per millimeter for caries detection. Dental clinics across China and India expand sensor deployment as FDA and CE marking requirements tighten diagnostic accuracy standards. Replacement cycles run shorter than panoramic systems due to physical wear and cable fatigue.
- Intraoral X-Ray:Wall-mounted and handheld generators emit controlled ionizing radiation for single-tooth imaging.
- Panoramic X-Ray:Rotating tube-detector assemblies capture full dentition in single exposures.
- Imaging Software:Reconstruction algorithms and diagnostic viewers generate recurring licensing revenue streams.
By volume, Digital Sensors leads. By growth pace, Cone Beam Computed Tomography is ahead.
Technology:
Cost tier stratification separates capital-intensive 3D platforms from lower-cost digital retrofits, with film-based systems persisting only in price-sensitive replacement markets.
- Digital Radiography:Direct and indirect capture systems eliminate chemical processing. Brazil and India concentrate new unit shipments as clinics modernize from analog workflows. FDA 510(k) clearance pathways shape product development timelines for sensor manufacturers.
- 3D Imaging:Volumetric reconstruction enables implant navigation and orthodontic treatment planning. Academic institutions in the United States and South Korea pilot photon-counting detector architectures for sub-micron bone assessment. EU MDR harmonization extends clinical evidence requirements for novel reconstruction algorithms.
- Film-Based Radiography:Silver halide emulsion systems persist in rural clinics with limited capital budgets.
- Computed Tomography:Medical-grade systems adapted for maxillofacial applications in hospital settings.
- Cephalometric Imaging:Lateral skull analysis supports orthodontic diagnosis and treatment monitoring.
By installed base, Digital Radiography dominates. By margin expansion, 3D Imaging commands premium positioning.
Application:
Procedure complexity and malpractice exposure create divergent technology refresh rhythms across dental specialties.
- Oral Surgery:Implant placement and orthognathic procedures demand sub-millimeter spatial accuracy. Centers in Japan and Germany deploy photon-counting CBCT for trabecular bone assessment. Litigation exposure drives fastest technology refresh cycles among all applications.
- Orthodontics:Cephalometric analysis and 3D treatment planning require consistent imaging protocols. Clear aligner therapy expansion in the United States and China concentrates demand for integrated workflow software. EU AI Act risk classification now mandates notified body involvement for automated pathology detection modules.
- Endodontics:Periapical imaging guides root canal therapy and post-treatment evaluation.
- Periodontology:Bone level assessment supports disease staging and surgical intervention planning.
- Prosthodontics:Crown and bridge workflows integrate intraoral scanning with radiographic verification.
By procedure volume, Endodontics leads. By technology investment intensity, Oral Surgery is expanding most quickly.
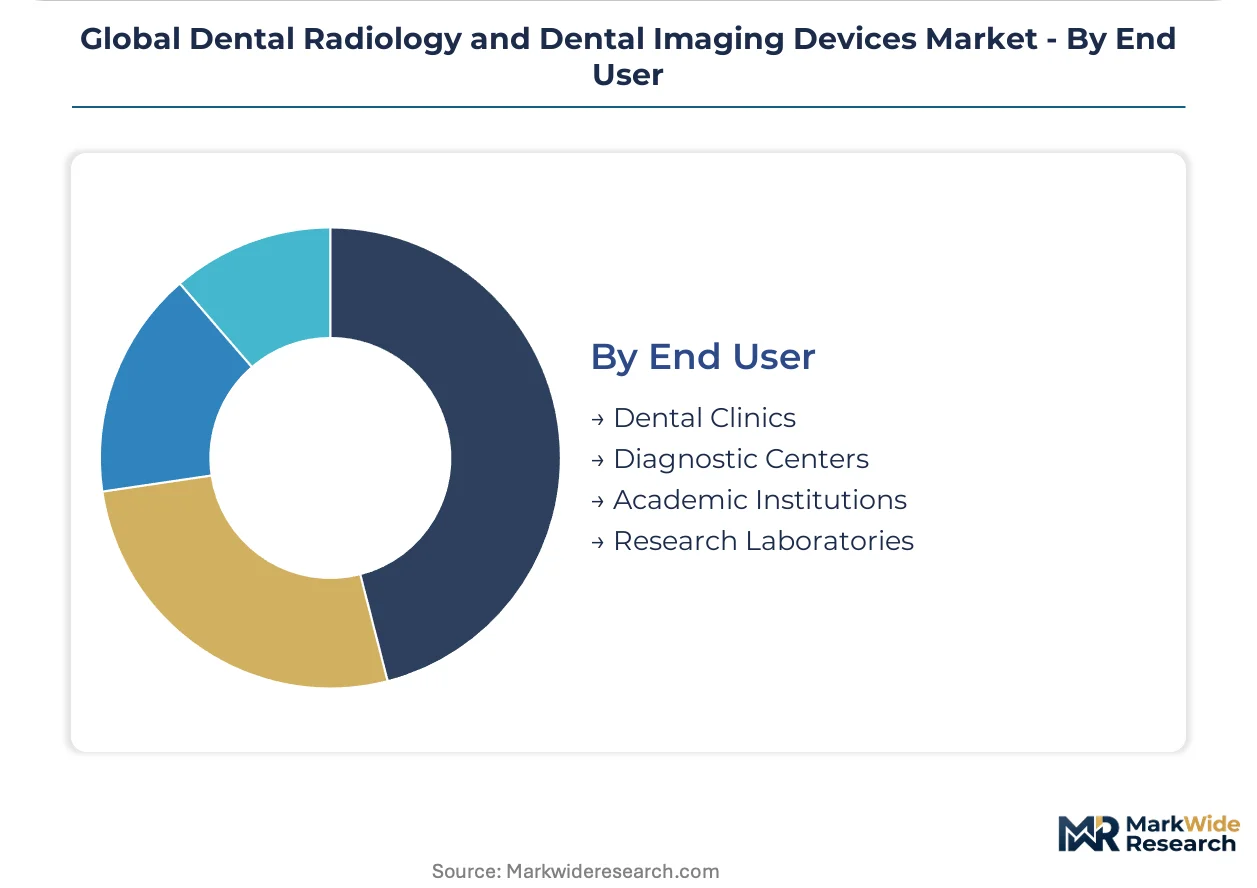
End User:
Customer type dictates procurement scale, with multi-location dental service organizations negotiating enterprise agreements that bundle hardware and software access.
- Dental Clinics:Solo practices and group practices generate the majority of unit demand. China's NMPA accelerated review timelines redirect competitive investment toward domestic production partnerships. Subscription licensing for reconstruction software displaces perpetual seat licenses among United States-based DSOs.
- Academic Institutions:Teaching hospitals and dental schools pilot experimental detector technologies. Research collaborations in South Korea and Japan advance photon-counting architectures from synchrotron facilities to clinical platforms. PMDA and MFDS localization testing filters out smaller competitors lacking regulatory infrastructure.
- Diagnostic Centers:Independent imaging facilities serve referring dentists without in-house radiology.
- Research Laboratories:Preclinical and materials science applications drive detector innovation.
By unit shipments, Dental Clinics leads. By technology access, Academic Institutions gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Brazilian and Indian clinics prioritize cost-efficient digital sensors, while German and Japanese oral surgery centers absorb premium pricing for photon-counting CBCT systems without volume elasticity.
United States
Dental service organizations drive enterprise procurement of subscription-licensed imaging software. FDA 510(k) clearance pathways extend development timelines for novel reconstruction algorithms. Greater Boston and Pacific Northwest academic clusters pilot photon-counting detector architectures for sub-micron bone assessment.
Germany
Oral surgery centers absorb premium pricing for litigation-risk mitigation through high-resolution imaging. EU MDR harmonization mandates notified body involvement for AI-embedded diagnostic software. Bavaria's industrial corridor concentrates manufacturing of precision 3D imaging hardware.
China
Domestic clinics expand digital radiography deployment as diagnostic accuracy standards tighten. NMPA accelerated review timelines redirect competitive investment toward in-country production partnerships. Yangtze River Delta manufacturing clusters scale CMOS sensor fabrication for regional supply security.
Japan
Academic institutions advance photon-counting migration from synchrotron facilities to clinical platforms. PMDA localization testing filters out smaller competitors lacking regulatory infrastructure. Kansai region research hospitals collaborate with detector manufacturers on sub-micron trabecular assessment protocols.
Brazil
Price-sensitive clinics in secondary cities sustain film-based replacement cycles alongside digital adoption. ANVISA registration requirements shape import timelines for European and Asian manufacturers. São Paulo state dental chains negotiate volume discounts on panoramic systems for multi-location deployment.
Global Dental Radiology and Dental Imaging Devices Market Competitive Landscape
Capability concentration sits with Nordic and German precision manufacturers; scale advantage sits with North American distribution-heavy conglomerates. The vendor base stratifies across three tiers: integrated workflow software providers, hardware specialists with captive manufacturing, and regional distributors with service-intensive business models. Dominant competitive moves include backward integration into sensor fabrication and enterprise licensing deals that lock dental service organizations into five-to-seven year fleet replacement cycles.
Among Nordic manufacturers, Planmeca Oy occupies a position exemplifying premium-tier 3D imaging hardware. Envista Holdings Corporation represents the scale-driven distribution archetype through dense North American dealer networks. DENTSPLY SIRONA anchors the integrated workflow tier, tying imaging systems to chairside restorative platforms.
| Leading Market Players |
|---|
| Planmeca Oy |
| ACTEON Group |
| Envista Holdings Corporation |
| 3Shape A/S |
| DÜRR DENTAL |
| DENTSPLY SIRONA |
| Carestream Dental LLC |
| Genoray Co., Ltd. |
| VATECH |
| Others |
Supply & Pricing Matrix
CMOS sensor fabrication concentrates among East Asian foundries, channeling margin capture toward manufacturers with captive detector supply or long-term foundry partnerships. This upstream concentration forces pricing discipline downstream, where vendors differentiate through after-sales service bundling rather than hardware commoditization.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime customer value in CBCT and panoramic systems. Pricing stratifies across premium, standard, and economy tiers based on detector resolution grade and FDA 510(k) clearance tier. Cost compression in economy-tier digital sensors intensifies because CMOS foundry capacity expansion outpaces demand growth. Solo dental clinics in Brazil and India exhibit highest price sensitivity, while oral surgery centers in Germany absorb premium positioning without volume elasticity.
Supply Chain Analysis
Contract manufacturing for CMOS photodiodes and scintillator arrays concentrates with Taiwanese and South Korean foundries, with Japanese suppliers holding precision detector assembly capacity. Raw material dependencies include rare-earth phosphors, high-purity silicon wafers, and lead-shielding components. Single-source vulnerability in advanced CMOS fabrication exposes manufacturers to geopolitical supply disruption. Distribution runs through dense North American dealer networks and direct sales forces in European orthodontic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photon-counting detector commercialization and EU AI Act risk classification for diagnostic algorithms constitute dual inflection points reshaping competitive positioning. Stakeholders must calibrate capital deployment and capability investment against these structural shifts.
For Market Incumbents: Pre-empt emerging photon-counting specialists by securing exclusive foundry allocation for next-generation detector architectures. Backward integration into CMOS sensor design protects margin pools threatened by East Asian supply concentration. Lock dental service organizations into five-to-seven year fleet replacement cycles through bundled software-hardware subscription terms. For New Entrants and Emerging Players: Secondary cities in Brazil and rural India present underpenetrated demand for cost-efficient digital radiography retrofits. Film-based system persistence in price-sensitive replacement markets creates white-space opportunity for low-cost sensor manufacturers. Target group dental practices with direct-to-clinic distribution bypassing traditional dealer markups. For Investors and Strategic Acquirers: Capital is best deployed toward integrated workflow software providers with recurring licensing revenue and AI-embedded diagnostic modules. Long-term viability centers on vendors bridging imaging hardware to chairside restorative platforms. Watch FDA digital health guidance harmonization with EU AI Act enforcement as signal for regulatory compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Migration | Sub-micron bone assessment capability commands premium pricing in German and Japanese oral surgery centers. |
| EU AI Act Compliance Pathway | Notified body involvement for high-risk diagnostic algorithms filters out uncertified software competitors. |
| Domestic Production Partnerships | NMPA accelerated review timelines redirect investment toward China-based CBCT manufacturing joint ventures. |
| Subscription Licensing Transition | Enterprise agreements with United States DSOs concentrate vendor switching costs across fleet replacement cycles. |
| Foundry Capacity Securement | Long-term CMOS fabrication contracts insulate against East Asian supply disruption and cost volatility. |
Research Methodology
A standing panel of oral surgeons, orthodontic practice administrators, biomedical equipment procurement managers, and dental dealer network executives provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) clearance databases, CE marking notifications under EU MDR, and NMPA registration filings. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing.
Scenario-bracketing framed demand projections across the analysis window, incorporating regulatory timeline uncertainty and technology substitution curves. Segmentation dimensions modeled include product type, technology tier, application specialty, and end-user category. CAGRs derived from logistic diffusion curves for digital radiography adoption and replacement cycle analysis for 3D imaging systems. Forecast inputs incorporated CMOS sensor cost trajectories and dental clinic density projections by metropolitan statistical area.
Practitioners should monitor NMPA review timeline changes, EU AI Act enforcement precedents, and photon-counting detector clinical trial readouts for early signals of forecast revision. Quarterly review of foundry capacity announcements and dental service organization procurement RFP patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Italy Computed Tomography Market
Medical Imaging
India Mammography Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
South America MRI Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Global Micro-Ultrasound Systems Market