
 Whole-Body Imaging Market | 2026-2036
Whole-Body Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Whole-Body Imaging Market Analytics
Oncology is decoupling from cardiology as the dominant application driver for whole-body imaging procurement. Siemens Healthineers leverages its dual-source CT architecture to dominate high-throughput cancer staging workflows in European university hospitals. GE Healthcare anchors its position through deep backward integration into helium-free MRI magnet production, insulating clients from supply volatility. Canon Medical Systems differentiates via detector manufacturing scale that sustains pricing pressure across Asia-Pacific diagnostic imaging centers.
Whole-body imaging denotes the simultaneous or rapid-sequence acquisition of anatomical data across all major body regions using ionizing or non-ionizing energy, with spatial resolution thresholds typically below one millimeter for CT and sub-millimeter isotropic voxels for 3T MRI. These systems enable comprehensive disease staging, trauma assessment, and whole-body screening without repeated patient repositioning. MRI systems command the deepest margin pools due to superconducting magnet maintenance contracts and site preparation complexity, while PET scanners represent the fastest-expanding product category as radiopharmaceutical supply chains mature. Digital X-ray technology occupies a mature cost-optimized tier, though 3D imaging capabilities are displacing conventional tomography in orthopedic trauma protocols.
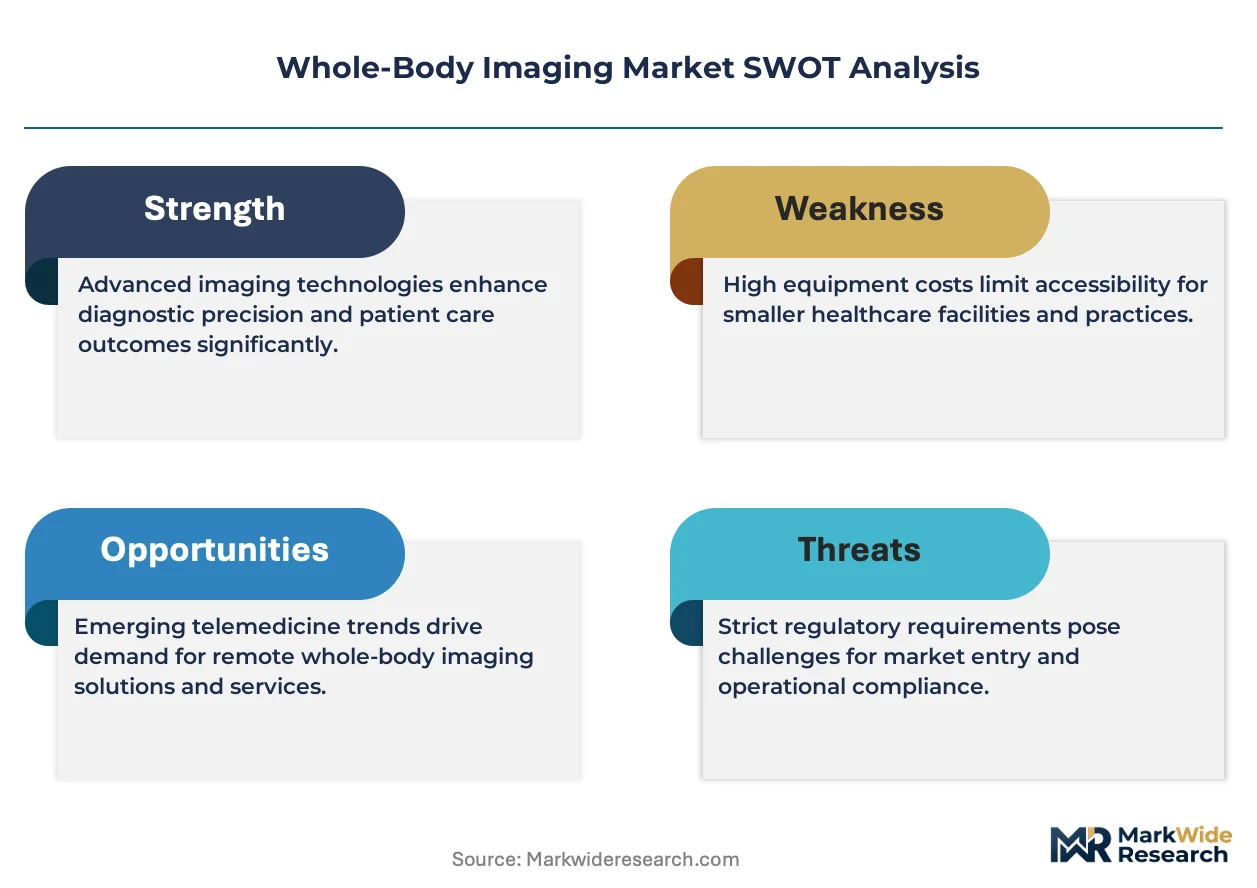
FDA premarket notification requirements under 21 CFR 892 shape hardware-software integration timelines for AI-enabled reconstruction modules, while EU MDR technical documentation demands extend certification cycles for CE-marked whole-body systems. The EPA oversees responsible disposal pathways for MRI cryogen systems containing helium and gadolinium wastewater from contrast-enhanced protocols. Stakeholders must monitor radiopharmaceutical manufacturing capacity constraints and reimbursement parity between anatomical and functional imaging codes when allocating capital across modality portfolios.
Market Dynamics
The Whole-Body Imaging Market pivots on radiopharmaceutical supply maturation compressing PET scanner deployment cycles while AI reconstruction algorithms shorten FDA clearance timelines from 18-month averages toward 12-month windows.
Growth Catalysts
- AI-Assisted Reconstruction:FDA 21 CFR 892 premarket notification pathways for algorithmic modules are accelerating hardware-software integration timelines. Academic medical centers in the United States are expanding metastatic screening protocols.
- Helium-Free MRI Magnet Production:Backward integration into superconducting magnet manufacturing is insulating hospital capital budgets from cryogen supply volatility. European university hospitals are prioritizing integrated diagnostic platforms.
- Radiopharmaceutical Supply Chain Maturation:Cyclotron network density improvements are enabling PET scanner category expansion. Asia-Pacific diagnostic imaging centers are scaling detector manufacturing partnerships.
Market Restraints
- Superconducting Magnet Maintenance Contracts:Site preparation complexity and cryogen system operating costs constrain margin pools for MRI system vendors. Hospital capital allocation favors multi-modality platforms over single-purpose installations.
- Gadolinium Wastewater Disposal:EPA oversight of contrast-enhanced protocol byproduct handling adds compliance overhead. Imaging centers face escalating environmental liability exposure.
- EU MDR Technical Documentation:Extended certification cycles for CE-marked whole-body systems delay European revenue recognition. Manufacturers must maintain parallel regulatory track files.
Strategic Opportunities
- India Diagnostic Imaging Infrastructure:CDSCO regulatory harmonization with international standards is opening procurement pathways for imported systems. PLI scheme incentives favor domestic assembly partnerships.
- 3D Digital X-Ray Orthopedic Trauma:Conventional tomography displacement in emergency departments creates upgrade cycles. Volume CT capabilities command premium positioning against legacy radiography.
- Outcome-Based Equipment Leasing:Per-scan pricing models are penetrating independent imaging center channels. United States hospital systems are unbundling maintenance from capital acquisition.
Industry Challenges
- AI Algorithm Validation Workflows:FDA software-as-medical-device documentation requirements strain regulatory affairs staffing. Manufacturers must demonstrate clinical equivalence across patient demographic variations.
- Multi-Modality Integration Complexity:PET-MRI hybrid system installation demands specialized shielding engineering. Site readiness timelines extend 8-14 months from contract signature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whole-Body Imaging Market |
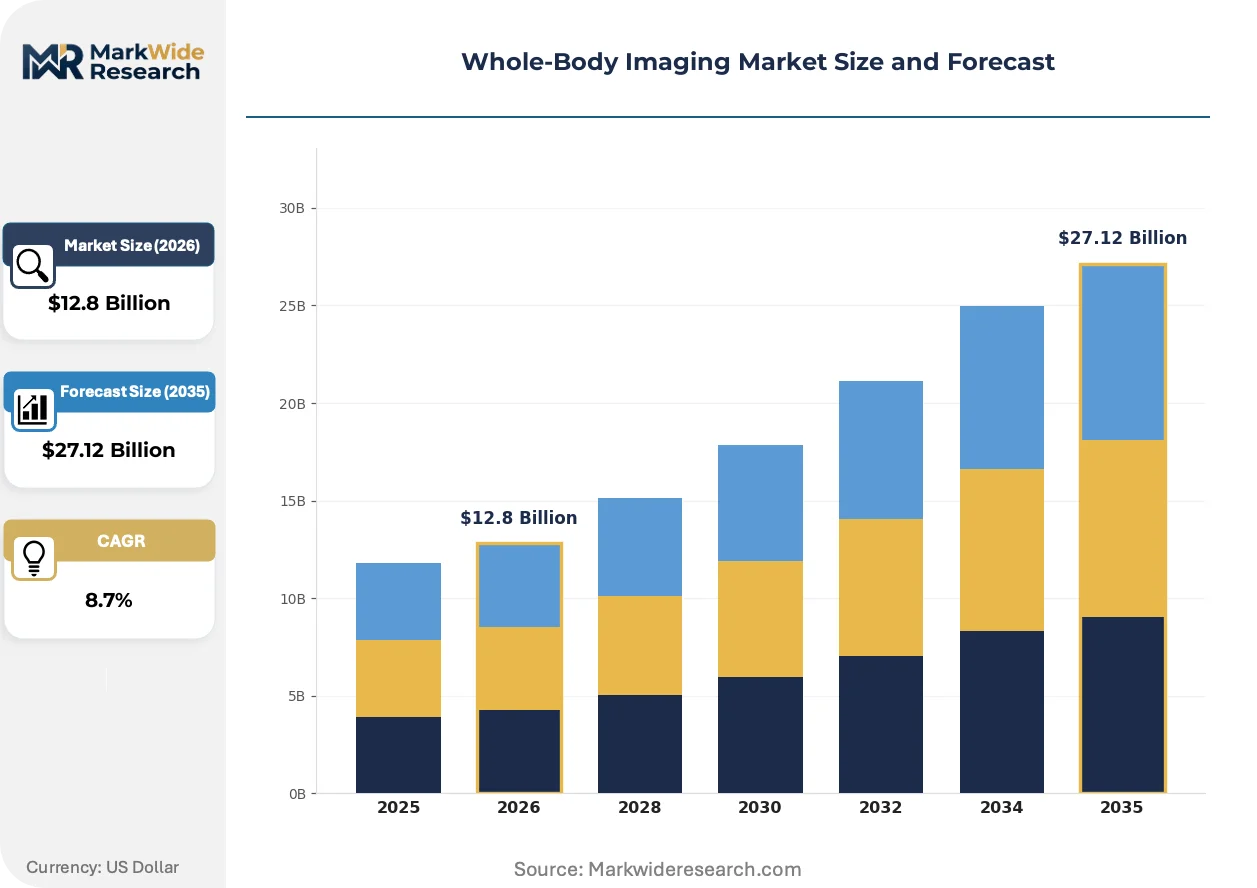
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Systems, PET Scanners, Ultrasound Devices Application: Oncology, Cardiology, Neurology, Orthopedics End User: Hospitals, Diagnostic Imaging Centers, Research Institutes, Outpatient Facilities Technology: 3D Imaging, Digital X-ray, Nuclear Imaging, Magnetic Resonance |
| Companies Covered | Canon Medical Systems Corporation, Shimadzu Corporation, GE Healthcare, Mediso Ltd., United Imaging Healthcare, Siemens Healthineers, Fujifilm Holdings Corporation, Samsung Electronics, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whole-Body Imaging Market Evolving Landscape
Computational reconstruction architectures and procurement model fragmentation are compressing technology refresh cycles while regulatory frameworks adapt to software-centric diagnostic systems.
Deep learning-based image reconstruction is automating noise reduction protocols in CT protocols, enabling diagnostic-quality scans at 40% lower radiation dose. Academic medical centers in Germany and Japan are piloting these systems for pediatric oncology staging. The technology is automating technologist workflow standardization across high-throughput cancer screening programs.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence portfolios for software-enabled whole-body systems. Manufacturers must submit post-market surveillance data extending five years post-clearance. PET scanner vendors with existing CE marks face the steepest re-certification burden ahead of 2027 renewal deadlines.
Consolidated purchasing coalitions among United States health systems are unbundling service contracts from equipment financing. Independent imaging centers in Texas and Florida are migrating toward per-procedure leasing arrangements. Radiology group purchasing organizations are extracting 12-18% pricing concessions through multi-year volume commitments.
Whole-Body Imaging Market Segmentation
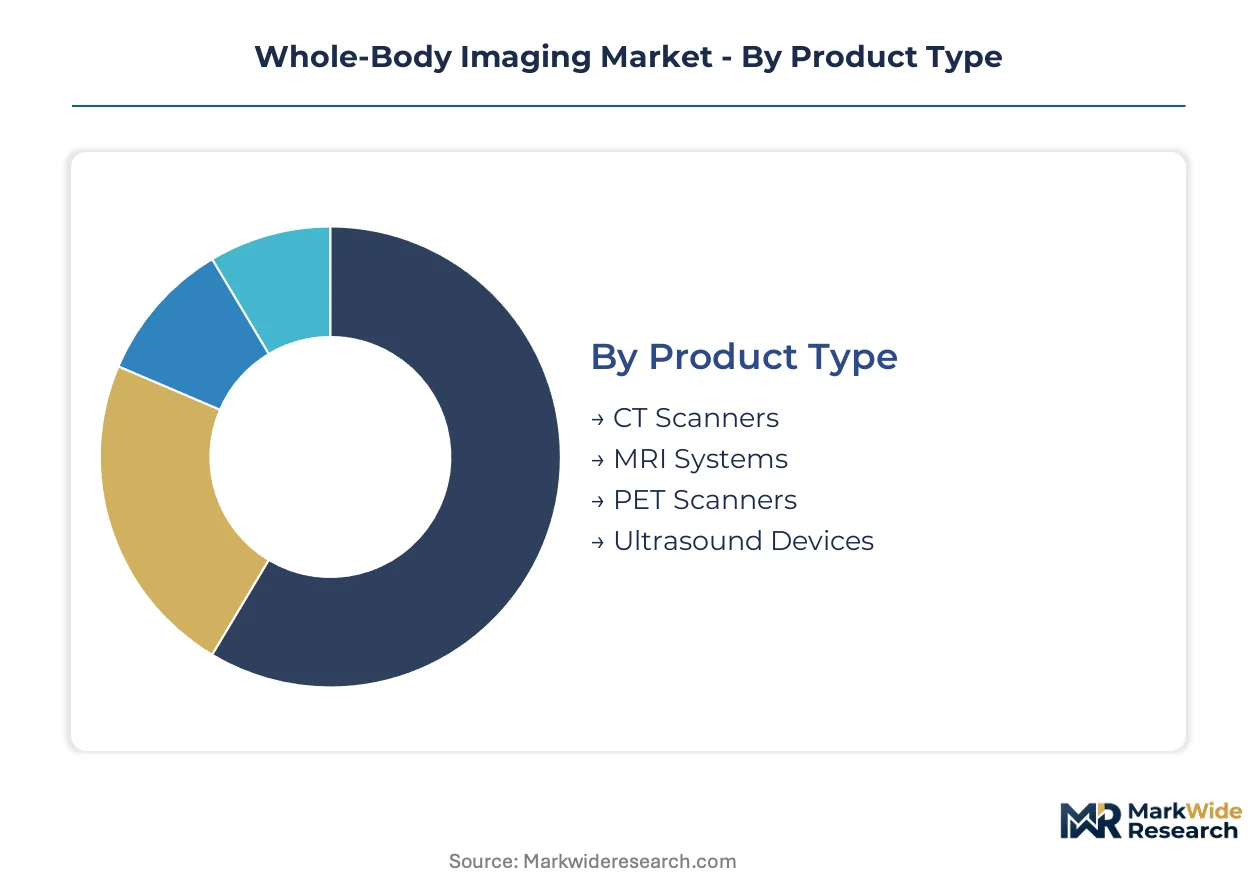
Whole-body imaging procurement patterns diverge sharply across product architectures, clinical applications, and facility types. Certification requirements under FDA 21 CFR 892 and EU MDR create asymmetric compliance burdens that reshape competitive positioning within each segment cluster.
Product Type:
FDA premarket notification pathways vary substantially across ionizing versus non-ionizing modalities, with PET scanners facing additional radiopharmaceutical manufacturing facility inspections.
- CT Scanners:Dual-source architectures enable sub-millisecond temporal resolution for cardiac and trauma protocols. Siemens Healthineers anchors high-throughput cancer staging workflows in German university hospitals where dual-energy spectral imaging commands premium positioning.
- MRI Systems:Superconducting 3T platforms with active shielding dominate neuro-oncology and musculoskeletal applications. Helium-free magnet production is insulating hospital capital budgets from cryogen supply volatility across United States academic medical centers.
- PET Scanners:Time-of-flight detector arrays paired with cyclotron-produced radiotracers.
- Ultrasound Devices:Portable whole-body platforms with shear-wave elastography for liver and thyroid assessment.
MRI Systems sit at the top of the volume ranking, with PET Scanners climbing the fastest as cyclotron network density improves.
Application:
Reimbursement parity between anatomical and functional imaging codes determines capital allocation intensity across clinical service lines.
- Oncology:Whole-body diffusion-weighted MRI and FDG-PET/CT protocols enable single-session metastatic staging. Academic medical centers in the United States are expanding screening programs for high-risk patient cohorts.
- Cardiology:Coronary CT angiography with fractional flow reserve computation displaces invasive catheterization in intermediate-risk patients. European preventive cardiology programs favor calcium scoring for asymptomatic screening.
- Neurology:Quantitative susceptibility mapping and arterial spin labeling for neurodegenerative disease tracking.
- Orthopedics:Weight-bearing CT and metal-artifact reduction sequences for arthroplasty surveillance.
Oncology leads absolute procedure volume, though Cardiology applications are expanding most quickly through preventive screening program adoption.
End User:
Site preparation complexity and service contract bundling create distinct procurement economics across facility ownership models.
- Hospitals:Integrated diagnostic platforms with multi-modality suites and 24/7 emergency coverage requirements. United States health systems are consolidating purchasing coalitions to extract 12-18% pricing concessions through multi-year volume commitments.
- Diagnostic Imaging Centers:Independent operators in Texas and Florida are migrating toward per-procedure leasing arrangements that unbundle maintenance from capital acquisition.
- Research Institutes:Preclinical imaging cores with 7T and 9.4T small-bore systems for translational studies.
- Outpatient Facilities:Limited-service sites focused on extremity MRI and low-dose CT lung screening.
Hospitals retain dominant installed base share, with Diagnostic Imaging Centers gaining share fastest through outcome-based equipment leasing penetration.
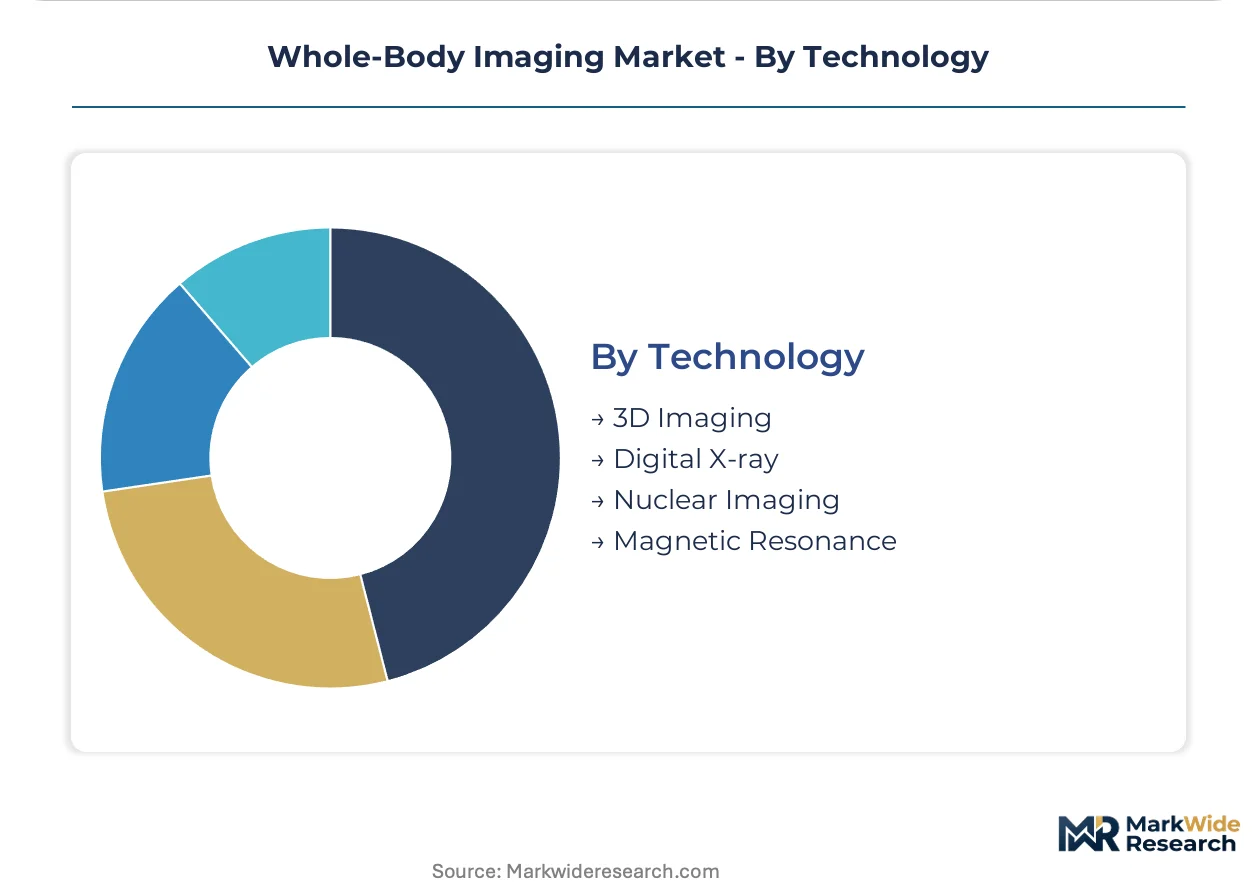
Technology:
AI-enabled reconstruction algorithms are compressing hardware-software integration timelines while reshaping competitive differentiation across acquisition modalities.
- 3D Imaging:Cone-beam CT and digital tomosynthesis protocols automating technologist workflow standardization. Volume CT capabilities command premium positioning against legacy radiography in emergency departments.
- Digital X-ray:Flat-panel detectors with wireless data transmission for orthopedic trauma and chest imaging. Asia-Pacific diagnostic imaging centers are scaling detector manufacturing partnerships to sustain pricing pressure.
- Nuclear Imaging:SPECT-CT hybrids with cadmium-zinc-telluride semiconductor detectors.
- Magnetic Resonance:Compressed sensing and parallel imaging acceleration for motion-robust abdominal protocols.
Magnetic Resonance holds the steepest expansion trajectory among technology categories, with 3D Imaging applications in orthopedic trauma creating immediate upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production investment toward jurisdictions where FDA 21 CFR 892 premarket pathways and EU MDR certification burdens create asymmetric compliance costs. Manufacturers are optimizing facility placement across the United States, Germany, China, Japan, and India based on cyclotron network density and helium supply chain resilience.
United States
Academic medical centers in Boston and Houston are expanding metastatic screening protocols using AI-assisted reconstruction modules. FDA premarket notification pathways under 21 CFR 892 are accelerating hardware-software integration timelines for domestic vendors. The Texas Medical Center cluster anchors PET scanner deployment as cyclotron network density improves across the Gulf Coast.
Germany
University hospitals in Munich and Heidelberg prioritize dual-source CT architectures for high-throughput cancer staging workflows. EU MDR technical documentation requirements are extending certification cycles for CE-marked systems ahead of 2027 renewal deadlines. The Baden-Württemberg industrial corridor concentrates superconducting magnet engineering talent for helium-free MRI development.
China
Domestic imaging center chains in Shanghai and Beijing are scaling detector manufacturing partnerships to sustain pricing pressure. NMPA regulatory harmonization with international standards is opening procurement pathways for imported systems. The Yangtze River Delta cluster anchors volume CT production for orthopedic trauma applications.
Japan
Preventive cardiology programs in Tokyo and Osaka favor coronary CT angiography with fractional flow reserve computation. PMDA software-as-medical-device documentation requirements are shaping AI algorithm validation workflows for reconstruction modules. The Nagoya medical device corridor concentrates PET-MRI hybrid system engineering capabilities.
India
Diagnostic imaging infrastructure in Mumbai and Bengaluru is expanding through PLI scheme incentives favoring domestic assembly partnerships. CDSCO regulatory harmonization is streamlining import pathways for whole-body systems. The Maharashtra-Gujarat industrial belt anchors flat-panel detector manufacturing for cost-optimized digital X-ray deployment.
Whole-Body Imaging Market Competitive Landscape
Backward integration into superconducting magnet manufacturing dominates the current landscape, with vendors insulating hospital capital budgets from cryogen supply volatility. The vendor base clusters around three strategic archetypes: diversified conglomerates with medical device divisions, pure-play imaging specialists, and emerging Asian challengers with detector manufacturing scale. Competitive intensity concentrates on M&A activity targeting AI reconstruction algorithm portfolios and geographic expansion into underpenetrated diagnostic imaging markets.
Among diversified conglomerates with medical device divisions, Siemens Healthineers and GE Healthcare exemplify the integrated diagnostic platform archetype through captive supply of critical components. Canon Medical Systems occupies a position within the detector manufacturing scale tier, leveraging production volume to sustain pricing pressure across Asia-Pacific diagnostic imaging centers. United Imaging Healthcare represents the emerging Asian challenger archetype, with domestic market scale enabling rapid protocol iteration for cost-sensitive procurement channels.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| GE Healthcare |
| Mediso Ltd. |
| United Imaging Healthcare |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Samsung Electronics |
| Philips Healthcare |
| Others |
Value Network & Pricing Analysis
Superconducting magnet engineering talent concentration in the Baden-Württemberg industrial corridor feeds labor-cost differentials that widen pricing-tier spreads between helium-free MRI platforms and conventional cryogen-dependent systems. Hospital capital allocation across United States academic medical centers and Asia-Pacific diagnostic imaging centers stratifies procurement economics around site preparation complexity and maintenance contract bundling.
Pricing Analysis
Distributor margins on AI-enabled reconstruction modules compress as direct-to-hospital contracting expands among consolidated United States health systems. Three-tier pricing structure across premium, standard, and economy levels separates dual-source CT architectures with spectral imaging from single-source configurations and refurbished legacy systems. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service bundling intensity. Cost compression in the standard tier is intensifying because detector manufacturing partnerships in Asia-Pacific are scaling production volume. Independent imaging centers in Texas and Florida exhibit highest price sensitivity, while German university hospitals prioritize performance specifications over procurement cost.
Supply Chain Analysis
Freight costs for superconducting magnet cryogen systems escalate with helium supply chain fragmentation, pressuring landed cost structures for MRI platform vendors. Manufacturing concentration in Germany, Japan, and the United States anchors production of high-field MRI systems and dual-source CT architectures. Raw material dependencies span niobium-titanium superconducting wire, liquid helium reserves, and cadmium-zinc-telluride semiconductor substrates for PET detector arrays. Single-source vulnerability in radiopharmaceutical precursor supply creates bottleneck exposure for cyclotron-dependent PET scanner deployment. Distribution runs through authorized dealer networks for hospital capital equipment, with direct OEM relationships penetrating consolidated health system purchasing coalitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA 21 CFR 892 premarket notification efficiency in the United States contrasts against EU MDR extended certification cycles, creating divergent capital deployment timelines for manufacturers optimizing regulatory pathway sequencing.
For Market Incumbents: Cement dominance in high-throughput cancer staging workflows by deepening backward integration into helium-free magnet production, insulating hospital clients from cryogen supply volatility. Capture incremental share through AI reconstruction algorithm portfolios that accelerate FDA clearance timelines, countering emerging Asian challengers with detector manufacturing scale. Prioritize multi-modality platform bundling to defend margin pools against unbundled per-scan leasing arrangements penetrating independent imaging center channels. For New Entrants and Emerging Players: Capture procurement pathways opened by CDSCO regulatory harmonization in India, where PLI scheme incentives favor domestic assembly partnerships for cost-optimized digital X-ray and portable ultrasound deployment. Target diagnostic imaging infrastructure expansion in Maharashtra and Gujarat industrial corridors, leveraging flat-panel detector manufacturing partnerships to sustain pricing pressure. Lead with outcome-based equipment leasing models that unbundle maintenance from capital acquisition, matching independent operator preference in Texas and Florida markets. For Investors and Strategic Acquirers: Diversified conglomerates with medical device divisions are the most active acquirers in this space, consolidating AI reconstruction algorithm specialists to compress hardware-software integration timelines. Long-term viability centers on captive supply of critical components—superconducting magnets, detector arrays, radiopharmaceutical manufacturing capacity—across a five-to-ten year technology refresh horizon. Acquisition target archetype: pure-play imaging specialists with CE-marked portfolios facing 2027 EU MDR renewal deadlines and constrained regulatory affairs staffing. Monitor cyclotron network density improvements as the inflection signal for PET scanner category expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI Reconstruction Module | Accelerates hardware-software integration timelines for CT and MRI vendors seeking United States market entry. |
| Helium-Free Superconducting Magnet Production Scale-Up | Insulates hospital capital budgets from cryogen supply volatility while deepening vendor margin pools. |
| Hospital System Partnership for Multi-Modality Suite Deployment | Locks in 12-18% pricing concessions through multi-year volume commitments across integrated diagnostic platforms. |
| Software Companion Development for PET-MRI Hybrid Systems | Addresses installation complexity extending 8-14 month site readiness timelines through automated workflow protocols. |
| Reimbursement Strategy for Functional Imaging Codes | Secures parity between anatomical and functional imaging reimbursement to drive capital allocation intensity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with hospital purchasing committees, biomedical engineers, GPO contracts managers, and radiology department heads with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement data, hospital procurement databases, and EU MDR technical documentation repositories. Bottom-up installed base modeling and top-down capital expenditure triangulation anchored volume and value estimates.
Historical reference periods spanning system shipment data, cyclotron network expansion records, and radiopharmaceutical manufacturing capacity informed projection anchor points across the modeling period. Segmentation dimensions spanned modality architecture, clinical application intensity, end-user facility type, and regional regulatory cluster. CAGRs derived from curve-fitting against technology refresh cycle compression and AI-enabled reconstruction adoption velocity, with inputs from helium supply chain resilience indices and cyclotron network density metrics.
Radiopharmaceutical manufacturing capacity constraints, EU MDR certification timeline extensions, and reimbursement code parity adjustments are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Digital X Ray Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Global Digital Subtraction Angiography Market