
 Magnetic Resonance Imaging Equipment Coils Market | 2026-2036
Magnetic Resonance Imaging Equipment Coils Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Resonance Imaging Equipment Coils Market Insights
North American coil manufacturing is consolidating as OEMs tighten control over RF subsystem supply. Siemens Healthineers leverages captive coil production across its magnet facilities in Germany and the United States. GE Healthcare anchors its coil portfolio through deep integration with its SIGNA platform architecture. Koninklijke Philips N.V. differentiates via adaptive coil arrays that pair with its dStream digital broadband technology.
Magnetic resonance imaging equipment coils are radiofrequency antenna assemblies engineered from copper or silver conductors embedded in flexible polymer substrates, tuned to Larmor frequencies between approximately 8 MHz and 300 MHz depending on field strength, serving to excite nuclear spins and capture emitted signals for image reconstruction. Surface coils dominate clinical revenue due to their superior signal-to-noise ratio for targeted anatomies, while volume coils sustain installed base demand in whole-body screening protocols. Ultra-high-field MRI represents the fastest-growing technology segment as research institutions push toward 7-tesla and above for enhanced spatial resolution in neuroimaging.
The FDA regulates coil safety under 21 CFR 892.1000 as magnetic resonance diagnostic devices, while IEC 60601-2-33 governs electromagnetic compatibility and patient exposure limits across international markets. The EU MDR reclassification of active implantable MRI accessories has extended conformity assessment timelines for coil manufacturers seeking CE marking. Stakeholders must monitor harmonization gaps between FDA electromagnetic compatibility standards and emerging IEC amendments affecting multi-nuclear coil designs.
Market Dynamics
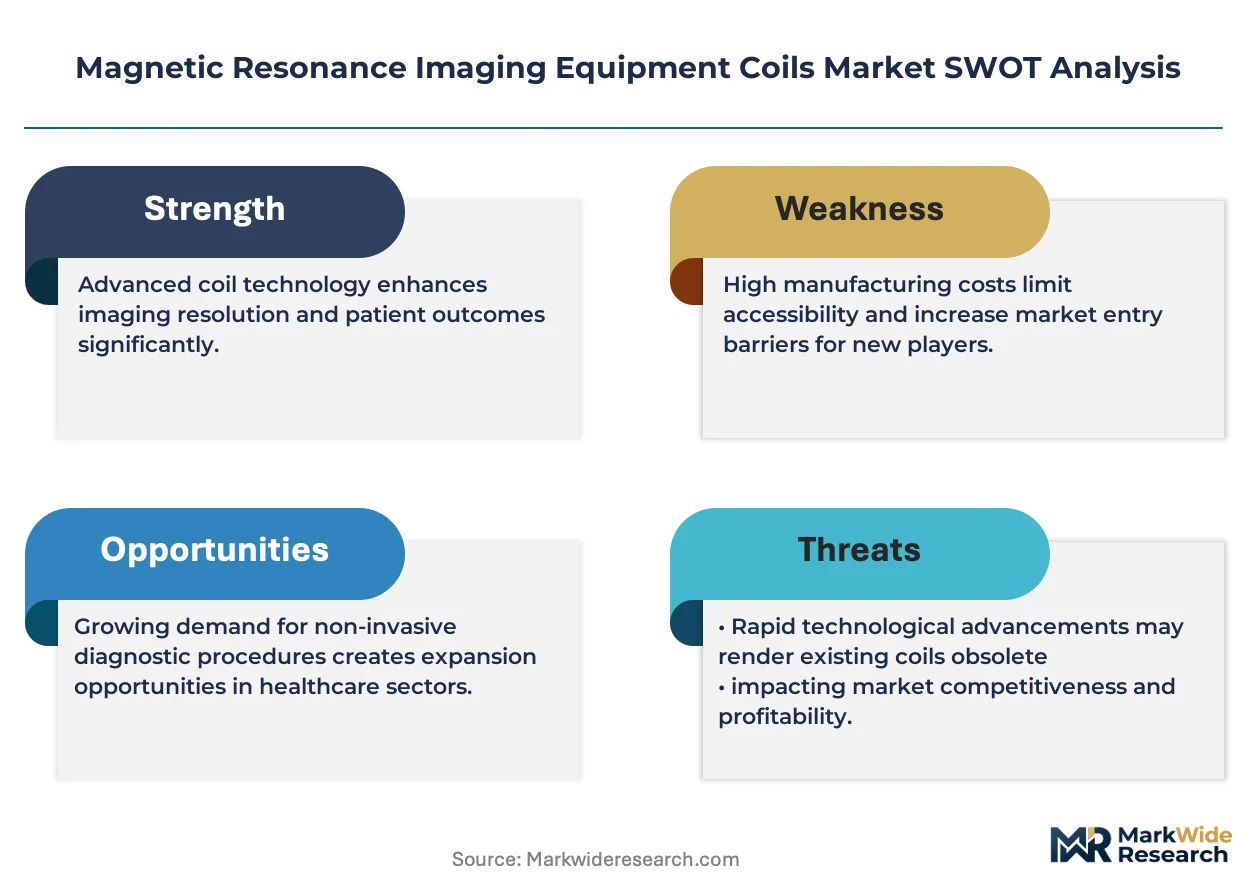
Ultra-high-field MRI adoption above 7-tesla is compressing replacement cycles for legacy coil arrays while research institutions demand purpose-built neurovascular and musculoskeletal configurations.
Growth Catalysts
- Hospital installed base expansion:Tertiary care centers in China and Germany are refreshing aging 1.5-tesla systems with 3-tesla platforms requiring compatible coil suites.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for RF accessories accelerates coil variant introductions compared to full device submissions.
- Multi-nuclear spectroscopy protocols:Sodium and phosphorus imaging applications drive demand for broadband-tunable coil architectures.
Market Restraints
- Copper and silver conductor volatility:Precious metal price swings compress manufacturing margins for flexible substrate assemblies.
- OEM captive supply concentration:Siemens Healthineers and GE Healthcare internalize coil production, limiting third-party vendor access to replacement markets.
- IEC 60601-2-33 electromagnetic compatibility:Stringent patient exposure limits constrain multi-channel array density in ultra-high-field designs.
Strategic Opportunities
- Veterinary diagnostic imaging:Companion animal MRI installations in the United States and Japan lack specialized coil form factors for non-human anatomies.
- EU MDR reclassification tailwinds:Extended conformity timelines for active implantable accessories create first-mover advantage for coil manufacturers achieving CE marking early.
- Disposable single-use surface coils:Infection control protocols in interventional MRI suites favor sterilization-eliminating polymer coil designs.
Industry Challenges
- RF engineer scarcity:Specialized expertise in Larmor frequency tuning and impedance matching commands premium compensation, constraining R&D throughput.
- Legacy system backward compatibility:Coil manufacturers must maintain variant portfolios spanning 15-plus years of magnet platform generations.
- Multi-regulatory certification parallelism:Simultaneous FDA 510(k), CE marking, and NMPA registration demands duplicate testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Resonance Imaging Equipment Coils Market |
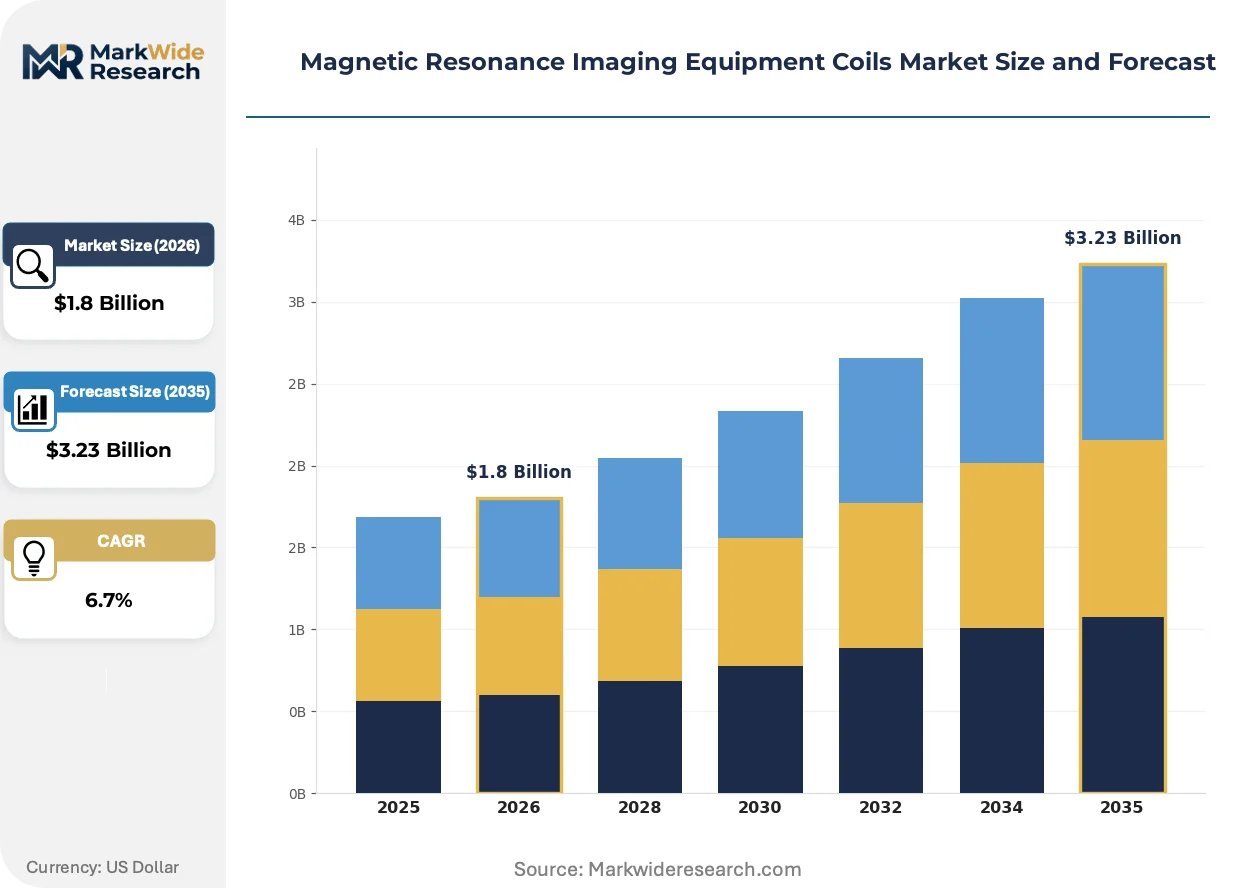
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Coils, Head Coils, Extremity Coils, Volume Coils End User: Hospitals, Imaging Centers, Research Facilities, Rehabilitation Clinics Technology: High-Field MRI, Low-Field MRI, Open MRI, Ultra-High-Field MRI Application: Neurology, Orthopedics, Oncology, Cardiovascular |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems, Shanghai United Imaging Healthcare Co., LTD, Esaote S.p.A., MR Instruments, Inc. (MRIi), Rapid MR International, LLC., Noras MRI Products GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Resonance Imaging Equipment Coils Market Trends and Innovations
Digital integration between coil arrays and reconstruction algorithms is collapsing the traditional boundary between hardware acquisition and software processing, forcing vendors to co-develop RF and computational subsystems.
Flexible printed circuit coil technology is modularizing around patient-specific anatomical conformations. Pediatric hospitals and orthopedic clinics adopt these substrates for improved signal-to-noise ratio in extremity imaging. The shift is modularizing procurement from standardized coil sets toward configurable channel banks that match examination protocols.
EU MDR reclassification of active implantable MRI accessories extends conformity assessment timelines for coil manufacturers seeking CE marking. The regulation forces smaller vendors to consolidate technical documentation capabilities or exit the European market entirely. Research institutions and university hospitals face delayed access to experimental multi-nuclear coil designs.
After-sales service unbundling disrupts traditional OEM coil replacement revenue. Independent service organizations in the United States now source third-party compatible arrays, fragmenting what was captive annuity streams. Radiology groups with in-house biomedical engineering capabilities drive this behavior most aggressively.
Magnetic Resonance Imaging Equipment Coils Market Segmentation
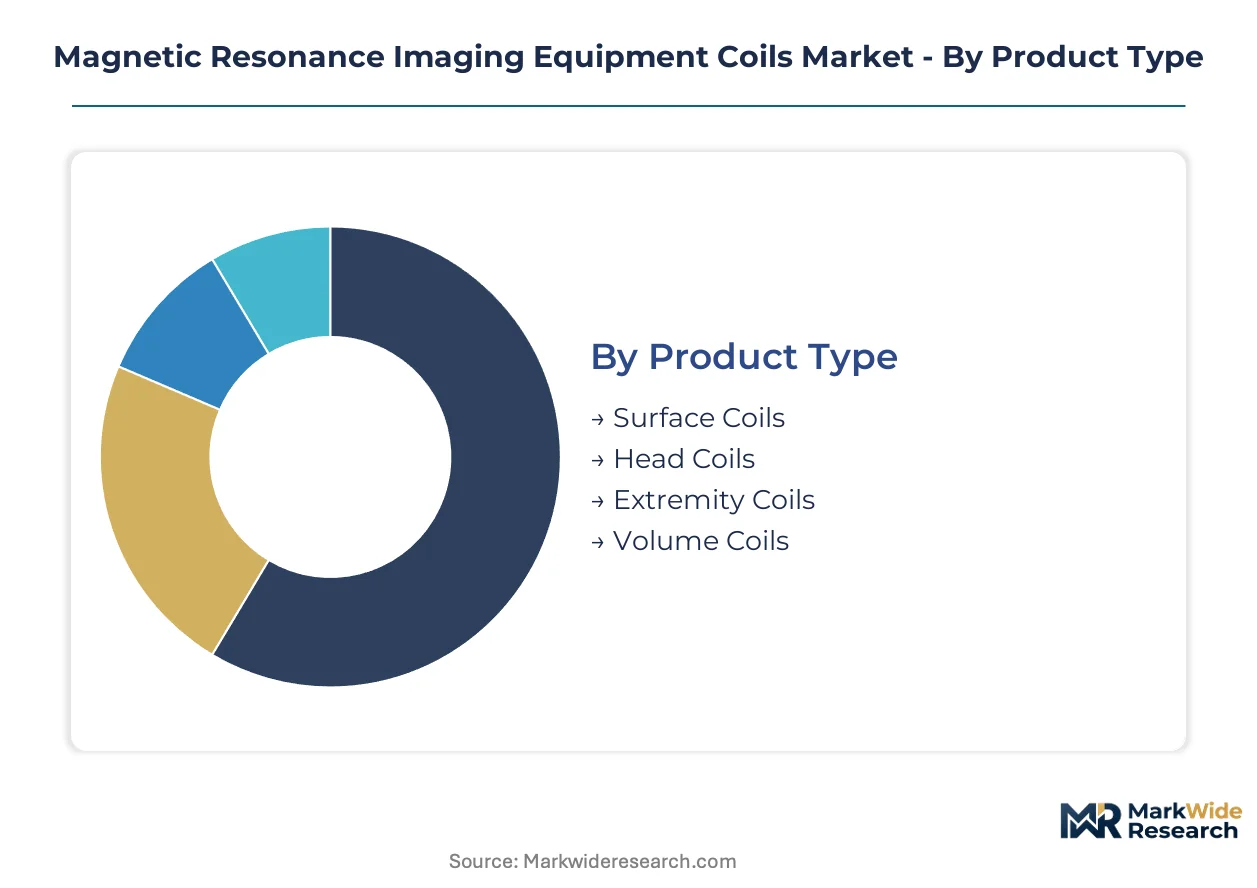
Coil procurement patterns diverge sharply across clinical settings and magnet platforms. Procurement committees weight signal fidelity against examination throughput, while research buyers prioritize spectral bandwidth over patient comfort.
Product Type:
Supply concentration in flexible substrate manufacturing favors vendors with captive polymer lamination capabilities.
- Surface Coils:Copper or silver conductors embedded in flexible polymer substrates deliver superior signal-to-noise ratio for targeted anatomies. Demand concentrates in orthopedic clinics across Germany and the United States where extremity imaging volumes justify dedicated coil investments. The FDA's 510(k) pathway enables rapid variant introductions for anatomically specialized configurations.
- Head Coils:Multi-channel arrays tuned to Larmor frequencies between 64 MHz and 300 MHz support neurovascular protocols. Research facilities in China and university hospitals in Germany drive refresh cycles as 7-tesla platforms displace legacy 3-tesla installations.
- Extremity Coils:Compact form factors target wrist, ankle, and shoulder examinations in sports medicine practices.
- Volume Coils:Whole-body screening protocols sustain installed base demand despite surface coil encroachment.
Today's leader: Surface Coils. Tomorrow's challenger: Head Coils.
End User:
Customer procurement sophistication separates tender-driven hospital systems from research grant-funded acquisitions.
- Hospitals:Tertiary care centers in China and Germany anchor coil procurement volume through magnet platform refresh programs. Siemens Healthineers and GE Healthcare captive supply agreements limit third-party vendor access to replacement markets.
- Imaging Centers:Independent radiology groups in the United States aggressively unbundle after-sales service, sourcing third-party compatible arrays through independent service organizations.
- Research Facilities:Sodium and phosphorus spectroscopy protocols drive demand for broadband-tunable architectures.
- Rehabilitation Clinics:Lower examination volumes favor shared coil pools over dedicated inventory.
Hospitals dominate procurement volume. Research facilities command the steepest expansion trajectory.
Technology:
Field strength migration patterns determine coil replacement cadence across installed base vintages.
- Ultra-High-Field MRI:Platforms above 7-tesla compress replacement cycles for legacy arrays while demanding purpose-built neurovascular configurations. Research institutions in Germany and the United States lead adoption as IEC 60601-2-33 electromagnetic compatibility constraints challenge multi-channel array density.
- High-Field MRI:3-tesla platforms represent the clinical standard for hospitals refreshing aging 1.5-tesla systems in China and Germany.
- Low-Field MRI:Open architecture designs serve claustrophobic patient populations and bariatric protocols.
- Open MRI:Permanent magnet configurations sustain demand in pediatric and interventional settings.
Ultra-High-Field MRI captures R&D investment. High-Field MRI sustains revenue concentration.
Application:
Reimbursement coding density varies sharply across clinical specialties, influencing coil specialization economics.
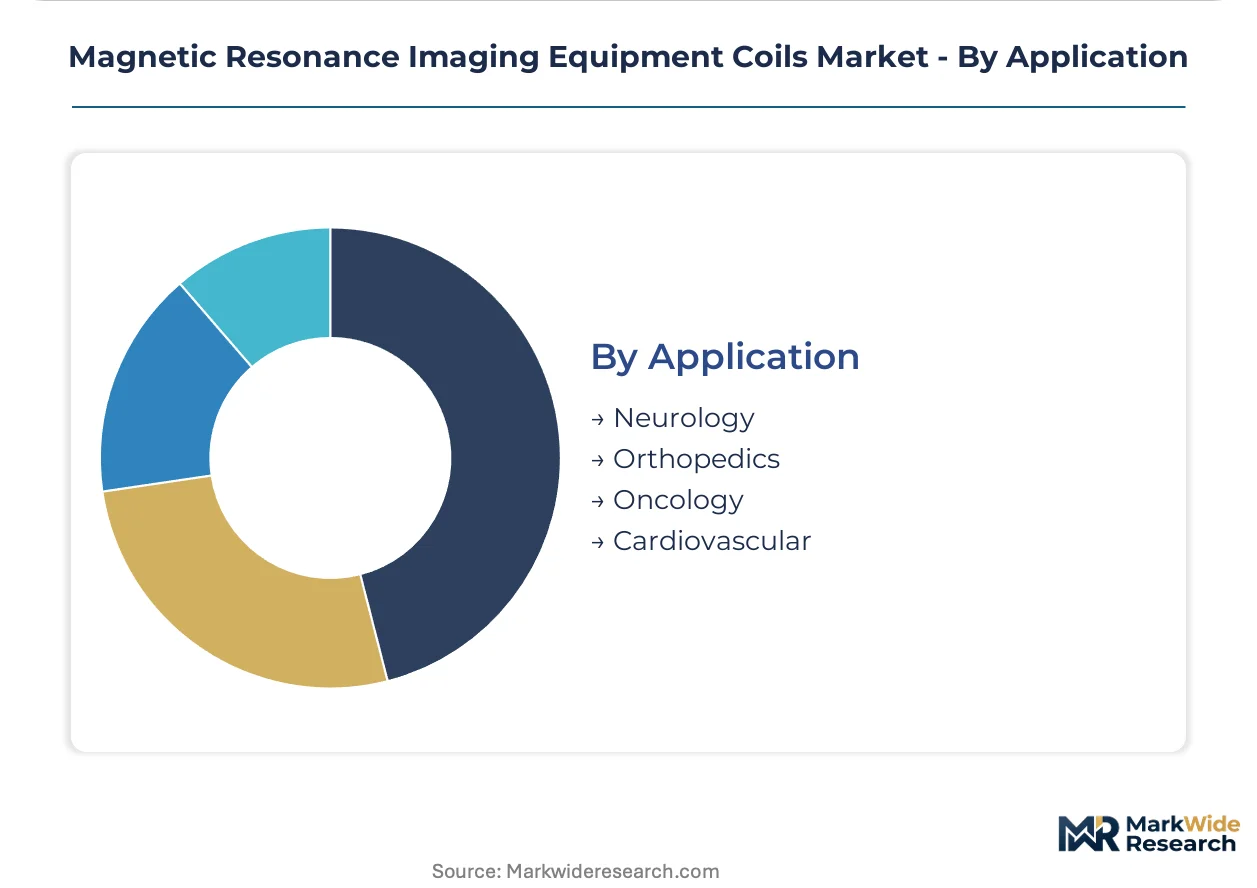
- Neurology:Functional imaging and diffusion tensor protocols demand multi-channel head arrays with advanced parallel imaging capabilities. Academic medical centers in the United States and Germany drive specification requirements as ultra-high-field adoption accelerates.
- Orthopedics:Extremity and dedicated shoulder coils support sports medicine and arthroplasty planning. Imaging centers in Japan and the United States favor flexible printed circuit substrates for patient-specific anatomical conformations.
- Oncology:Multiparametric imaging protocols require coil compatibility across magnet platforms.
- Cardiovascular:Cardiac gating integration constrains coil array geometry.
Neurology commands premium pricing. Orthopedics offers volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping coil manufacturing footprints as vendors relocate production to jurisdictions with streamlined electromagnetic compatibility certification. Cost-of-compliance gaps between the FDA's 510(k) pathway and the EU MDR's extended conformity timelines are accelerating this migration. Production clusters in Germany, the United States, and China now dominate, each leveraging distinct regulatory efficiencies.
United States
Tertiary care centers in Texas and California are refreshing aging 1.5-tesla magnet platforms with 3-tesla systems requiring compatible coil suites. The FDA's 510(k) premarket notification pathway enables rapid RF accessory introductions compared to full device submissions. Boston's medical technology corridor anchors domestic coil R&D, with Massachusetts General Hospital and Stanford University driving ultra-high-field neuroimaging specifications.
Germany
Siemens Healthineers leverages captive coil production across its magnet facilities in Erlangen and Forchheim, tightening control over RF subsystem supply. The EU MDR reclassification of active implantable MRI accessories has extended conformity assessment timelines, forcing smaller vendors to consolidate technical documentation. Bavaria's precision engineering cluster supports specialized copper conductor lamination for flexible substrate assemblies.
China
Hospital installed base expansion concentrates in Shanghai and Beijing, where tertiary care centers are displacing legacy systems with 3-tesla platforms. The NMPA registration process demands duplicate testing protocols alongside FDA and CE marking, constraining multi-regional certification parallelism. United Imaging Healthcare anchors domestic production in Shenzhen, serving both replacement markets and greenfield installations.
Japan
Companion animal MRI installations in Tokyo and Osaka lack specialized coil form factors for veterinary anatomies, creating unmet demand. METI standards govern electromagnetic compatibility for diagnostic devices, with JIS certification required for domestic market entry. Osaka's medical device manufacturing district hosts precision polymer substrate fabricators serving regional OEMs.
United Kingdom
Research facilities in Cambridge and London drive demand for broadband-tunable coil architectures supporting sodium and phosphorus spectroscopy. Post-Brexit regulatory divergence from EU MDR timelines creates compliance complexity for coil manufacturers seeking UKCA marking. The Oxford-Cambridge arc concentrates ultra-high-field MRI research, with 7-tesla platforms displacing legacy 3-tesla installations.
Magnetic Resonance Imaging Equipment Coils Market Competitive Landscape
German producers anchor one tier with captive supply integration; United States specialists hold replacement market access through independent service organization channels. The vendor structure concentrates around OEMs with magnet platform control, while third-party vendors fragment across compatible aftermarket arrays. Two archetypes dominate: vertically integrated equipment manufacturers and specialized RF subsystem fabricators. Competitive moves center on backward integration into conductor lamination and strategic partnerships with academic medical centers for ultra-high-field protocol development.
Among German-based fabricators, Siemens Healthineers and Noras MRI Products GmbH exemplify contrasting scale positions within the coil supply ecosystem. Siemens Healthineers occupies a position as the archetypal integrated equipment manufacturer with captive production across magnet facilities. Noras MRI Products GmbH represents the specialized RF subsystem tier, serving research institutions with purpose-built configurations. GE Healthcare, with its United States origins, anchors the premium-tier vector through deep platform architecture integration. These three entities collectively illustrate the market's bifurcation between scale-driven OEM control and specialist flexibility.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| Shanghai United Imaging Healthcare Co., LTD |
| Esaote S.p.A. |
| MR Instruments, Inc. (MRIi) |
| Rapid MR International, LLC. |
| Noras MRI Products GmbH |
| Others |
Pricing and Supply Chain Analysis
Captive coil production by Siemens Healthineers and GE Healthcare anchors both supply security and pricing power across the MRI equipment coils market, insulating these OEMs from precious metal volatility while constraining third-party vendor access to replacement revenue streams. This integration choice compresses margins for independent fabricators competing against bundled coil-magnet procurement agreements in hospital systems across the United States and Germany.
Pricing Analysis
Distributor margins on third-party compatible arrays range between 15% and 25% for independent service organizations serving imaging centers in the United States. Three-tier pricing structure across premium, standard, and economy levels separates OEM-branded coils with full platform integration from compatible aftermarket arrays and refurbished legacy units. Cost compression in standard-tier flexible substrate assemblies intensifies because copper and silver conductor price volatility feeds directly into manufacturing margins. Research facilities demonstrate the least price sensitivity due to grant-funded procurement protocols, while independent imaging centers aggressively negotiate unbundled service contracts.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from hospital systems in China, Germany, and the United States, with Siemens Healthineers and GE Healthcare internalizing RF subsystem production. Raw material dependencies center on copper and silver conductor stock, flexible polymer substrates from precision lamination facilities, and rare-earth magnet components for ultra-high-field configurations. Single-source vulnerability concentrates in Bavaria's precision engineering cluster for specialized conductor lamination. Distribution runs through captive OEM supply agreements for new magnet installations and independent service organizations for replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where the EU MDR's extended conformity timelines in Germany contrast sharply against the FDA's streamlined 510(k) pathway in the United States, creating cost and speed differentials for multi-regional certification strategies.
For Market Incumbents: Cement platform integration advantages by deepening captive supply of flexible substrate assemblies and locking hospital systems into multi-year coil refresh schedules tied to magnet platform upgrades. Defend against independent service organization encroachment by restricting technical documentation access for compatible array manufacturers. Prioritize R&D investment in broadband-tunable architectures for multi-nuclear spectroscopy protocols.
For New Entrants and Emerging Players: Veterinary diagnostic imaging represents an underserved buyer archetype with minimal OEM attention and unmet demand for non-human anatomical coil form factors in Japan and the United States. Disposable single-use surface coils for interventional MRI suites offer a second white-space target where infection control protocols favor sterilization-eliminating designs. Pursue regulatory-first go-to-market positioning by securing early CE marking ahead of EU MDR reclassification tailwinds.
For Investors and Strategic Acquirers: Roll-up economics work for specialized RF subsystem fabricators because OEM captive supply concentration has fragmented the third-party vendor landscape into sub-scale regional players. Long-term viability centers on technical documentation capabilities and multi-regulatory certification parallelism rather than manufacturing scale alone. Watch sodium and phosphorus spectroscopy adoption curves as the inflection indicator for broadband-tunable coil demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Early conformity achievement creates first-mover advantage against delayed competitor timelines. |
| Hospital System Partnership | Tertiary care center alliances in China and Germany anchor multi-year coil refresh revenue. |
| Software Companion Development | Digital integration with reconstruction algorithms collapses hardware-software boundaries for competitive differentiation. |
| Backward Integration into Conductor Lamination | Captive polymer substrate production insulates margins from copper and silver price volatility. |
| Veterinary Coil Form Factor Development | Companion animal MRI installations in Japan and the United States lack specialized anatomical configurations. |
Research Methodology
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged hospital purchasing committees, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs specialists at coil manufacturers. Secondary sources included FDA 510(k) filings, NMPA registration databases, EU MDR technical documentation, and hospital procurement records. Bottom-up coil shipment estimates triangulated against top-down magnet platform installation data.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include coil product type, end-user category, field strength technology tier, and clinical application specialty. CAGRs derived from installed base refresh cycles, replacement cadence by magnet vintage, and research facility expansion trajectories. Forecast inputs incorporated IEC 60601-2-33 electromagnetic compatibility constraint evolution and multi-nuclear spectroscopy protocol adoption curves.
Underlying measurement precision varies by segment; ultra-high-field and research facility categories carry tighter precision than replacement markets for legacy 1.5-tesla platforms. Forecasts reflect assumptions about regulatory harmonization timelines, precious metal price stability, and OEM captive supply continuity that could shift materially. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
India Ultrasound Devices Market