
 Global Biosensors Market | 2026-2036
Global Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biosensors Market Analysis
Software-defined analytics layers embedded in continuous glucose monitor platforms is broadening the recurring revenue base for device makers. Abbott Laboratories leverages its vertically integrated manufacturing footprint to control sensor production costs across multiple geographies. Dexcom sustains R&D intensity focused on algorithm-driven predictive glucose alerts. F. Hoffmann-La Roche Ltd anchors its competitive position through deep specialization in laboratory-grade electrochemical assay systems.
Biosensors are analytical devices combining a biological recognition element with a physicochemical transducer to detect target analytes with specificity measured in nanomolar or picomolar ranges; they convert biological responses into quantifiable electrical, optical, or thermal signals for industrial process control, clinical decision-making, and environmental surveillance. Electrochemical technology dominates unit economics due to mature screen-printed electrode manufacturing and minimal power requirements, while optical platforms capture premium positioning in multiplexed genomic and proteomic applications. Point-of-care testing segments are expanding fastest as decentralized health infrastructure demands rapid turnaround without laboratory logistics.
FDA breakthrough device designations and EU MDR conformity assessments compress development timelines for novel biorecognition formats while raising documentation burdens for market entrants. ISO 13485 quality management systems and IEC 60601 electrical safety standards form the baseline compliance architecture across all commercial jurisdictions. Stakeholders must monitor convergence between artificial-intelligence-enabled signal processing and evolving premarket review criteria for software-as-medical-device classifications.
Market Dynamics
Software-defined biosensor platforms are compressing development cycles and enabling real-time algorithm updates without hardware redesign, fundamentally altering how manufacturers capture recurring value from disposable sensor consumables.
Growth Catalysts
- EU MDR streamlined pathways:The European Medical Device Regulation's breakthrough device analog accelerates novel biorecognition formats toward commercialization, reducing time-to-revenue for electrochemical assay developers targeting laboratory-grade accuracy.
- Homecare glucose monitoring:Continuous glucose monitor adoption in decentralized diabetes management creates pull-through demand for interoperable insulin delivery systems and data analytics subscriptions.
- German industrial diagnostics cluster:Concentrated precision manufacturing capabilities in Baden-Württemberg and Bavaria supply screen-printed electrode substrates to global point-of-care device assemblers.
Market Restraints
- Platinum-group metal cost volatility:Electrochemical sensor electrodes depend on ruthenium and palladium thin-film deposition, exposing manufacturers to mining supply disruptions and speculative price swings.
- Japanese precision component concentration:High-sensitivity photodetectors for optical biosensor platforms source predominantly from specialized METI-certified suppliers in the Kansai region, creating single-source vulnerability.
- ISO 13485 documentation burden:Quality management system certification timelines extend 18-24 months for novel transducer formats, delaying revenue recognition for early-stage developers.
Strategic Opportunities
- India's CDSCO fast-track:The country's pharmaceutical regulator offers abbreviated review pathways for biosensors addressing antimicrobial resistance surveillance, opening clinical microbiology applications.
- Environmental contaminant monitoring:Surface water and soil analyte detection represents underpenetrated demand as China's MEE tightens discharge monitoring mandates for heavy industry.
- AI-enabled signal processing:Machine learning integration with electrochemical impedance spectroscopy is automating noise reduction and expanding detection limits without hardware redesign.
Industry Challenges
- Electrochemical firmware integration:Legacy hospital information systems lack native support for continuous glucose monitor data streams, forcing costly middleware development and validation cycles.
- Bioreceptor stability engineering:Enzyme and aptamer degradation during sterilization and shelf storage demands specialized lyophilization expertise that concentrates among contract manufacturing organizations in Switzerland and Singapore.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biosensors Market |
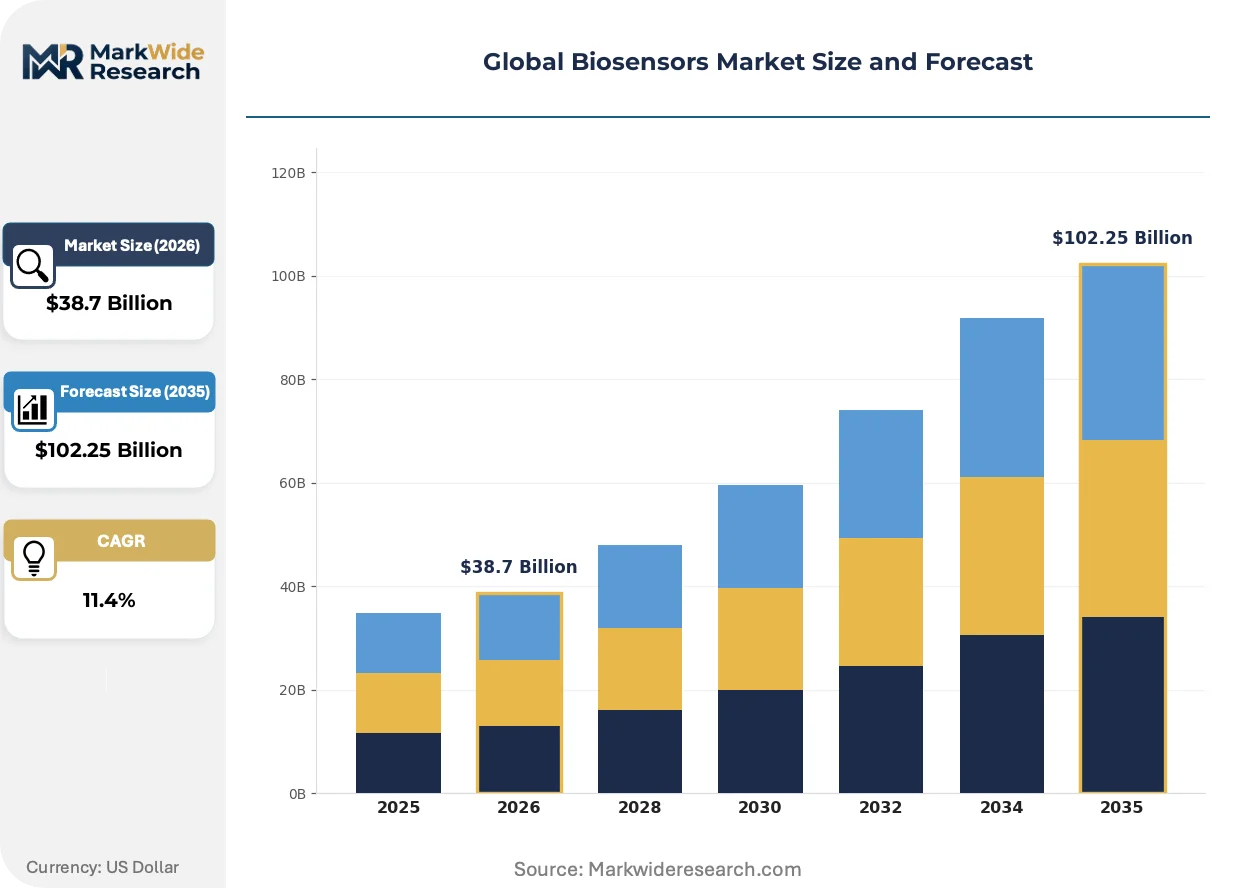
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Invasive Sensors, Non-invasive Sensors, Continuous Glucose Monitors Technology: Electrochemical, Optical, Piezoelectric, Thermal Application: Point-of-Care Testing, Environmental Monitoring, Food Safety Testing, Clinical Diagnostics End User: Hospitals, Laboratories, Homecare, Research Institutions |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Medtronic, Bio-Rad Laboratories, DuPont, Biosensors International Group, Dexcom, Universal Biosensors, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biosensors Market Emerging Trajectories
Artificial intelligence is penetrating signal processing layers across biosensor categories, compressing detection thresholds and enabling predictive health alerts that shift clinical decision-making from reactive to preemptive models.
Electrochemical impedance spectroscopy is automating real-time biomarker quantification in wearable form factors. Sports medicine clinics and occupational health programs in the United States are piloting sweat-based electrolyte and cortisol monitoring for hydration and stress management protocols. The FDA's software-as-medical-device guidance is forcing manufacturers to validate algorithm updates through controlled clinical studies rather than post-market patches.
REACH substance restrictions are phasing out legacy phthalate plasticizers in sensor housing materials. European electrochemical sensor assemblers are reformulating polyurethane encapsulants to maintain moisture barriers while complying with SVHC disclosure thresholds. Germany's industrial diagnostics cluster is absorbing compliance costs through vertical integration into polymer compounding.
Hospital procurement departments are consolidating biosensor vendors to reduce contract management overhead and standardize data interoperability. Integrated delivery networks in the United States are mandating HL7 FHIR compliance for all point-of-care devices, disqualifying legacy platforms lacking API-native architectures. This certification-driven preference shift favors manufacturers with captive software development capabilities over pure hardware suppliers.
Global Biosensors Market Segmentation
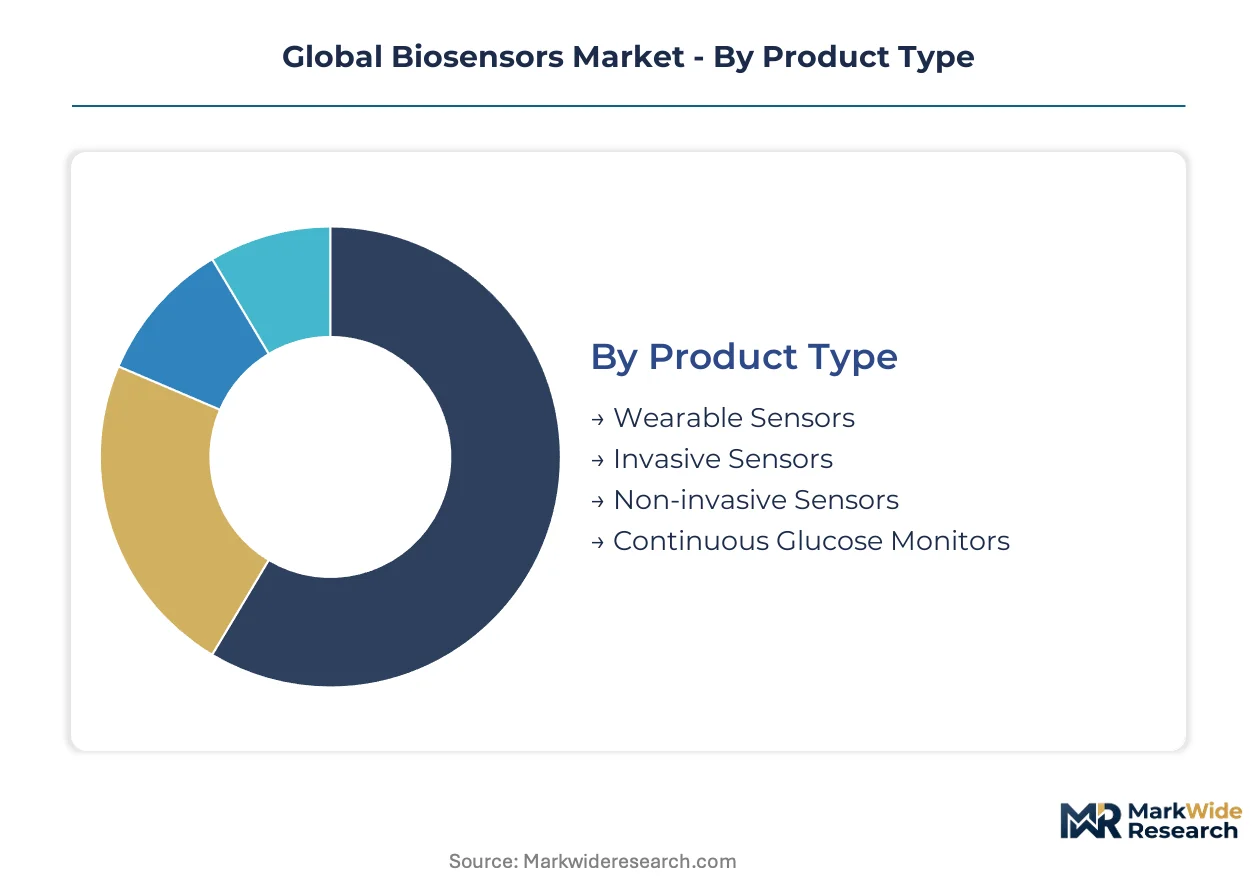
Biosensor architectures fragment across four critical dimensions: form factor intimacy with the body, transduction physics, clinical workflow position, and care setting infrastructure. Each axis creates distinct margin profiles and regulatory pathways that determine competitive viability.
Product Type:
Wearable and continuous monitoring systems embed into consumer lifestyles, while invasive and non-invasive formats serve episodic clinical encounters.
- Continuous Glucose Monitors:Subcutaneous filament sensors paired with algorithmic transmitters dominate recurring revenue models. Demand concentrates in United States homecare settings where FDA breakthrough designations accelerated commercial timelines and payer coverage expansion.
- Wearable Sensors:Electrochemical patches and optical wristbands integrate sweat, interstitial fluid, and photoplethysmography into unified health platforms. German industrial diagnostics clusters supply precision electrode substrates to manufacturers targeting occupational health programs.
- Invasive Sensors:Catheter-integrated or implantable electrochemical probes serve critical care glucose and lactate monitoring in surgical settings.
- Non-invasive Sensors:Optical and thermal transcutaneous platforms address patient populations with needle aversion or coagulopathy risks.
Volume placements concentrate in Continuous Glucose Monitors; the faster expansion belongs to Wearable Sensors.
Technology:
Cost structures and power requirements separate mature electrochemical platforms from premium optical systems requiring specialized photodetector supply chains.
- Electrochemical:Amperometric and potentiometric transducers using screen-printed electrodes dominate unit economics. Japanese METI-certified suppliers in the Kansai region control high-sensitivity photodetector availability for hybrid platforms.
- Optical:Surface plasmon resonance and fluorescence-based systems capture multiplexed genomic and proteomic applications. Demand concentrates in Switzerland's contract research manufacturing sector serving laboratory-grade assay developers.
- Piezoelectric:Quartz crystal microbalance and surface acoustic wave devices detect mass changes from biomolecular binding events.
- Thermal:Calorimetric transducers measuring enthalpy changes from enzymatic reactions serve niche industrial process control.
Electrochemical platforms anchor current volume; optical systems are climbing the fastest on precision medicine pull-through.
Application:
Decentralization pressure from healthcare systems favors point-of-care formats over centralized laboratory workflows.
- Point-of-Care Testing:Handheld electrochemical readers and cartridge-based optical systems eliminate sample transport logistics. India's CDSCO fast-track pathways for antimicrobial resistance surveillance are opening clinical microbiology placements.
- Clinical Diagnostics:Laboratory-grade systems with automated sample handling serve high-throughput hospital core labs. Demand concentrates in United States integrated delivery networks mandating HL7 FHIR data interoperability.
- Environmental Monitoring:Heavy metal and pathogen detection in surface water responds to China's MEE discharge tightening for industrial facilities.
- Food Safety Testing:Rapid pathogen and allergen screening at processing plants and import checkpoints.
Point-of-Care Testing captures volume leadership; environmental applications show steepest expansion trajectory on regulatory enforcement.
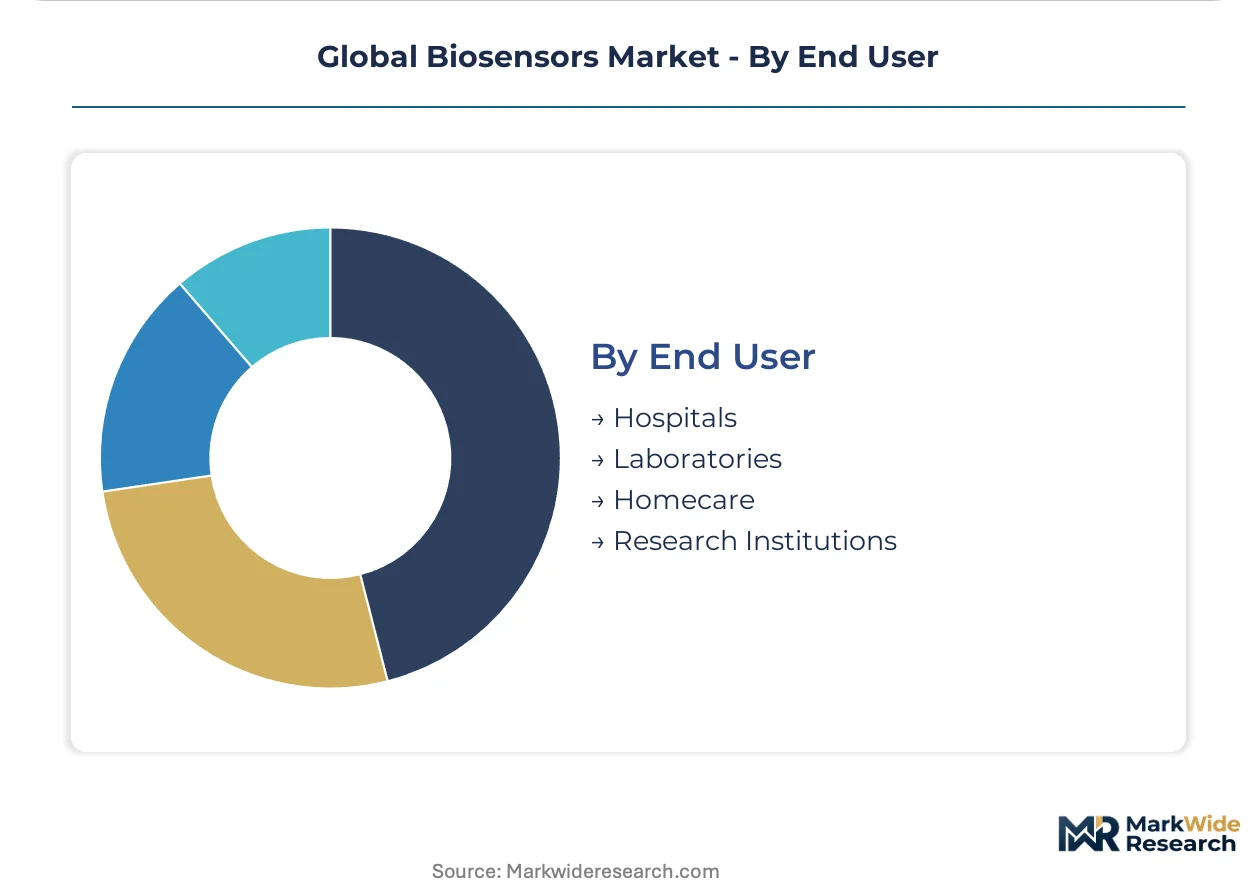
End User:
Procurement sophistication and reimbursement pathways create tiered pricing structures across care settings.
- Homecare:Direct-to-consumer and pharmacy-channel glucose monitors bypass institutional purchasing committees. United States Medicare coverage determinations for continuous glucose monitoring drive category definition.
- Hospitals:Enterprise contracts with integrated delivery networks favor vendors with captive software development for EMR integration.
- Laboratories:Reference labs and hospital core facilities demand ISO 13485-certified manufacturing and extensive analytical validation documentation.
- Research Institutions:Academic and government laboratories pilot novel biorecognition formats before commercial translation.
Homecare channels dominate placement velocity; hospital procurement consolidation is gaining share fastest on vendor rationalization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision manufacturing corridor supplies screen-printed electrode substrates to glucose monitor assemblers worldwide. FDA breakthrough designations in the United States and EU MDR pathways in Europe compress approval timelines while raising documentation standards. Industrial clusters in Germany, Japan, and Switzerland anchor component supply chains for electrochemical and optical platforms.
United States
Medicare coverage determinations for continuous glucose monitoring drive homecare channel expansion. FDA breakthrough device designations accelerate commercial timelines for novel biorecognition formats. The Boston-Cambridge corridor concentrates algorithm development talent for predictive glucose alert systems.
Germany
Industrial diagnostics demand concentrates in Bavaria's automotive supplier ecosystem for occupational health screening. EU MDR conformity assessments reshape documentation requirements for electrochemical assay developers. Baden-Württemberg's precision tooling manufacturers supply screen-printed electrode substrates to global device assemblers.
Japan
Precision medicine initiatives pull through demand for multiplexed genomic biosensors in Tokyo's academic medical centers. METI-certified suppliers in the Kansai region control high-sensitivity photodetector availability for optical platforms. Osaka's contract research manufacturing sector serves laboratory-grade assay developers.
Switzerland
Lyophilization expertise for enzyme and aptamer stabilization concentrates among contract manufacturing organizations near Basel. Swissmedic regulates in vitro diagnostic performance claims for point-of-care devices. The country's pharmaceutical supplier ecosystem feeds bioreceptor engineering capabilities into European device supply chains.
India
CDSCO fast-track pathways for antimicrobial resistance surveillance biosensors open clinical microbiology applications. Maharashtra's pharmaceutical manufacturing belt absorbs contract assembly work for electrochemical readers. The country's central bank monitors foreign investment flows into medical device joint ventures.
Global Biosensors Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the biosensor value chain, creating tiered competitive dynamics. Vertically integrated pharmaceutical conglomerates control sensor substrate manufacturing and algorithm development under unified ownership. Specialized diabetes technology firms concentrate R&D intensity on continuous monitoring software layers. Contract research manufacturers in Switzerland and Singapore anchor bioreceptor stabilization capabilities. Dominant competitive moves include backward integration into electrode substrate production and strategic partnerships for AI-enabled signal processing.
Among diversified healthcare conglomerates, Abbott Laboratories and F. Hoffmann-La Roche Ltd occupy positions spanning electrochemical assay systems and vertically integrated sensor manufacturing. Dexcom exemplifies the specialized continuous monitoring archetype with concentrated investment in algorithm-driven glucose prediction. These three companies represent distinct strategic postures: full-stack integration, laboratory-grade specialization, and software-defined platform development.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Medtronic |
| Bio-Rad Laboratories |
| DuPont |
| Biosensors International Group |
| Dexcom |
| Universal Biosensors |
| Koninklijke Philips |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation in the United States is mandating HL7 FHIR data interoperability for all point-of-care devices, disqualifying legacy platforms lacking API-native architectures and forcing manufacturers to absorb middleware development costs into pricing strategies. This certification-driven preference shift favors manufacturers with captive software development capabilities over pure hardware suppliers, compressing margins for undifferentiated electrode substrate vendors.
Pricing Analysis
Cost-down pressure on electrochemical sensor tiers accelerates because hospital integrated delivery networks are consolidating vendor lists to reduce contract management overhead. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated platforms with predictive algorithms from basic glucose readers and private-label alternatives. Price differentiation hinges on ISO 13485 certification tier and after-sales analytics subscription bundling. Homecare direct-to-consumer channels exhibit highest price sensitivity; laboratory-grade systems with automated sample handling command lowest sensitivity due to reimbursement pass-through.
Supply Chain Analysis
Platinum-group metal supply rests on South African mining operations and Russian speculative markets, exposing electrode manufacturers to ruthenium and palladium thin-film deposition cost volatility. Screen-printed electrode substrates draw from Baden-Württemberg precision tooling clusters, while high-sensitivity photodetectors for optical platforms sources from METI-certified Kansai region suppliers. Single-source vulnerability in Japanese precision components creates tariff exposure risk. Distribution runs through pharmaceutical distributor networks for hospital channels and pharmacy retail chains for homecare segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Biosensors Market operates as a cost-of-compliance story where EU MDR conformity assessments and FDA breakthrough device pathways create 18-24 month certification timelines that function as barrier-to-entry moats for compliant players with established quality management systems.
For Market Incumbents: Cement algorithm-driven predictive health alert capabilities through software-as-medical-device validation investments that lock in recurring revenue from disposable sensor consumables. Backward integration into screen-printed electrode substrate production defends against platinum-group metal cost volatility and Baden-Württemberg supply concentration. Prioritize captive software development for HL7 FHIR interoperability to capture hospital procurement consolidation mandates. For New Entrants and Emerging Players: Launch via India's CDSCO fast-track pathways for antimicrobial resistance surveillance biosensors, targeting clinical microbiology applications with abbreviated review timelines. Environmental contaminant monitoring in China represents white-space demand as MEE discharge mandates tighten for heavy industry. Sweat-based electrolyte and cortisol monitoring for occupational health programs offers go-to-market entry with lower regulatory burden than clinical diagnostics. For Investors and Strategic Acquirers: The window for entry favors contract research manufacturers with lyophilization expertise for enzyme and aptamer stabilization in Switzerland and Singapore. Long-term viability centers on platforms integrating AI-enabled signal processing with electrochemical impedance spectroscopy. Watch FDA software-as-medical-device guidance enforcement as inflection indicator for algorithm update validation costs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercial timelines for novel biorecognition formats in United States homecare settings. |
| EU MDR Conformity Assessment | Compresses approval pathways while raising documentation burdens for electrochemical assay developers. |
| Backward Integration into Electrode Substrates | Captures Baden-Württemberg precision manufacturing capabilities for cost control across geographies. |
| Software-as-Medical-Device Validation | Enables recurring revenue from algorithm updates without hardware redesign cycles. |
| CDSCO Fast-Track Pathway Entry | Opens clinical microbiology placements in India's pharmaceutical manufacturing belt. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, combined with primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at electrochemical assay developers. FDA 510(k) filings, EU MDR technical documentation, CMS Medicare coverage determinations, and ISO 13485 certification databases provided secondary validation. Bottom-up sensor unit economics and top-down healthcare expenditure triangulation cross-verified market sizing across the analysis window.
Reconciliation of continuous glucose monitor prescription volumes, point-of-care testing placement data, and environmental monitoring procurement records informed the analytical framework. Segmentation dimensions modeled include form factor intimacy, transduction physics, clinical workflow position, and care setting infrastructure. CAGRs derived from algorithmic curve-fitting against historical adoption patterns, with electrochemical impedance spectroscopy penetration and AI signal processing integration as industry-specific forecast inputs.
Regulatory timeline delays, platinum-group metal price volatility, and hospital procurement consolidation acceleration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about reimbursement expansion and software validation burden evolution. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Cryogenic Temperature Controller Market
Sensors and Controls
Printed Antenna Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Embedded Biometric Sensor Market