
 Semiconductor Wafer Fab Equipment (WFE) Market | 2026-2036
Semiconductor Wafer Fab Equipment (WFE) Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Wafer Fab Equipment (WFE) Market Analytics
Multi-source procurement for critical subsystems is shifting how foundries and IDMs contract equipment vendors. Applied Materials sustains broad process technology portfolios spanning deposition and etch. ASML Holding dominates extreme ultraviolet lithography with no near-term rival. Tokyo Electron anchors wet processing and thermal systems across leading-edge and mature nodes.
Semiconductor Wafer Fab Equipment encompasses the precision machinery used to pattern, deposit, modify, and clean silicon wafers during integrated circuit fabrication, with tools operating at nanometer-scale tolerances and sub-angstrom process control. These systems enable transistor formation through repeated cycles of lithography, etching, and material deposition on 300mm or 200mm substrates. Etching equipment commands substantial capital allocation as three-dimensional transistor architectures multiply process steps per wafer. EUV Lithography sits at the margin center due to sole-source optics and light-source complexity. Foundries represent the fastest-expanding end-user category as pure-play contractors add capacity for fabless chip designers.
Export control frameworks administered by the US Bureau of Industry and Security and Japan's METI restrict shipment of advanced lithography and deposition tools to specific fabrication facilities, reshaping vendor geographic strategies. The EU Chips Act and national subsidy programs in South Korea and the United States are conditioning equipment procurement on local content and supply chain transparency requirements. Stakeholders must track how dual-use technology classifications and evolving subsidy eligibility rules redirect equipment demand across competing fabrication clusters.
Market Dynamics
Three-dimensional transistor architectures are multiplying process steps per wafer, forcing foundries to double etch and deposition tool counts while EUV lithography bottlenecks concentrate capex allocation toward sole-source optics suppliers.
Growth Catalysts
- Automotive chip content expansion:Electric powertrains and advanced driver-assistance systems are driving silicon area per vehicle upward, pulling additional 300mm wafer starts through foundry networks.
- EU Chips Act subsidies:The framework's local content requirements are redirecting equipment procurement toward European fabrication clusters in Dresden and Leuven.
- High-bandwidth memory stacking:3D NAND layer counts exceeding 200 tiers are multiplying etch cycles per wafer, extending tool utilization rates at memory fabs.
Market Restraints
- EUV source component scarcity:Laser-produced plasma light sources depend on tin droplet generators and collector mirrors supplied by a concentrated German optics base.
- Fluorinated gas restrictions:The F-Gas Regulation is capping etch chamber cleaning chemistries, forcing process requalification timelines at European fabs.
- Specialized technician shortages:Vacuum system maintenance and lithography alignment engineering require multi-year training pipelines that lag equipment delivery schedules.
Strategic Opportunities
- India semiconductor subsidy schemes:The PLI scheme and Design Linked Incentive program are attracting outsourced assembly and test capacity that precedes front-end fab investments.
- Silicon carbide power device transition:Automotive inverter demand is pulling 150mm and 200mm SiC wafer processing equipment into dedicated fabrication lines.
- Chiplets and heterogeneous integration:Advanced packaging equipment for die-to-wafer bonding is creating new tool categories between front-end and back-end process boundaries.
Industry Challenges
- Cleanroom construction bottlenecks:Steel and concrete delivery timelines for gigafab shells now exceed equipment lead times, delaying tool installation schedules.
- Legacy 200mm equipment obsolescence:Mature node analog and power semiconductor demand is colliding with discontinued support for older deposition and etch platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Wafer Fab Equipment (WFE) Market |
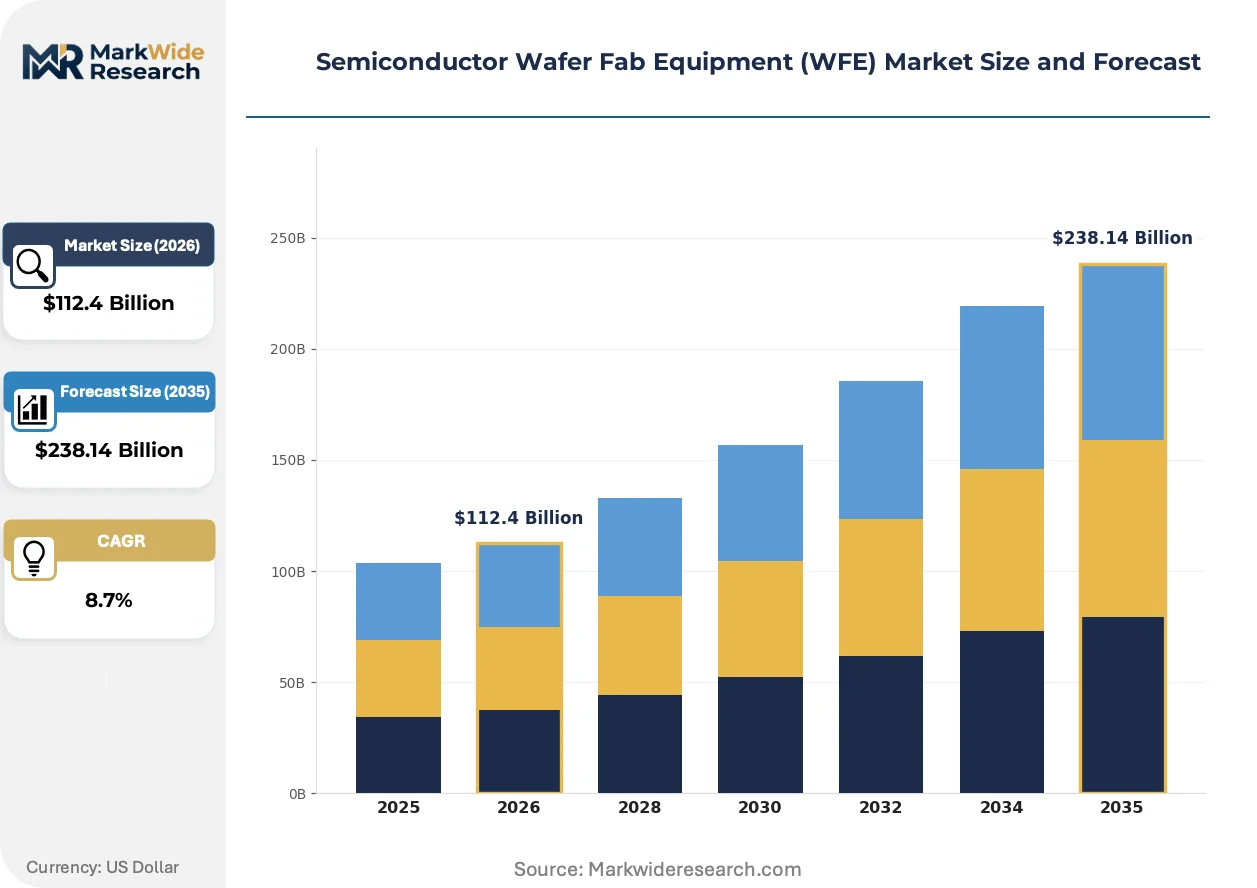
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $238.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deposition Equipment, Etching Equipment, Ion Implantation Equipment, Cleaning Equipment End User: Foundries, IDMs, Memory Manufacturers, Integrated Circuit Designers Technology: Optical Lithography, EUV Lithography, Electron Beam Lithography, Advanced Packaging Technology Application: Consumer Electronics, Automotive Electronics, IT & Telecommunications, Industrial Electronics |
| Companies Covered | Tokyo Electron, Advantest, Applied Materials, Panasonic Corporation, Canon Machinery, ASML Holding, KLA Corporation, ASM International, Lam Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Wafer Fab Equipment (WFE) Market Evolving Landscape
Equipment architectures are fragmenting into subsystem-specialized configurations as process complexity outpaces monolithic tool development cycles, compressing vendor competitive moats.
Atomic layer deposition systems are modularizing into chamber-exchangeable configurations that separate precursor delivery modules from vacuum transfer platforms. Memory manufacturers in South Korea are adopting these configurations to reduce qualification downtime between high-k dielectric and metal nitride film sequences. This architecture is modularizing vendor revenue streams from integrated system sales toward recurring chamber and precursor module attachments.
The US Bureau of Industry Security export control framework is restricting extreme ultraviolet lithography and certain plasma deposition tools to specific fabrication facilities based on end-use and location criteria. Equipment vendors are segmenting product roadmaps into restricted and unrestricted technology tiers, diverting engineering resources toward compliance documentation. Leading-edge logic capacity expansion in Taiwan and South Korea faces heightened licensing scrutiny, compressing delivery certainty for affected tool categories.
Multi-vendor service contracts are displacing single-source maintenance agreements as foundries seek to reduce downtime exposure from proprietary spare part dependencies. Pure-play contractors in the United States are unbundling lithography light source maintenance from original equipment vendor packages, redirecting service revenue toward third-party specialists. This pattern is most visible in Arizona and Texas fabrication clusters where rapid capacity ramps strain incumbent vendor field service density.
Semiconductor Wafer Fab Equipment (WFE) Market Segmentation
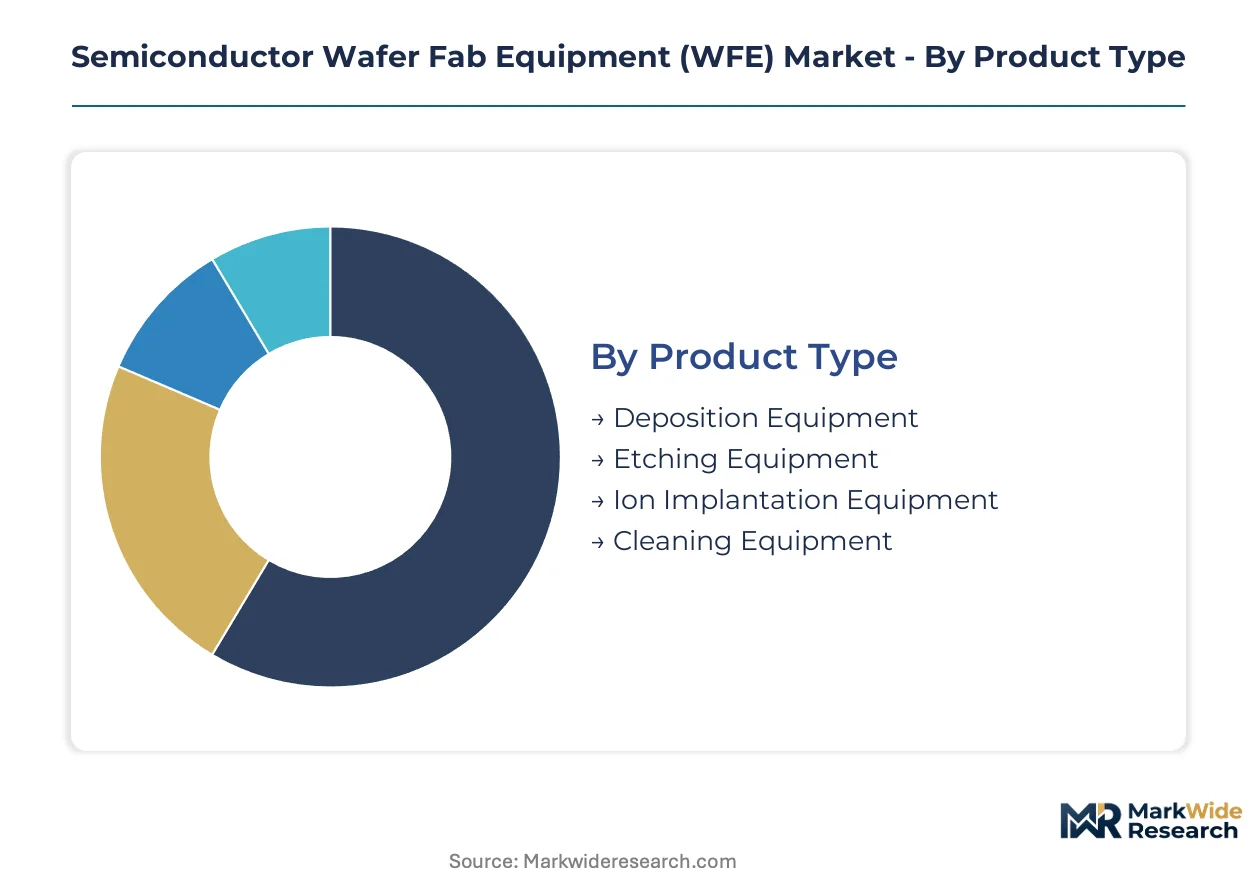
Equipment procurement patterns in semiconductor fabrication diverge sharply by buyer sophistication and process node requirements. Foundries and integrated device manufacturers deploy fundamentally different capex allocation models that reshape vendor engagement strategies.
Product Type:
Capital intensity per wafer layer separates deposition platforms from cleaning systems in foundry tender processes.
- Deposition Equipment:Atomic layer deposition and chemical vapor deposition systems deposit dielectric and conductive films with sub-nanometer thickness control. Taiwan and South Korea foundries are expanding ALD capacity for high-k metal gate stacks as transistor scaling accelerates.
- Etching Equipment:Plasma etch systems remove material selectively using reactive ion chemistry to pattern nanometer-scale features. Memory manufacturers in South Korea are multiplying etch tool counts as 3D NAND layer stacks exceed 200 tiers, extending chamber utilization cycles.
- Ion Implantation Equipment:Beamline and plasma immersion systems dope silicon with precise impurity concentrations to modulate electrical conductivity.
- Cleaning Equipment:Wet benches and single-wafer spray tools remove particulate and chemical residues between process steps.
Volume sits with Etching Equipment; growth tilts toward Deposition Equipment.
End User:
Business model architecture distinguishes pure-play contractors from captive fabrication operators in equipment specification priorities.
- Foundries:Pure-play manufacturing contractors process wafers for fabless chip designers on multi-project wafer runs. Taiwan-based foundries are expanding EUV lithography fleets to service advanced logic tape-outs from US and Chinese fabless customers.
- IDMs:Vertically integrated device manufacturers combine design and fabrication in captive facilities. Intel and Samsung IDM operations in Arizona and Texas are qualifying new deposition platforms for internal process roadmaps independent of merchant tool standards.
- Memory Manufacturers:Specialized DRAM and NAND flash producers operate dedicated fabs with process flows optimized for cell density scaling.
- Integrated Circuit Designers:Fabless semiconductor companies specify equipment requirements through foundry partner agreements without direct tool procurement.
Capex concentration favors Foundries; margin expansion is strongest among IDMs.
Technology:
Patterning resolution requirements and light-source physics differentiate lithography modalities in node-specific deployment.
- Optical Lithography:Deep ultraviolet systems using argon fluoride lasers pattern features at 193nm wavelength through immersion and multi-patterning techniques. Mature node fabs in China and Southeast Asia continue optical lithography investment for analog and power semiconductor production.
- EUV Lithography:Extreme ultraviolet systems at 13.5nm wavelength enable single-exposure patterning of sub-7nm transistor features. ASML's EUV monopoly concentrates procurement decisions for leading-edge logic capacity in Taiwan, South Korea, and the United States.
- Electron Beam Lithography:Maskless direct-write systems pattern wafers using focused electron beams for prototyping and low-volume production.
- Advanced Packaging Technology:Die-to-wafer bonding and through-silicon via equipment enables heterogeneous integration of chiplets.
Revenue pools concentrate in EUV Lithography; adoption velocity is climbing fastest for Advanced Packaging Technology.
Application:
Silicon content per unit and reliability specifications drive divergent equipment configurations across end-equipment categories.
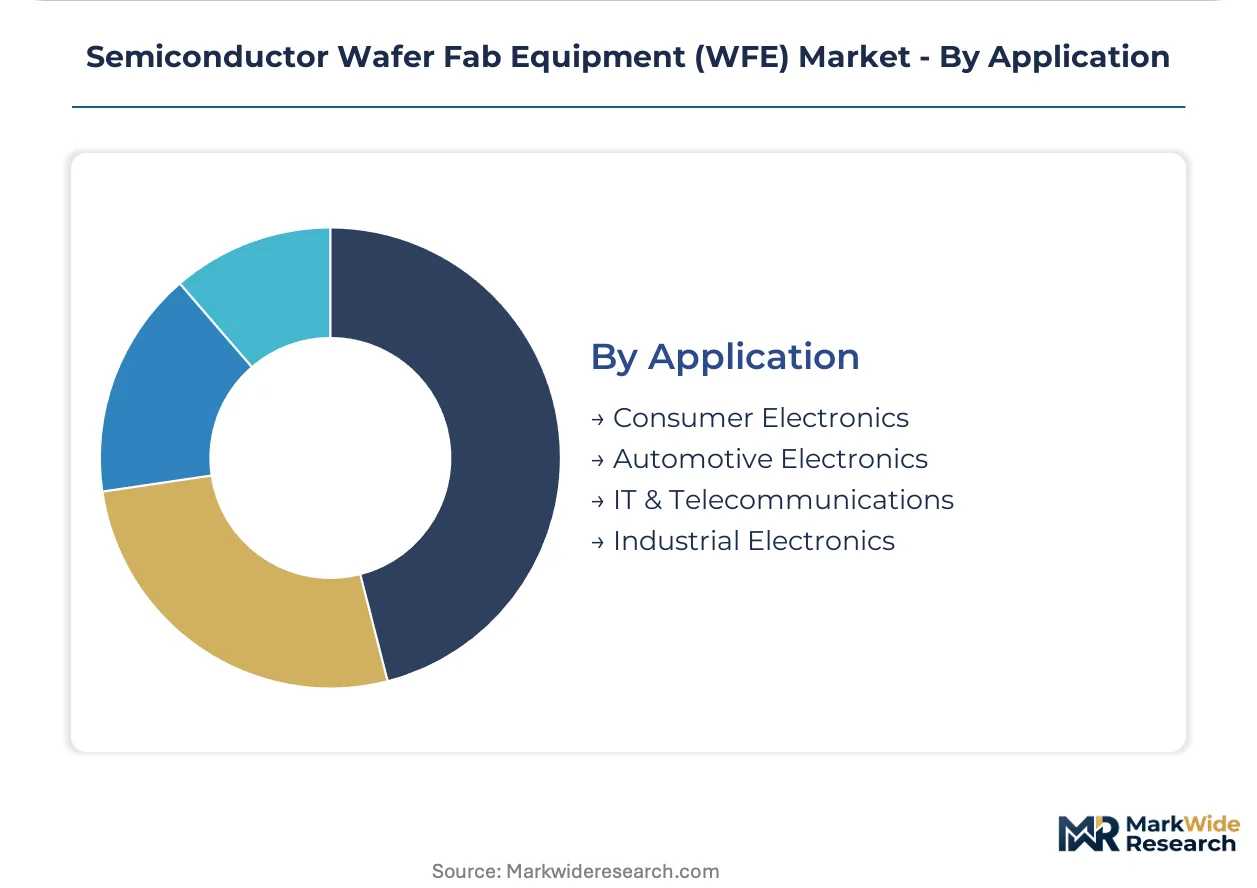
- Consumer Electronics:Smartphone and personal computing processors demand leading-edge logic fabrication with aggressive transistor density scaling. Apple and Qualcomm processor tape-outs through Taiwan foundries are pulling EUV lithography and advanced etch capacity.
- Automotive Electronics:Powertrain controllers and sensor fusion chips require extended temperature range qualification and zero-defect process control. German automotive tier-1 suppliers are qualifying 28nm and 40nm foundry capacity in Europe for electric vehicle inverter controllers.
- IT & Telecommunications:Datacenter processors and baseband modems balance performance with power efficiency in semi-custom process nodes.
- Industrial Electronics:Programmable logic controllers and motor drives operate on mature nodes with extended product lifecycle guarantees.
Unit volume dominates Consumer Electronics; capacity expansion is most aggressive in Automotive Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon feedstock from German and Japanese chemical suppliers anchors equipment demand geography. Lithography-grade synthetic quartz and fluorinated polymer supply chains concentrate procurement decisions in specific fabrication clusters. Equipment vendor field service density follows these material flows.
United States
CHIPS Act subsidies are pulling EUV lithography and advanced etch capacity toward Arizona and Texas fabrication clusters. The Bureau of Industry and Security export control framework restricts deposition tool shipments to specific end-users based on node thresholds. Intel's Arizona expansion and TSMC's Phoenix fab are qualifying new atomic layer deposition platforms for 3nm process roadmaps.
Taiwan
TSMC and UMC wafer starts are concentrating EUV fleet expansion in the Tainan Science Park and Hsinchu corridor. The National Science and Technology Council coordinates fab land allocation and power grid expansion for advanced node capacity. Kaohsiung's emerging 2nm megafab cluster is driving wet processing equipment demand for high-volume manufacturing.
South Korea
Samsung and SK Hynix 3D NAND layer stacking beyond 200 tiers is multiplying etch tool counts in Pyeongtaek and Icheon memory complexes. The Ministry of Trade, Industry and Energy K-Semiconductor Belt initiative subsidizes local equipment component sourcing. Yongin's emerging semiconductor cluster is attracting deposition equipment vendors for HBM memory die manufacturing.
Japan
Tokyo Electron and Shin-Etsu Chemical process technology leadership is anchoring equipment innovation in Kyushu's Kumamoto and Nagasaki prefectures. METI export controls on advanced deposition and lithography tools are reshaping vendor licensing procedures. Hiroshima's emerging logic fab cluster is qualifying new cleaning equipment for EUV resist processing.
Germany
Zeiss and Trumpf optics supply chain concentration is positioning Dresden and Leuven-adjacent facilities for EUV source component manufacturing. The EU Chips Act local content requirements are redirecting foundry equipment procurement toward Saxony's Silicon Saxony cluster. Infineon's Dresden expansion is driving thermal processing equipment demand for automotive power semiconductor lines.
Semiconductor Wafer Fab Equipment (WFE) Market Competitive Landscape
Capacity expansion dominates the current landscape as foundries and IDMs double tool counts for 3nm logic and 200-tier 3D NAND transitions. The vendor base concentrates around three strategic tiers: integrated process technology platforms spanning deposition and etch, lithography monopolists controlling sole-source EUV optics, and subsystem specialists modularizing chamber and precursor delivery architectures. Competitive positioning hinges on multi-year service contract capture and compliance documentation for export control licensing.
Within the integrated platform tier, Applied Materials and Lam Research exemplify broad process technology coverage across atomic layer deposition and plasma etch domains. ASML Holding occupies a singular position as the exclusive EUV lithography system supplier, with no near-term rival in extreme ultraviolet optics and light-source engineering. Tokyo Electron represents the wet processing and thermal systems anchor, serving both leading-edge logic and mature node analog fabrication lines across East Asian and North American clusters.
| Leading Market Players |
|---|
| Tokyo Electron |
| Advantest |
| Applied Materials |
| Panasonic Corporation |
| Canon Machinery |
| ASML Holding |
| KLA Corporation |
| ASM International |
| Lam Research |
| Others |
Value Network & Pricing Analysis
Foundry procurement concentration in Taiwan, South Korea, and Arizona is compressing equipment vendor margins through multi-year service contract unbundling and chamber modularity. EUV lithography's sole-source optics dependency leaves ASML with pricing power, while deposition and etch vendors face cost compression from subsystem specialization.
Pricing Analysis
Warranty and field service bundling is fragmenting as pure-play foundries in Arizona and Texas unbundle lithography light source maintenance from original equipment packages. Three-tier pricing structure across premium, standard, and economy levels separates EUV systems from DUV immersion tools and mature node equipment, with price differentiation driven by certification tier and volume scale. Pricing pressure stems from multi-vendor service contracts displacing single-source agreements. Memory manufacturers exhibit highest price sensitivity due to cyclical capacity planning, while IDMs absorb premium pricing for internal roadmap qualification.
Supply Chain Analysis
ISO 14644 cleanroom certification and SEMI equipment standards gate vendor qualification timelines, extending from chamber design to field installation. Component supply draws from Germany's Zeiss optics base, Japan's fluorinated polymer suppliers, and South Korea's precision motion systems. Single-source vulnerability concentrates in tin droplet generators and EUV collector mirrors. Distribution runs through direct vendor-foundry relationships with localized spare part hubs in Hsinchu, Pyeongtaek, and Dresden.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor consolidation is accelerating as export control compliance costs and R&D scale requirements force mid-tier subsystem specialists toward acquisition or exit. Sole-source lithography dominance and modular chamber architectures are reshaping competitive boundaries.
For Market Incumbents: Lock in multi-year service contract capture before third-party maintenance specialists achieve critical mass in Arizona and Texas clusters. Deepen backward integration into precursor chemistry supply to offset chamber modularity margin erosion. Threat from modular ALD platform entrants demands certification investment in high-k dielectric process roadmaps. For New Entrants and Emerging Players: Third-party lithography light source maintenance providers represent the most penetrable channel entry point, particularly in rapidly ramping US fabrication clusters. Target wet processing equipment refurbishment for mature node analog fabs facing 200mm platform obsolescence. Go-to-market angle: unbundled service contracts with guaranteed uptime SLAs against incumbent field service density gaps. For Investors and Strategic Acquirers: The window for entry favors subsystem specialists with chamber-exchangeable ALD configurations and EUV source component engineering capabilities. Long-term viability centers on compliance documentation infrastructure for Bureau of Industry and Security licensing. Signal to watch: METI export control expansion beyond current deposition tool categories.| Strategic Initiative | Industry Significance |
|---|---|
| Chamber Modularity Platform Development | Separates precursor delivery from vacuum transfer to reduce foundry qualification downtime. |
| Multi-Vendor Service Contract Capture | Unbundles maintenance from OEM packages to redirect revenue toward third-party specialists in Arizona. |
| Export Control Compliance Infrastructure | Segments product roadmaps into restricted and unrestricted tiers for Bureau of Industry and Security licensing. |
| Backward Integration into Precursor Chemistry | Captures recurring chamber attachment revenue streams from modular ALD configurations. |
| Geographic Field Service Density Expansion | Establishes spare part hubs in Hsinchu and Dresden to match foundry ramp timelines. |
Research Methodology
Multi-period observation of foundry capex announcements, EUV fleet deployment schedules, and export control licensing patterns anchored the trend analysis, supplemented by interviews with fab equipment procurement directors, lithography process engineers, vacuum system maintenance technicians, and chamber module suppliers. Secondary validation drew from Bureau of Industry and Security filings, SEMI equipment market data, foundry investor presentation disclosures, and national subsidy program documentation. Bottom-up tool count modeling triangulated against top-down wafer start projections.
Segment-weighting across equipment type, end-user category, technology node, and regional fabrication cluster shaped the analytical framework. CAGRs were derived from equipment intensity per wafer layer multiplied by projected wafer start growth across the analysis window. Industry-specific inputs included 3D NAND layer stacking trajectories, EUV source component lead times, and CHIPS Act subsidy disbursement schedules.
Caveats apply where METI export control expansion, F-Gas Regulation process requalification delays, or cleanroom construction bottlenecks could materially shift the outlook. Forecasts reflect assumptions on subsidy program continuity and dual-use technology classification stability. A model refresh is warranted upon material change in Bureau of Industry and Security node threshold definitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market