
 Paper-Thin Display Market | 2026-2036
Paper-Thin Display Market Size, Share, and Industry Trends Forecast 2026-2036
Paper-Thin Display Market Analytics
Indium tin oxide is consolidating its replacement by silver nanowire and metal mesh electrodes in flexible OLED stacks, cutting sheet resistance while maintaining optical transparency. Samsung Electronics leverages its in-house semiconductor-to-panel integration to dominate high-resolution smartphone substrates. BOE Technology anchors massive Gen 10.5 fab capacity in China, competing on cost at scale for LCD and emerging OLED lines. E Ink Holdings specializes in reflective e-paper architectures, occupying a defensible niche in low-power signage and e-reader segments.
Paper-thin displays are emissive or reflective visual interfaces measuring typically under 0.3 mm in total thickness, constructed on polyimide or ultra-thin glass substrates through vacuum thermal evaporation or inkjet printing of organic semiconductor layers, designed to deliver images while enabling mechanical bending radii below 5 mm for conformal mounting in space-constrained devices. Flexible display technology leads commercial shipments, with foldable variants capturing premium smartphone margins as Samsung and LG Display extend manufacturing yields. E-paper applications in retail digital signage sustain the fastest expansion trajectory, driven by shelf-edge labels that eliminate cabling infrastructure and enable decade-long battery operation in ambient light environments.
EPA hazardous substance rules and REACH substance restrictions constrain heavy metal content in display manufacturing, compelling substrate and phosphor reformulation across supply chains. South Korea's Ministry of Trade, Industry and Energy enforces national strategic technology designations that direct R&D tax credits toward domestic OLED equipment makers. China's GB standards for electronic product recyclability mandate disassembly-friendly adhesive systems, reshaping module lamination processes. Stakeholders must monitor how divergent ecodesign timelines between Brussels and Beijing fragment certification requirements for export-bound panel volumes.
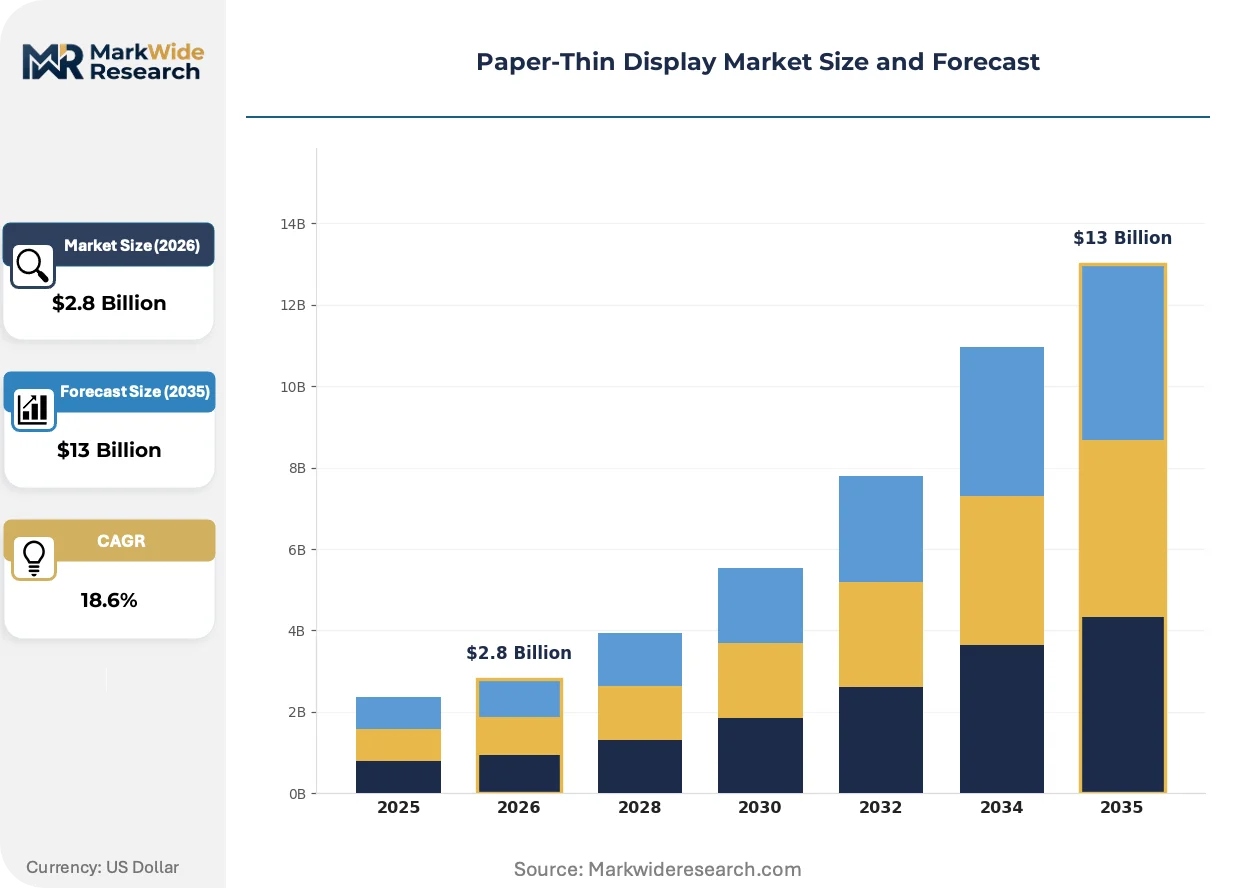
Market Dynamics
The transition from rigid glass substrates to polyimide-based flexible architectures is compressing module thickness below 0.3 mm while expanding bendable form factors, forcing capital reallocation across deposition equipment supply chains.
Growth Catalysts
- EU Green Deal ecodesign mandates:Mercury-free backlight requirements and recyclable substrate obligations are accelerating material reformulation investments across display module manufacturers.
- Automotive curved dashboard integration:Electric vehicle OEMs are specifying conformal display surfaces that conform to interior curvature without optical distortion at viewing angles exceeding 160 degrees.
- South Korean vertical fab concentration:Integrated substrate-to-module production corridors in Gyeonggi Province are compressing cycle times and yielding cost structures unmatched by fragmented supply chains.
Market Restraints
- Indium supply concentration:Over 80 percent of refined indium originates from Chinese smelters, creating input cost volatility for ITO electrode deposition processes.
- Silver nanowire sheet resistance trade-offs:Metal mesh alternatives sacrifice optical clarity above 85 percent transmission thresholds, limiting adoption in high-resolution smartphone stacks.
- EPA hazardous substance rules:Heavy metal content restrictions in phosphor formulations are forcing costly substrate and emitter layer redesigns across US-bound panel volumes.
Strategic Opportunities
- Retail digital signage battery elimination:Reflective e-paper shelf-edge labels operating on ambient light are displacing wired LCD installations in grocery and pharmacy chains.
- China's GB recyclability standards:Disassembly-friendly adhesive mandates are creating first-mover advantages for module laminators with reversible bonding chemistries.
- Foldable form factor premium capture:Mechanical bending radii below 5 mm are enabling device categories that command 40-60 percent price premiums over rigid equivalents in consumer electronics.
Industry Challenges
- Vacuum thermal evaporation technician scarcity:Organic semiconductor layer deposition requires specialized cleanroom operators with compound-specific handling certifications that outpace vocational training pipeline output.
- Gen 10.5 fab capex intensity:Single substrate generation upgrades demand equipment investments exceeding 3 billion dollars, concentrating capacity expansion among balance-sheet-heavy conglomerates.
- Divergent ecodesign timelines:Brussels and Beijing certification calendars are misaligned by 18-24 months, fragmenting test protocols for export-bound panel volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper-Thin Display Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, LCD, E-Paper, Mini-LED Application: Smartphones, Tablets, Wearable Devices, Digital Signage Technology: Flexible Displays, Transparent Displays, Foldable Displays, Biometric Integration End User: Consumer Electronics, Automotive, Retail, Healthcare |
| Companies Covered | LG Display, Samsung Electronics, AU Optronics, Innolux Corporation, BOE Technology, Japan Display, E Ink Holdings, Sharp Corporation, Visionox Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper-Thin Display Market Evolving Landscape
Material substitution at the electrode layer is compressing manufacturing costs while regulatory pressure on heavy metals is rewiring supplier qualification protocols across three continents.
Silver nanowire transparent conductors are rewriting the cost-transparency tradeoff in flexible OLED stacks. Automotive tier-one suppliers are qualifying these electrodes for curved instrument clusters ahead of 2025 model year launches. The technology is rewriting procurement specifications that previously locked ITO as the default conductive oxide.
REACH substance restrictions on cadmium and lead content are compelling phosphor reformulation across European-bound display volumes. Module manufacturers are qualifying rare-earth alternatives that maintain color gamut while satisfying ECHA authorization thresholds. Automotive and medical imaging segments face the steepest compliance timelines as these applications trigger the strictest substance concentration limits.
Direct procurement from substrate fabs is displacing traditional panel distributor networks in high-volume smartphone assembly. Foxconn and Pegatron are negotiating wafer-level contracts that bypass legacy module aggregators. South Korean and Chinese device assemblers are most advanced in this channel compression, with contract structures now covering 60-month supply horizons.
Paper-Thin Display Market Segmentation
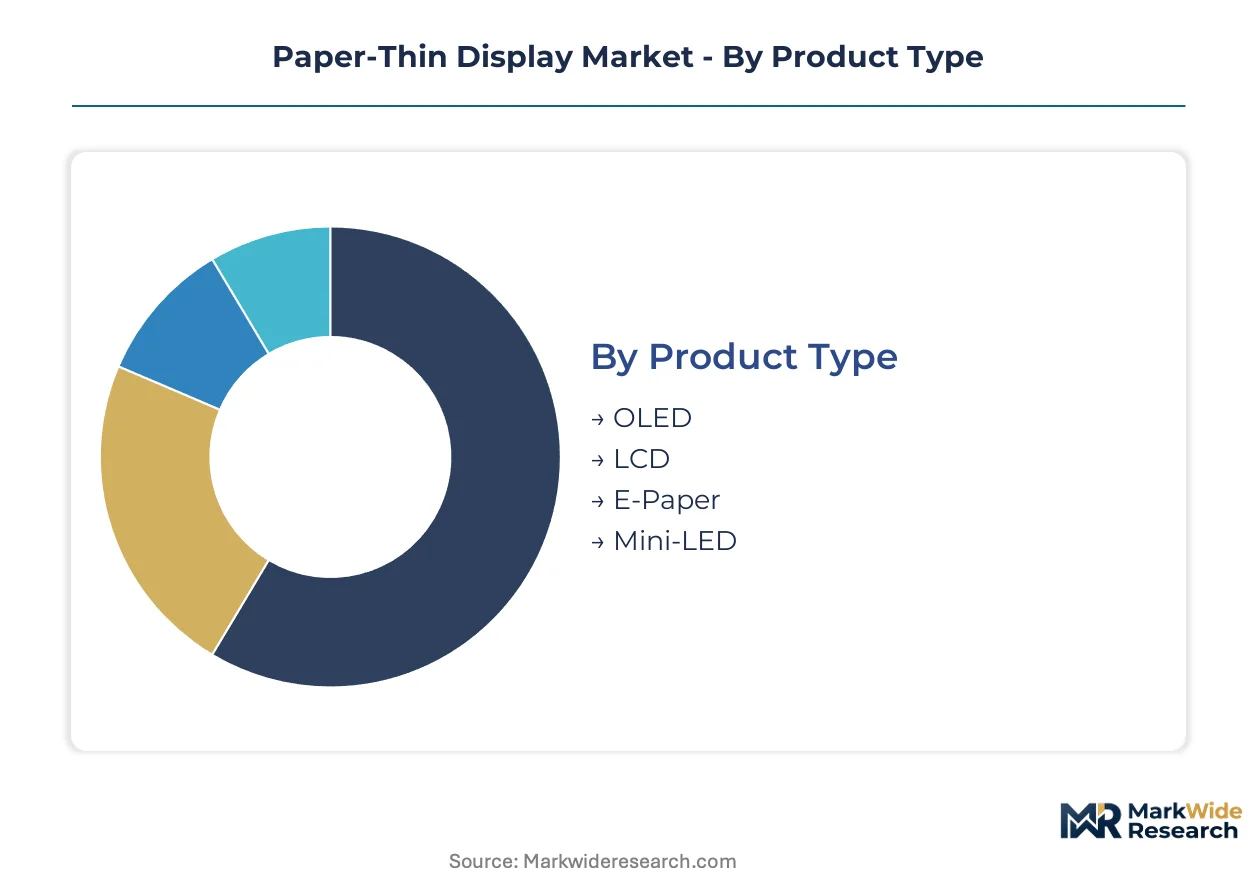
Paper-thin display architectures diverge sharply across substrate chemistry and emissive mechanisms, with each product type commanding distinct capital intensity and margin profiles. Segmentation clarity enables buyers to match bending radius specifications and power budgets against deployment environments.
Product Type:
OLED volumes dominate premium smartphone shipments while LCD retains cost-sensitive tablet and automotive positions; E-Paper and Mini-LED occupy opposing poles of power efficiency versus brightness performance.
- OLED:Organic semiconductor stacks deposited on polyimide substrates enable sub-0.3 mm thickness with mechanical bending radii below 5 mm. Samsung Electronics and LG Display concentrate capacity in South Korean fabs serving foldable smartphone OEMs, where panel prices command substantial premiums over rigid LCD equivalents.
- LCD:Thin-film transistor arrays on glass maintain cost leadership for larger-format applications where flexibility is non-critical. BOE Technology anchors Gen 10.5 capacity in China, shipping high-volume panels for automotive curved dashboards and budget tablet segments.
- E-Paper:E Ink Holdings produces reflective bistable displays operating without backlight power, dominating retail shelf-edge label deployments.
- Mini-LED:Local dimming backlights on ultra-thin substrates deliver HDR performance for premium tablets and automotive instrument clusters.
Today's leader: OLED. Tomorrow's challenger: E-Paper.
Application:
Smartphone form factors generate the steepest panel price premiums, while digital signage applications expand fastest as battery elimination reshapes retail infrastructure economics.
- Smartphones:Foldable and rollable variants drive substrate innovation, with mechanical durability testing exceeding 200,000 bending cycles. South Korean and Chinese OEMs concentrate procurement through direct fab contracts, compressing traditional distributor margins.
- Digital Signage:Reflective e-paper shelf-edge labels eliminate cabling infrastructure and enable decade-long battery operation under ambient light, with grocery and pharmacy chains in Europe and North America deploying at scale.
- Tablets:LCD retains share in education and enterprise segments where cost sensitivity outweighs flexibility requirements.
- Wearable Devices:Conformal displays on curved wrist surfaces demand specialized polyimide substrates with enhanced moisture barriers.
Smartphone panels capture peak margins. Digital signage offers the steepest expansion trajectory.
Technology:
Flexible architectures lead commercial shipments while biometric integration commands development resources from tier-one panel manufacturers seeking differentiation.
- Flexible Displays:Polyimide substrate technology enables conformal mounting on curved surfaces, with automotive tier-one suppliers qualifying panels for 2025 model year instrument clusters requiring 160-degree viewing angles without optical distortion.
- Foldable Displays:Mechanical bending radii below 5 mm create device categories commanding 40-60 percent price premiums, though yield management remains challenging at scale.
- Transparent Displays:Partial transparency applications in automotive head-up displays and retail window installations remain niche due to brightness trade-offs.
- Biometric Integration:Under-panel fingerprint sensors and cameras require specialized pixel aperture architectures, with Samsung Display leading integration efforts.
Flexible technology anchors current revenue. Biometric integration shapes next-generation R&D allocation.
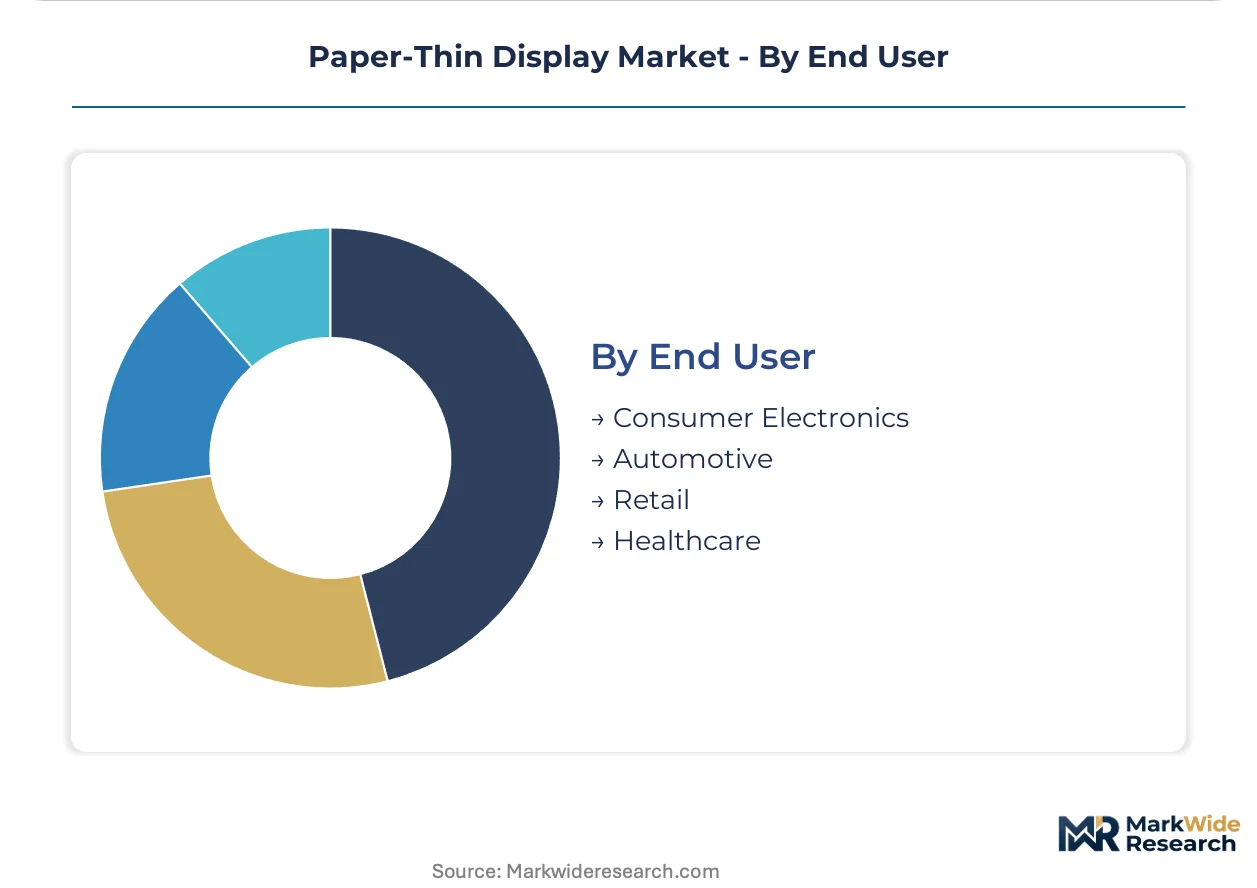
End User:
Consumer electronics absorbs the majority of panel volume while automotive specifications tighten fastest under functional safety and optical performance requirements.
- Automotive:Electric vehicle OEMs specify conformal dashboard surfaces with mercury-free backlights under EU Green Deal ecodesign mandates, requiring substrate and phosphor reformulation across supply chains.
- Consumer Electronics:Smartphone and tablet manufacturers concentrate demand in South Korea and China, with direct procurement from substrate fabs displacing legacy module aggregators.
- Retail:Digital signage deployments prioritize reflective e-paper for battery elimination, with EU F-Gas Regulation and REACH substance restrictions shaping panel qualification protocols.
- Healthcare:Medical imaging displays face the strictest heavy metal concentration limits under EPA hazardous substance rules and ECHA authorization thresholds.
Consumer electronics drives volume scale. Automotive sets the pace for specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi Province anchors substrate-to-panel manufacturing corridors, compressing cycle times through vertically integrated production. South Korean fabs supply foldable smartphone stacks to device assemblers across Asia and North America. Regulatory divergence between Brussels and Beijing fragments certification timelines for export-bound volumes.
South Korea
Seoul Capital Area drives foldable OLED procurement for premium smartphone OEMs, with mechanical bending radii below 5 mm commanding substantial panel premiums. The Ministry of Trade, Industry and Energy directs R&D tax credits toward domestic OLED equipment makers under national strategic technology designations. Gyeonggi Province hosts integrated corridors where LG Display and Samsung Electronics operate from substrate fabrication through module assembly.
China
Yangtze River Delta concentrates Gen 10.5 fab capacity serving cost-sensitive tablet and automotive dashboard segments. GB standards for electronic product recyclability mandate disassembly-friendly adhesive systems, reshaping module lamination processes. BOE Technology anchors massive substrate generation capacity in Hefei and Beijing, competing on scale for LCD and emerging OLED lines.
Japan
Kansai region sustains specialized e-paper and reflective display architectures for retail signage applications. METI enforces industrial standards that shape phosphor formulation requirements for display exports. Sharp Corporation maintains production presence in Sakai and Kameyama, supplying ultra-thin glass substrates for automotive instrument clusters.
United States
California and Texas host automotive tier-one suppliers qualifying curved dashboard panels for 2025 electric vehicle model years. EPA hazardous substance rules constrain heavy metal content in phosphor formulations, compelling substrate redesigns for US-bound volumes. Detroit-area engineering centers coordinate specification alignment with South Korean and Chinese panel sources.
Germany
Baden-Württemberg anchors automotive OEM specification development for conformal instrument clusters requiring 160-degree viewing angles. EU Green Deal ecodesign mandates enforce mercury-free backlight requirements and recyclable substrate obligations across European-bound panel volumes. Stuttgart engineering corridors coordinate qualification protocols with South Korean substrate fabs.
Paper-Thin Display Market Competitive Landscape
Global majors compete with regional champions across substrate generation capacity and specialized display architectures. The vendor base separates into scale-driven conglomerates operating Gen 10.5+ fabs, technology specialists commanding niche emissive mechanisms, and integrated device manufacturers with captive panel demand. Three archetypes dominate: substrate-scale leaders, flexible-stack specialists, and reflective-architecture pure-plays. Capacity expansion and direct procurement channel compression represent the dominant competitive moves reshaping distributor relationships.
Among South Korea-based integrated manufacturers, Samsung Electronics and LG Display exemplify the substrate-to-device archetype with in-house semiconductor-to-panel integration. BOE Technology represents the scale-driven Chinese competitor anchoring massive Gen 10.5 capacity. E Ink Holdings occupies a defensible position as the reflective-architecture specialist serving low-power signage segments.
| Leading Market Players |
|---|
| LG Display |
| Samsung Electronics |
| AU Optronics |
| Innolux Corporation |
| BOE Technology |
| Japan Display |
| E Ink Holdings |
| Sharp Corporation |
| Visionox Technology |
| Others |
Value Network & Pricing Analysis
Silver nanowire electrode costs cascade from Chinese precursor suppliers through South Korean fab operators into foldable smartphone panel pricing tiers, with indium price volatility forcing rapid substitution decisions at the deposition equipment layer.
Pricing Analysis
Input-cost pass-through from indium and silver nanowire precursors compresses margins in ITO-dependent LCD tiers while OLED stacks capture premium-mid-economy pricing differentiation based on bending radius specifications. Certification under EU Green Deal ecodesign and REACH substance thresholds adds compliance cost layers that widen spreads between mercury-free and legacy backlight configurations. Price erosion runs through standard-grade LCD segments as BOE Technology's Gen 10.5 scale economies feed downstream. Automotive OEMs exhibit lowest price sensitivity due to functional safety requirements, while education tablet assemblers face acute pressure from budget procurement cycles.
Supply Chain Analysis
Dual-sourcing requirements from Samsung Electronics and LG Display compel smartphone OEMs to qualify BOE Technology and Visionox Technology as alternative substrate suppliers, fragmenting procurement concentration despite Gyeonggi Province's integrated corridor advantages. Supply draws from South Korea, China, and Japan for polyimide substrates, organic semiconductor precursors, and ultra-thin glass respectively. Single-source vulnerability concentrates in Chinese indium smelters controlling over four-fifths of refined output. Distribution runs through direct fab contracts that displace legacy module aggregators, with Foxconn and Pegatron negotiating wafer-level agreements covering extended supply horizons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as automotive electrification mandates conformal display integration across every OEM platform refresh cycle.
For Market Incumbents: Anticipate silver nanowire qualification timelines accelerating as automotive tier-one suppliers demand 160-degree viewing angle conformance for 2025 model year instrument clusters. Samsung Electronics and LG Display should deepen backward integration into precursor chemistry to offset Chinese indium concentration. BOE Technology must defend Gen 10.5 cost position against emerging OLED line competition from domestic rivals. For New Entrants and Emerging Players: Capture reflective e-paper shelf-edge label deployments in European grocery and pharmacy chains where battery elimination eliminates cabling infrastructure costs. Retail digital signage offers the most penetrable vertical due to decade-long replacement cycles and minimal incumbent lock-in. Pursue disassembly-friendly adhesive qualification under China's GB recyclability standards to secure first-mover positioning with domestic module laminators. For Investors and Strategic Acquirers: Consolidation pressure builds where Gen 10.5 fab capex intensity exceeds three billion dollars per substrate generation upgrade, concentrating expansion among balance-sheet-heavy conglomerates. Long-term viability favors reflective-architecture specialists with defensible e-paper IP and automotive-qualified flexible stack developers. Watch for inflection in vacuum thermal evaporation technician pipeline output, as compound-specific handling certification scarcity constrains organic semiconductor layer deposition capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Samsung Electronics reduces indium cost exposure through captive silver nanowire electrode development. |
| Automotive Tier-One Qualification | LG Display secures curved dashboard panel supply agreements under EU Green Deal mercury-free mandates. |
| Retail Digital Signage Deployment | E Ink Holdings expands reflective e-paper shelf-edge label volumes across European grocery chains. |
| Gen 10.5 Capacity Expansion | BOE Technology anchors cost leadership in LCD tablet and automotive dashboard segments at scale. |
| Disassembly-Friendly Adhesive Development | Module laminators with reversible bonding chemistries capture first-mover advantage under China's GB standards. |
Research Methodology
Coverage spans South Korea, China, Japan, the United States, and Germany, with primary inputs from each market cluster combining interviews with substrate fab operations directors, automotive tier-one supplier procurement leads, retail signage deployment managers, OLED equipment R&D heads, and regulatory affairs specialists handling REACH and EPA compliance. Secondary validation draws from SEC 10-K filings of listed panel manufacturers, EU ECHA substance restriction databases, Korean Ministry of Trade R&D tax credit disclosures, and Chinese GB standard publication records. Bottom-up panel shipment data triangulates against top-down display market value estimates.
Granularity-level modeling distinguishes flexible versus foldable versus rigid substrate architectures, with OLED, LCD, E-Paper, and Mini-LED product types tracked separately across smartphone, digital signage, tablet, wearable, and automotive applications. Technology dimensions include flexible display, foldable display, transparent display, and biometric integration categories. End-user segmentation separates consumer electronics, automotive, retail, and healthcare procurement patterns. CAGRs derive from shipment volume trajectories weighted by average selling price evolution across the projection horizon. Forecast inputs incorporate indium price volatility scenarios and automotive OEM platform electrification timelines.
Underlying measurement precision varies by segment; smartphone panel volumes carry tighter precision than emerging transparent display categories due to established direct procurement reporting channels. Forecasts reflect assumptions on silver nanowire yield improvement rates and EU-China regulatory timeline convergence. Deviation in indium supply disruption or automotive qualification delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global 5K Display Resolution Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
OLED Panel Market
Display Technologies
United States Microdisplay Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Global Industrial Display System Market
Display Technologies
Head Up Display Market
Display Technologies
3D Display Module Market
Display Technologies
E-Paper Display Market
Display Technologies
Video Wall Display Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Dot Matrix Display Market
Display Technologies
3D Display Market
Display Technologies
OLED Laptops Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Projector Screen Market