
 Power Integrated Modules Market | 2026-2036
Power Integrated Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Power Integrated Modules Market Analytics
Aftermarket thermal management and predictive maintenance services are reshaping margin distribution across the power module value chain. Infineon Technologies AG leverages its Dresden and Kulim manufacturing complexes to sustain cost leadership in silicon-based IGBT modules for industrial drives. Mitsubishi Electric Corporation anchors its position through captive silicon carbide substrate development, reducing dependency on external wafer suppliers. ON Semiconductor Corporation competes by specializing in intelligent power modules with integrated gate drivers for appliance motor control.
Power integrated modules combine multiple power semiconductor dies, gate drive circuitry, and thermal management substrates into single packaged assemblies rated from several hundred watts to multiple megawatts for efficient energy conversion. Manufacturers employ direct bonded copper substrates, aluminum nitride ceramics, and silver sintering processes to achieve junction temperatures exceeding 175°C while maintaining thermal cycling reliability. Three-phase modules currently occupy the largest revenue share due to their dominance in motor drive and grid-tied inverter applications. Silicon carbide technology represents the fastest-expanding segment as 1200V and 1700V MOSFET modules displace silicon IGBTs in electric vehicle inverters and renewable energy converters.
The US Department of Energy appliance efficiency standards and EPA industrial emissions frameworks tighten specifications for motor drive systems, directly elevating demand for higher-efficiency module architectures. China's GB standards for electric vehicle power electronics and the EU Ecodesign Directive for industrial equipment mandate minimum efficiency thresholds that favor wide-bandgap semiconductor adoption. Stakeholders must monitor regulatory divergence between jurisdictions where efficiency test methodologies and certification requirements create distinct product qualification pathways.
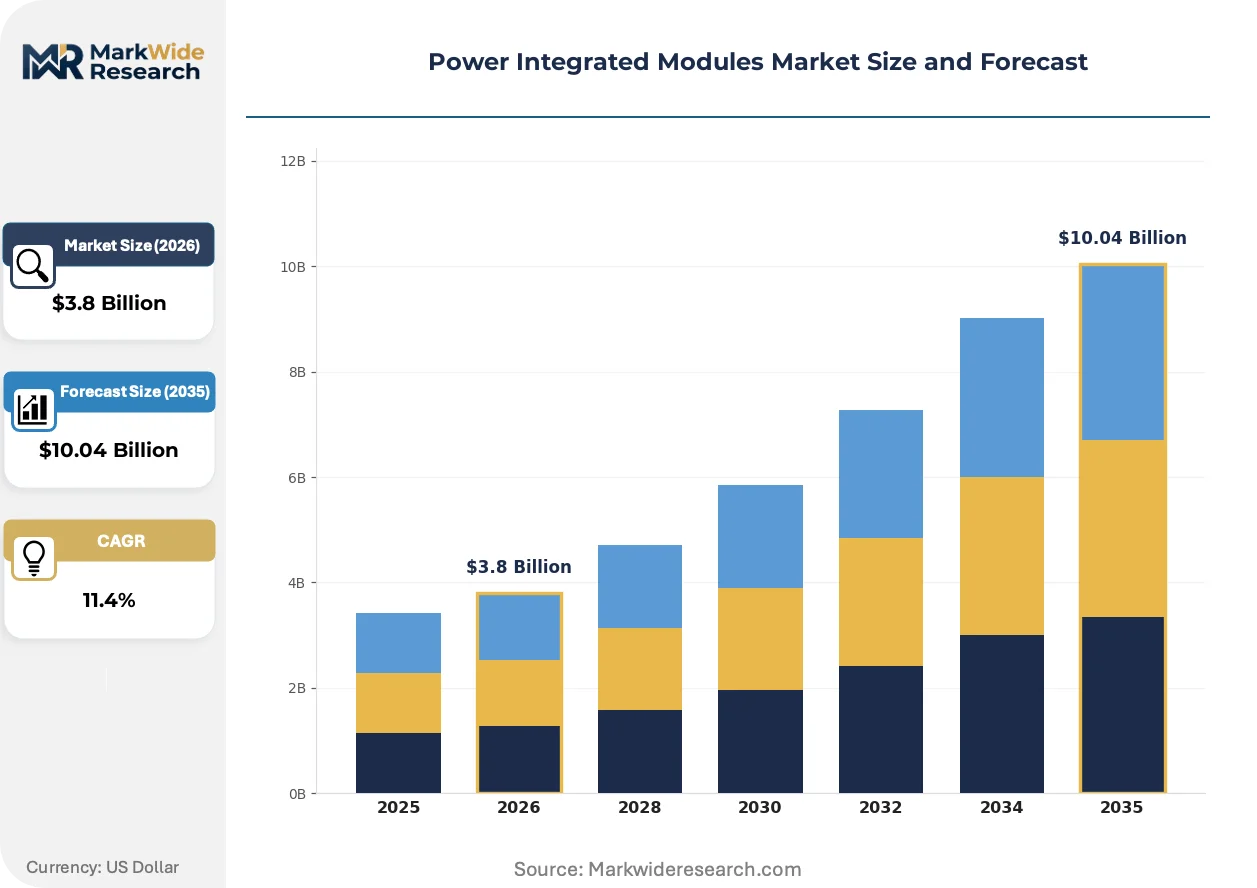
Market Dynamics
Silicon carbide substrate transitions are compressing design cycles across automotive inverter programs while fragmenting supplier qualification pathways. Tier-1 module manufacturers face simultaneous pressure to scale 1700V MOSFET architectures and defend silicon IGBT positions in industrial motor drives.
Growth Catalysts
- China GB Standards for EV Power Electronics:Mandatory efficiency thresholds for electric vehicle inverters accelerate wide-bandgap semiconductor adoption across domestic OEM supply chains.
- Aluminum Nitride Ceramic Substrates:Advanced thermal management materials enable junction temperatures exceeding 175°C, unlocking higher power density in three-phase motor drive modules.
- Renewable Energy Converter Buildouts:Utility-scale solar and wind installations in Germany, India, and Brazil generate concentrated demand for 1200V and 1700V switching modules.
Market Restraints
- Silicon Carbide Wafer Supply Concentration:Captive substrate production by integrated device manufacturers limits external supply availability for fabless module specialists.
- Silver Sintering Material Costs:Precious metal price volatility in die-attach processes compresses gross margins for high-reliability automotive programs.
- IGBT-to-SiC Conversion Capex Burden:Front-end manufacturing equipment for wide-bandgap devices requires substantially higher capital intensity than silicon legacy lines.
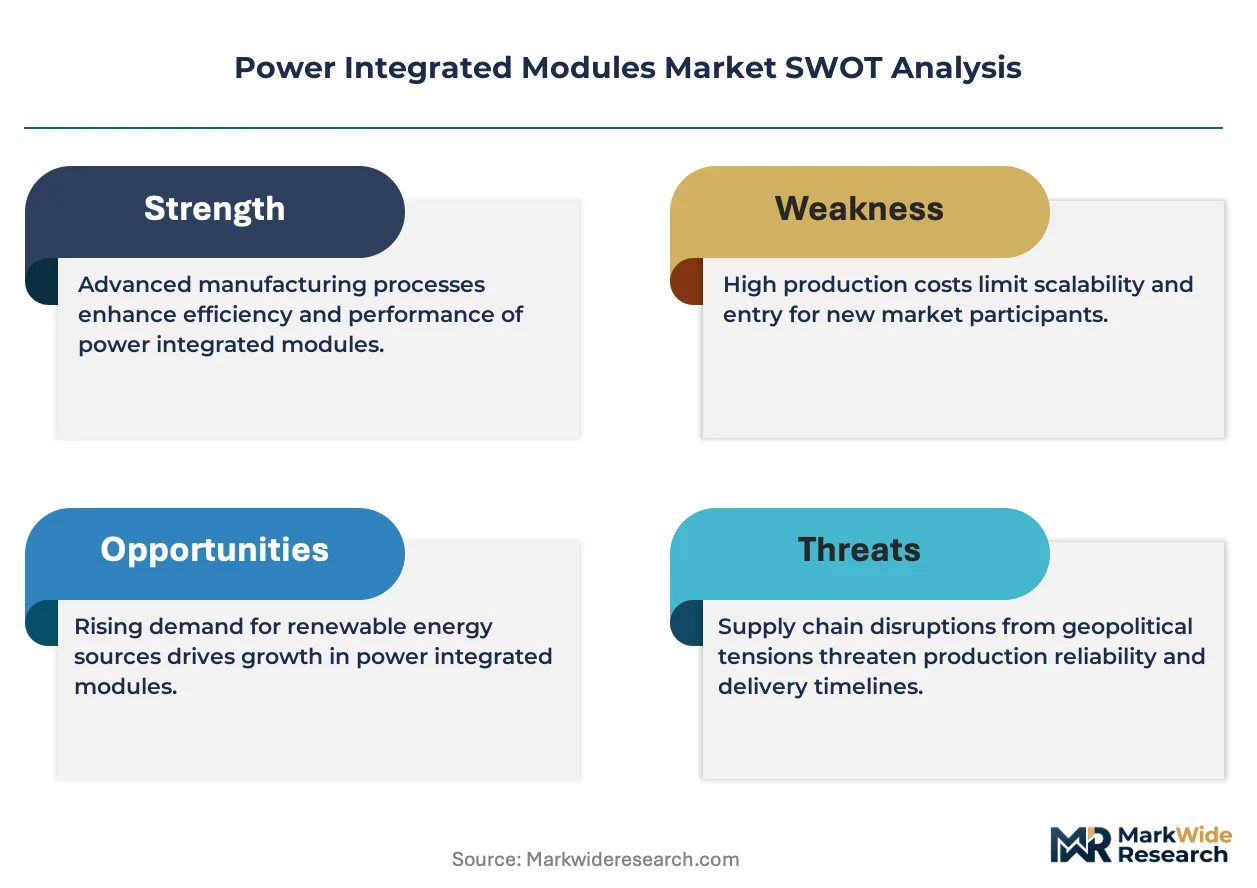
Strategic Opportunities
- India Industrial Motor Drive Modernization:BIS efficiency regulations and PLI scheme incentives create import substitution potential for intelligent power modules with integrated gate drivers.
- Predictive Maintenance Service Attach:Sensor-embedded modules enabling thermal cycling monitoring unlock recurring revenue streams from aftermarket thermal management.
- GaN-on-Silicon Process Convergence:Mature 650V platforms from consumer adapter applications migrate into appliance motor control and low-voltage industrial drives.
Industry Challenges
- Power Electronics Packaging Engineering Talent:Shortage of specialists in direct bonded copper design and thermomechanical simulation extends product development timelines.
- Multi-Jurisdictional Certification Complexity:Divergent efficiency test methodologies between EPA industrial frameworks and EU Ecodesign Directive create distinct qualification pathways for single product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Integrated Modules Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, DC-DC Converters, Power Supplies End User: Consumer Electronics, Automotive, Industrial Equipment, Renewable Energy Technology: Silicon-based, GaN, SiC, Hybrid Application: Telecommunications, Datacenters, UPS, Automotive Powertrains |
| Companies Covered | Infineon Technologies AG, Mitsubishi Electric Corporation, ON Semiconductor Corporation, Texas Instruments Incorporated, STMicroelectronics, Fuji Electric Co., Ltd., Semikron Danfoss GmbH & Co. KG, NXP Semiconductors, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Integrated Modules Market Evolving Landscape
Module architectures are converging toward intelligent, sensor-integrated platforms that bridge power conversion and digital control functions. Three interconnected developments are compressing traditional supplier boundaries.
Embedded temperature and current sensing is digitizing real-time junction monitoring, enabling condition-based maintenance contracts previously impossible with passive discrete designs. Automotive inverter programs at Volkswagen, BYD, and Stellantis now specify digital telemetry as standard, forcing analog-only suppliers to rearchitect gate driver integration.
The EU Ecodesign Directive for industrial equipment tightens minimum efficiency thresholds that favor wide-bandgap adoption over silicon IGBTs in motor drives above 750W. German industrial OEMs including Siemens and Bosch Rexroth are accelerating SiC module qualification to meet 2026 compliance deadlines, compressing supplier validation windows.
Buyer consolidation among automotive OEMs is concentrating procurement leverage with tier-1 inverter manufacturers, squeezing module supplier margins and forcing direct technical engagement with vehicle platform teams. This pattern is most visible in China, where CATL and BYD's vertical integration into powertrain assembly reshapes traditional distribution through component distributors.
Power Integrated Modules Market Segmentation
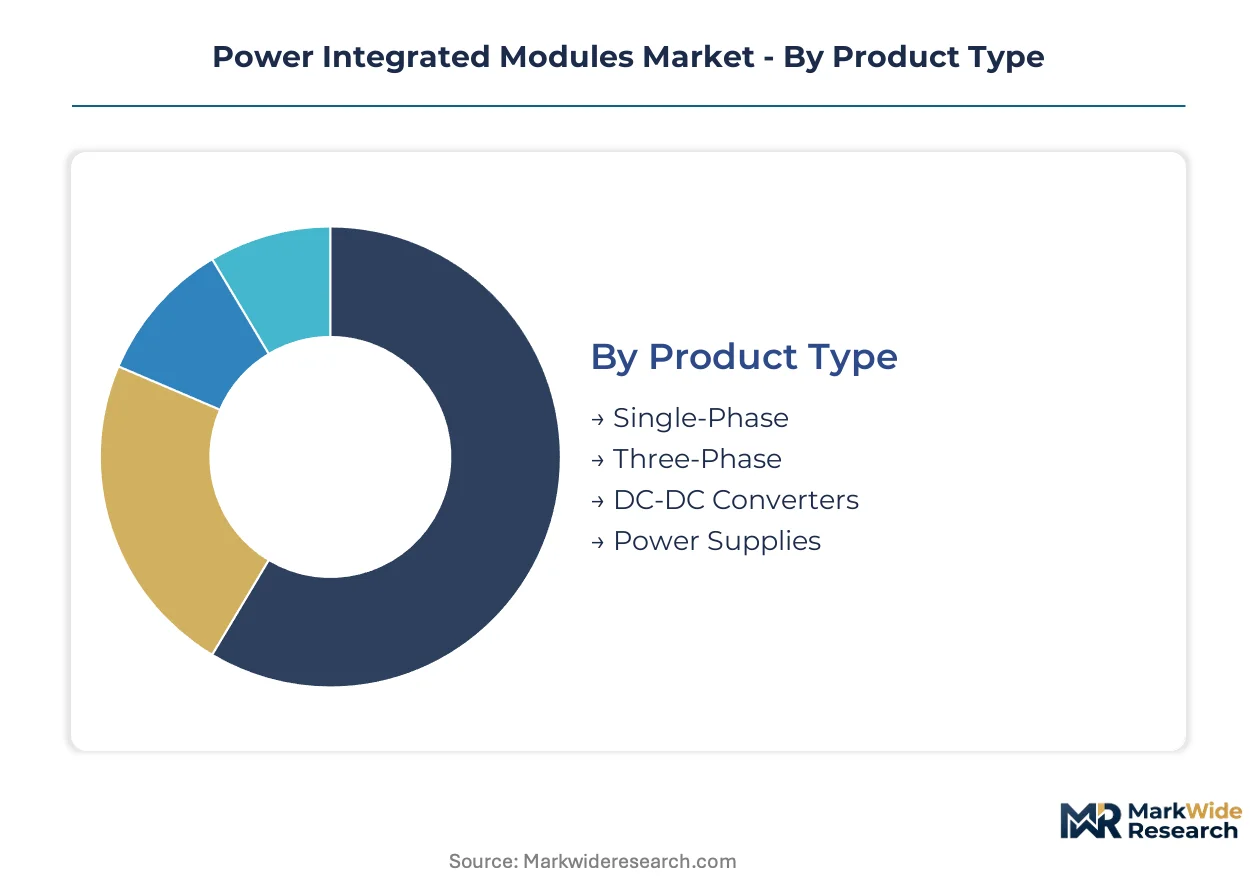
Power integrated modules serve heterogeneous energy conversion requirements across voltage classes, thermal envelopes, and switching frequencies. Segmentation reveals how substrate materials, phase architectures, and end-use specifications create distinct procurement criteria and supplier qualification pathways.
Product Type:
Mature industrial motor drive applications coexist with emerging electric vehicle inverter platforms, creating divergent packaging and thermal management specifications.
- Single-Phase:Compact modules integrating one or more power switches with gate drivers for residential appliance motor control and low-power HVAC compressors. Demand concentrates in India and Southeast Asia where BIS efficiency regulations and domestic manufacturing incentives elevate module specifications for washing machines and refrigerator compressors.
- Three-Phase:Multi-die assemblies with six-switch bridge configurations rated from kilowatts to megawatts for industrial motor drives and grid-tied inverters. Siemens, ABB, and Yaskawa procurement programs in Germany and Japan absorb the largest production volumes, driven by EU Ecodesign Directive compliance deadlines and METI industrial efficiency frameworks.
- DC-DC Converters:Buck and boost architectures for battery management systems and auxiliary power networks in electric vehicles.
- Power Supplies:Front-end PFC and LLC resonant stages for server racks and telecommunications infrastructure.
Three-phase modules handle the majority of throughput; DC-DC converters are climbing the fastest on share as 800V automotive architectures proliferate.
End User:
Cost tier stratification separates high-volume consumer applications from premium automotive and industrial programs with extended qualification cycles.
- Consumer Electronics:Low-voltage intelligent power modules for smartphone chargers, laptop adapters, and white goods motor control. GaN-on-silicon platforms from 65W to 240W dominate procurement conversations with Foxconn, Delta, and Salcomp manufacturing complexes in China and Vietnam.
- Automotive:Traction inverters, onboard chargers, and DC-DC stages requiring AEC-Q101 qualification and functional safety certification. BYD, Tesla, and Volkswagen inverter programs specify 1200V SiC modules with junction temperatures exceeding 175°C, compressing supplier validation timelines.
- Industrial Equipment:Variable frequency drives, servo systems, and welding power supplies rated for harsh thermal cycling.
- Renewable Energy:String inverters, central inverters, and energy storage power conversion systems.
Automotive commands the steepest price premiums per watt; renewable energy is expanding most quickly on installed capacity.
Technology:
Silicon carbide substrate availability and silver sintering process maturation are fragmenting competitive positioning between incumbent silicon suppliers and wide-bandgap specialists.
- Silicon-based:Trench-field-stop IGBTs and superjunction MOSFETs in standard packages for cost-sensitive industrial drives. Infineon's Dresden complex and Mitsubishi's Fukuoka fab sustain cost leadership through 300mm wafer scale and captive substrate supply.
- GaN:High-electron-mobility transistors on silicon substrates for sub-650V applications with switching frequencies above 100kHz. Navitas, GaN Systems, and Innoscience compete for socket opportunities in 65W-240W adapter programs and appliance motor drives.
- SiC:Vertical MOSFETs on 4H-SiC substrates for 650V-1700V traction inverters and renewable energy converters.
- Hybrid:Asymmetric configurations combining silicon IGBTs with SiC diodes or GaN HEMTs for cost-performance optimization.
Silicon-based modules retain the largest installed base; SiC is gaining share fastest as 1700V platforms qualify for heavy-duty commercial vehicles.
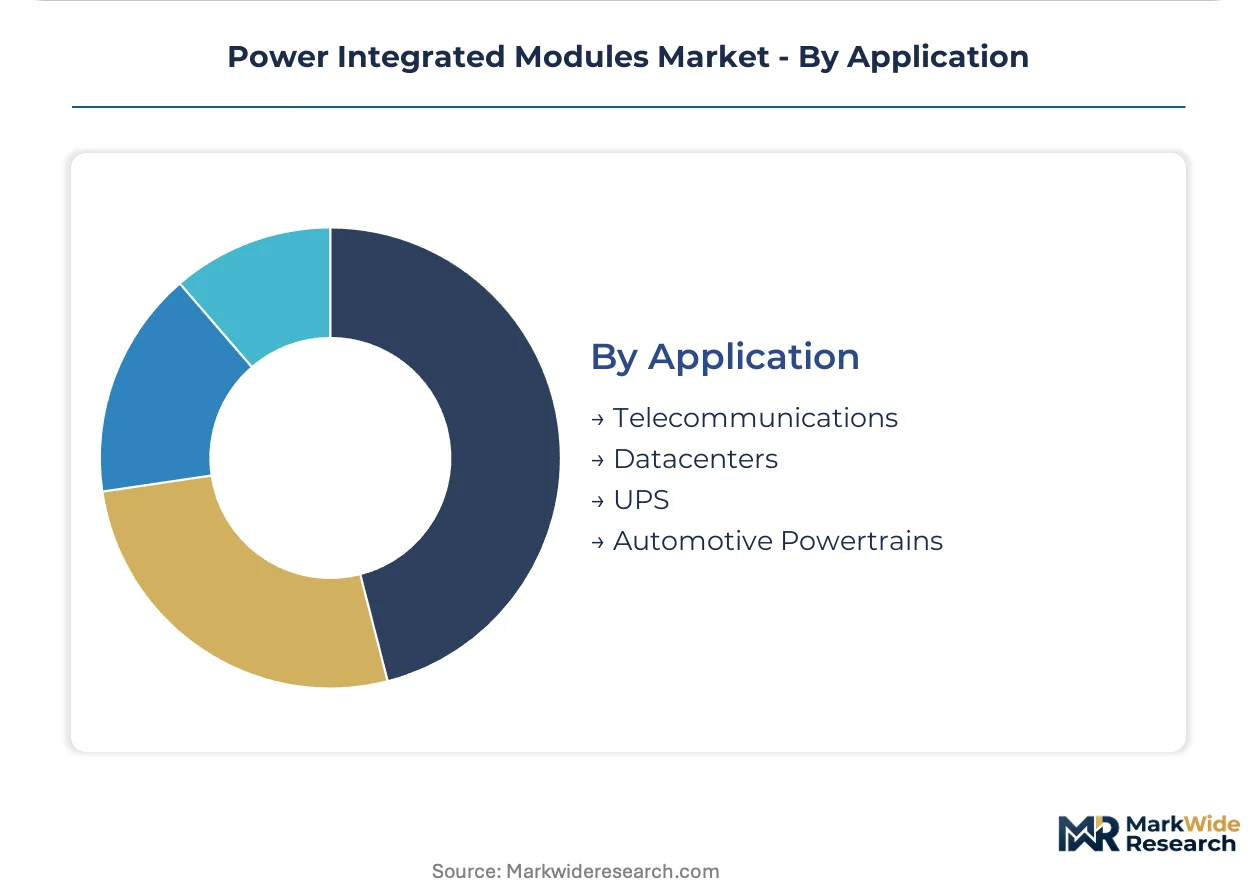
Application:
Geography determines procurement concentration, with China's datacenter buildouts and Germany's automotive engineering centers anchoring distinct demand clusters.
- Telecommunications:Rectifier modules and DC-DC stages for 5G base stations and central office power plants. Huawei, ZTE, and Ericsson procurement specifications in China and Sweden mandate 98% efficiency thresholds that favor GaN and SiC adoption.
- Datacenters:48V direct-conversion and intermediate bus architectures for hyperscale server farms. Google, Microsoft, and Alibaba facility expansions in Iowa, Virginia, and Zhangjiakou drive concentrated demand for 3kW-10kW power shelf modules.
- UPS:Three-phase online double-conversion systems for enterprise and industrial backup power.
- Automotive Powertrains:Main inverters, boost converters, and auxiliary power modules for battery electric and hybrid vehicles.
Datacenter applications absorb the highest power density modules; automotive powertrains show the steepest expansion trajectory as 800V platforms reach mass production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity for single-phase appliance modules, while German and Japanese industrial OEMs absorb substantial premiums for three-phase systems with extended thermal cycling warranties.
China
Domestic inverter and charging infrastructure buildouts consume the largest volume of advanced power modules globally. GB standards for electric vehicle power electronics mandate minimum efficiency thresholds that accelerate wide-bandgap semiconductor adoption across BYD and CATL supply chains. Shenzhen and Shanghai manufacturing clusters host concentrated module assembly operations serving both domestic OEMs and export programs.
Germany
Siemens, ABB, and Bosch Rexroth procurement programs absorb the largest European production volumes for industrial motor drives. The EU Ecodesign Directive tightens minimum efficiency thresholds for equipment above 750W, compressing supplier validation windows for SiC module qualification. Bavaria's engineering centers anchor automotive inverter development for Volkswagen Group platforms.
United States
EPA industrial emissions frameworks and Department of Energy appliance efficiency standards elevate demand for higher-efficiency module architectures. Google, Microsoft, and Amazon facility expansions in Iowa and Virginia drive concentrated procurement of 3kW-10kW power shelf modules for datacenter infrastructure. Detroit-area automotive engineering operations specify 1200V SiC modules for 800V traction inverter programs.
Japan
METI industrial efficiency frameworks sustain premium pricing for three-phase modules with extended reliability certifications. Mitsubishi Electric and Yaskawa procurement programs dominate domestic absorption for variable frequency drives and servo systems. Fukuoka and Nagoya manufacturing clusters concentrate captive silicon carbide substrate production and advanced packaging operations.
India
BIS efficiency regulations and PLI scheme incentives create import substitution potential for intelligent power modules with integrated gate drivers. Washing machine and refrigerator compressor manufacturers in Gujarat and Maharashtra elevate module specifications to meet domestic content requirements. Chennai and Bangalore industrial corridors attract module assembly investments targeting appliance motor control applications.
Power Integrated Modules Market Competitive Landscape
Integrated device manufacturers and fabless module specialists split the market along substrate access lines. Concentration is pronounced at the wide-bandgap tier where captive silicon carbide wafer production limits external supply availability. Three strategic archetypes dominate: vertically integrated semiconductor conglomerates with internal substrate supply, fabless module specialists dependent on external wafer procurement, and industrial conglomerates with captive power electronics divisions. Capacity expansion in 1700V SiC platforms and strategic partnerships for silver sintering process development represent the dominant competitive vectors.
Among European integrated device manufacturers, Infineon Technologies AG and STMicroelectronics exemplify the vertically integrated archetype through sustained cost leadership in silicon-based modules and captive substrate development. Mitsubishi Electric Corporation anchors the Asia-Pacific tier with internal silicon carbide wafer production reducing dependency on external suppliers. ON Semiconductor Corporation occupies a position within the fabless-specialist tier, concentrating procurement qualification pathways for intelligent power modules with integrated gate driver functionality.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Mitsubishi Electric Corporation |
| ON Semiconductor Corporation |
| Texas Instruments Incorporated |
| STMicroelectronics |
| Fuji Electric Co., Ltd. |
| Semikron Danfoss GmbH & Co. KG |
| NXP Semiconductors |
| Renesas Electronics Corporation |
| Others |
Value Network & Pricing Analysis
Silver sintering material volatility compresses gross margins for automotive programs while simultaneously fragmenting supplier tiers across silicon IGBT and wide-bandgap module categories. This input cost instability widens pricing spreads between premium AEC-Q101 qualified platforms and economy-grade industrial drives, concentrating procurement leverage with buyers who can absorb precious metal exposure through long-term offtake contracts.
Pricing Analysis
Predictive maintenance service contracts now drive lifetime value capture across intelligent power module portfolios. Three-tier pricing structure across premium, standard, and economy levels separates automotive inverter platforms with embedded telemetry from commodity three-phase motor drives. Cost compression in silicon-based IGBT segments is intensifying because Chinese domestic suppliers are scaling 300mm wafer production. Appliance motor control manufacturers in India exhibit acute price sensitivity, while German industrial OEMs absorb substantial premiums for extended thermal cycling warranties.
Supply Chain Analysis
Export-control restrictions on silicon carbide substrate equipment limit technology transfer to emerging manufacturing hubs. Captive wafer production concentrates in Japan, Germany, and the United States, while module assembly clusters in China and Southeast Asia draw from external substrate supply. Silver paste, aluminum nitride ceramics, and direct bonded copper substrates constitute critical input dependencies. Single-source vulnerability runs through Wolfspeed and Coherent substrate allocations for fabless module specialists. Distribution runs through Tier 1 inverter manufacturers who consolidate procurement leverage with automotive OEM platform teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power integrated modules sit in early-cycle expansion as 800V automotive architectures and renewable energy converter buildouts accelerate wide-bandgap penetration beyond legacy silicon strongholds.
For Market Incumbents: Entrench cost leadership in silicon-based IGBT modules through captive 300mm wafer scale at Dresden and Kulim manufacturing complexes. Deepen backward integration into silicon carbide substrate production to reduce dependency on external wafer suppliers. Defend against GaN-on-silicon displacement in sub-650V appliance motor control by accelerating intelligent power module qualification with integrated gate drivers.
For New Entrants and Emerging Players: Establish a beachhead in India's industrial motor drive modernization under BIS efficiency regulations and PLI scheme incentives. Target white-space opportunities in sensor-embedded modules enabling predictive maintenance contracts for aftermarket thermal management. Pursue qualification partnerships with Gujarat and Maharashtra washing machine compressor manufacturers seeking import substitution.
For Investors and Strategic Acquirers: Fabless module specialists with silver sintering process expertise and automotive qualification pathways represent attractive acquisition targets. Long-term viability hinges on substrate access security across the next decade. Watch for inflection when captive silicon carbide wafer producers begin external supply allocation to non-captive module manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Carbide Substrate Development | Reduces dependency on Wolfspeed and Coherent allocations for automotive inverter programs. |
| Silver Sintering Process Maturation | Enables junction temperatures exceeding 175°C for AEC-Q101 qualified traction modules. |
| Intelligent Power Module Integration | Combines gate drivers and telemetry for condition-based maintenance contracts. |
| India Manufacturing Footprint Expansion | Captures PLI scheme incentives for appliance motor control under BIS efficiency regulations. |
| GaN-on-Silicon Platform Migration | Extends mature 650V consumer adapter technology into industrial drives above 750W. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with power module procurement directors, inverter platform engineers, and thermal management specialists; and secondary validation against SEC filings from Infineon and ON Semiconductor, customs records for silicon carbide substrate trade flows, and EPA industrial emissions framework documentation. Bottom-up triangulation across voltage class, phase architecture, substrate material, and end-use qualification tier anchored volume estimates. Top-down cross-checks against automotive inverter production schedules and renewable energy installation databases validated segment splits.
Forecast inputs considered technology substitution curves from silicon IGBT to SiC MOSFET across the projection horizon, regulatory compliance deadlines under EU Ecodesign Directive and China GB standards, and capital expenditure cycles for wide-bandgap front-end equipment. Modeled dimensions span voltage rating, phase configuration, semiconductor technology, and regional manufacturing cluster. CAGRs were derived from segment-level adoption curves weighted by automotive platform ramp schedules and industrial efficiency mandate timelines. Silver price volatility and substrate supply allocation constraints fed into scenario-based sensitivity bands.
Sensitivities concentrate around silicon carbide wafer supply availability, precious metal cost trajectories, and regulatory divergence between EPA industrial frameworks and EU Ecodesign Directive test methodologies. Forecasts reflect documented assumptions on technology transition rates and qualification timeline compression. Material shifts in export-control restrictions on substrate manufacturing equipment or abrupt silver market dislocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Central Battery Systems Market
Power Systems
Synchrophasors Market
Power Systems
Charge Pumps Market
Power Systems
AC DC Power Adapter Market
Power Systems
Global Synchronous Motor Market
Power Systems
Charge Controller System Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
BCD Power IC Market
Power Systems
Power Diode Market
Power Systems
Smart Power Strips Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Integrated UPS Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Europe Shunt Reactors Market
Power Systems
North America Electric Vehicle Power Inverter Market