
 Global Atomic Layer Deposition (ALD) Equipment Market | 2026-2036
Global Atomic Layer Deposition (ALD) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Atomic Layer Deposition (ALD) Equipment Market Intelligence
Procurement from leading-edge chip makers is rotating away from more mature applications like solar cell production and basic MEMS. This shift favors suppliers with advanced technology roadmaps. ASM International NV leverages its strong position in single-wafer ALD systems for logic and memory. Tokyo Electron Limited specializes in high-productivity batch ALD solutions, while Lam Research Corporation competes with advanced plasma-enhanced ALD technologies for critical etch and deposition steps.
Atomic layer deposition equipment facilitates a thin-film deposition process using sequential, self-limiting chemical reactions with gaseous precursors. These systems are engineered to deposit material one atomic layer at a time, enabling ultrathin, highly conformal, and pinhole-free films. Within product types, Plasma-Enhanced ALD Equipment gains share for low-temperature processing on sensitive substrates. The semiconductor fabrication application overwhelmingly dominates equipment investment, particularly for advanced memory and logic device manufacturing.
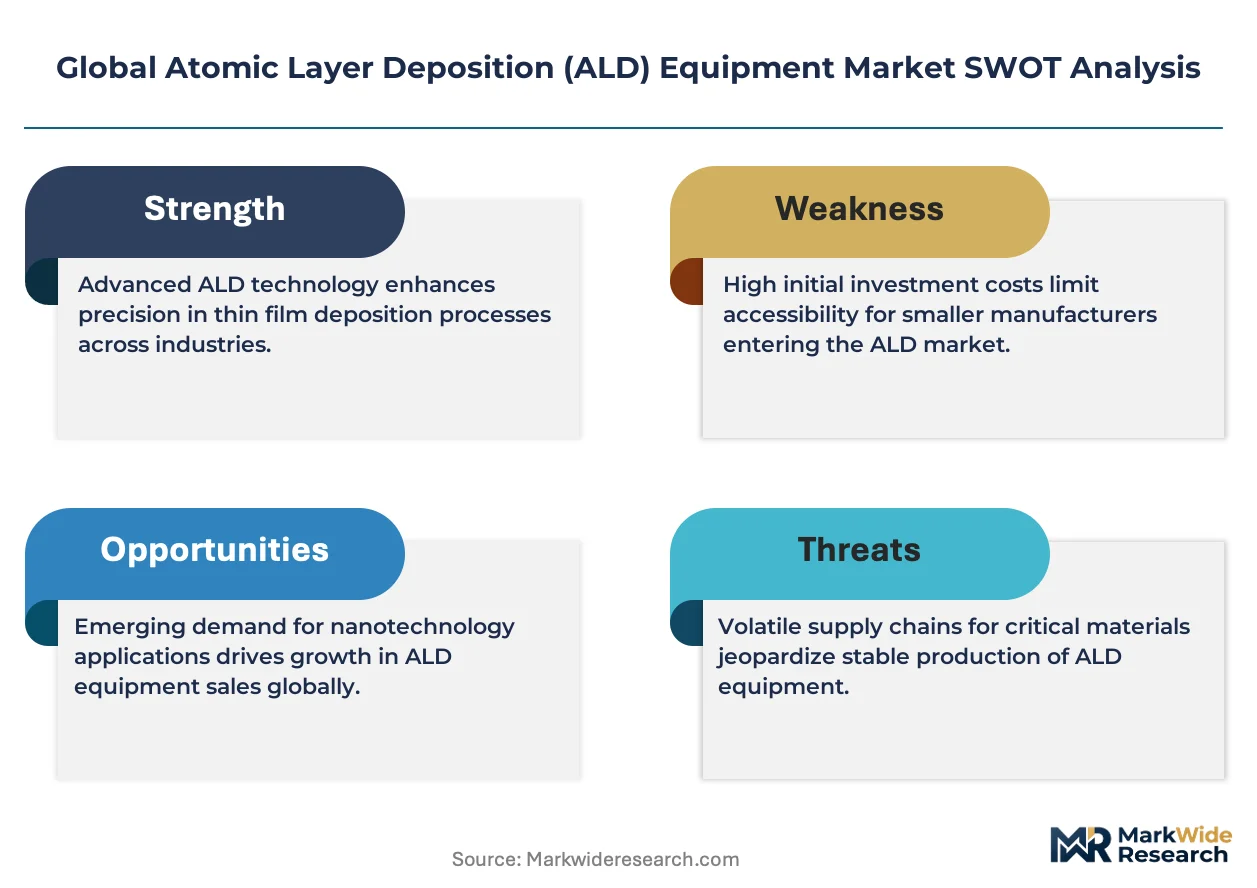
Equipment and material suppliers must comply with chemical regulations like the EU's REACH directive for precursor safety and registration. Concurrently, standards such as RoHS and various ISO quality management certifications govern the end-use electronics and semiconductor products, influencing material selection. Future profitability will depend on securing precursor supply chains and aligning R&D with the next node in semiconductor process technology.
Market Dynamics
The semiconductor industry's transition to three-dimensional transistor architectures, particularly Gate-All-Around (GAA) structures, is the central force shaping the Atomic Layer Deposition Equipment market. This architectural shift makes the atomic-scale precision of ALD a necessity, not an option.
Growth Catalysts
- Gate-All-Around (GAA) Adoption:The migration by leading logic manufacturers to GAA transistors for sub-3nm nodes fundamentally requires the conformal, uniform thin films that only ALD can provide for channel and gate dielectric formation.
- Memory Device Scaling:Continued scaling of 3D NAND and DRAM, especially High-Bandwidth Memory (HBM), relies on ALD for depositing high-k dielectrics and barrier layers deep within high-aspect-ratio structures, ensuring device performance and reliability.
- Advanced Packaging:The use of ALD is expanding into advanced packaging applications, where its ability to deposit conformal barrier and seed layers on complex topographies is critical for creating reliable interconnects in chiplet-based designs.
Market Restraints
- High Equipment Cost:The initial capital outlay for advanced ALD systems is significantly higher than for conventional deposition tools like CVD, posing a barrier for manufacturers in more cost-sensitive segments like MEMS or analog devices.
- Precursor Supply Chain:The market depends on a concentrated supply of high-purity, often proprietary, precursor chemicals. This creates risks related to cost volatility, supply disruption, and single-sourcing for specific advanced materials.
- Low Throughput:The sequential, self-limiting nature of the ALD process results in inherently low deposition rates, making it less economically viable for applications requiring thick films or where high-volume throughput is the primary concern.
Strategic Opportunities
- Emerging Geographies:National semiconductor initiatives, such as the CHIPS Acts in the United States and the European Union, are creating new geographic markets for advanced equipment as they seek to build domestic fabrication capabilities.
- Medical Device Coatings:There is a nascent opportunity in applying ALD for biocompatible and hermetic coatings on medical implants and diagnostic tools, where ultrathin, pinhole-free layers enhance device longevity and patient safety.
- Spatial ALD Development:Innovations in spatial ALD and roll-to-roll systems that separate precursors in space rather than time offer a pathway to higher throughput, potentially unlocking applications in flexible electronics, batteries, and solar cells.
Industry Challenges
- Process Integration Complexity:Integrating new ALD steps and materials into established, multi-hundred-step semiconductor manufacturing flows without impacting yield or interacting negatively with other processes is a major technical hurdle for process engineers.
- Specialized Talent Scarcity:A shortage of engineers and technicians with deep expertise in ALD process chemistry, plasma physics, and equipment maintenance creates operational bottlenecks for fabs scaling up advanced nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Atomic Layer Deposition (ALD) Equipment Market |
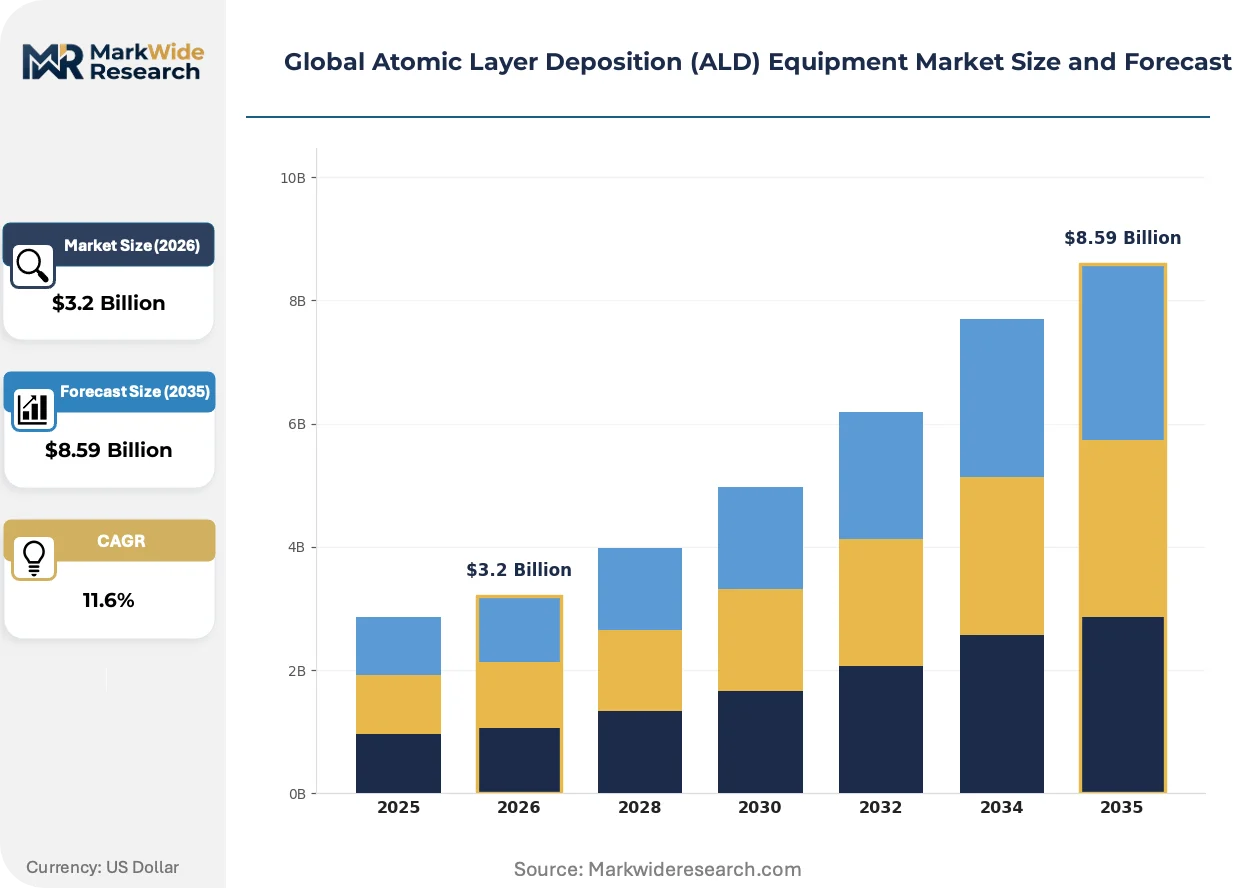
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $8.59 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch ALD Systems, Spatial ALD Tools, Plasma-Enhanced ALD Equipment, Thermal ALD Machines, Rotary ALD Instruments Technology: Pulsed Vapor Deposition, Plasma Activation, Thermal Process, Remote Plasma, Radical-Enhanced Deposition Application: Semiconductor Fabrication, Optical Coatings, Solar Module Manufacturing, Display Panel Production, Microelectromechanical Systems End User: Chip Makers, Solar Cell Producers, Electronics Manufacturers, MEMS Developers, Coating Service Providers |
| Companies Covered | ASM International NV, Veeco Instruments Inc, Applied Materials, Inc., CVD Equipment Corporation, Beneq Oy, Lam Research Corporation, Aixtron SE, Entegris Inc., Tokyo Electron Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Atomic Layer Deposition (ALD) Equipment Market Strategic Shifts & Innovations
Equipment innovation is focused on enhancing throughput and expanding the process window for temperature-sensitive substrates. The evolution toward batch and spatial ALD systems aims to broaden the technology's economic viability beyond the most critical, leading-edge device layers.
Plasma-Enhanced ALD (PE-ALD) utilizes an energy source to activate precursor molecules, enabling film deposition at significantly lower temperatures than conventional thermal processes. This technology is rapidly being adopted by manufacturers of flexible electronics and advanced memory devices that cannot withstand high thermal budgets. This low-temperature capability is displacing thermal ALD for critical layers on temperature-sensitive substrates and in multi-layer stacks.
Compliance with chemical safety regulations like the European Union's REACH directive is a major consideration for market participants. The directive mandates stringent registration and safety data for all chemical substances, including the novel organometallic precursors used in ALD. This forces equipment and material suppliers to invest in extensive testing and documentation, sometimes limiting the palette of available chemistries in the EU market.
Collaborative research and development partnerships between chipmakers and equipment vendors are replacing traditional transactional sales models. This shift involves establishing joint development centers to co-optimize ALD tools and process recipes for specific, next-generation device applications. The trend is most visible in Taiwan and South Korea, where logic and memory giants work directly with suppliers to solve integration challenges for future process nodes.
Global Atomic Layer Deposition (ALD) Equipment Market Segmentation
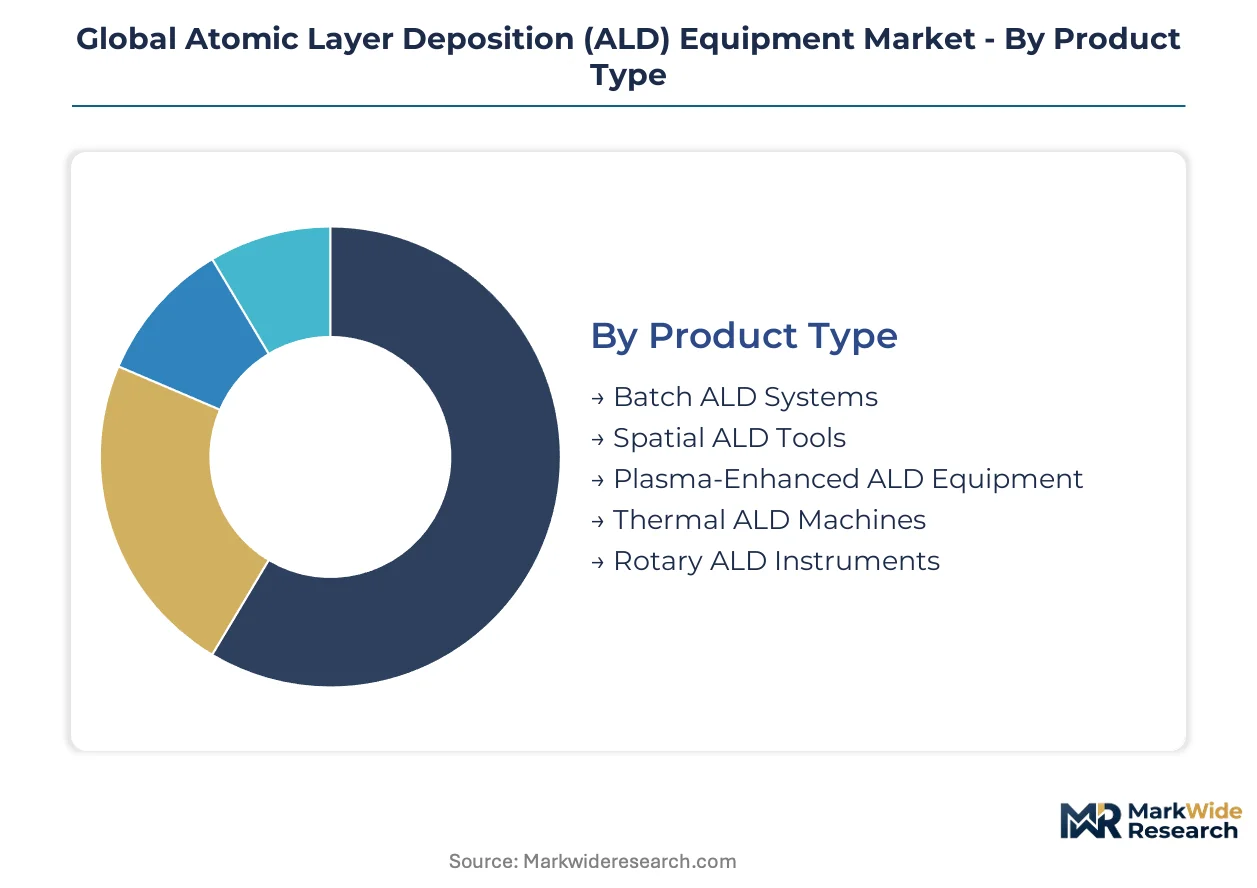
Understanding the Global Atomic Layer Deposition (ALD) Equipment Market through its segmentation reveals the specialized demands driving innovation. This detailed breakdown highlights distinct technological preferences, application priorities, and end-user requirements across the industry. Analyzing these segments provides clarity on where investment and development efforts are concentrated for future growth.
Product Type:
The product type segmentation differentiates ALD systems by their operational mechanisms and throughput capabilities, with some designs optimized for domestic high-volume manufacturing and others for export-led advanced research facilities.
- Plasma-Enhanced ALD Equipment:These systems utilize plasma to activate precursor molecules, enabling film deposition at significantly lower temperatures. Demand concentrates in advanced semiconductor fabrication clusters in South Korea and Taiwan for sensitive substrates.
- Batch ALD Systems:Designed for high-volume production, these tools process multiple wafers simultaneously within a single chamber, optimizing throughput. Leading-edge chip makers in Taiwan and the United States adopt batch solutions for cost-effective scaling.
- Spatial ALD Tools:These systems separate precursor introduction in space rather than time, offering potential for higher throughput.
- Thermal ALD Machines:Relying on thermal energy for precursor activation, these are traditional ALD systems for high-quality, conformal films.
- Rotary ALD Instruments:Featuring rotating substrates, these tools aim to improve film uniformity and increase throughput for specific applications.
Plasma-Enhanced ALD Equipment holds the largest share; momentum sits with Spatial ALD Tools.
Technology:
Different ALD technologies cater to specific application requirements, ranging from ultra-low temperature processing to achieving exceptional film density in critical device layers.
- Plasma Activation:This technology employs plasma to energize precursor chemicals, facilitating deposition at reduced thermal budgets critical for temperature-sensitive substrates. It is essential for manufacturing advanced logic and memory devices.
- Thermal Process:Relying purely on heat for chemical reactions, this foundational ALD method produces highly conformal and dense films. Thermal ALD remains crucial for stable dielectric layers in established semiconductor nodes.
- Pulsed Vapor Deposition:This technique involves sequential pulsing of precursor vapors, ensuring self-limiting reactions for precise film growth.
- Remote Plasma:Generating plasma away from the substrate minimizes ion bombardment damage, preserving sensitive device architectures.
- Radical-Enhanced Deposition:This method utilizes reactive radicals to drive ALD reactions, offering precise control over film properties at lower temperatures.
Plasma Activation accounts for the majority of installations, while Radical-Enhanced Deposition is expanding most quickly.
Application:
The market's application landscape is shaped by diverse customer types, each requiring ALD equipment tailored for specific material properties and manufacturing scales.
- Semiconductor Fabrication:This segment represents the largest investment area, driven by demand for ultrathin, conformal films in advanced logic and memory chips. ALD is indispensable for Gate-All-Around (GAA) transistors and 3D NAND structures.
- Display Panel Production:ALD is used for depositing barrier layers and TFT dielectrics in advanced OLED and flexible display manufacturing. This application demands high uniformity and low-temperature processing.
- Optical Coatings:ALD creates precise, multi-layered optical films for lenses, mirrors, and sensors, enhancing performance and durability.
- Solar Module Manufacturing:ALD applies passivation layers and transparent conductive oxides to improve efficiency and longevity of photovoltaic cells.
- Microelectromechanical Systems:ALD provides conformal coatings for MEMS devices, offering protection and functionalization for miniature sensors and actuators.
Investment remains concentrated in Semiconductor Fabrication, with Display Panel Production showing significant future potential.
End User:
The maturity of end-user industries significantly influences their ALD equipment procurement strategies, with established sectors prioritizing proven reliability and emerging areas seeking innovative solutions.
- Chip Makers:These entities represent the primary end-users, investing heavily in advanced ALD systems for manufacturing leading-edge logic and memory chips. Their procurement focuses on precision single-wafer and high-throughput batch tools.
- Electronics Manufacturers:This broad category includes companies producing various electronic components, where ALD is used for barrier layers, encapsulation, and dielectric films. Demand spans consumer electronics to specialized industrial devices.
- Solar Cell Producers:These manufacturers use ALD for passivation and anti-reflection coatings to enhance solar cell efficiency and durability.
- MEMS Developers:Companies designing and producing microelectromechanical systems utilize ALD for conformal and protective coatings on intricate 3D structures.
- Coating Service Providers:These firms offer ALD coating services to multiple industries, providing specialized film deposition without requiring clients to invest in their own equipment.
The largest share of ALD equipment procurement comes from Chip Makers, while Coating Service Providers are steadily increasing their adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global trade flows of advanced ALD equipment primarily originate from established technology hubs, supplying critical systems to burgeoning semiconductor manufacturing centers. This dynamic supports the intricate supply chains required for next-generation chip production. Key equipment exports move towards regions with significant investment in advanced logic and memory fabrication.
Taiwan
Demand for ALD equipment in Taiwan stems from its robust semiconductor industry and aggressive node migration. The Taiwan Semiconductor Manufacturing Company (TSMC) heavily invests in ALD for Gate-All-Around (GAA) structures. Hsinchu Science Park remains a crucial hub for advanced chip manufacturing, driving significant ALD procurement.
South Korea
South Korea's memory and logic chip manufacturers drive substantial ALD equipment demand for high-bandwidth memory (HBM) and 3D NAND scaling. National initiatives support domestic semiconductor capabilities, encouraging advanced equipment adoption. The Gyeonggi Province, home to Samsung and SK Hynix, concentrates ALD investment.
United States
The United States sees ALD equipment demand from its resurgent domestic semiconductor manufacturing and advanced R&D efforts. The CHIPS and Science Act provides incentives for new fabrication plants, boosting equipment procurement. Arizona and New York are emerging as critical centers for advanced logic production.
Germany
European demand for ALD systems, particularly Plasma-Enhanced ALD, supports specialized applications in MEMS and advanced packaging. The EU's REACH directive influences precursor chemical selection and equipment design. Dresden's Silicon Saxony cluster remains a focal point for semiconductor and microelectronics innovation.
Global Atomic Layer Deposition (ALD) Equipment Market Key Industry Players
Player mix skews toward a concentrated group of technology leaders specializing in advanced deposition solutions for semiconductors. The market structure exhibits a tiered consolidation, with a few dominant players at the high-end and several niche specialists. Strategic archetypes include integrated equipment providers, plasma technology innovators, and batch processing specialists. Dominant competitive moves involve strategic partnerships with chipmakers and continuous technology roadmap development.
Specialists in advanced ALD technologies include ASM International NV, a Netherlands-based company known for its single-wafer systems. Tokyo Electron Limited, a Japanese corporation, consistently advances high-productivity batch ALD solutions for high-volume manufacturing. Lam Research Corporation, an American entity, exemplifies innovation in plasma-enhanced ALD for critical etch and deposition steps. These companies anchor the market for cutting-edge ALD equipment, representing leaders in their respective technological niches.
| Leading Market Players |
|---|
| ASM International NV |
| Veeco Instruments Inc |
| Applied Materials, Inc. |
| CVD Equipment Corporation |
| Beneq Oy |
| Lam Research Corporation |
| Aixtron SE |
| Entegris Inc. |
| Tokyo Electron Limited |
| Others |
Cost & Logistics Intelligence
The EU's REACH directive gates the qualification of ALD precursor chemicals, directly influencing their supply availability and cost, which in turn differentiates equipment pricing based on material compliance. This regulatory framework significantly impacts the economic viability of certain ALD process chemistries.
Pricing Analysis
Next-generation ALD systems for sub-3nm nodes command premium pricing over prior-generation thermal ALD machines. Pricing operates on a contract-based long-term offtake model, where customization level and extensive after-sales service drive differentiation. Pricing softness reflects intense competition among equipment vendors for leading-edge customer contracts. MEMS or analog device manufacturers exhibit the highest price sensitivity, unlike advanced chipmakers.
Supply Chain Analysis
Strategic stockpiling of high-purity ALD precursor chemicals mitigates supply chain volatility for equipment manufacturers. Supply relies heavily on specialized chemical producers concentrated in specific regions for novel organometallic precursors and advanced components. Single-source vulnerability for proprietary advanced materials represents a significant supply chain risk. Distribution runs through direct sales channels and localized technical support teams from equipment vendors to chipmakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Atomic Layer Deposition Equipment market presents a defensive-moat story, driven by the high switching costs associated with integrating ALD tools into established semiconductor manufacturing flows. Co-optimization efforts further cement vendor relationships.
For Market Incumbents:
Compound existing relationships with leading-edge chipmakers through joint development centers to co-optimize process recipes. This strategy defends against emerging spatial ALD technologies from niche players. Further invest in next-generation precursor development, potentially through backward integration into specialized chemical production. Expanding localized technical support in new fabrication regions also reinforces market position.
For New Entrants and Emerging Players:
Specialized training and maintenance support for complex ALD systems represent a significant service-layer gap. Target nascent opportunities in medical device coatings or flexible electronics manufacturing, where incumbents are less entrenched. Focus on emerging geographies with national semiconductor initiatives, offering bundled equipment and process recipe packages. A strong go-to-market angle involves providing comprehensive turnkey solutions with robust localized technical expertise.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with smaller, specialized ALD technology developers, offering attractive acquisition opportunities. This market exhibits strong long-term viability over the next decade due to ALD's indispensability for advanced logic and memory. Target niche innovators specializing in spatial ALD or novel precursor synthesis. The successful integration of spatial ALD into high-volume manufacturing will serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Development Centers with Chipmakers | Co-optimizing ALD tools with logic and memory giants accelerates next-generation process node development. |
| Investment in Spatial ALD R&D | Developing higher-throughput spatial ALD systems unlocks applications in flexible electronics and advanced packaging. |
| Securing Precursor Supply Chains | Establishing long-term contracts for organometallic precursors mitigates supply disruption risks for equipment manufacturers. |
| Expansion into Emerging Geographies | Building domestic fabrication capabilities in the United States and Europe creates new markets for advanced ALD equipment. |
| Enhanced Plasma-Enhanced ALD Capabilities | Advancing PE-ALD for low-temperature processing supports the production of sensitive substrates in memory devices. |
Research Approach
A standing panel of process engineers, R&D directors, procurement managers, and equipment specialists provided ongoing calibration for market insights. This involved primary interviews combined with secondary validation from SEC filings, industry association reports, and patent databases. A rigorous bottom-up and top-down triangulation approach ensured data consistency. This dual methodology captured both granular detail and broad market trends.
Outputs were validated against external benchmarks, including historical equipment sales and semiconductor capital expenditure reports, ensuring forecast consistency. The analytical framework modeled key segmentation dimensions: product type, technology, application, end-user, and regional demand. Compound annual growth rates were derived using weighted averages of historical trends and projected future adoption rates. Semiconductor capital expenditure cycles and advanced node migration roadmaps served as critical forecast inputs across the analysis window.
Material uncertainties — including unforeseen geopolitical events or rapid technological breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding global trade policy stability and precursor supply chain continuity. Revision becomes warranted when significant disruptions in these areas cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Sputtering Equipment Cathode Market
Semiconductor Equipment
Global Semiconductor Coolers Market