
 Global Artificial Intelligence (AI) Defence Market | 2026-2036
Global Artificial Intelligence (AI) Defence Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence (AI) Defence Market Intelligence
The integration of edge computing with deep learning models is reconfiguring the development of autonomous defence systems. This shift enables faster, localized decision-making on the battlefield without constant reliance on central servers. Lockheed Martin Corporation leverages this capability for its advanced combat and reconnaissance systems. Palantir Technologies Inc. specializes in the software platforms that unify data from these distributed AI nodes, creating a common operating picture for command and control.
Artificial Intelligence (AI) Defence involves applying computational systems to military operations to augment human intelligence and accelerate decision cycles. These systems use machine learning and computer vision algorithms to process vast streams of sensor data for tasks like target recognition and threat analysis. Within applications, demand for Cyber Defence solutions is accelerating to counter sophisticated state-level threats. The deployment model shows Edge Computing gaining traction over traditional on-premises systems for real-time battlefield decision support.
The US Department of Defense's ethical AI principles and the forthcoming EU AI Act create distinct compliance pathways for market participants. National security export controls in the United States and the United Kingdom also govern the international transfer of sensitive AI technologies. Navigating these divergent ethical guidelines and export control regimes will determine market access and partnership viability for technology developers.
Market Dynamics
The central tension shaping the market is the dual-track development of AI capabilities. Nations are simultaneously racing to deploy autonomous and semi-autonomous systems for tactical advantage while also constructing complex ethical frameworks and export controls to govern their use and proliferation.
Growth Catalysts
- National Security Strategies:Defence modernization policies in the United States, the United Kingdom, and China explicitly prioritize investment in AI and machine learning to maintain a technological edge in military capabilities, creating sustained government funding streams.
- Sensor Data Proliferation:The widespread deployment of advanced electro-optical, infrared, and signals intelligence sensors on satellites, drones, and ground platforms generates immense data volumes that necessitate AI-powered tools for effective and timely analysis.
- Autonomous System Demand:Military forces are expanding their use of unmanned aerial, ground, and underwater vehicles for reconnaissance and logistics, which requires sophisticated onboard AI for navigation, threat identification, and independent operation in contested environments.
Market Restraints
- Technical Trust and Verification:The "black box" nature of some complex neural networks creates a significant barrier to adoption in high-stakes military applications, where operators and commanders require transparent and verifiable decision-making processes.
- Regulatory and Ethical Hurdles:Divergent and evolving regulatory landscapes, such as the US Department of Defense's ethical principles versus the forthcoming EU AI Act, create compliance complexity and can delay the fielding of new systems.
- Scarcity of Specialized Talent:A persistent shortage of cleared personnel with expertise in both military operations and advanced AI disciplines like reinforcement learning constrains the pace of development and deployment for defence agencies and contractors.
Strategic Opportunities
- Predictive Maintenance:Applying AI algorithms to analyze performance data from naval vessels, aircraft, and ground vehicles offers a substantial opportunity to forecast component failures, optimize maintenance schedules, and improve overall fleet readiness.
- Synthetic Data Generation:Creating high-fidelity synthetic training data for AI models presents a key opportunity to overcome the scarcity of real-world classified data, particularly for training algorithms to recognize rare but critical threats.
- Counter-UAS Systems:The growing threat from small, commercially available drones creates a significant market for AI-driven counter-unmanned aircraft systems that can detect, classify, and neutralize aerial threats automatically in complex environments.
Industry Challenges
- Legacy System Integration:A primary operational challenge is integrating modern AI software and edge hardware with decades-old military command, control, and communications systems without compromising security, reliability, or performance.
- Adversarial AI Attacks:Defending AI models against sophisticated adversarial attacks, such as data poisoning or evasion techniques designed to fool recognition systems, is a critical and continuous challenge for system developers and military operators.
- Standardization of Protocols:The lack of common data formats and interoperability standards among different AI systems and platforms from various vendors complicates the creation of a unified operational picture for joint and coalition forces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence (AI) Defence Market |
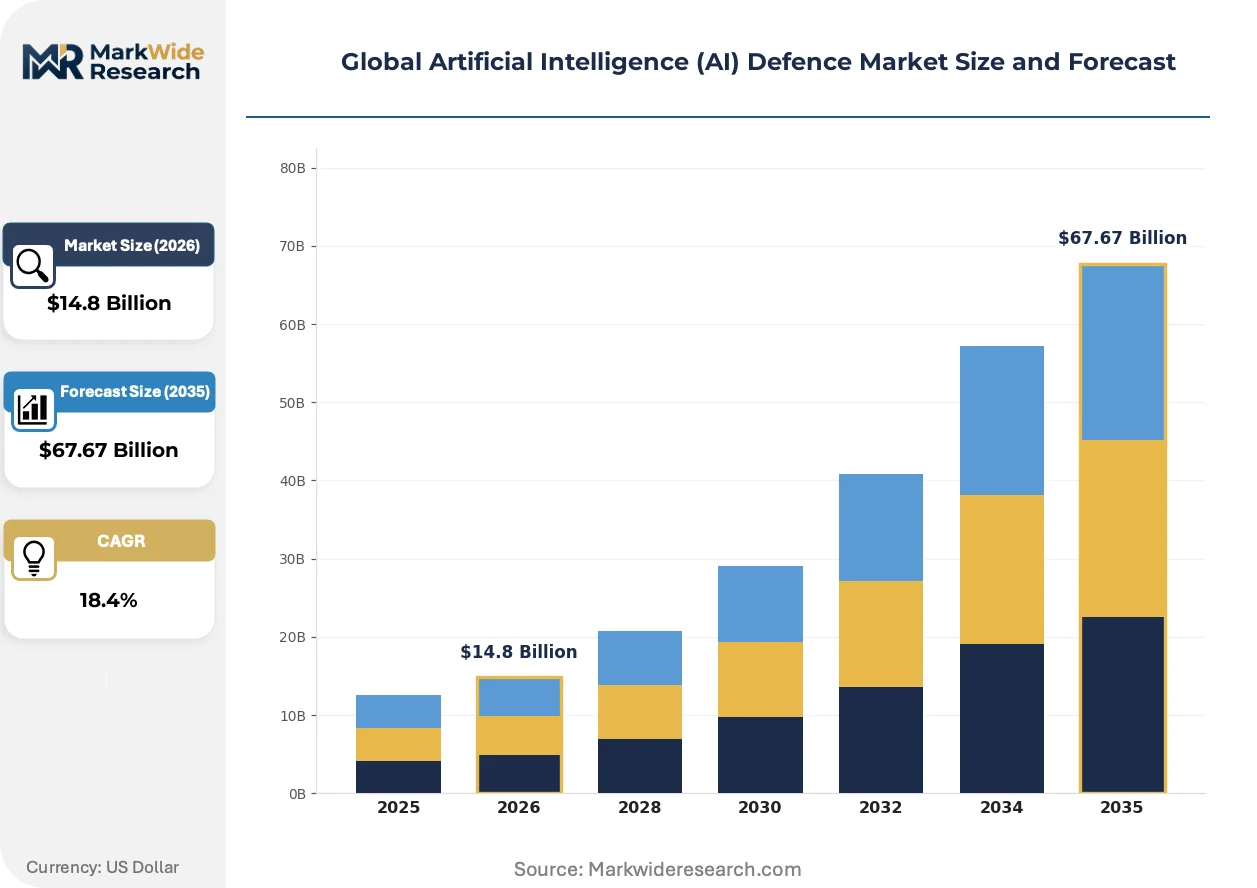
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $67.67 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Surveillance Systems, Autonomous Vehicles, Target Recognition, Cyber Defence, Command & Control, Electronic Warfare Deployment: On-Premises, Cloud-Based, Edge Computing, Hybrid Systems Technology: Machine Learning, Computer Vision, Natural Language Processing, Robotics, Neural Networks, Deep Learning End User: Military Forces, Defence Contractors, Intelligence Agencies, Homeland Security, Aerospace & Security Firms |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation, BAE Systems plc, Thales Group, L3Harris Technologies, Inc., Palantir Technologies Inc., Leonardo S.p.A., Anduril Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence (AI) Defence Market Strategic Shifts & Innovations
The market is being redefined by the push to create resilient and adaptive AI that can function in communication-denied environments. This drives innovation in on-device processing and distributed intelligence, moving capabilities away from centralized command posts and directly to the tactical edge.
Digital twin technology provides a high-fidelity virtual replica of a physical asset or an operational environment. Defence developers and military planners are rapidly adopting this for system design, wargaming, and mission rehearsal. This technology is virtualizing the test and evaluation lifecycle, enabling thousands of simulated scenarios to be run to validate AI behavior and performance before physical deployment.
The US Department of Defense’s ethical AI principles serve as a foundational policy shaping system design and procurement. This framework mandates that all AI capabilities must be responsible, equitable, traceable, reliable, and governable. Consequently, developers targeting the US military market are embedding "explainable AI" (XAI) features and robust human-in-the-loop controls directly into their core architecture to ensure compliance.
A notable demand-side shift is occurring from acquiring standalone, single-purpose AI applications to procuring integrated software platforms. This disrupts vendors focused on niche algorithms, as defence customers increasingly prefer extensible platforms that can fuse data from diverse sensors and host multiple third-party AI tools. This trend is most prominent within command and control modernization programs in the United States and other Five Eyes nations.
Global Artificial Intelligence (AI) Defence Market Segmentation
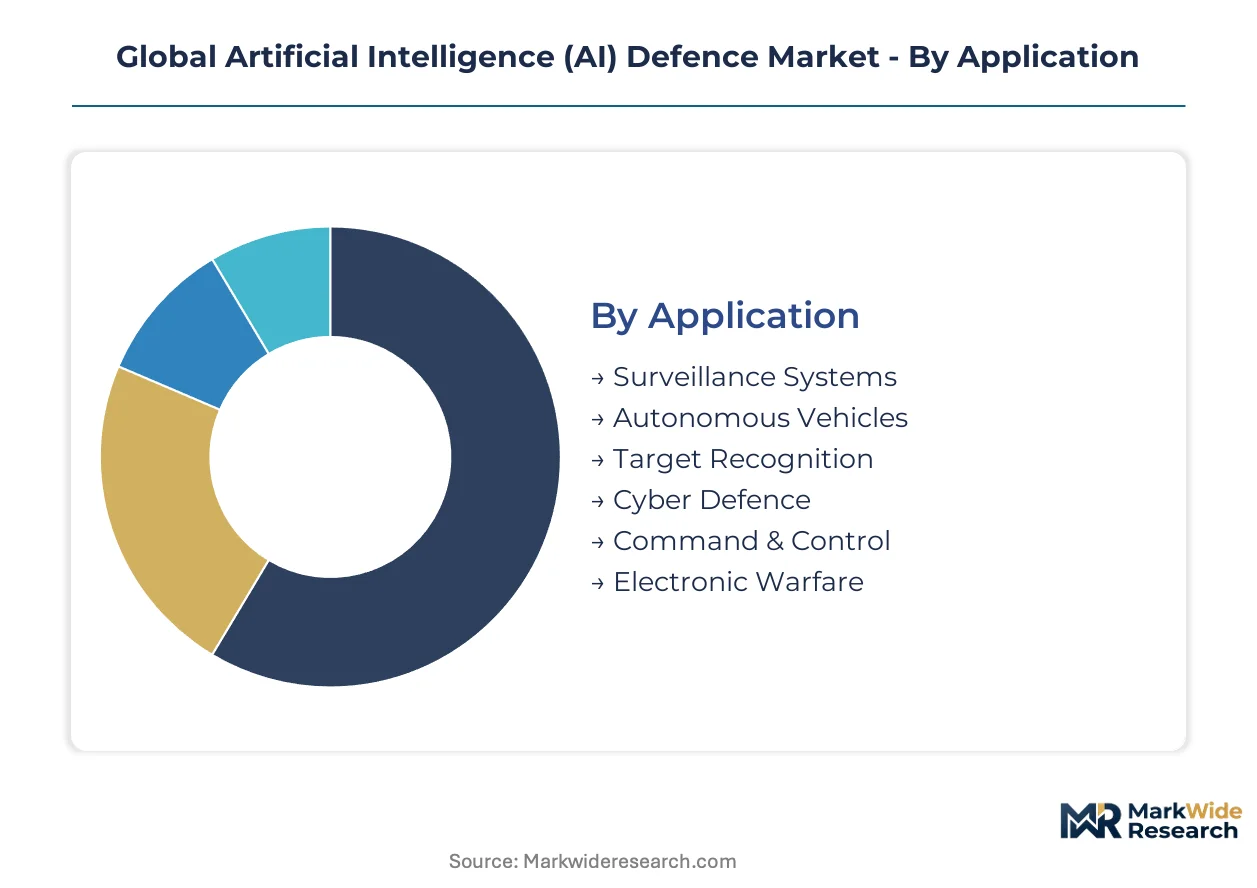
The Global Artificial Intelligence (AI) Defence market segments underscore distinct operational requirements and technological approaches. Understanding these divisions clarifies where investment flows and how military capabilities are evolving. Each segment reflects unique challenges and opportunities for technology developers and defence agencies.
Application:
The intensity of after-sales service and ongoing operational support varies significantly across AI defence applications, demanding continuous data updates and algorithm refinement.
- Autonomous Vehicles:Autonomous Vehicles integrate AI for independent navigation, target identification, and mission execution in contested environments. Demand concentrates within the US defence industrial base, driving investment.
- Cyber Defence:Cyber Defence involves AI algorithms to detect, analyze, and neutralize sophisticated state-level cyber threats targeting critical military infrastructure. Demand accelerates globally to counter evolving digital warfare.
- Surveillance Systems:Surveillance Systems process vast sensor data for real-time threat detection and intelligence gathering.
- Target Recognition:Target Recognition enhances automated identification and classification of objects or personnel from sensor feeds.
- Command & Control:Command & Control supports decision-making by integrating and analyzing data from distributed nodes for a common operating picture.
- Electronic Warfare:Electronic Warfare optimizes jamming, deception, and signal intelligence operations, enhancing countermeasures against adversary systems.
By volume, Autonomous Vehicles leads. By growth pace, Cyber Defence is ahead.
Deployment:
The cost tier for AI defence deployment models reflects infrastructure requirements, data sovereignty, and bandwidth availability, offering distinct advantages per operational context.
- Edge Computing:Edge Computing processes data directly on devices near the source, enabling faster, localized decision-making on the battlefield. The US Department of Defense prioritizes this for real-time tactical support.
- Cloud-Based:Cloud-Based deployments leverage scalable, remote computing for AI model training and data analysis, offering flexibility for non-tactical applications. Defence contractors utilize this for large-scale data processing.
- On-Premises:On-Premises systems house AI infrastructure within secure military facilities, ensuring maximum data security and regulatory compliance.
- Hybrid Systems:Hybrid Systems combine on-premises, cloud, and edge computing, optimizing resource allocation across diverse operational environments.
Edge Computing deployments are gaining significant traction, particularly for real-time battlefield decision support, displacing traditional on-premises systems.
Technology:
The application focus of underlying AI technologies dictates their suitability for specific defence tasks, from pattern recognition to autonomous reasoning.
- Deep Learning:Deep Learning uses multi-layered neural networks to process complex data patterns, crucial for advanced image recognition and predictive analytics. Lockheed Martin Corporation applies this for advanced combat systems.
- Machine Learning:Machine Learning algorithms enable systems to learn from data without explicit programming, supporting tasks like target classification and threat analysis. This forms the foundation for many AI-enabled capabilities.
- Computer Vision:Computer Vision interprets visual information from cameras and sensors, vital for autonomous navigation and target identification.
- Natural Language Processing:Natural Language Processing enables AI to understand, interpret, and generate human language for intelligence analysis.
- Robotics:Robotics integrates AI for controlling autonomous and semi-autonomous physical systems, essential for unmanned vehicles.
- Neural Networks:Neural Networks are computational models inspired by the human brain, forming the backbone for deep learning and pattern recognition.
Machine Learning remains a foundational technology, while Deep Learning is experiencing the steepest expansion trajectory due to its advanced pattern recognition capabilities.
End User:
The customer type within the AI defence market defines procurement cycles, integration requirements, and regulatory compliance needs.
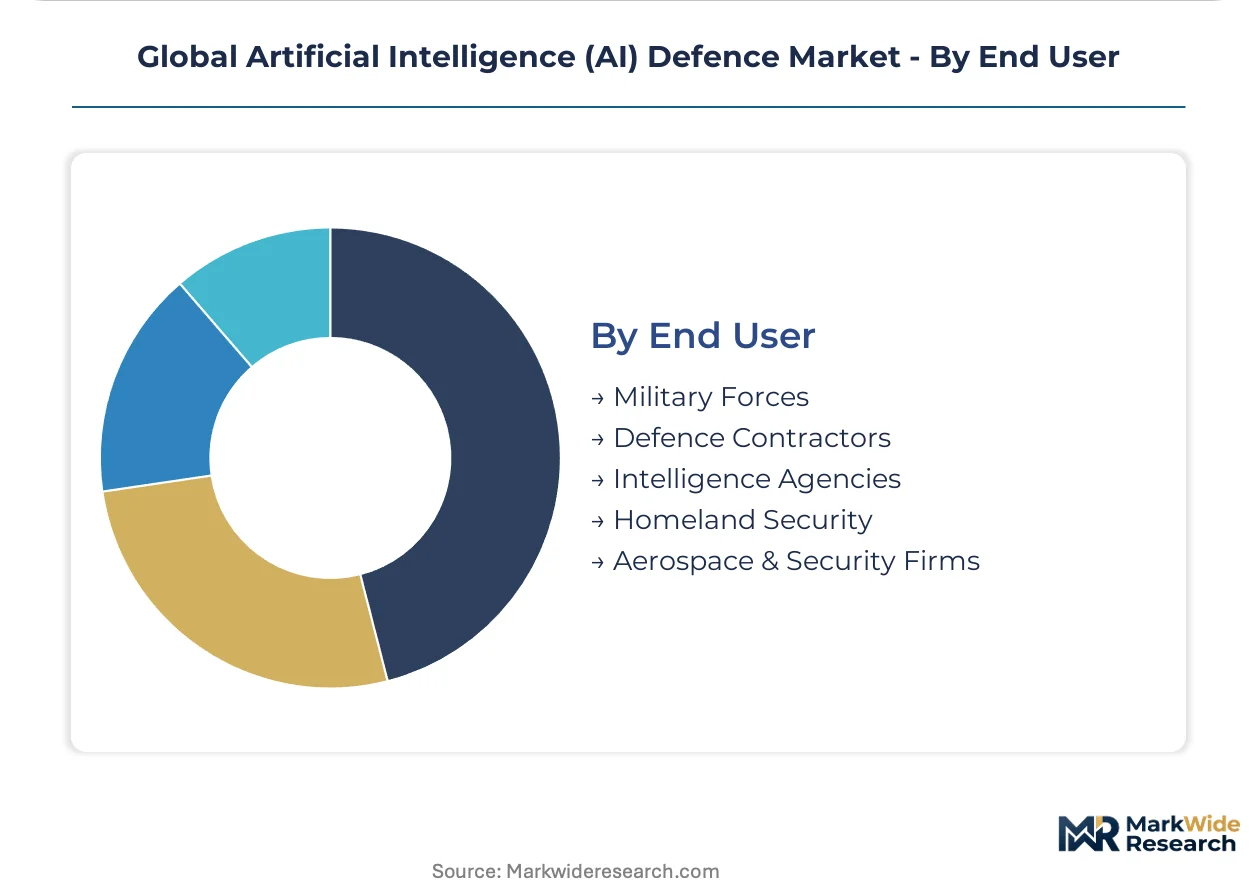
- Military Forces:Military Forces represent the primary consumers of AI defence solutions, integrating advanced systems into operational doctrine for tactical advantage. The US Department of Defense champions substantial investment.
- Defence Contractors:Defence Contractors develop and supply AI-enabled hardware and software solutions to military forces, often acting as prime integrators. Palantir Technologies Inc. specializes in unifying data platforms.
- Intelligence Agencies:Intelligence Agencies leverage AI for advanced data analysis, predictive intelligence, and threat assessment.
- Homeland Security:Homeland Security employs AI for border surveillance, critical infrastructure protection, and counter-terrorism efforts.
- Aerospace & Security Firms:Aerospace & Security Firms develop AI solutions for aerospace applications, including autonomous flight and satellite intelligence.
Military Forces consistently represent the largest end-user segment, with Defence Contractors closely following as key enablers of technological deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The buyer-archetype concentration for AI defence solutions predominantly resides within established military powers. These nations prioritize significant investments in AI-enabled capabilities to maintain a technological edge and enhance national security postures. This strategic focus drives demand for advanced autonomous systems and sophisticated cyber defence platforms across key global regions.
United States
The United States defence industrial base drives substantial investment in AI-enabled autonomous vehicles and advanced combat systems. The US Department of Defense's ethical AI principles significantly influence system design and procurement. Washington D.C. and its surrounding areas, including Northern Virginia, represent a major hub for defence contractors and AI research, fostering innovation in military AI applications.
United Kingdom
United Kingdom defence modernization policies explicitly prioritize investment in AI and machine learning to maintain military capabilities. National security export controls in the United Kingdom govern the international transfer of sensitive AI technologies. London and the aerospace clusters in the Southwest of England are centers for AI defence development, focusing on secure data analysis and autonomous platforms.
China
China's national security strategies prioritize investment in AI and machine learning to enhance its military capabilities. The country's robust digital infrastructure supports the development of AI for surveillance systems and unmanned vehicles. Research institutions in Beijing and technology hubs in Shenzhen are actively developing AI solutions for military applications, including advanced sensor data processing.
France
France is a significant player in European defence, with its military forces integrating AI for enhanced command and control and electronic warfare. The nation's defence industry, including companies like Thales Group, develops AI solutions for various military applications. The aerospace and defence cluster around Toulouse focuses on AI for autonomous aerial platforms and advanced reconnaissance systems.
Israel
Israel's defence sector demonstrates strong demand for AI in cyber defence and advanced surveillance systems due to regional security challenges. The country's defence establishment actively funds AI research and development for intelligence gathering and target recognition. Tel Aviv's vibrant tech ecosystem, particularly in cybersecurity, contributes significantly to AI defence innovations.
Global Artificial Intelligence (AI) Defence Market Key Industry Players
Channel-controlling players compete with product-specialist players to secure defence contracts and integrate AI technologies. The market structure exhibits a tiered approach, where large prime contractors integrate solutions from specialized AI software and hardware developers. Strategic partnerships and technology licensing are common competitive moves, enabling companies to expand their portfolio of AI-enabled defence capabilities.
Among the prime defence contractors, Lockheed Martin Corporation represents a major integrator of AI into autonomous vehicles and advanced combat systems. Palantir Technologies Inc. exemplifies a software platform specialist, providing unified data solutions for distributed AI nodes. BAE Systems plc, a European defence giant, occupies a position in developing AI for electronic warfare and surveillance systems.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| RTX Corporation |
| BAE Systems plc |
| Thales Group |
| L3Harris Technologies, Inc. |
| Palantir Technologies Inc. |
| Leonardo S.p.A. |
| Anduril Industries, Inc. |
| Others |
Cost & Logistics Intelligence
The US defence industrial base's high capacity utilization for AI-enabled systems drives robust supplier investment and influences contract pricing. This sustained demand for advanced capabilities shapes long-term procurement strategies.
Pricing Analysis
Cost-plus contracts, often indexed to defense budget allocations and technology development milestones, dominate the AI Defence market. This model supports the long-term, project-based development of highly specialized AI systems. Price differentiation stems from the level of customization required for specific military applications and the integration complexity with legacy systems. Pricing softness emerges in commoditized AI components due to increased competition from dual-use technology firms. Military Forces prioritize mission effectiveness over initial cost for critical systems, while Homeland Security agencies often exhibit greater price sensitivity for broader deployments.
Supply Chain Analysis
Extended payment terms and specialized supply-chain finance facilities support the complex, long-duration projects characteristic of AI defence procurement. The supply chain for advanced AI components concentrates in the United States, China, and Taiwan. Key dependencies include high-performance semiconductors, specialized sensor arrays, and secure data storage solutions. A structural risk is single-source vulnerability for advanced AI processors, particularly those designed for radiation-hardened military specifications. Distribution runs through a network of prime defence contractors and specialized technology integrators directly to military forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Artificial Intelligence Defence market necessitates a robust substitution defense strategy. Incumbents must navigate the threat posed by rapidly evolving commercial AI technologies that could be adapted for military use, potentially disrupting established procurement cycles.
For Market Incumbents: Harden core AI platforms against adversarial AI attacks to maintain system integrity and operator trust. Invest in explainable AI (XAI) features to address the "black box" nature of neural networks, countering regulatory and ethical hurdles. Expand vertical integration into key component manufacturing to mitigate single-source vulnerability for specialized hardware.
For New Entrants and Emerging Players: European defence markets represent a geographic underpenetration for advanced AI solutions beyond the established US industrial base. Target niche applications like predictive maintenance for specific fleet types or counter-UAS systems, where rapid deployment and specialized algorithms offer a competitive edge. Focus go-to-market strategies on securing strategic partnerships with established European defence contractors to navigate complex regulatory landscapes.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software platform specialists providing integrated command and control solutions. The long-term viability of AI defence investments hinges on continuous government funding streams and the integration of ethical AI principles into product roadmaps. Identify acquisition targets with proven expertise in secure edge computing and synthetic data generation, as these capabilities are critical for future battlefield autonomy. The signal to watch is the consistent allocation of national defence budgets towards AI modernization initiatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration for C2 | Unifying data from distributed AI nodes enhances decision-making for military command and control. |
| Ethical AI Framework Adoption | Embedding explainable AI features ensures compliance with US Department of Defense principles for system procurement. |
| Edge Computing Hardware Development | Localized processing on tactical devices enables faster, real-time decision support on the battlefield. |
| Synthetic Data Generation Investment | Creating high-fidelity training data overcomes scarcity of real-world classified data for AI models. |
| Counter-UAS System R&D | AI-driven counter-drone solutions address the growing threat from small, commercially available unmanned aerial systems. |
Research Approach
The analysis maps AI defence sub-sectors like autonomous vehicles, cyber defence, and surveillance systems, each validated through primary interviews with defence contractors, military strategists, and AI technology developers. Secondary validation drew from US Department of Defense reports, EU AI Act legislative documents, and aerospace industry publications. This approach combined bottom-up market sizing with top-down strategic insights, ensuring robust data triangulation.
The forecast held geopolitical stability and consistent defence spending as fixed assumptions, while varying technological adoption rates and regulatory compliance costs. Segmentation dimensions modeled included application (e.g., autonomous vehicles, cyber defence), deployment model (edge, cloud), technology type (deep learning, machine learning), and end-user (military forces, defence contractors). Compound annual growth rates were derived from historical trends and projected investment cycles. Key inputs included national security strategies and sensor data proliferation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed AI developers or new disruptive tech firms would shift outcomes. This analysis reflects current geopolitical tensions and technological trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Linear Particle Accelerators Market