
 Aerospace Accumulator Market | 2026-2036
Aerospace Accumulator Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Accumulator Market Analysis
Defense contractors are redrawing demand patterns as military aviation outpaces commercial aviation in accumulator procurement intensity. Parker Aerospace leverages in-house forging capabilities to control titanium shell supply for high-pressure units. Safran Landing Systems anchors European aftermarket channels through landing gear-integrated hydraulic systems. Eaton Aerospace competes on electromechanical technology leadership for next-generation platforms.
An aerospace accumulator is a pressure vessel that stores hydraulic or pneumatic energy under pre-charge conditions, typically constructed from 15-5PH stainless steel or titanium alloy with operating pressures ranging from 3,000 to 8,000 psi to dampen pulsations and provide emergency power. Its primary commercial purpose is ensuring continuous hydraulic pressure during pump failure or peak demand events in flight control systems. Metal bellows accumulators command premium positioning in spacecraft applications where zero-leak tolerance justifies unit costs several multiples above diaphragm designs. Commercial aviation remains the volume base though UAVs represent the fastest-expanding application segment as endurance requirements drive miniaturization. Fluidic technology lags in revenue share but captures outsized R&D allocation from space agencies seeking passive thermal compensation.
FAA airworthiness standards and EASA CS-25 certification frameworks mandate burst-pressure margins and fatigue-life documentation that elevate barrier-to-entry for new accumulator suppliers. AS9100 quality systems and NADCAP accreditation for heat treatment and non-destructive testing filter the vendor base to established specialists. Stakeholders must monitor evolving EPA regulations on chromium plating alternatives and MIIT dual carbon compliance timelines in China as these reshape material substitution roadmaps and supplier qualification cycles.
Market Dynamics
Defense procurement intensity for next-generation fighter programs is compressing commercial aviation's historical volume dominance, while FAA and EASA certification convergence on hydraulic redundancy standards is elevating material qualification barriers for new entrants.
Growth Catalysts
- Electrohydraulic accumulator adoption:Next-generation military platforms require sealed energy storage for flight-critical redundancy. Defense contractors in the United States, France, and Germany are expanding long-term supply agreements.
- EASA CS-25 burst-pressure mandates:Certification frameworks now demand documented fatigue-life margins that filter vendor pools to AS9100-accredited specialists with NADCAP heat-treatment capabilities.
- UAV endurance miniaturization:Unmanned platforms require compact, lightweight hydraulic storage. Metal bellows designs with zero-leak tolerance are penetrating this fastest-expanding application segment.
Market Restraints
- Titanium alloy supply concentration:High-pressure shell forging capacity clusters with in-house aerospace OEM capabilities, limiting independent supplier scaling.
- Chromium plating regulatory friction:EPA restrictions on hexavalent chromium surface treatments are forcing material substitution roadmaps that extend qualification cycles by 18-24 months.
- Fluidic technology substitution threat:Passive thermal compensation systems from space agency R&D programs threaten conventional accumulator architectures in satellite and long-endurance drone applications.
Strategic Opportunities
- Aftermarket channel integration:Landing gear-integrated hydraulic systems create captive demand for accumulator replacement tied to MRO cycles at major European hubs.
- MIIT dual carbon compliance:China's Ministry of Industry and Information Technology timelines are accelerating domestic certification of lightweight titanium alternatives to stainless steel 15-5PH.
- Additive manufacturing convergence:Topology-optimized shell geometries combined with in-situ monitoring sensors enable predictive maintenance contracts for commercial fleet operators.
Industry Challenges
- AS9100D and NADCAP talent scarcity:Heat-treatment and non-destructive testing certification pipelines cannot match OEM qualification demands, constraining supplier expansion.
- Legacy system integration complexity:New electromechanical accumulator designs must interface with 30-year-old hydraulic architectures without triggering full flight-control recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Accumulator Market |
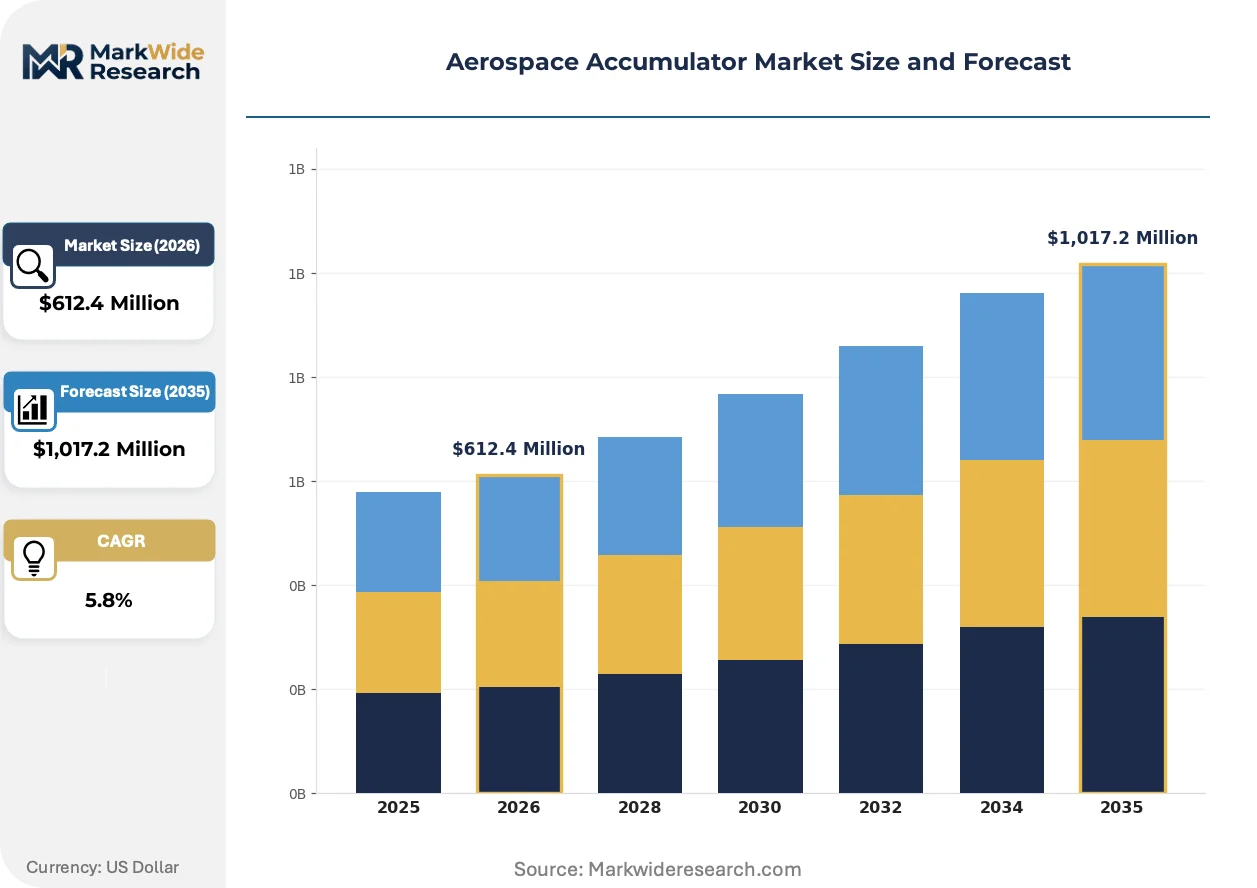
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Diaphragm, Metal Bellows Application: Commercial Aviation, Military Aviation, Spacecraft, UAVs End User: Aircraft Manufacturers, Defense Contractors, Space Agencies, Repair Facilities Technology: Electromechanical, Electrohydraulic, Fluidic, Mechanical |
| Companies Covered | Safran Landing Systems, Triumph Group, Parker Aerospace, Senior Aerospace, HYDAC, Collins Aerospace, Liebherr-Aerospace, Valcor Engineering Corporation, Eaton Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Accumulator Market Emerging Trajectories
Active materials and regulatory convergence are compressing traditional design cycles while opening white space in predictive maintenance and thermal management architectures.
Metal bellows accumulator technology is supplanting piston and diaphragm designs in spacecraft and high-altitude UAV applications where zero-leak tolerance overrides unit cost premiums. NASA and ESA contractors are adopting these systems for thermal compensation in orbital platforms. The shift is compressing procurement pools to vendors with vacuum-brazing and electron-beam welding capabilities.
REACH restrictions on hexavalent chromium are forcing surface-treatment substitutions across European supply chains. Plasma electrolytic oxidation and HVOF ceramic coatings are displacing legacy plating for corrosion resistance in 15-5PH stainless steel shells. German and French OEMs are qualifying these alternatives ahead of 2026 sunset dates for aerospace exemptions.
Buyer consolidation among tier-one integrators is unbundling aftermarket service from original equipment contracts. Airlines and MRO providers in the United States now procure accumulators separately from landing gear overhauls, compressing switching costs and privileging suppliers with direct airworthiness documentation support.
Aerospace Accumulator Market Segmentation
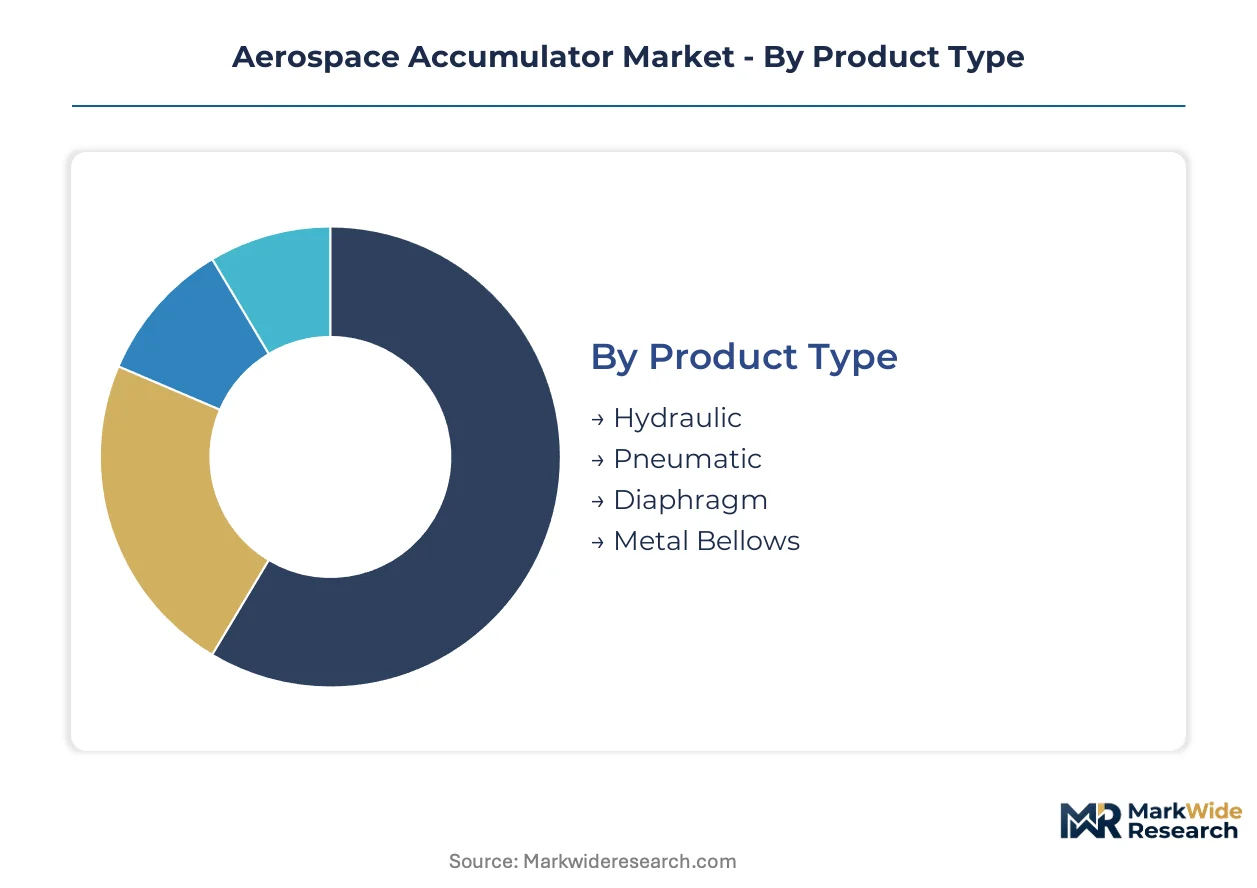
Aerospace accumulator procurement splits across four distinct axes, each governed by certification intensity and operational environment. Product type and application categories carry the heaviest regulatory load, while end-user and technology segments reflect divergent qualification timelines and supply chain access.
Product Type:
FAA burst-pressure documentation and EASA CS-25 fatigue-life mandates create tiered barriers that concentrate vendor pools differently across each design architecture.
- Hydraulic:Dominant volume category storing pressurized fluid for flight control redundancy. Commercial aviation manufacturers in the United States and Germany anchor procurement through long-term supply agreements tied to single-aisle production rates. EPA chromium plating restrictions are extending qualification cycles for surface-treated piston variants.
- Metal Bellows:Zero-leak tolerance construction using vacuum-brazed titanium or Inconel bellows assemblies. NASA and ESA spacecraft contractors command premium positioning for orbital thermal compensation applications. Electron-beam welding capabilities filter the supplier base to AS9100-accredited specialists with NADCAP heat-treatment credentials.
- Pneumatic:Compressed gas energy storage for emergency deployment systems in military platforms.
- Diaphragm:Elastomeric membrane designs for lower-pressure auxiliary systems in regional aircraft.
Hydraulic accumulators handle the majority of throughput; metal bellows designs are expanding most quickly on share as spacecraft and high-altitude UAV procurement accelerates.
Application:
Defense procurement intensity now outpaces commercial aviation in unit-value terms, compressing historical volume hierarchies.
- Military Aviation:Next-generation fighter programs demand sealed electrohydraulic storage for flight-critical redundancy. Defense contractors in France and Germany are expanding long-term agreements ahead of platform certification milestones. EASA and FAA convergence on hydraulic system redundancy is elevating material qualification barriers for new entrants.
- UAVs:Endurance-driven miniaturization requirements favor compact, lightweight architectures. Metal bellows designs with zero-leak tolerance are penetrating this segment fastest as mission durations extend. MIIT dual carbon compliance timelines in China are accelerating domestic certification of titanium alternatives.
- Commercial Aviation:Volume base for hydraulic accumulator replacement cycles tied to flight-hour maintenance schedules.
- Spacecraft:Thermal compensation applications requiring vacuum-qualified assemblies with documented outgassing properties.
Commercial aviation retains the installed base; UAV applications show the steepest expansion trajectory as endurance requirements reshape procurement specifications.
End User:
Buyer consolidation among tier-one integrators is unbundling aftermarket procurement from original equipment contracts, compressing switching costs.
- Aircraft Manufacturers:Final assembly line demand concentrates in Boeing and Airbus supply chains with direct airworthiness documentation requirements. AS9100D and NADCAP accreditation filters limit vendor pools for heat-treatment and non-destructive testing capabilities. Talent scarcity in these certification pipelines constrains supplier expansion.
- Defense Contractors:Lockheed Martin, Dassault Aviation, and Airbus Defence and Space anchor electrohydraulic procurement for next-generation platforms. Long-term supply agreements span development through production phases with qualification milestones tied to flight-test schedules.
- Repair Facilities:MRO providers in the United States now procure accumulators separately from landing gear overhauls.
- Space Agencies:NASA and ESA contractors drive metal bellows adoption with thermal management specifications.
Aircraft manufacturers command the largest order book; defense contractors are gaining share fastest as fighter program procurement accelerates.
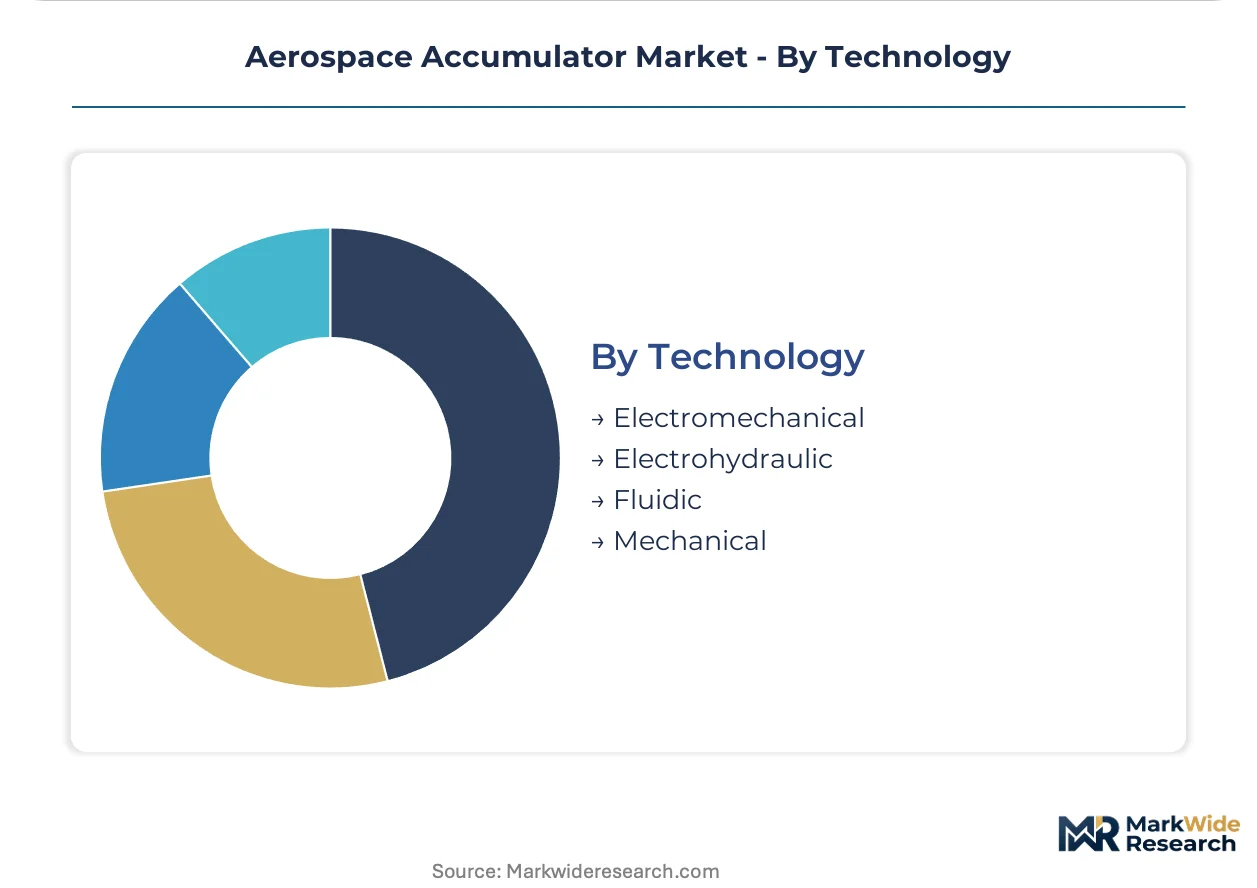
Technology:
Electromechanical and electrohydraulic architectures are displacing legacy mechanical designs as flight-control electrification progresses.
- Electrohydraulic:Sealed energy storage integrating hydraulic power with electronic control for next-generation military platforms. Defense procurement in the United States and France is compressing development cycles. Legacy system integration complexity forces backward compatibility with 30-year-old hydraulic architectures.
- Electromechanical:Motor-driven pump replacements for conventional accumulator functions in more-electric aircraft architectures. Eaton Aerospace competes on technology leadership for platform development programs. Full flight-control recertification risks slow adoption in retrofitted commercial fleets.
- Fluidic:Passive thermal compensation systems from space agency R&D programs threaten conventional architectures in satellite applications.
- Mechanical:Spring-loaded and weight-loaded designs for non-flight-critical auxiliary systems.
Electrohydraulic technology captures the dominant development spend; electromechanical systems are climbing the fastest as more-electric aircraft architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's aerospace logistics corridor underwrites Germany's distribution dominance for hydraulic system components across European final assembly lines.
United States
Boeing's Everett and Charleston final assembly lines drive concentrated demand for flight-control redundancy systems. FAA airworthiness directives on hydraulic burst-pressure margins filter vendor pools to AS9100-accredited specialists. The Seattle-Tacoma aerospace cluster anchors titanium shell forging capacity for high-pressure accumulator variants.
France
Dassault Aviation's Rafale and future combat air system programs expand electrohydraulic procurement through multi-year supply agreements. EASA CS-25 certification convergence with FAA standards elevates material qualification barriers for new market entrants. The Toulouse-Blagnac aerospace hub concentrates landing gear-integrated hydraulic system production.
Germany
Airbus Defence and Space anchors military aviation demand alongside commercial single-aisle production rates. REACH restrictions on hexavalent chromium surface treatments force plasma electrolytic oxidation qualification cycles extending 18-24 months. The Hamburg-Finkenwerder final assembly line integrates accumulator replacement schedules with MRO turnaround protocols.
China
MIIT dual carbon compliance timelines accelerate domestic certification of lightweight titanium alternatives to 15-5PH stainless steel. The country's national aviation regulator tightens documentation requirements for hydraulic system redundancy in indigenous narrow-body programs. The Yangtze River Delta aerospace manufacturing corridor concentrates electrohydraulic component testing facilities.
United Kingdom
BAE Systems' Tempest program participation drives sealed energy storage procurement for next-generation fighter architectures. The Civil Aviation Authority aligns burst-pressure documentation requirements with EASA frameworks post-Brexit. The Midlands aerospace cluster hosts specialized heat-treatment and non-destructive testing capabilities for accumulator shell production.
Aerospace Accumulator Market Vendor Landscape
Concentration sits with diversified aerospace tier-one suppliers controlling in-house forging and certification pipelines. The vendor base compresses around three strategic archetypes: integrated landing gear specialists with captive hydraulic system demand, diversified fluid power conglomerates spanning commercial and defense segments, and precision metal-forming specialists with vacuum-brazing capabilities for spacecraft applications. Dominant competitive moves include backward integration into titanium shell forging capacity and strategic positioning for aftermarket channel unbundling.
Among French-integrated system providers, Safran Landing Systems exemplifies the landing gear-anchored archetype with aftermarket channel control. Parker Aerospace and Eaton Aerospace occupy positions within the diversified fluid power tier, representing contrasting technology bets on electrohydraulic versus electromechanical architectures. These three entities anchor the competitive structure without exhausting its full composition.
| Leading Market Players |
|---|
| Safran Landing Systems |
| Triumph Group |
| Parker Aerospace |
| Senior Aerospace |
| HYDAC |
| Collins Aerospace |
| Liebherr-Aerospace |
| Valcor Engineering Corporation |
| Eaton Aerospace |
| Others |
Supply Flow & Price Mechanics
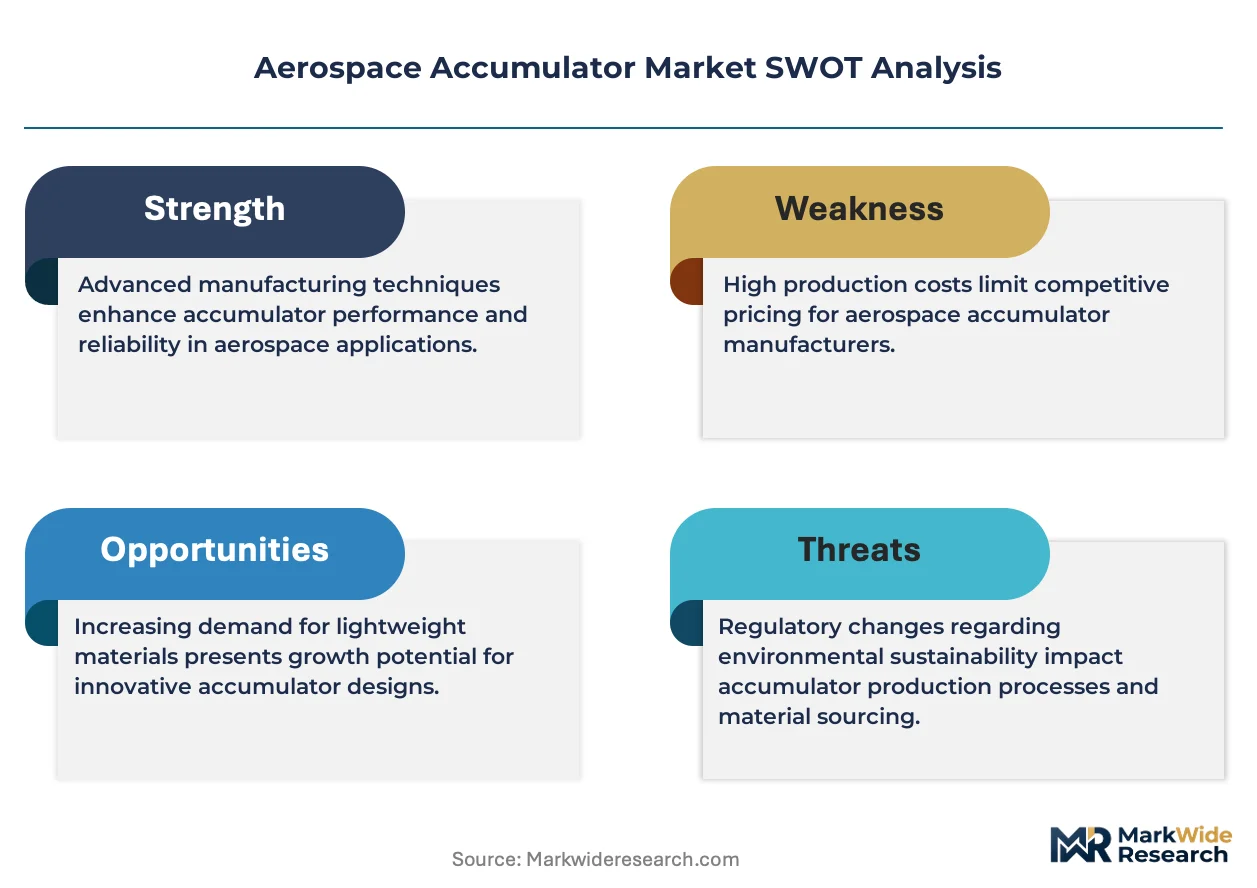
Twenty-four to thirty-six month qualification cycles for titanium shell forgings concentrate pricing power with AS9100-accredited specialists controlling in-house heat-treatment capacity, while EPA chromium plating restrictions force material substitution premiums that compress margins for independent suppliers lacking captive forging assets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NASA-qualified metal bellows units from commercial aviation hydraulic variants and non-flight-critical auxiliary systems. Price differentiation hinges on NADCAP heat-treatment certification and electron-beam welding capabilities for spacecraft applications. Cost compression in standard-tier piston accumulators is intensifying because REACH sunset dates for hexavalent chromium exemptions force surface-treatment substitutions. Defense contractors show lowest price sensitivity due to flight-critical redundancy mandates, while regional airline MRO providers face acute budget constraints on replacement cycles.
Supply Chain Analysis
Titanium sponge refining capacity in Japan, Russia, and Kazakhstan constitutes the critical upstream chokepoint for high-pressure shell production. The supply chain draws from vacuum-arc remelting feedstock, 15-5PH stainless steel billet, and Inconel bellows strip. Single-source vulnerability concentrates in electron-beam welding equipment qualified to aerospace specifications. Distribution runs through tier-one landing gear integrators unbundling aftermarket procurement from original equipment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AS9100D and NADCAP credential pipelines cannot match OEM qualification demands, creating a structural bottleneck that privileges incumbents with established heat-treatment and non-destructive testing infrastructure.
For Market Incumbents: Fortify captive titanium forging capacity to defend against fluidic technology substitution threats in satellite thermal management applications. Prioritize additive manufacturing qualification for topology-optimized shell geometries with embedded sensors. Deepen backward integration into electron-beam welding equipment to control vacuum-brazing capacity for metal bellows production. For New Entrants and Emerging Players: Differentiate on MIIT dual carbon compliance timelines by qualifying lightweight titanium alternatives for China's indigenous narrow-body programs. Target UAV endurance miniaturization as the most penetrable segment given compressed switching costs and absence of legacy system integration requirements. Pursue direct airworthiness documentation support capabilities to bypass tier-one integrator channel control. For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because AS9100 and NADCAP accreditation filters create irreproducible barriers that compound over multi-year qualification cycles. Acquisition targets should display vacuum-brazing capabilities paired with established defense contractor relationships. Watch for EASA-FAA regulatory divergence on burst-pressure documentation as an inflection signal that could reshape vendor pool composition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Forging | Parker Aerospace's in-house shell production insulates against Japan-Russia-Kazakhstan sponge concentration. |
| Additive Manufacturing Qualification | Topology-optimized geometries with in-situ sensors enable predictive maintenance contracts for commercial fleets. |
| Plasma Electrolytic Oxidation Adoption | German and French OEMs qualify REACH-compliant surface treatments ahead of hexavalent chromium sunset dates. |
| Aftermarket Channel Unbundling | US MRO providers now procure accumulators separately from landing gear overhauls, compressing switching costs. |
| Metal Bellows Capacity Expansion | NASA and ESA thermal compensation specifications filter suppliers to vacuum-brazing specialists with electron-beam welding credentials. |
Methodological Framework
Desk research of FAA airworthiness directives, EASA CS-25 certification frameworks, and EPA chromium plating regulations preceded structured interviews with hydraulic system engineering directors, NADCAP-accredited heat-treatment facility managers, defense contractor procurement leads, and MRO purchasing officers at major European hubs. Secondary validation drew from AS9100 certification databases, customs records of titanium alloy imports, and spacecraft thermal management R&D disclosures from NASA and ESA contractors. Bottom-up segment sizing triangulated against top-down OEM production rate estimates.
Variance decomposition across product type, application, end user, and technology dimensions anchored the analytical framework over the projection horizon. CAGRs derived from production rate forecasts for single-aisle commercial platforms and next-generation fighter program procurement schedules. Industry-specific inputs included flight-hour maintenance intervals for accumulator replacement cycles and MIIT dual carbon compliance timeline assumptions for Chinese domestic certification.
Material uncertainties — defense budget reallocation, REACH exemption extensions, fluidic technology maturation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and titanium alloy supply continuity. Practitioners should keep alternative scenarios live as EASA-FAA certification convergence and EPA surface-treatment restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market