
 AI in Military Market | 2026-2036
AI in Military Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Military Market Analysis
Multi-source contracting for algorithm training data is rebalancing toward hybrid models blending government labs with cleared commercial vendors. Lockheed Martin Corporation leverages its Skunk Works heritage to sustain classified AI development pipelines. Palantir Technologies competes on software-first architectures that reduce hardware lock-in for military clients. BAE Systems plc anchors European sovereign AI capabilities through UK and Swedish defense industrial partnerships.
AI in Military denotes the integration of machine learning, neural networks, and autonomous decision systems into command-and-control, intelligence analysis, and weapons platforms operating at tactical through strategic echelons. These systems process multi-sensor data streams in milliseconds to generate targeting solutions or cyber defense responses that exceed human cognitive bandwidth. Machine Learning applications for signal intelligence and predictive maintenance currently absorb the largest procurement budgets, while Neural Networks for autonomous target identification attract the fastest-growing investment as rules-of-engagement protocols evolve. Natural Language Processing for multilingual intelligence exploitation occupies a mature niche with stable margins, whereas Robotics integration for unmanned ground and aerial platforms concentrates vendor competition around edge-computing performance.
The US Department of Defense implements AI ethics guidelines through the Responsible AI Strategy, while NATO's data governance frameworks shape transatlantic interoperability standards for allied algorithm deployment. China's SAMR and GB standards enforce divergent technical specifications for dual-use AI components, fragmenting supplier certification requirements. The EU AI Act's high-risk system classifications will constrain European military AI exports unless defense exemptions clarify liability boundaries. Stakeholders must monitor how classified procurement thresholds and export control lists evolve for foundation models trained on sensitive operational data.
Market Dynamics
Defense procurement offices are compressing vendor qualification cycles from years to months as autonomous systems move from experimental to operational deployment, forcing suppliers to restructure development pipelines around continuous algorithm certification rather than hardware platform milestones.
Growth Catalysts
- Replicator Initiative:The Pentagon's program to field thousands of attritable autonomous systems by 2026 is accelerating procurement timelines for edge-computing hardware and sensor fusion software across multiple service branches.
- NATO Data Governance Frameworks:Standardized algorithm interoperability protocols are enabling cross-border military AI deployments and creating pooled procurement mechanisms for allied defense agencies.
- Signal Intelligence Automation:Machine learning pipelines for electronic warfare and communications intercept are absorbing expanded R&D budgets as electromagnetic spectrum operations intensify.
Market Restraints
- High-Performance Computing Constraints:Energy-intensive neural network training requires specialized GPU clusters whose supply concentrates with Taiwan Semiconductor Manufacturing and Samsung Foundry, creating single-source vulnerability.
- EU AI Act Liability Uncertainty:High-risk system classifications for autonomous weapons components remain undefined, freezing pre-contract negotiations for European defense exporters.
- Operational Data Scarcity:Classified tactical datasets essential for training cannot circulate across security clearance boundaries, fragmenting algorithm development into isolated silos.
Strategic Opportunities
- Swedish-Norwegian Arctic Surveillance:NATO's northern flank is deploying autonomous undersea and aerial sensor networks where harsh conditions favor AI-driven predictive maintenance over human intervention.
- Multi-Domain Task Force Integration:Convergence of space-based targeting, cyber effects, and kinetic strike systems creates demand for unified command algorithms that fuse orbital and terrestrial intelligence streams.
- UK Defence AI Strategy:British sovereign capability mandates are channeling procurement toward domestic software vendors and creating captive markets for ethical algorithm certification services.
Industry Challenges
- Algorithmic Bias Audit Shortfalls:Military AI systems lack standardized testing protocols for lethal autonomous decision-making, forcing program offices to develop ad-hoc validation frameworks that delay fielding.
- Legacy Platform Integration Friction:Cold War-era command systems with proprietary data architectures resist API-based connectivity, requiring expensive middleware development for AI overlay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Military Market |
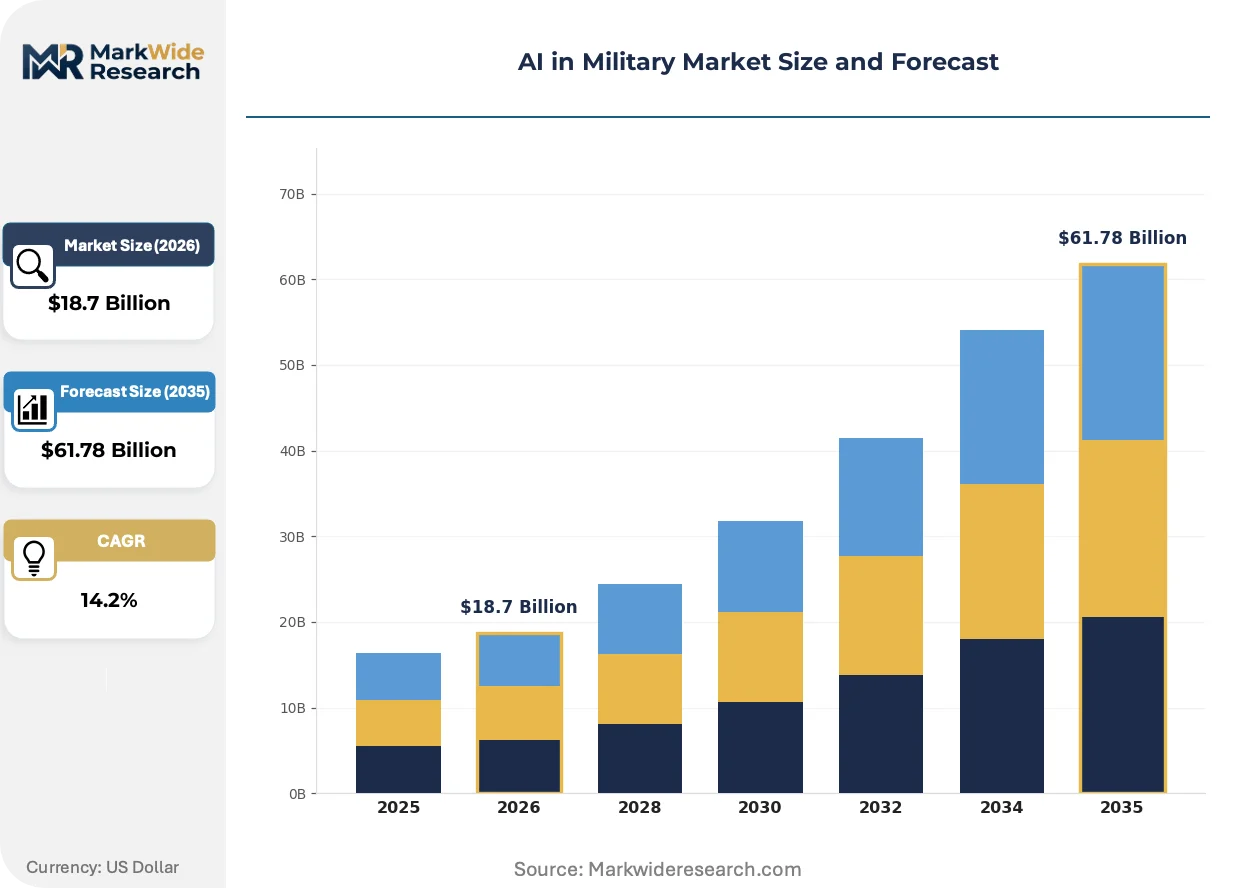
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Surveillance, Reconnaissance, Target Identification, Cyber Defense Technology: Machine Learning, Natural Language Processing, Neural Networks, Robotics End User: Defense Contractors, Military Agencies, Research Institutions, Government Entities Service Type: Consulting, System Integration, Maintenance, Training |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, BAE Systems plc, Thales Group, L3Harris Technologies, General Dynamics Corporation, Leonardo S.p.A., Palantir Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Military Market Emerging Trajectories
Neural network architectures are migrating from cloud-centric training to edge-deployed inference, compressing decision latency for tactical systems while fragmenting supplier ecosystems between semiconductor fabricators and specialized military software houses.
Federated learning architectures are consolidating distributed model training across classified networks without centralizing sensitive operational data. Defense agencies in the United States, United Kingdom, and Australia are deploying these systems for coalition intelligence sharing where raw intercepts cannot cross national boundaries. The approach compresses development cycles while preserving compartmentalization protocols that traditional data pooling would violate.
The EU AI Act's high-risk system classifications are forcing European defense contractors to segregate military algorithm development from civilian product lines. BAE Systems and Thales are establishing standalone certification tracks for weapons-adjacent AI components, creating parallel governance structures that add compliance overhead but preserve export eligibility. German and French procurement offices are delaying foundation model contracts until liability boundaries clarify.
Buyer concentration around the Pentagon's Replicator program and classified Special Access Programs is consolidating vendor selection authority within a handful of program executive offices. Mid-tier suppliers without existing security clearances face exclusion from algorithm training data contracts, while cleared incumbents capture multi-year development agreements. This pattern concentrates R&D investment in the Washington DC metro area and select UK defense clusters, marginalizing European continental vendors lacking US facility clearances.
AI in Military Market Segmentation
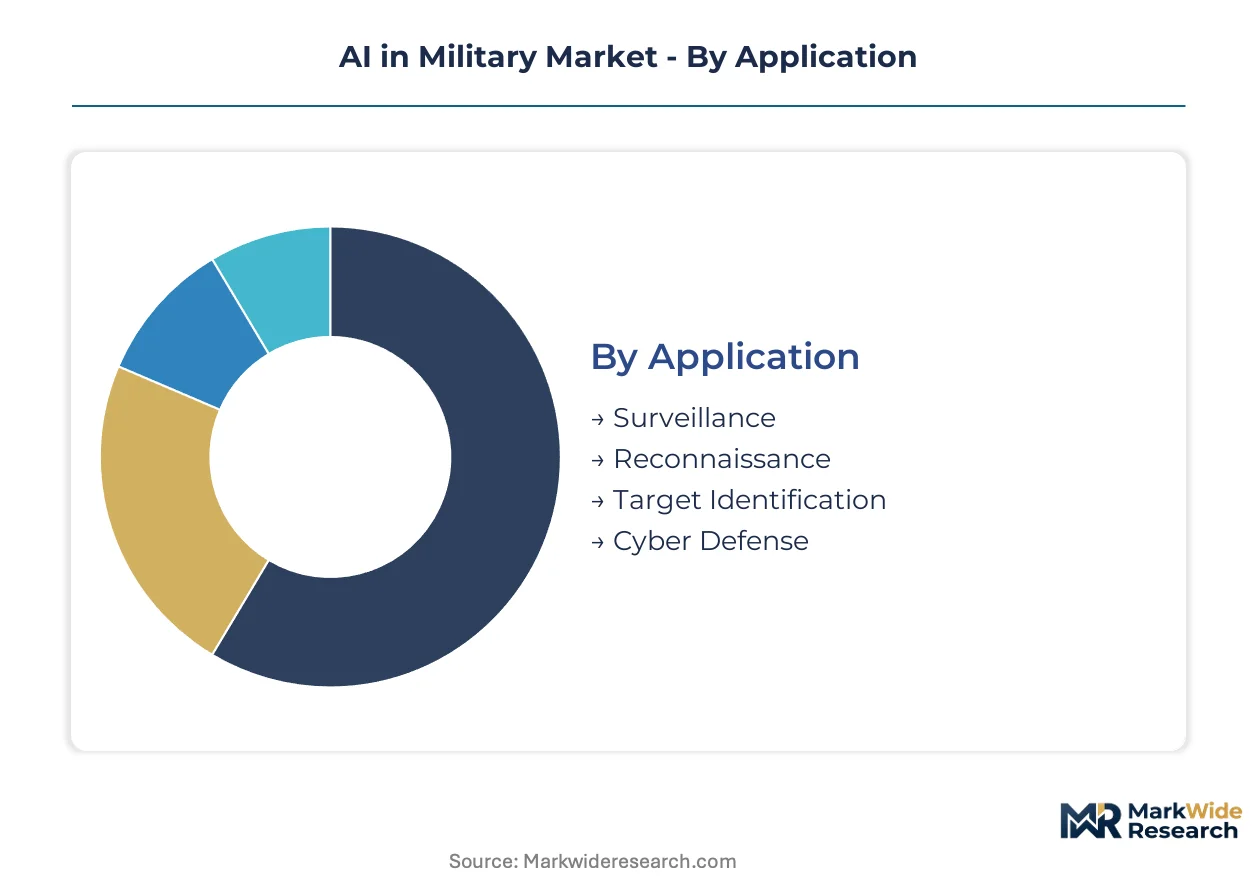
Military AI procurement fragments across mission-critical applications, underlying technologies, and institutional buyers with divergent security protocols. Each segmentation dimension reveals distinct vendor qualification thresholds and contracting rhythms that shape competitive positioning.
Application:
Standardized threat-detection algorithms compete against bespoke mission-specific systems across this category, with customization intensity rising sharply for classified operational environments.
- Surveillance:Multi-sensor fusion systems process electro-optical, infrared, and synthetic aperture radar feeds for persistent area monitoring. The Pentagon's Replicator initiative channels concentrated investment toward attritable autonomous surveillance platforms, compressing procurement cycles from years to months.
- Reconnaissance:High-altitude and deep-strike penetration systems integrate signals intelligence with real-time route planning. NATO's northern flank deployments in Norway and Sweden favor AI-driven predictive maintenance for Arctic reconnaissance assets where human intervention proves operationally costly.
- Target Identification:Neural network classifiers for kinetic strike authorization operate under strict rules-of-engagement protocols. Procurement concentrates in US Special Access Programs with limited vendor pools.
- Cyber Defense:Automated threat-hunting algorithms monitor network anomalies at machine speed. UK Defence AI Strategy mandates channel sovereign capability development toward domestic cyber defense vendors.
Most installed capacity flows through Surveillance. Expansion is steepest in Target Identification.
Technology:
Cost tiers separate mature commercial-adjacent tools from classified military-only architectures, with price premiums widening for systems requiring specialized hardware and cleared development environments.
- Machine Learning:Supervised learning pipelines for predictive maintenance and logistics optimization leverage commercial cloud infrastructure with security modifications. Signal intelligence automation absorbs the largest procurement budgets across US and UK defense agencies as electromagnetic spectrum operations intensify.
- Natural Language Processing:Multilingual intelligence exploitation systems process intercepted communications and open-source documents. European procurement under EU AI Act uncertainty delays foundation model contracts for weapons-adjacent NLP components.
- Neural Networks:Deep learning architectures for autonomous target recognition require specialized GPU clusters from Taiwan Semiconductor Manufacturing and Samsung Foundry, creating supply concentration risk. Federated learning deployments across Five Eyes intelligence-sharing agreements enable distributed training without centralizing classified data.
- Robotics:Edge-computing platforms for unmanned ground and aerial vehicles demand millisecond-latency inference. Competition centers on semiconductor fabricators and military software houses with facility clearances.
Machine Learning captures the dominant share of current procurement. Neural Networks are climbing the fastest as rules-of-engagement protocols evolve for lethal autonomous systems.
End User:
Customer type determines security clearance requirements, with classified program access creating steep barriers between tier-one primes and excluded mid-tier suppliers.
- Defense Contractors:Prime integrators like Lockheed Martin and BAE Systems manage multi-year development agreements requiring facility clearances and compartmentalized data access. Pentagon program executive offices consolidate vendor selection authority within this tier.
- Military Agencies:Service-specific research labs and operational commands procure tactical systems with compressed fielding timelines. US Army Futures Command and UK Defence Science and Technology Laboratory drive rapid experimentation-to-deployment pipelines.
- Research Institutions:University-affiliated laboratories and federally funded research centers develop foundational algorithms without immediate operational deployment. DARPA and AFRL contracts support basic research with longer evaluation horizons.
- Government Entities:Civilian defense agencies and intelligence community elements procure dual-use capabilities with distinct oversight protocols. NSA and GCHQ signal intelligence requirements shape specialized procurement frameworks.
Defense Contractors absorb the majority of algorithm development spending. Military Agencies are gaining share fastest as operational deployment accelerates beyond experimental phases.
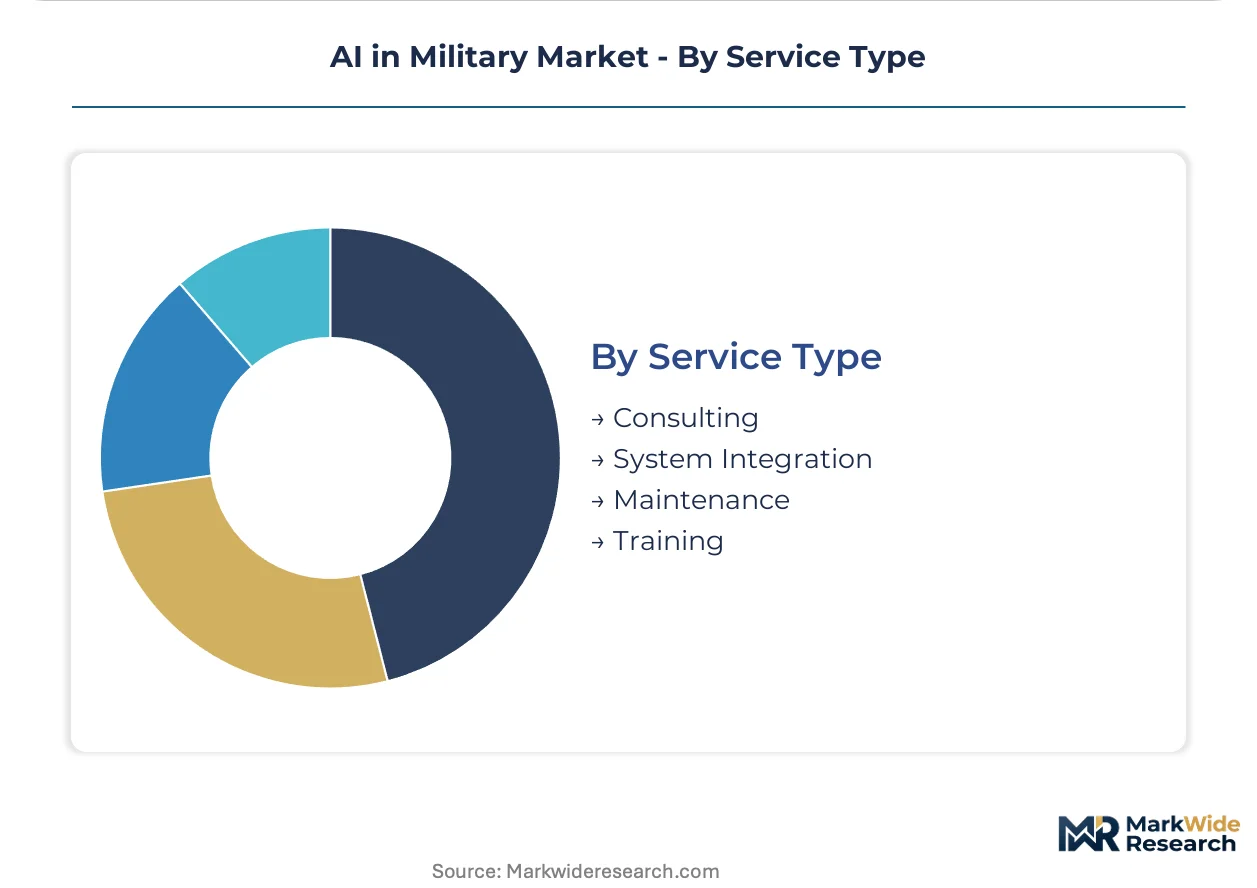
Service Type:
Margin structures vary from high-touch consulting engagements to recurring maintenance contracts, with profitability concentrating in services requiring sustained security clearances.
- Consulting:Strategic advisory on AI ethics, governance, and acquisition strategy supports defense agencies navigating Responsible AI Strategy implementation. Palantir Technologies competes on software-first architectures that reduce long-term consulting dependency.
- System Integration:Middleware development for legacy platform connectivity addresses Cold War-era command systems with proprietary data architectures. This service category faces friction from API-resistant infrastructure requiring expensive overlay deployment.
- Maintenance:Continuous algorithm certification and edge-computing hardware sustainment generate recurring revenue streams. Cleared technicians perform field updates for deployed autonomous systems under operational security constraints.
- Training:Workforce development for AI-enabled command systems spans operator certification and maintainer education. UK sovereign capability mandates create captive markets for domestic ethical algorithm certification services.
System Integration represents the largest current contract value. Maintenance is expanding most quickly as fielded autonomous systems require sustained algorithm update cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Washington DC metro area concentrates the dominant share of classified AI development contracts, with procurement authority consolidating within Pentagon program executive offices and driving vendor investment patterns across allied defense ecosystems.
United States
The Pentagon's Replicator initiative accelerates procurement timelines for attritable autonomous systems across multiple service branches. The Department of Defense's Responsible AI Strategy shapes ethics guidelines and vendor qualification frameworks. Northern Virginia's defense corridor hosts cleared development facilities where Lockheed Martin and Palantir Technologies sustain multi-year algorithm training agreements.
United Kingdom
The UK Defence AI Strategy channels sovereign capability mandates toward domestic software vendors and ethical algorithm certification services. British procurement offices prioritize facility-cleared contractors for classified development pipelines. The Defence Science and Technology Laboratory at Porton Down drives rapid experimentation-to-deployment pipelines for tactical AI systems.
China
Dual carbon goals and SAMR technical specifications enforce divergent procurement frameworks for energy-intensive neural network training infrastructure. GB standards fragment supplier certification requirements for dual-use AI components. Beijing's Zhongguancun technology corridor anchors state-directed development of autonomous surveillance and targeting systems.
Sweden
NATO's northern flank deployments favor AI-driven predictive maintenance for Arctic reconnaissance assets where human intervention proves operationally costly. Swedish-Norwegian bilateral agreements enable autonomous undersea and aerial sensor networks. Saab's Linköping facilities anchor Nordic sovereign capabilities in electronic warfare algorithm development.
Germany
The Bundeswehr's multi-domain task force integration creates demand for unified command algorithms fusing orbital and terrestrial intelligence streams. EU AI Act liability uncertainty freezes pre-contract negotiations for foundation model contracts. Munich's defense industrial cluster hosts cleared middleware development for legacy platform AI overlay deployment.
AI in Military Market Vendor Landscape
Global majors compete with regional champions across cleared facility access and algorithm certification authority. The vendor base stratifies between tier-one primes with compartmentalized data access and excluded mid-tier suppliers lacking security clearances. Two strategic archetypes dominate: heritage defense conglomerates leveraging Skunk Works-style classified pipelines, and software-first challengers reducing hardware lock-in through modular architectures. Consolidation concentrates through multi-year development agreements and continuous certification contracts rather than discrete platform milestones.
Within the heritage prime tier, Lockheed Martin Corporation and BAE Systems plc exemplify facility-cleared incumbents capturing algorithm training data contracts through compartmentalized development environments. Palantir Technologies occupies a distinct software-native position, representing the challenger archetype that competes on architecture flexibility rather than hardware integration depth.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Thales Group |
| L3Harris Technologies |
| General Dynamics Corporation |
| Leonardo S.p.A. |
| Palantir Technologies |
| Others |
Supply Flow & Price Mechanics
Cleared AI engineering talent clustering in the Washington DC metro area and Northern Virginia defense corridor drives labor-cost differentials that separate premium-tier algorithm development contracts from commoditized maintenance services. Pricing stratifies across facility-cleared development, standard government contracting, and commercial-adjacent support tiers based on security clearance depth and compartmentalized data access.
Pricing Analysis
Input-cost pass-through from specialized GPU clusters and cleared labor pools shapes contract structures across the military AI market. Three-tier pricing separates compartmentalized Special Access Program development from standard federal procurement and commercial software licensing. Price differentiation rests on certification grade—facility clearances and polygraph requirements—and customization level for rules-of-engagement protocols. Cost compression in the commercial-adjacent tier is intensifying because cloud infrastructure providers compete for modified-security workloads. Defense contractors with existing clearances exhibit the lowest price sensitivity; mid-tier software vendors without facility access face the highest.
Supply Chain Analysis
Dual-sourcing requirements for neural network training hardware mandate multi-supplier qualification across Taiwan, South Korea, and the United States for advanced GPU and ASIC fabrication. Raw material dependencies center on high-purity silicon wafers, rare earth elements for magnetics, and specialized cooling systems for edge-computing deployments. Single-source vulnerability concentrates with Taiwan Semiconductor Manufacturing for leading-edge process nodes, creating geopolitical exposure that defense procurement offices mitigate through strategic stockpiling. Distribution runs through cleared prime integrators—Lockheed Martin, BAE Systems, RTX Corporation—who control algorithm certification authority and compartmentalized delivery channels.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement offices prioritize algorithmic reliability and ethical certification over cost minimization, reflecting demand-shift toward premium specifications for lethal autonomous decision systems.
For Market Incumbents: Deepen backward integration into cleared semiconductor packaging and testing facilities to secure supply continuity against Taiwan Strait disruption. Fortify algorithm bias audit capabilities to preempt Responsible AI Strategy compliance gaps that emerging software-native challengers exploit. Facility-cleared incumbents should consolidate subcontractor networks before mid-tier suppliers achieve security clearance thresholds. For New Entrants and Emerging Players: Capture white-space in ethical algorithm certification services and federated learning middleware where heritage primes lack software-native agility. The UK Defence AI Strategy creates the most penetrable entry point through sovereign capability mandates that favor domestic vendors. A software-first architecture approach reduces hardware lock-in and accelerates procurement qualification cycles. For Investors and Strategic Acquirers: Prime defense contractors with excess cash reserves are the most active acquirer in this space, targeting software-native specialists with facility clearances and compartmentalized development pipelines. Long-term viability centers on continuous algorithm certification revenue rather than discrete platform milestones. Watch for EU AI Act liability boundary clarifications as the inflection indicator that unfreezes European foundation model procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Facility Clearance Acquisition | Unlocks Pentagon Replicator program and Special Access Program algorithm training contracts. |
| Federated Learning Platform Deployment | Enables Five Eyes intelligence sharing without centralizing classified operational datasets. |
| Ethical Algorithm Certification Service Launch | Captures UK sovereign capability mandates and EU defense exemption preparation demand. |
| Edge-Computing Hardware Co-Design | Reduces inference latency for attritable autonomous systems under Replicator initiative timelines. |
| Legacy Platform Middleware Integration | Addresses Cold War-era command system API resistance through expensive overlay deployment. |
Methodological Framework
Bottom-up defense contractor and military agency procurement tracking reconciled against top-down semiconductor supply-side monitoring forms the analytical core of this study. Primary interviews with program executive officers, cleared facility security officers, algorithm certification leads, and federal procurement specialists combined with secondary validation from Department of Defense budget justification materials, SEC 10-K filings of defense primes, NATO data governance framework documents, and EU AI Act regulatory drafts. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Historical trendline analysis of classified program spending and unclassified AI research appropriations established baseline growth patterns across the analysis window. The forecast framework models segmentation dimensions including application type—surveillance, reconnaissance, target identification, cyber defense—technology tier—machine learning, neural networks, natural language processing, robotics—and end-user category—defense contractors, military agencies, research institutions, government entities. CAGRs derive from procurement cycle compression rates and rules-of-engagement protocol evolution timelines. Edge-computing hardware fielding schedules and federated learning deployment trajectories serve as industry-specific forecast inputs.
Geopolitical escalation, EU AI Act liability boundary revisions, and Taiwan Strait supply disruption are the dominant revision risks to the outlook. Deviation in classified procurement threshold adjustments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Aerospace Consulting Services Market