
 Virtual Reality in Aerospace and Defense Market | 2026-2036
Virtual Reality in Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality in Aerospace and Defense Market Intelligence
The rising emphasis on battlefield simulation is restructuring procurement priorities away from traditional hardware-only training systems. This shift favors firms with deep software and integration expertise. CAE Inc. specializes in high-fidelity flight simulation platforms for pilot training across military and civilian sectors. BAE Systems plc leverages its extensive defense portfolio to integrate VR into complex mission training environments. Thales Group competes by offering solutions that span both simulation hardware and tactical planning software.
Virtual reality in aerospace and defense involves creating immersive, computer-generated environments for training, design, and operational planning. These systems often require head-mounted displays with high-resolution screens and low-latency tracking to ensure user safety and simulation fidelity. Within the technology stack, haptic feedback and eye tracking are gaining traction over more basic gesture recognition systems. The use case for pilot training remains the largest segment, while equipment maintenance applications represent the fastest-growing area due to cost-saving potential.
Regulatory bodies establish the certification standards for VR-based training systems, directly influencing market access and product design. In the United States, the FAA sets requirements for using flight simulation platforms in pilot certification, while military procurement in countries like the UK and France adheres to stringent defense-specific standards. Stakeholder success will depend on navigating the complex interplay between commercial off-the-shelf technology costs and the rigorous validation demanded by aviation and defense authorities.
Market Dynamics
The central force shaping the market is the strategic pivot by defense and aviation authorities toward high-fidelity simulation to reduce operational costs and improve safety. This demand for realism favors integrated software and hardware solutions over standalone components.
Growth Catalysts
- Cost-Effective Pilot Training:The rising cost of live flight hours and aircraft maintenance compels commercial airlines and air forces to adopt VR simulators. Aviation authorities like the FAA are expanding the scope of training credits achievable through certified simulation, accelerating this transition.
- Advanced Display Technology:Continuous improvements in the resolution, field-of-view, and refresh rates of head-mounted displays (HMDs) are enhancing immersion and reducing cybersickness. This technological maturation makes VR viable for longer, more intensive training sessions.
- Battlefield Simulation Demand:Military end-users are increasing investment in complex, networked VR environments for joint-force mission rehearsal. These systems allow for the simulation of multi-domain operations that are too costly or dangerous to conduct in live exercises.
Market Restraints
- High Initial Investment:The procurement and integration of full-motion, high-fidelity VR simulation platforms with haptic feedback systems require significant upfront capital expenditure. This cost can be prohibitive for smaller airlines or defense contractors with limited budgets.
- Technical Limitations:Issues such as vestibular mismatch, which can induce nausea and disorientation, remain a technical barrier. This limits the duration of effective training sessions and can impact user adoption and training effectiveness for sensitive individuals.
- Stringent Certification Processes:Gaining certification from regulatory bodies like EASA or national defense agencies for VR training systems is a lengthy and expensive process. The rigorous validation required for safety-critical applications slows market entry for new technologies.
Strategic Opportunities
- Maintenance and Repair Applications:Developing VR tools for complex equipment maintenance, repair, and overhaul (MRO) presents a significant growth avenue. These applications offer clear ROI by reducing errors, speeding up repairs, and minimizing aircraft downtime.
- AI-Driven Adaptive Training:Integrating artificial intelligence with VR simulators allows for the creation of dynamic training scenarios. These systems can adapt in real-time to a trainee's performance, identify skill gaps, and personalize difficulty for more effective learning outcomes.
- Expansion in Emerging Defense Markets:Defense modernization programs in countries such as India and Australia create new opportunities. These nations are looking to procure advanced simulation capabilities to train personnel on newly acquired military platforms.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complexity of integrating modern VR training platforms with existing, often decades-old, military hardware and command-and-control software. This challenge requires specialized systems integration expertise.
- Specialized Talent Scarcity:The market faces a shortage of developers and engineers who possess a dual expertise in aerospace systems and advanced real-time 3D simulation engines. This talent gap can delay project timelines and increase development costs.
- Lack of Interoperability Standards:The absence of universal standards for VR hardware and software complicates joint training exercises. Incompatibility between systems from different vendors hinders the ability of allied forces to train together in a shared virtual environment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality in Aerospace and Defense Market |
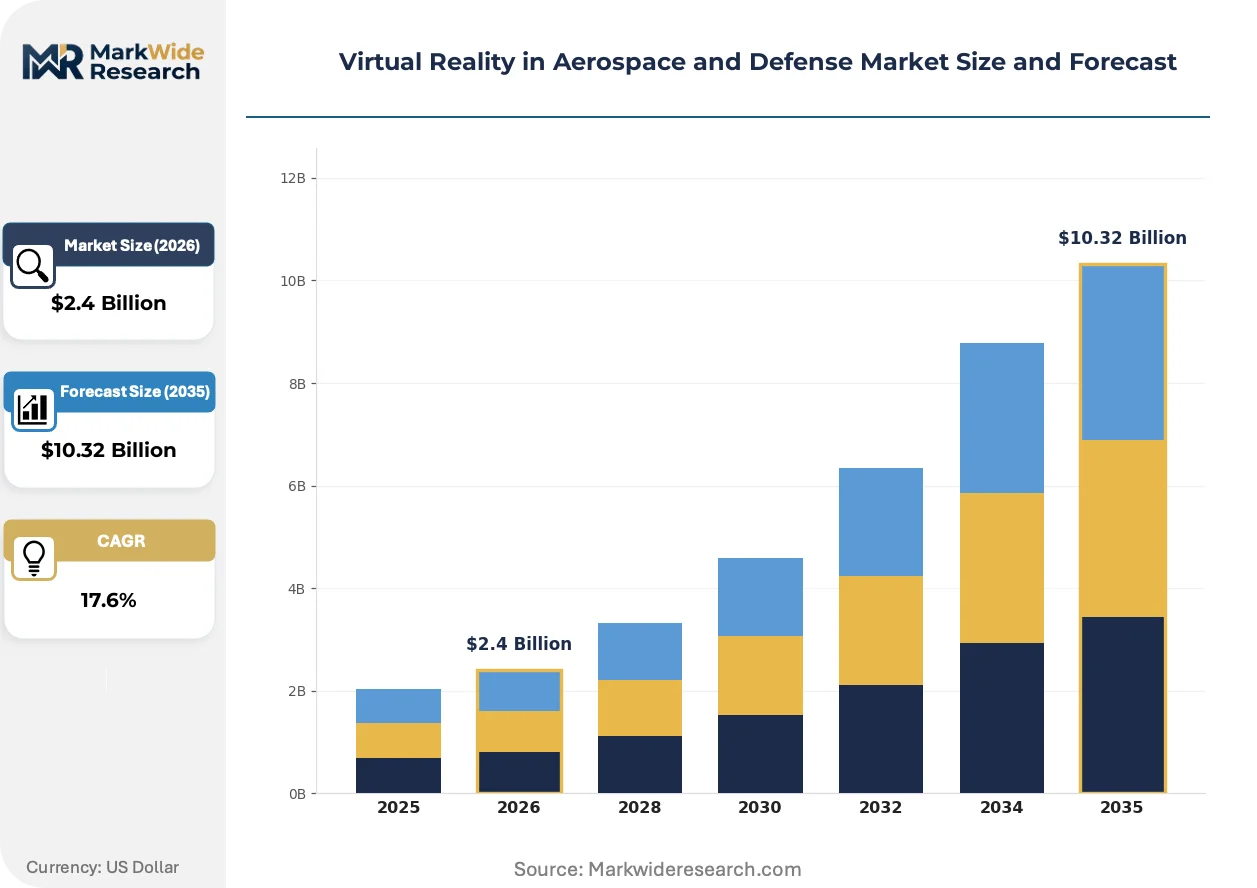
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $10.32 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Simulation Platforms, Mission Training Software, Maintenance Support Systems, Design Visualization Tools Technology: Head-Mounted Displays, Gesture Recognition, Eye Tracking, Haptic Feedback, Spatial Audio Use Case: Pilot Training, Battlefield Simulation, Equipment Maintenance, Tactical Planning, Disaster Response Preparedness End User: Aircraft Manufacturers, Defense Contractors, Military Training Centers, Aviation Maintenance Providers |
| Companies Covered | Lockheed Martin Corporation, BAE Systems plc, Thales Group, CAE Inc., Microsoft Corporation, Northrop Grumman Corporation, Indra Sistemas, Red Six Aerospace, Varjo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality in Aerospace and Defense Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward hyper-realistic, data-driven simulation. This trend moves beyond basic visualization, aiming to create predictive and responsive virtual environments that mirror the complexities of real-world aerospace and defense operations.
Advanced haptic feedback technology provides users with tactile sensations, such as cockpit vibrations or the recoil of a weapon system. Military pilot training and infantry simulation segments are the primary adopters, seeking to build muscle memory and heighten situational awareness. This technology is consolidating the market around full-immersion solutions, marginalizing platforms that lack realistic physical feedback for critical skill development.
New certification guidelines from bodies like the European Union Aviation Safety Agency (EASA) are formalizing the use of VR in pilot training. These regulations establish clear performance criteria for Flight Simulation Training Devices, creating a defined pathway for manufacturers to gain approval. The commercial flight school segment in Europe is most directly impacted, needing to align procurement with these EASA standards.
A transition toward subscription-based Simulation-as-a-Service (SaaS) models is altering software procurement patterns. This approach replaces large, one-time capital outlays with predictable, recurring operational expenses that include continuous content updates and technical support. This model is gaining traction within defense organizations in the United Kingdom, enabling more flexible budgeting and faster access to updated threat scenarios.
Virtual Reality in Aerospace and Defense Market Segmentation
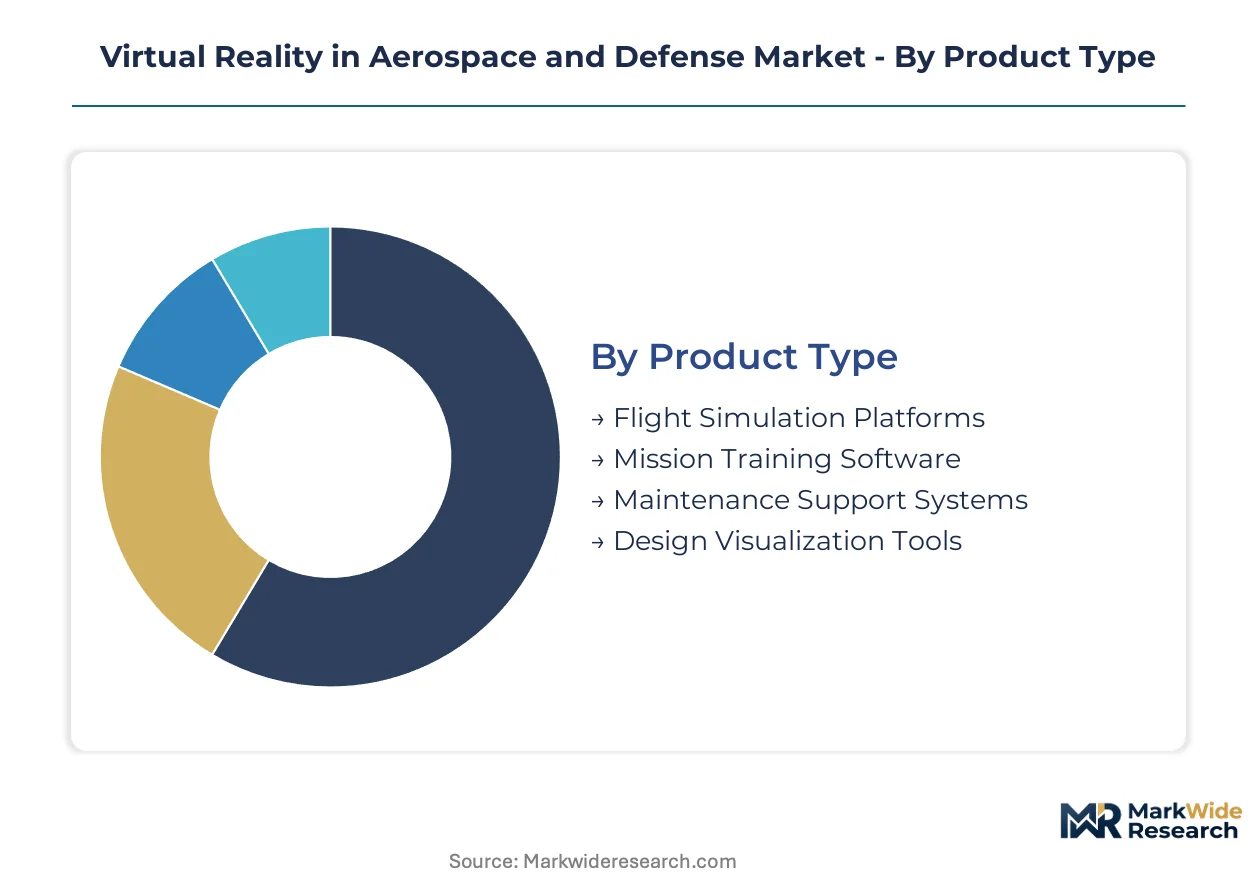
The virtual reality in aerospace and defense market is segmented to reflect the diverse applications and technological requirements across military and commercial aviation. This detailed breakdown helps stakeholders understand where specific investments are being made and how different components contribute to overall market growth and capability enhancement.
Product Type:
Buyer decisions for virtual reality products in aerospace and defense hinge on the operational functionality and integration capabilities required for specific training or development needs.
- Flight Simulation Platforms:These are comprehensive systems designed to replicate aircraft cockpits and flight dynamics, providing immersive training for pilots. Demand concentrates in both military air forces and commercial airlines, driven by the need for cost-effective, high-fidelity pilot certification.
- Mission Training Software:This software creates complex, dynamic virtual environments for rehearsing multi-domain operations and strategic planning. Military end-users in countries like the United States increasingly demand these systems to prepare for joint-force exercises and complex battlefield scenarios.
- Maintenance Support Systems:These tools utilize VR for guided repairs, equipment assembly, and diagnostic procedures, often employing augmented reality overlays. These systems offer clear return on investment by reducing errors and minimizing aircraft downtime.
- Design Visualization Tools:These platforms allow engineers and designers to interact with virtual prototypes of aircraft or defense systems. Product development teams use these for ergonomic assessments and early-stage design reviews.
Volume sits with Flight Simulation Platforms; growth tilts toward Maintenance Support Systems.
Technology:
Application requirements dictate the selection of specific virtual reality technologies, influencing immersion levels and user interaction.
- Haptic Feedback:This technology provides tactile sensations, such as vibrations or resistance, to enhance realism within virtual environments. Military pilot training benefits significantly from haptic feedback, building muscle memory for critical controls.
- Head-Mounted Displays:These devices provide high-resolution visual immersion with wide fields of view and low latency, forming the core interface for VR systems. Continuous improvements in display technology drive adoption across all segments, reducing cybersickness.
- Eye Tracking:This technology monitors a user's gaze within the virtual environment, providing data for performance assessment and adaptive training scenarios. Training centers utilize eye tracking to analyze pilot attention and decision-making processes.
- Spatial Audio:Spatial audio systems create realistic 3D soundscapes, enhancing situational awareness and immersion in virtual training environments. Battlefield simulation benefits from accurate sound cues for threat identification.
- Gesture Recognition:This technology allows users to interact with virtual objects using natural hand movements without physical controllers. Early-stage design visualization tools often incorporate gesture recognition for intuitive model manipulation.
Technological advancements continue to refine Head-Mounted Displays, while Haptic Feedback expands its functional integration.
Use Case:
Customer priorities in the aerospace and defense sector shape the primary use cases for virtual reality, focusing on critical operational needs.
- Pilot Training:This segment involves using VR for flight instruction, emergency procedure drills, and aircraft system familiarization for both military and commercial aviators. Regulatory bodies like the FAA in the United States are expanding training credits for certified VR simulators.
- Equipment Maintenance:VR applications in this area focus on guiding technicians through complex repair procedures, troubleshooting, and assembly of aerospace and defense hardware. This use case represents the fastest-growing area due to significant cost-saving potential.
- Battlefield Simulation:These complex networked environments allow military personnel to rehearse joint-force operations and tactical maneuvers. Defense organizations in the United Kingdom are increasing investment in these multi-domain training systems.
- Tactical Planning:VR tools enable commanders and strategists to visualize battlefields, plan missions, and analyze potential outcomes in a 3D immersive space. This aids in preparing for complex operations by offering detailed environmental awareness.
- Disaster Response Preparedness:VR simulates emergency scenarios, allowing first responders and military units to practice coordination and decision-making under high-stress conditions. Training exercises for humanitarian aid missions leverage these virtual environments.
Pilot Training remains the foundational application, with Equipment Maintenance demonstrating significant market expansion.
End User:
The volume of virtual reality system procurement varies across end-user segments, reflecting distinct operational scales and investment capacities.
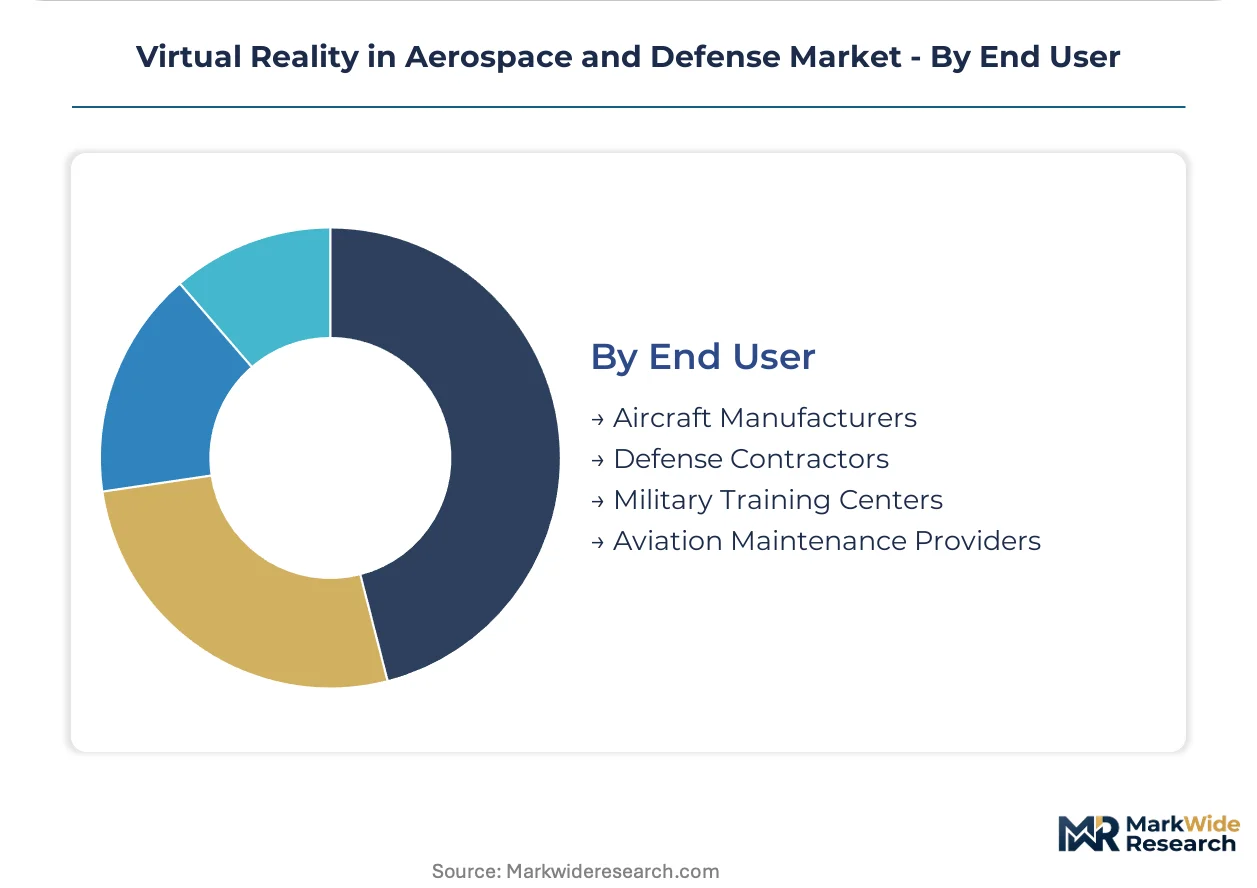
- Military Training Centers:These facilities are major procurers of VR systems for pilot training, battlefield simulation, and equipment maintenance for armed forces personnel. Investment is driven by the need to reduce live training costs and enhance combat readiness.
- Defense Contractors:These companies develop and integrate VR solutions for various defense applications, often serving as prime contractors for government agencies. BAE Systems plc leverages its extensive defense portfolio to integrate VR into mission training.
- Aircraft Manufacturers:These firms utilize VR for design visualization, engineering reviews, and quality control during the development and production of new aircraft. Boeing and Airbus integrate VR into their product lifecycle management.
- Aviation Maintenance Providers:These organizations adopt VR to train technicians, improve repair efficiency, and reduce errors in the maintenance, repair, and overhaul (MRO) of aircraft. Cost reduction and safety compliance are key drivers.
Investment strategies are concentrated within Military Training Centers, while Aviation Maintenance Providers represent a growing procurement channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global virtual reality in aerospace and defense market exhibits a clear divide between concentrated production and widespread consumption. While demand for advanced simulation capabilities spans numerous nations, technological innovation and manufacturing hubs remain largely centered in a few key economies. These regions drive both the adoption of VR solutions and the development of next-generation training systems.
United States
The United States drives significant demand for VR in aerospace and defense, fueled by substantial defense sector investment and extensive pilot training requirements. The FAA sets stringent requirements for flight simulation platforms used in pilot certification, guiding product development. Defense contractors in the Washington D.C. metropolitan area and tech firms in California's Silicon Valley actively develop and integrate these advanced VR solutions.
United Kingdom
United Kingdom military end-users are increasing investment in complex battlefield simulation and mission training environments. UK defense procurement adheres to stringent defense-specific standards for VR systems, impacting market entry. Aerospace clusters around Bristol and Farnborough concentrate development efforts for advanced flight simulators.
France
French defense authorities prioritize VR for tactical planning and high-fidelity mission rehearsal across their armed forces. EASA standards influence the certification of commercial flight simulators, ensuring high realism levels. The Aerospace Valley in Toulouse serves as a key hub for aviation simulation technology development.
Germany
German air force and commercial aviation sectors seek advanced VR solutions for pilot training, emphasizing high-resolution HMDs. EASA regulations also shape the development and approval of VR flight simulation training devices within Germany. Aerospace and defense firms in Bavaria and Hamburg contribute to cutting-edge VR simulator platforms.
Japan
Japan's ongoing military modernization programs are increasing demand for advanced VR simulation capabilities to train personnel on new platforms. The Ministry of Economy, Trade and Industry (METI) supports technological advancements in simulation, influencing domestic development. Technology firms in Tokyo and defense contractors in Nagoya actively contribute to VR system integration.
Virtual Reality in Aerospace and Defense Market Key Industry Players
Top-tier vendors anchor the market for large-scale, integrated virtual reality solutions in aerospace and defense, while specialized firms focus on niche technologies. The market structure includes integrated defense primes, pure-play simulation providers, and technology specialists. Strategic partnerships for systems integration and portfolio diversification into software solutions represent dominant competitive moves.
Integrated defense primes like Lockheed Martin Corporation and BAE Systems plc exemplify companies offering comprehensive virtual reality solutions, often leveraging their broad defense portfolios for complex mission training environments. These entities frequently anchor large-scale government contracts for high-fidelity simulation systems and integration services. In contrast, CAE Inc. represents a pure-play simulation specialist, providing high-fidelity flight simulation platforms across both military and civilian sectors. CAE's focus on advanced flight dynamics and immersive cockpits positions it as a key provider for pilot training across global air forces and airlines.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems plc |
| Thales Group |
| CAE Inc. |
| Microsoft Corporation |
| Northrop Grumman Corporation |
| Indra Sistemas |
| Red Six Aerospace |
| Varjo |
| Others |
Cost & Logistics Intelligence
Sovereign-backed defense contractors and private equity-rolled-up simulation specialists drive the market's pricing discipline, reflecting concentrated supply and the high capital expenditure required for advanced VR platforms. Their investment cycles directly influence the availability and cost of next-generation training systems.
Pricing Analysis
Cost-down pressure on commercial aviation VR solutions accelerates because airlines seek to offset rising operational expenses with more affordable training. The dominant pricing model for high-fidelity flight simulators is project-based, often including long-term service contracts. Price differentiation stems from certification level, such as FAA or EASA approval, and the degree of customization for specific aircraft platforms. Military training centers exhibit lower price sensitivity due to mission-critical requirements, while smaller commercial flight schools are highly sensitive to initial capital outlay.
Supply Chain Analysis
Regional distribution centers for advanced VR components often operate from the United States and Germany, supporting localized integration and deployment. The supply chain for VR in aerospace and defense draws from high-resolution display panels, specialized haptic feedback mechanisms, and low-latency tracking sensors. Single-source vulnerability for these specialized components represents a key structural risk. Downstream distribution typically runs through direct sales channels and specialized systems integrators, especially for defense contracts requiring secure delivery and custom installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virtual reality in aerospace and defense market is evolving into a vertical integration race, as companies pursue control over high-fidelity software platforms to enhance simulation realism and reduce reliance on third-party developers.
For Market Incumbents:Cement market leadership by acquiring specialized software developers focusing on AI-driven adaptive training algorithms. Incumbents should also invest heavily in securing certification pathways for next-generation VR systems across multiple regulatory bodies like FAA and EASA, mitigating market entry barriers for emerging entrants. This dual strategy protects against technical obsolescence and regulatory shifts.
For New Entrants and Emerging Players:Smaller commercial flight schools and regional defense forces represent an underserved buyer archetype ripe for disruption. Target these segments with cost-effective, modular VR solutions focused on specific training modules rather than full-scale platforms. A go-to-market angle emphasizing rapid deployment and subscription-based Simulation-as-a-Service (SaaS) models can accelerate adoption within these budget-conscious organizations.
For Investors and Strategic Acquirers:Widespread EASA certification approval for VR-based pilot training systems is the leading indicator that the market is ready for accelerated long-term growth over the next five to ten years. Acquisition targets should include specialized haptic feedback technology providers or firms with deep expertise in integrating VR with legacy military hardware. Monitor defense modernization program budgets in emerging markets for early signs of significant procurement increases.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI-Driven Training Software Firms | This enhances dynamic scenario generation and personalized learning paths for military and commercial aviators. |
| Investment in Advanced Haptic Feedback R&D | This improves simulation realism and builds critical muscle memory for pilots and maintenance technicians. |
| Expansion of SaaS Model Offerings | This provides flexible procurement options and continuous content updates for defense organizations and flight schools. |
| Pursuit of Multi-National Regulatory Certifications | This broadens market access and validates training effectiveness for VR systems across diverse geographies. |
| Development of VR Solutions for MRO Applications | This addresses the fastest-growing use case, reducing operational errors and aircraft downtime for airlines. |
Research Approach
FAA certification documents, EASA regulatory guidelines, and defense procurement reports formed the secondary backbone for this market analysis. This was complemented by primary interviews with aerospace engineers, military training officers, commercial airline procurement managers, and VR technology developers. The study integrated insights from both bottom-up market sizing and top-down validation, ensuring comprehensive data triangulation.
A bottom-up analytical approach estimated market size by aggregating data across product types, technologies, use cases, and end-user segments, then validated through top-down industry projections. Compound annual growth rates were derived from historical trends and anticipated technological advancements over the projection horizon. Key forecast inputs included defense spending allocations and commercial aviation fleet expansion plans.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and rapid technological obsolescence. This study's projections reflect assumptions regarding regulatory stability and sustained investment in simulation capabilities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market