
 Global Signals Intelligence (SIGINT) Market | 2026-2036
Global Signals Intelligence (SIGINT) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Signals Intelligence (SIGINT) Market Foresight
Consolidation among defense procurement agencies is repositioning contract structures toward multi-year platform awards. Lockheed Martin leverages its integrated electronic warfare portfolio to anchor long-term military relationships. BAE Systems competes through sovereign UK manufacturing capacity and deep European intelligence partnerships. Thales Group differentiates via dual-use civil-military signal processing architectures that span NATO interoperability requirements.
Signals Intelligence denotes the discipline of intercepting, collecting, and analyzing electromagnetic transmissions to extract actionable information, encompassing communications intelligence and electronic intelligence gathered across radio frequency, microwave, and optical spectra. Interception equipment and software defined radio technologies dominate current procurement volumes, while data analysis tools represent the fastest-expanding margin pool as artificial intelligence-enabled processing reduces analyst-to-signal ratios. Military surveillance applications sustain the largest revenue base, though cybersecurity monitoring is displacing traditional budget allocations among intelligence organizations seeking integrated cyber-electromagnetic capabilities.
The US Department of Defense and NATO standardization agreements shape equipment interoperability mandates, while national regulators including the UK's National Cyber Security Centre and Israel's Ministry of Defense certify encryption analysis and frequency management systems for classified deployment. The EU's developing defense procurement frameworks are forcing non-European suppliers to establish continental production footprints or face market access restrictions. Stakeholders must monitor how sovereign data-localization requirements and allied technology-sharing agreements reshape competitive positioning in electromagnetic spectrum operations.
Market Dynamics
Defense procurement agencies across NATO member states are consolidating contract structures toward multi-year platform awards, compressing vendor selection cycles and privileging integrated electronic warfare portfolios over point solutions.
Growth Catalysts
- EU Strategic Autonomy Framework:Sovereign capability investments are accelerating as Brussels mandates continental production footprints for classified systems access.
- Artificial Intelligence-Enabled Processing:Machine learning algorithms are reducing analyst-to-signal ratios, expanding addressable mission sets for intelligence organizations.
- Electromagnetic Spectrum Superiority:United States, United Kingdom, and Israel defense agencies prioritize spectrum dominance, concentrating procurement volumes in interception equipment and software-defined radio technologies.
Market Restraints
- Export Control Regimes:US International Traffic in Arms Regulations and EU dual-use restrictions fragment supplier access across allied markets.
- Specialized Talent Scarcity:Cryptographic analysis and frequency management expertise concentrates in Tel Aviv, Cheltenham, and Fort Meade labor pools.
- Encryption Proliferation:Commercial quantum-resistant algorithms are outpacing classical decryption capabilities, degrading intercept value.
Strategic Opportunities
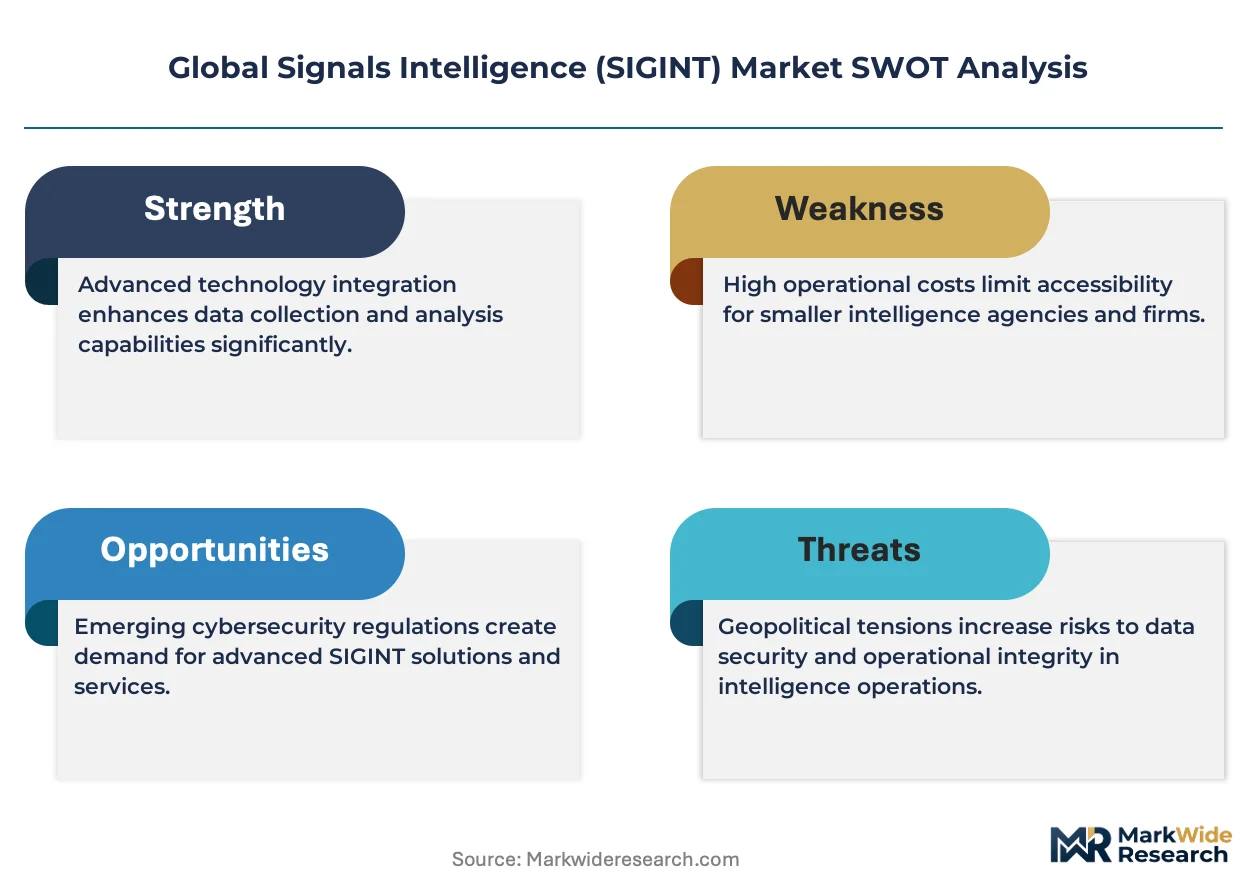
- Cyber-Electromagnetic Convergence:Integrated cyber-SIGINT platforms are displacing siloed budget allocations among Five Eyes intelligence services.
- Civil-Military Dual-Use Architectures:Satellite signal processing systems developed for aviation safety are migrating to defense applications under NATO interoperability mandates.
- Poland and Baltic States:Frontline NATO members are establishing sovereign SIGINT capabilities independent of legacy Warsaw Pact infrastructure.
Industry Challenges
- Security Clearance Bottlenecks:Personnel vetting timelines for compartmented programs extend 18-24 months, constraining workforce scaling.
- Legacy System Integration:Cold War-era intercept platforms require costly middleware development to interface with cloud-native analytics architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Signals Intelligence (SIGINT) Market |
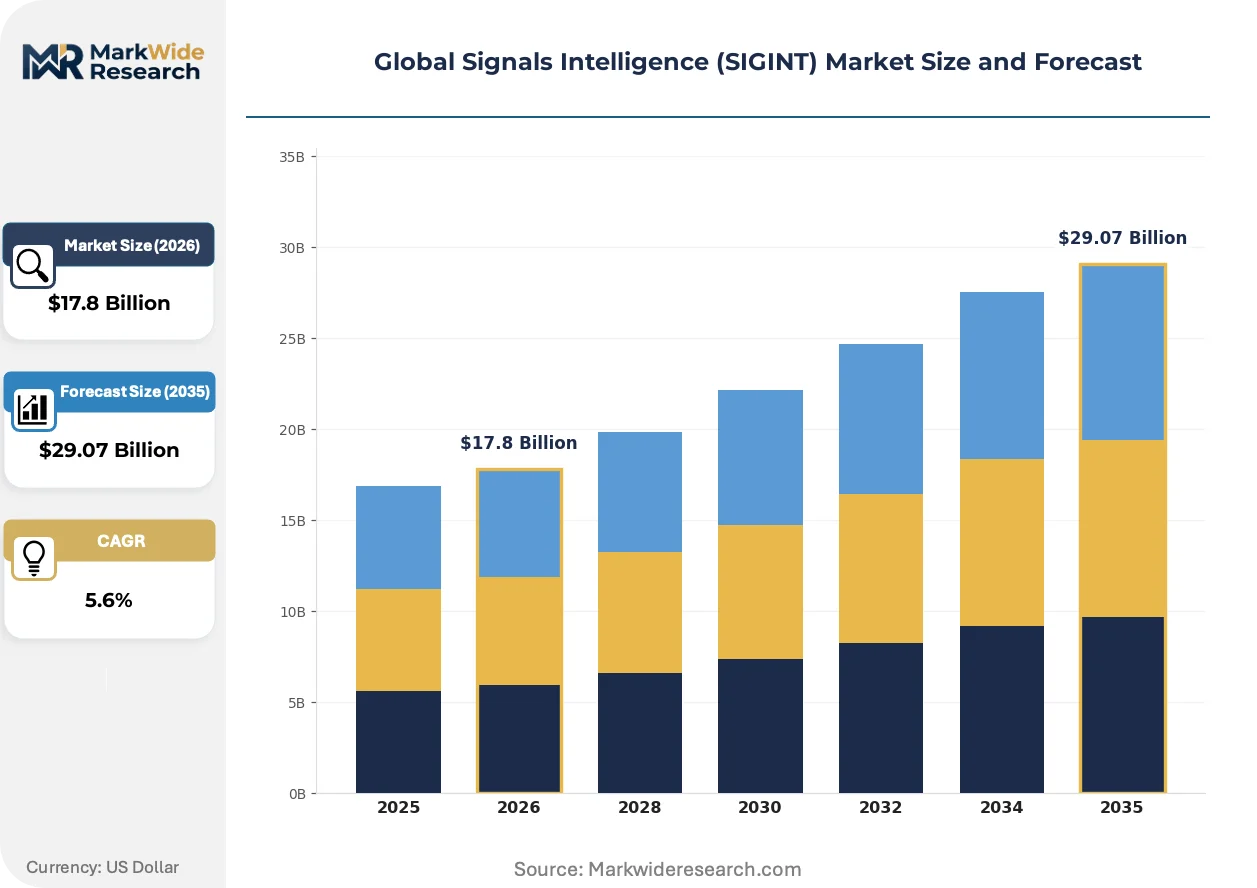
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $29.07 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interception Equipment, Signal Processors, Antenna Systems, Data Analysis Tools, Communication Receivers Technology: Software Defined Radio, Direction Finding, Digital Signal Processing, Frequency Management, Encryption Analysis Application: Military Surveillance, Counterterrorism Operations, Cybersecurity Monitoring, Electronic Warfare, Border Security End User: Defense Agencies, Intelligence Organizations, Law Enforcement Units, Homeland Security, Cyber Defense Firms |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, Raytheon Technologies, Thales Group, General Dynamics, L3Harris Technologies, Elbit Systems, HENSOLDT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Signals Intelligence (SIGINT) Market Shifts & Advancements
Software-defined architectures are dissolving hardware-software boundaries in signal processing, enabling rapid reconfiguration across frequency bands and mission types without physical equipment swaps.
Software-defined radio technology is modularizing traditional fixed-function intercept hardware into reprogrammable signal chains. Defense agencies in the United States and Israel are fielding multi-mission platforms that reconfigure via firmware updates. This compression of hardware refresh cycles is shifting supplier margins toward persistent software licensing arrangements.
EU AI Act risk classification frameworks are mandating human-in-the-loop oversight for automated signal classification systems deployed in member states. Equipment vendors must now document algorithmic decision pathways for national security regulators. French and German certification bodies are requiring interpretability standards that slow deployment of opaque deep learning models.
Multi-year platform awards are compressing vendor selection windows from 36 months to 18 months for NATO electronic warfare procurements. Prime contractors are absorbing subsystem suppliers to guarantee integrated delivery timelines. This concentration is most visible in UK Ministry of Defence programs, where BAE Systems and Thales Group now compete on total-system accountability rather than component specifications.
Global Signals Intelligence (SIGINT) Market Segmentation
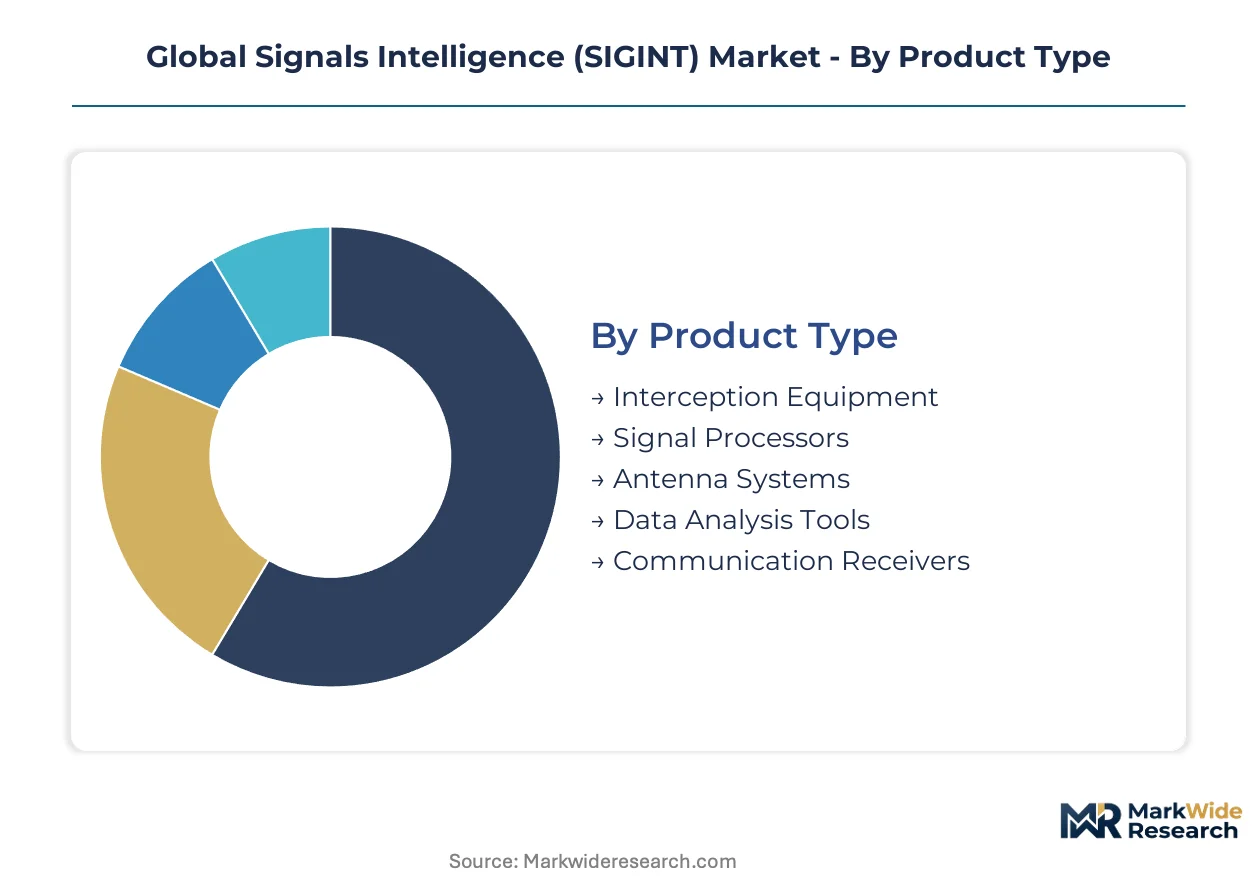
Segmentation in the SIGINT market reveals how procurement patterns bifurcate between hardware refresh cycles and software capability upgrades. Defense agencies prioritize platform longevity while intelligence services chase analytical throughput.
Product Type:
Upgrade cycles vary dramatically across equipment categories, with software-centric tools refreshing faster than physical intercept hardware.
- Interception Equipment:Ruggedized receivers and tunable front-ends designed for electromagnetic spectrum capture across VHF through millimeter-wave bands. United States Navy surface combatants and Israeli Defense Forces mobile units drive procurement volumes for multi-band platforms that survive harsh electronic warfare environments.
- Data Analysis Tools:Artificial intelligence-enabled processing suites that reduce analyst-to-signal ratios through automated classification and anomaly detection. United Kingdom Government Communications Headquarters and Australian Signals Directorate are displacing legacy budget allocations toward these platforms as intercept volumes overwhelm human processing capacity.
- Signal Processors:FPGA-based compute modules executing real-time demodulation and protocol extraction.
- Antenna Systems:Directional arrays and conformal apertures for airborne and maritime platforms.
- Communication Receivers:Wideband digitizers feeding software-defined signal chains.
Volume placements concentrate in Interception Equipment; the faster expansion belongs to Data Analysis Tools.
Technology:
Cost tiers separate mature analog techniques from digital architectures commanding premium pricing.
- Software Defined Radio:Reprogrammable signal chains that reconfigure via firmware updates without hardware swaps. United States Special Operations Command and NATO airborne early warning programs are fielding multi-mission platforms that compress refresh cycles from years to months.
- Encryption Analysis:Cryptanalytic systems targeting commercial and military cipher implementations. Israel's Ministry of Defense and United Kingdom National Cyber Security Centre certify these for classified deployment as quantum-resistant algorithms proliferate.
- Direction Finding:Geolocation algorithms processing time-difference-of-arrival data.
- Digital Signal Processing:Filter banks and transform engines for real-time spectrum manipulation.
- Frequency Management:Dynamic allocation systems preventing self-interference in dense electromagnetic environments.
Defense procurement gravitates toward Software Defined Radio; Encryption Analysis climbs the fastest as intercept targets harden.
Application:
Mission type determines integration complexity and security classification thresholds.
- Military Surveillance:Theater-level collection platforms supporting operational commanders with actionable intelligence. United States Indo-Pacific Command and United Kingdom Strategic Command sustain the largest revenue base through airborne and space-based constellations.
- Cybersecurity Monitoring:Integrated cyber-electromagnetic platforms that fuse network intrusion detection with radio frequency anomaly tracking. Five Eyes intelligence services are displacing siloed budget allocations toward these converged capabilities.
- Counterterrorism Operations:Tactical intercept supporting law enforcement and special mission units.
- Electronic Warfare:Offensive and defensive electromagnetic operations including jamming and deception.
- Border Security:Fixed and mobile collection along territorial boundaries.
Platform awards cluster in Military Surveillance; Cybersecurity Monitoring gains share fastest as threat vectors merge.
End User:
Customer type shapes contracting vehicles and technology transfer restrictions.
- Defense Agencies:Military departments executing platform-centric procurement through multi-year awards. United States Department of Defense and United Kingdom Ministry of Defence compress vendor selection windows to eighteen months for integrated electronic warfare portfolios.
- Intelligence Organizations:Civilian agencies prioritizing analytical throughput over platform specifications. Australia's Australian Signals Directorate and Canada's Communications Security Establishment concentrate specialized talent in Cheltenham and Fort Meade labor pools.
- Law Enforcement Units:Domestic agencies with constrained budgets and rapid deployment requirements.
- Homeland Security:Border and critical infrastructure protection mandates.
- Cyber Defense Firms:Commercial contractors supporting government classified programs.
Contract volume concentrates with Defense Agencies; Intelligence Organizations show the steepest expansion trajectory in data-centric procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement volumes concentrate in the United States, the United Kingdom, and Israel, with electromagnetic spectrum superiority driving sovereign capability investments across NATO and allied frameworks.
United States
The Department of Defense sustains the largest revenue base through airborne and space-based collection constellations. FCC and FAA regulations govern spectrum allocation for military-civil coordination. Fort Meade and Annapolis Junction anchor specialized talent pools for cryptographic analysis and signals processing workforce development.
United Kingdom
Government Communications Headquarters and Ministry of Defence compress vendor selection windows to eighteen months for integrated electronic warfare portfolios. National Cyber Security Centre certifies encryption analysis systems for classified deployment under UK-specific security frameworks. Cheltenham and Malvern host concentrated clusters of signals intelligence research and sovereign manufacturing capacity.
Israel
Ministry of Defense procurement prioritizes multi-mission platforms with rapid firmware reconfiguration capabilities. Israeli regulations mandate domestic production footprints for classified systems access. Tel Aviv and Beersheba concentrate cryptographic expertise and startup-driven signal processing innovation ecosystems.
Germany
Bundeswehr and federal intelligence services accelerate sovereign capability investments under EU strategic autonomy frameworks. BSI and BAFA administer dual-use export controls and security clearance frameworks for electromagnetic systems. Munich and Ulm host HENSOLDT and Thales Group manufacturing operations serving continental NATO requirements.
Australia
Australian Signals Directorate displaces legacy budget allocations toward AI-enabled data analysis platforms under Five Eyes intelligence-sharing agreements. Defence Trade Controls Act shapes technology transfer restrictions with allied partners. Canberra and Melbourne sustain analytical throughput specialization distinct from platform-centric procurement.
Global Signals Intelligence (SIGINT) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cyber-electromagnetic convergence and AI-enabled processing architectures. The vendor base concentrates among prime contractors with integrated electronic warfare portfolios, compressing subsystem supplier margins through multi-year platform accountability structures. Three archetypes dominate: sovereign manufacturers leveraging domestic security clearances, dual-use specialists spanning civil-military applications, and software-centric challengers modularizing hardware refresh cycles. Competitive moves center on absorbing subsystem suppliers to guarantee integrated delivery timelines and establishing continental production footprints to satisfy EU market access requirements.
Among US-based defense primes, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions anchoring long-term military relationships through platform-centric awards. Raytheon Technologies exemplifies the tier pursuing cyber-electromagnetic convergence. European sovereign capacity concentrates in BAE Systems and Thales Group, with the former representing UK manufacturing depth and the latter occupying a position spanning NATO interoperability mandates. Israel's Elbit Systems sits within the specialized tier serving Middle Eastern and allied export markets.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Raytheon Technologies |
| Thales Group |
| General Dynamics |
| L3Harris Technologies |
| Elbit Systems |
| HENSOLDT |
| Others |
Supply & Pricing Matrix
Multi-year platform awards from United States Department of Defense and United Kingdom Ministry of Defence are compressing vendor selection windows to eighteen months, forcing suppliers to absorb subsystem integration costs and compress hardware margins while shifting profitability toward persistent software licensing arrangements.
Pricing Analysis
Volume placements concentrate in interception equipment while margin expansion belongs to data analysis tools. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified platforms from national-tier systems and commercial-off-the-shelf alternatives. Pricing pressure stems from EU strategic autonomy mandates requiring continental production footprints for classified systems access. Defense agencies show lowest price sensitivity due to mission-critical specifications, while law enforcement units face severe budget constraints driving procurement toward economy-tier configurations.
Supply Chain Analysis
Domestic content mandates from Israel's Ministry of Defense and EU developing defense procurement frameworks are reshaping sourcing patterns, forcing non-European suppliers to establish continental manufacturing footprints or face market access restrictions. Component fabrication concentrates in United States, United Kingdom, and Israel. Supply chains draw from specialized FPGA foundries, cryptographic processor fabs, and precision antenna manufacturers. Single-source vulnerability runs through Tel Aviv and Cheltenham talent clusters for cryptographic analysis expertise. Distribution runs through prime contractor integration facilities serving national defense procurement agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cost-of-compliance dynamics dominate strategic positioning as EU AI Act risk classification frameworks mandate human-in-the-loop oversight and algorithmic interpretability standards, erecting regulatory moats favoring established vendors with documented certification pathways.
For Market Incumbents: Cement long-term military relationships by absorbing subsystem suppliers to guarantee integrated delivery timelines for compressed eighteen-month procurement windows. Prioritize backward integration into FPGA-based signal processor manufacturing to secure supply continuity against single-source chokepoints. Fortify positioning against software-centric challengers modularizing hardware refresh cycles through firmware-update-enabled platform longevity. For New Entrants and Emerging Players: Begin with Poland and Baltic States establishing sovereign SIGINT capabilities independent of legacy Warsaw Pact infrastructure, where incumbent presence remains thin and procurement frameworks favor rapid capability acquisition. Target cyber-electromagnetic convergence applications displacing siloed budget allocations among Five Eyes intelligence services. Pursue go-to-market partnerships with national cyber security centres seeking AI-enabled processing architectures. For Investors and Strategic Acquirers: Re-rating potential sits with dual-use civil-military specialists given NATO interoperability mandates accelerating satellite signal processing migration from aviation safety to defense applications. Long-term viability favors vendors with documented EU AI Act compliance pathways and established continental production footprints. Monitor encryption proliferation rates as the critical inflection signal—quantum-resistant algorithm adoption curves determine classical decryption capability obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Continental Production Footprint Establishment | EU strategic autonomy frameworks mandate domestic manufacturing for classified systems access. |
| Software-Defined Architecture Migration | Firmware-update-enabled platforms compress refresh cycles from years to months for United States Special Operations Command. |
| AI-Enabled Processing Suite Development | Automated classification reduces analyst-to-signal ratios for United Kingdom Government Communications Headquarters. |
| Subsystem Supplier Vertical Integration | Prime contractors absorb component vendors to guarantee integrated delivery timelines for NATO electronic warfare programs. |
| Cyber-Electromagnetic Convergence Platform Launch | Integrated capabilities displace siloed budget allocations across Five Eyes intelligence services. |
Research Methodology
Defense procurement databases, NATO standardization agreement filings, and national security regulator certification records formed the secondary backbone, cross-referenced with primary interviews involving electronic warfare program managers, signals intelligence analysts, defense procurement officers, and cryptographic systems engineers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators anchored the quantitative framework.
Historical trendline analysis across platform award cycles and software refresh patterns informed projection modeling throughout the forecast period. Segmentation dimensions included product type, technology architecture, application mission, and end-user contracting vehicle, with additional granularity across electromagnetic spectrum band coverage and security classification tier. CAGRs derived from fitted growth curves adjusted for procurement cycle timing and sovereign capability investment trajectories, incorporating inputs from defense budget appropriation patterns and dual-use technology export control evolution.
Encryption proliferation acceleration, regulatory framework fragmentation between EU AI Act and national security exemptions, and specialized talent scarcity in Cheltenham and Fort Meade labor pools are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding procurement consolidation trajectories and interoperability mandate adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Drone Surveillance Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Passive Radar Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Early Warning Radar Market