
 Mexico Aerospace Market | 2026-2036
Mexico Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Aerospace Market Insights
Market Context
Commercial airline fleet modernization is repositioning Mexico's aerospace manufacturing toward higher-value component production. Safran Group leverages its Querétaro engine nacelle facility to sustain European OEM supply chain integration. Bombardier Inc. anchors business jet final assembly in Mexico while GE Aerospace competes on aerostructure exports to North American defense primes.
Technical and Segment Structure
Mexico aerospace encompasses the design, fabrication, and assembly of airframes, propulsion components, and avionics systems for commercial and military platforms, with titanium machining tolerances reaching 0.005 inches for turbine applications. Aircraft production dominates value capture within the product type dimension, while unmanned systems represents the fastest-expanding industry vertical as defense contractors seek nearshored drone manufacturing. Propulsion systems technology concentrates margin pools due to specialized metallurgy requirements and limited supplier certification.
Regulatory Outlook
The FAA and Mexico's DGAC coordinate bilateral airworthiness certification under USMCA provisions, while BIS export controls shape technology transfer limits for defense-related manufacturing. Stakeholders must monitor evolving DGAC environmental standards for manufacturing emissions as Mexican regulators align with ICAO carbon reduction frameworks.
Market Dynamics
Fleet modernization programs across North American carriers are compressing supplier qualification timelines and forcing Mexican aerospace clusters to accelerate titanium machining capacity expansion. This structural pressure is redrawing competitive boundaries between Querétaro-based tier-one suppliers and emerging Chihuahua fabrication operations.
Growth Catalysts
- USMCA certification alignment:FAA-DGAC bilateral protocols are streamlining cross-border airworthiness approvals for Mexican aerostructure exports. Tier-two suppliers gain faster access to Boeing and Airbus vendor lists.
- Unmanned systems demand:Defense contractors are nearshoring drone manufacturing to Mexico to circumvent BIS export control complexity on sensitive avionics. This vertical is absorbing precision casting capacity from idle commercial lines.
- Querétaro cluster density:Safran and Bombardier anchor a 35-kilometer supplier ecosystem where specialized heat treatment and non-destructive testing infrastructure is shared across tier-one and tier-two firms.
Market Restraints
- Titanium sponge volatility:Russian supply disruptions have exposed Mexican fabricators to spot market pricing for aerospace-grade titanium, compressing margin on long-term fixed-price contracts with OEMs.
- Single-source forging dependence:Critical turbine disk forgings rely on a concentrated US supplier base, creating vulnerability for Mexican engine component assemblers without backward integration into primary metallurgy.
- DGAC environmental compliance lag:Mexican regulators have not finalized ICAO-aligned carbon accounting rules for manufacturing emissions, leaving exporters exposed to retroactive certification requirements.
Strategic Opportunities
- Baja California satellite integration:Underpenetrated northern Mexico offers proximity to California defense primes seeking alternative assembly locations outside congested Southern California corridors.
- Electrified propulsion subsystems:Hybrid-electric aircraft development is creating white space for Mexican suppliers to capture battery thermal management and power electronics packaging work previously dominated by automotive tier-ones.
- PLI scheme adaptation:Mexico's manufacturing incentives under USMCA regional value content rules are attracting European MRO providers to establish engine overhaul facilities in Guanajuato.
Industry Challenges
- Five-axis CNC programming scarcity:Mexican technical institutes produce insufficient machinists capable of programming complex titanium turbine blade geometries, forcing firms to poach talent from competing clusters.
- NADCAP accreditation timelines:Special process certification for heat treatment and chemical processing requires 18-24 month qualification cycles, delaying new supplier entry despite available capacity.
- Legacy ERP integration friction:Tier-two fabricators struggle to synchronize production data with Boeing's DCAC/MRM and Airbus's Supply Chain Platform, creating invoice reconciliation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Aerospace Market |
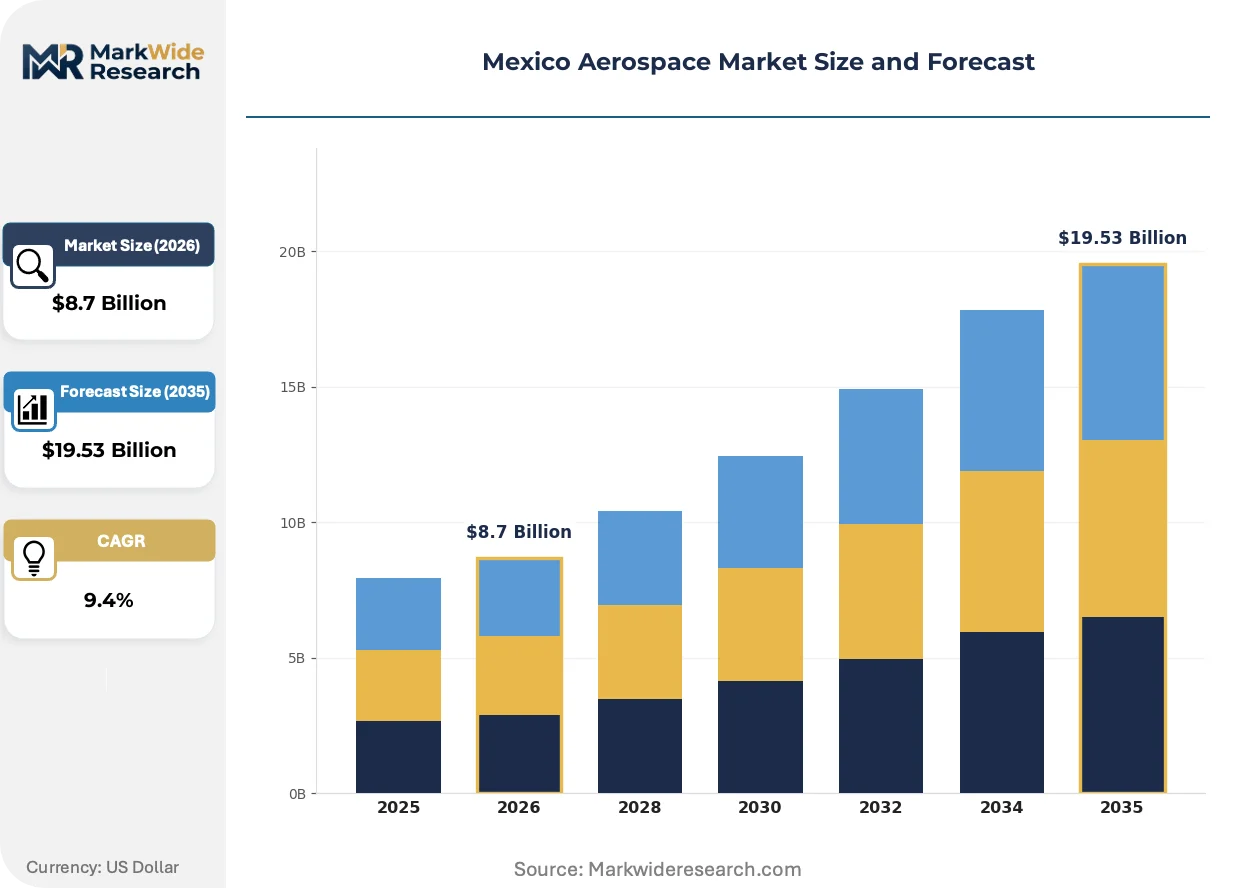
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Spacecraft, Satellites, Drones Industry Vertical: Aviation, Defense, Space Exploration, Unmanned Systems Technology: Avionics, Propulsion Systems, Materials, Navigation Systems End User: Commercial Airlines, Defense Contractors, Space Agencies, Research Institutes |
| Companies Covered | Safran Group, Bombardier Inc., Airbus, The Boeing Company, Honeywell Aerospace, Collins Aerospace, GE Aerospace, GKN Aerospace, Spirit AeroSystems Holdings, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Aerospace Market Trends and Innovations
Additive manufacturing is penetrating structural brackets and ducting applications that conventional machining cannot economically produce at low volumes. This shift is redistributing value capture from raw material suppliers to powder metallurgy specialists and post-processing equipment providers.
Directed energy deposition for titanium aerostructures is overtaking subtractive methods for non-flight-critical brackets and manifolds. Bombardier's Querétaro operations are adopting wire-fed AM for business jet interior monuments, compressing lead times from twelve weeks to seventy-two hours while reducing material scrap rates by two-thirds.
DGAC is implementing ICAO Annex 16 Vol IV emissions monitoring for manufacturing facilities, mirroring EPA aerospace sector rules. Mexican fabricators must install continuous emissions monitoring systems by 2027, with Querétaro-based heat treatment operations facing the steepest compliance capital requirements.
Airline procurement teams are unbundling long-term component contracts into discrete manufacturing and aftermarket service agreements. This disintermediation is compressing supplier margins on initial production while opening recurring revenue streams for Mexican MRO specialists capable of FAA Part 145 repair station certification.
Mexico Aerospace Market Segmentation
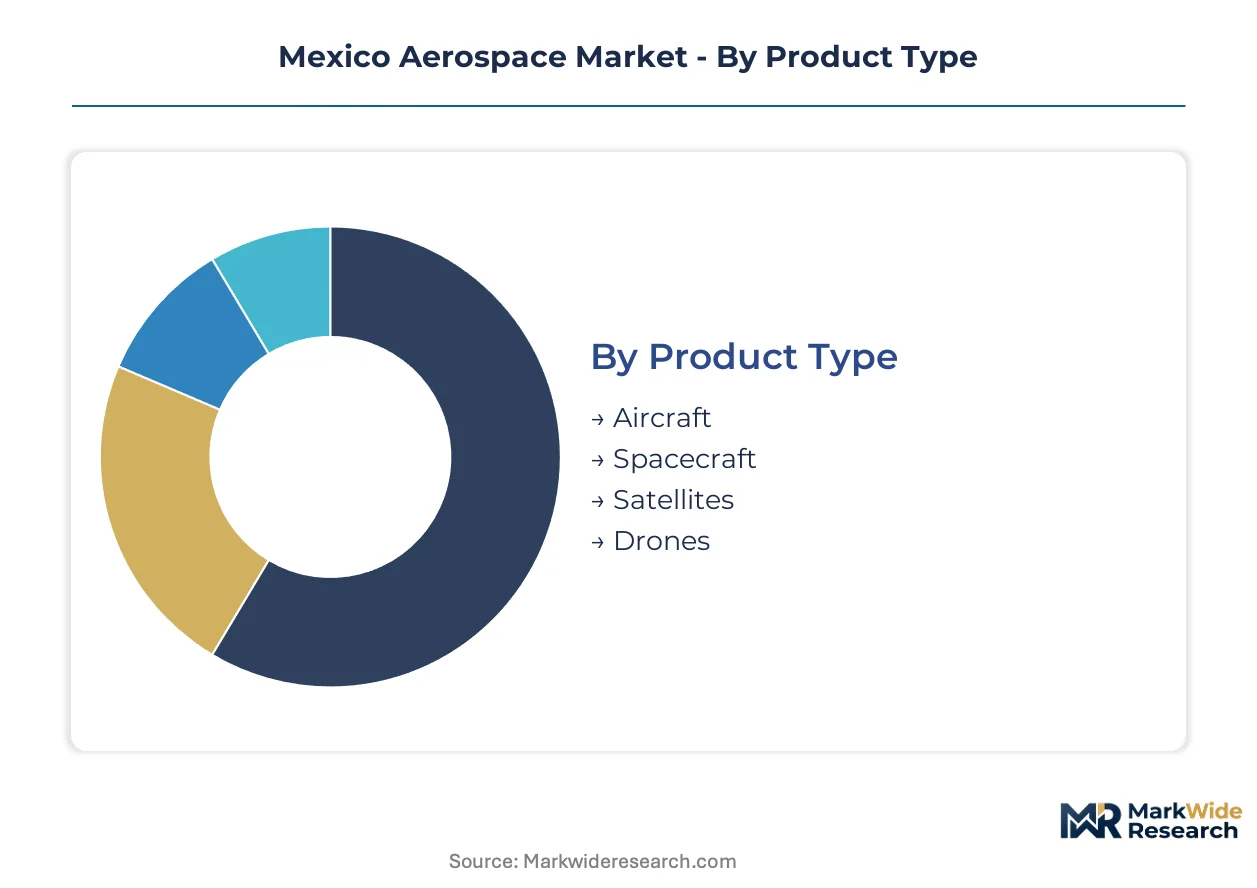
Mexico's aerospace manufacturing clusters specialize in distinct production tiers, from capital-intensive airframe assembly to precision component fabrication. Segment boundaries determine supplier qualification requirements, FAA-DGAC certification pathways, and regional value content calculations under USMCA rules.
Product Type:
Capital intensity escalates sharply from unmanned platforms to crewed aircraft production, with final assembly lines requiring tenfold greater upfront tooling investment than component fabrication.
- Aircraft:Fixed-wing and rotary-wing platforms dominate Querétaro manufacturing output, with Bombardier's final assembly operations absorbing the bulk of specialized labor and heat treatment infrastructure. Commercial airline procurement teams source fuselage sections and wing assemblies from Mexican tier-one suppliers to satisfy USMCA regional value thresholds.
- Drones:Unmanned aerial systems manufacturing concentrates in emerging Chihuahua operations where defense contractors circumvent BIS export controls on sensitive avionics. Lower certification barriers and modular assembly architectures enable faster supplier qualification cycles compared to crewed platforms.
- Spacecraft:Limited Mexican participation centers on structural subassemblies and thermal protection components for satellite buses, with Baja California fabricators supplying aluminum-lithium tank sections to US prime contractors.
- Satellites:Ground station equipment and antenna reflector production represents the primary Mexican contribution, with Guanajuato machine shops delivering Ka-band RF components under ITAR-compliant workflows.
Aircraft absorbs the bulk of installed capacity; drones is expanding most quickly.
Industry Vertical:
Application urgency separates military procurement cycles from commercial aviation's extended fleet planning horizons, with defense contracts compressing supplier onboarding from thirty-six to eighteen months.
- Aviation:Commercial airline fleet modernization drives demand for next-generation aerostructures, with Mexican suppliers producing composite wing skins and titanium landing gear components for Boeing and Airbus assembly lines. FAA Part 21 production certificates govern manufacturing quality systems.
- Defense:Pentagon nearshoring initiatives redirect subassembly work to Mexican facilities, particularly for platforms exempt from strict Buy American provisions. DGAC military airworthiness certification runs parallel to FAA military export approvals.
- Unmanned Systems:Autonomous platform manufacturing exploits regulatory arbitrage between US export controls and Mexican assembly freedoms, with precision casting shops repurposing idle commercial turbine blade capacity for drone propulsion housings.
- Space Exploration:NASA Artemis program subcontractors source machined aluminum structural elements from Mexican fabricators, though launch vehicle integration remains concentrated in US Gulf Coast facilities.
Aviation commands the greatest production volume; unmanned systems is gaining share fastest.
Technology:
Margin concentration follows metallurgical complexity, with specialized alloys and single-crystal casting processes capturing value unavailable to conventional machining operations.
- Propulsion Systems:Turbine disk forgings and engine nacelle assemblies require NADCAP-accredited heat treatment and non-destructive testing infrastructure concentrated in Querétaro's supplier ecosystem. Safran's local facility anchors European OEM supply chain integration for narrowbody powerplant components.
- Avionics:Flight control computers and navigation sensors face stringent BIS export licensing, limiting Mexican participation to cable harnesses and non-programmable hardware enclosures. Baja California assembly operations specialize in military-grade interconnect systems.
- Materials:Titanium machining to 0.005-inch tolerances for turbine applications demands five-axis CNC programming expertise scarce in Mexican technical institutes. Spot market volatility for aerospace-grade sponge compresses fabricator margins on fixed-price OEM contracts.
- Navigation Systems:GPS augmentation hardware and inertial measurement unit housings represent accessible entry points for Mexican suppliers, with Guadalajara electronics manufacturers qualifying for civil aviation certification under DGAC-FAA bilateral protocols.
Propulsion systems captures the highest value per kilogram; avionics faces the steepest regulatory barriers to expansion.
End User:
Procurement sophistication varies dramatically, with commercial airlines demanding integrated logistics support while research institutes prioritize technical flexibility over scale economies.
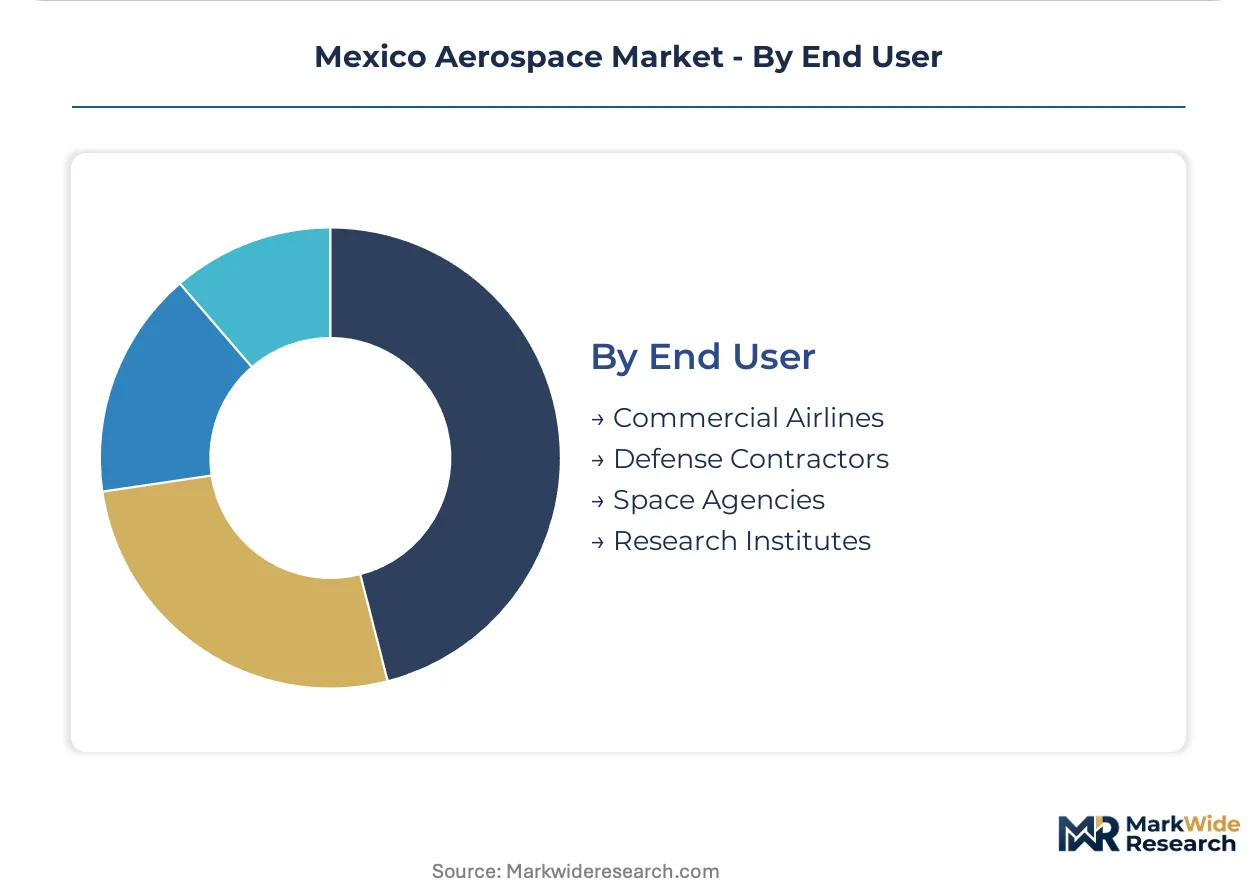
- Commercial Airlines:Fleet operators source aerostructures through Boeing and Airbus tier-one supplier networks, with Mexican fabricators competing on USMCA-compliant regional value content and proximity to US final assembly lines.
- Defense Contractors:Lockheed Martin and Raytheon subsidiaries direct classified subassembly work to Mexican facilities with pre-cleared personnel and facility security certifications, particularly for platforms destined for allied export.
- Space Agencies:NASA and ESA procurement of Mexican-manufactured components concentrates on non-flight-critical structural elements, with ITAR restrictions limiting technology transfer for propulsion and guidance systems.
- Research Institutes:University and national laboratory contracts for experimental aircraft components offer lower volume but higher margin opportunities, with CONACYT-funded projects supporting additive manufacturing process development in Querétaro technical centers.
Commercial airlines represent the dominant demand source; defense contractors are scaling procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IMMEX maquiladora program and USMCA regional value content rules concentrate aerospace investment in specific Mexican states. Federal manufacturing incentives under the PROSEC regime accelerate supplier clustering near existing OEM facilities.
Querétaro
Engine nacelle and aerostructure production dominates this central Mexico corridor. DGAC coordinates FAA bilateral certification protocols from its regional office here. Safran's engine component facility anchors a 35-kilometer supplier ecosystem sharing heat treatment infrastructure.
Baja California
Defense contractors seek satellite integration and avionics assembly proximity to California primes. The state's proximity to US border crossings reduces logistics friction for ITAR-controlled shipments. Tijuana and Mexicali operations specialize in military-grade cable harnesses and RF component enclosures.
Chihuahua
Unmanned systems manufacturing exploits regulatory arbitrage between BIS export controls and Mexican assembly freedoms. Precision casting shops repurpose idle commercial turbine capacity for drone propulsion housings. The emerging cluster absorbs displaced aerospace machinists from Juárez automotive operations.
Nuevo León
Monterrey's industrial base supports titanium machining and five-axis CNC programming for turbine blade geometries. State technical institutes partner with OEMs to address machinist scarcity. The region competes with Querétaro for tier-two supplier investment under federal PLI schemes.
Guanajuato
European MRO providers establish engine overhaul facilities to capture USMCA-compliant regional value content. León's manufacturing tradition translates into non-destructive testing and special process certification capacity. The state offers underpenetrated industrial real estate compared to saturated Querétaro corridors.
Mexico Aerospace Market Competitive Landscape
Top-tier vendors anchor final assembly and engine nacelle production, while tier-two fabricators compete on USMCA regional value content and proximity to OEM lines. The competitive landscape splits between European OEM-integrated suppliers and North American defense contractors. Strategic archetypes include: vertically integrated engine component specialists, unmanned systems assemblers exploiting regulatory arbitrage, and precision casting operations repurposing commercial capacity. Dominant competitive moves involve M&A to secure NADCAP-accredited heat treatment assets and strategic partnerships to access Boeing and Airbus vendor lists.
Within the OEM-integrated tier, Safran Group and Bombardier Inc. exemplify European-North American supply chain anchoring. GE Aerospace occupies a position among propulsion system specialists competing on aerostructure exports. These three entities represent distinct competitive archetypes: European OEM captive supply, business jet final assembly integration, and defense-aerospace dual-use manufacturing capability.
| Leading Market Players |
|---|
| Safran Group |
| Bombardier Inc. |
| Airbus |
| The Boeing Company |
| Honeywell Aerospace |
| Collins Aerospace |
| GE Aerospace |
| GKN Aerospace |
| Spirit AeroSystems Holdings, Inc. |
| Others |
Pricing and Supply Chain Analysis
Additive manufacturing adoption for titanium structural brackets and ducting applications simultaneously compresses unit production costs and redistributes value capture toward powder metallurgy specialists, concentrating margin pools among post-processing equipment providers while fragmenting traditional machining revenue streams across Mexican aerospace clusters.
Pricing Analysis
Lead-time premiums command substantial markups for NADCAP-accredited heat treatment and non-destructive testing services with sub-four-week turnaround, while spot inventory of aerospace-grade titanium sponge trades at discounts to contract offtake amid Russian supply disruption volatility. Three-tier pricing structure across NADCAP-certified premium, standard DGAC-compliant, and uncertified economy fabrication tiers differentiates suppliers by audit status and OEM approval level. Price differentiation hinges on FAA Part 21 production certificate holding and vertical integration into specialized metallurgy. Cost compression in tier-two machining is intensifying because long-term fixed-price contracts with Boeing and Airbus fail to pass through titanium sponge spot market spikes. Defense contractors exhibit lowest price sensitivity due to ITAR compliance premiums, while commercial airline procurement teams drive hardest bargain on USMCA regional value content calculations.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one supplier demand from Safran and Bombardier final assembly operations, while tier-two fabricators distribute through specialized aerospace distributors serving Boeing and Airbus vendor lists. Geographic supply concentration draws from US forging operations for critical turbine disk inputs, Russian and Japanese sponge producers for titanium feedstock, and domestic Querétaro heat treatment infrastructure for special process completion. Raw material dependencies rest on aerospace-grade titanium sponge, nickel-based superalloys for turbine applications, and carbon fiber prepregs for composite aerostructures. Single-source forging vulnerability for turbine disk inputs creates structural risk for Mexican engine component assemblers lacking backward integration into primary metallurgy. Distribution runs through OEM-authorized supplier networks with mandatory DCAC/MRM or Airbus Supply Chain Platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico aerospace manufacturing is consolidating around NADCAP-accredited special process capacity as titanium sponge volatility and eighteen-month certification timelines force sub-scale fabricators toward acquisition or exit.
For Market Incumbents: Deepen captive supply of heat treatment and non-destructive testing infrastructure through acquisition of distressed tier-two NADCAP-accredited facilities, while accelerating five-axis CNC programming talent development through technical institute partnerships in Nuevo León to defend against poaching from emerging Chihuahua unmanned systems clusters. For New Entrants and Emerging Players: Electrified propulsion thermal management subsystems offer accessible white-space entry as hybrid-electric aircraft development displaces automotive tier-one incumbents from battery packaging work, with Baja California satellite integration corridors presenting the most penetrable geography for California defense prime supplier qualification. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by European MRO providers seeking USMCA-compliant regional value content footholds, with long-term viability hinging on DGAC-FAA bilateral certification alignment durability. Target acquisition archetypes include NADCAP-accredited special process shops with underutilized capacity and established Boeing or Airbus vendor list positions. The signal to watch is DGAC finalization of ICAO-aligned carbon accounting rules, which will trigger compliance capital deployment requirements and distressed seller dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| NADCAP Accreditation Acquisition | Special process certification compresses supplier qualification timelines from thirty-six to eighteen months for tier-two fabricators. |
| Additive Manufacturing Capacity Buildout | Wire-fed directed energy deposition reduces titanium aerostructure lead times from twelve weeks to seventy-two hours at Bombardier Querétaro. |
| USMCA Regional Value Content Optimization | European MRO providers establish Guanajuato engine overhaul facilities to capture compliant supply chain positioning. |
| Unmanned Systems Manufacturing Pivot | Precision casting shops repurpose idle commercial turbine capacity for drone propulsion housings in Chihuahua. |
| Five-Axis CNC Talent Pipeline Development | Nuevo León technical institutes partner with OEMs to address machinist programming scarcity for complex turbine geometries. |
Research Methodology
Document review covered DGAC regulatory filings, FAA bilateral certification protocols, USMCA regional value content determinations, and NADCAP special process accreditation records, complemented by interviews with tier-one supplier procurement directors, DGAC certification engineers, aerospace distributor channel managers, and heat treatment facility operations heads. Secondary validation drew from SEC 10-K aerospace segment disclosures, Mexican federal manufacturing incentive program documentation, and titanium sponge trade flow customs data. Bottom-up capacity modeling triangulated against top-down OEM sourcing footprint analysis.
Cross-reference between historical fleet modernization procurement patterns and expert panel input on unmanned systems demand elasticity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, industry vertical, technology tier, and end-user procurement sophistication. CAGRs derived from installed capacity expansion trajectories, OEM supplier onboarding timelines, and regulatory convergence velocity. Industry-specific forecast inputs incorporated BIS export control stringency indices and DGAC environmental compliance rulemaking progress.
Several conditions sit outside the modeled scope, including geopolitical disruption to US-Russia titanium sponge trade, unilateral DGAC carbon accounting rule acceleration, and Pentagon nearshoring program cancellation. Forecasts reflect assumptions on FAA-DGAC bilateral protocol stability and USMCA regional value content rule continuity. Periodic stress-testing of base assumptions is recommended against titanium sponge spot market volatility and NADCAP accreditation backlog indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
AI in Modern Warfare Market