
 AI in Aviation Market | 2026-2036
AI in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Aviation Market Analysis
FAA Part 135 automation guidance is realigning the cost-of-entry calculus for AI vendors serving regional operators. Airbus SE leverages its Skywise platform to anchor predictive maintenance services across carrier fleets. Raytheon Technologies Corporation sustains R&D intensity in computer vision systems for runway monitoring. General Electric Company dominates digital twin deployments through its Edison platform, extending its reach from engine diagnostics to full flight operations optimization.
AI in aviation encompasses machine learning algorithms, computer vision systems, and natural language processing tools integrated into aircraft operations, air traffic management, and ground services, typically processing sensor data at latencies under 100 milliseconds to enable real-time decision support. Its primary commercial purpose centers on reducing operational expenditures while maintaining or exceeding existing safety thresholds through automated anomaly detection and predictive intervention. Predictive maintenance commands the largest current revenue pool as airlines prioritize fleet availability over experimental applications. Machine learning leads technology adoption due to mature toolchains and interpretable failure-mode models, while natural language processing shows the fastest growth trajectory as carriers automate crew scheduling and passenger communication workflows.
The FAA, EASA, and ICAO collectively shape certification pathways for autonomous flight systems, with each body imposing distinct validation requirements that fragment vendor go-to-market timelines. REACH and EU AI Act compliance obligations in Europe add material overhead for predictive maintenance platforms processing sensitive operational data. Stakeholders must monitor evolving algorithmic transparency mandates across jurisdictions to anticipate which technology architectures will retain market access.
Market Dynamics
FAA Part 135 automation guidance and EASA's evolving AI certification frameworks are compressing vendor timelines while fragmenting validation requirements across jurisdictions. This regulatory divergence forces predictive maintenance providers to architect multi-pathway compliance from initial design stages.
Growth Catalysts
- Machine Learning Maturation:Interpretable failure-mode models enable carriers to automate anomaly detection in legacy fleet retrofits without full platform replacement.
- EU AI Act Compliance Mandates:Algorithmic transparency requirements for high-risk systems accelerate procurement of certified predictive maintenance platforms across European operators.
- Regional Carrier Fleet Modernization:United States-based Part 135 operators face FAA pressure to replace reactive maintenance with sensor-driven diagnostics.
Market Restraints
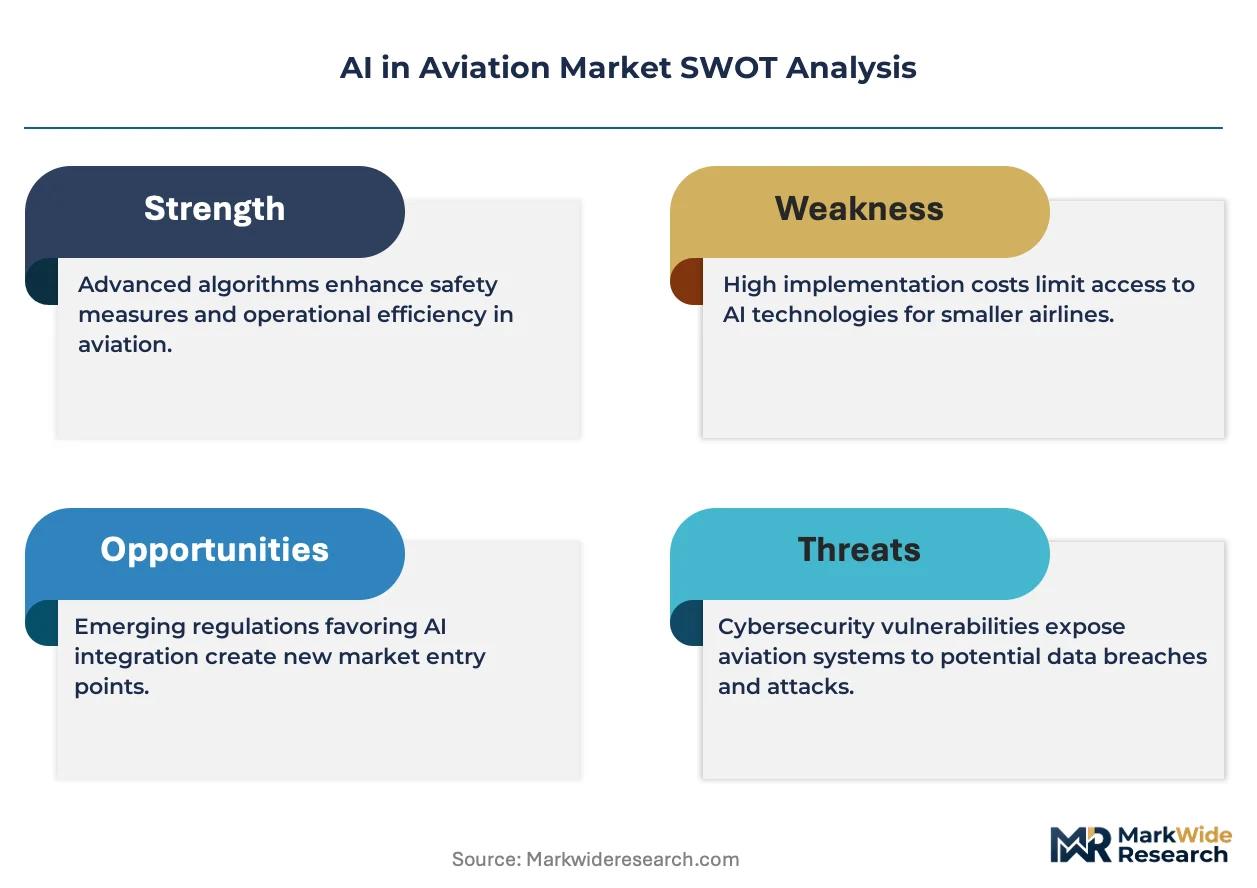
- Certification Cost Burden:Dual validation against FAA and EASA standards doubles engineering overhead for autonomous flight system vendors.
- Specialized Talent Scarcity:Aerospace-grade machine learning engineers concentrate in Seattle, Toulouse, and Munich, constraining vendor scaling outside these clusters.
- Legacy System Interoperability:ARINC 429 and MIL-STD-1553 bus architectures in older aircraft resist seamless AI sensor integration.
Strategic Opportunities
- India Aviation Expansion:DGCA regulatory modernization creates first-mover advantage for predictive maintenance platforms serving IndiGo and Air India's narrowbody growth.
- Natural Language Processing Convergence:Crew scheduling automation combined with passenger communication workflows opens adjacent revenue pools beyond hardware diagnostics.
- Digital Twin-as-a-Service:Cloud-native deployment models lower capital barriers for regional operators previously excluded from full-flight simulation ecosystems.
Industry Challenges
- Multijurisdictional Certification Timelines:ICAO, FAA, and EASA validation misalignment extends product launch windows by 18-24 months for autonomous systems.
- Edge Computing Hardware qualification:DO-178C and DO-254 compliance for AI inference chips at under-100-millisecond latency demands specialized foundry partnerships.
- Data Sovereignty Architecture:Cross-border flight operations trigger conflicting GDPR, state-level privacy, and military airspace data localization requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Aviation Market |
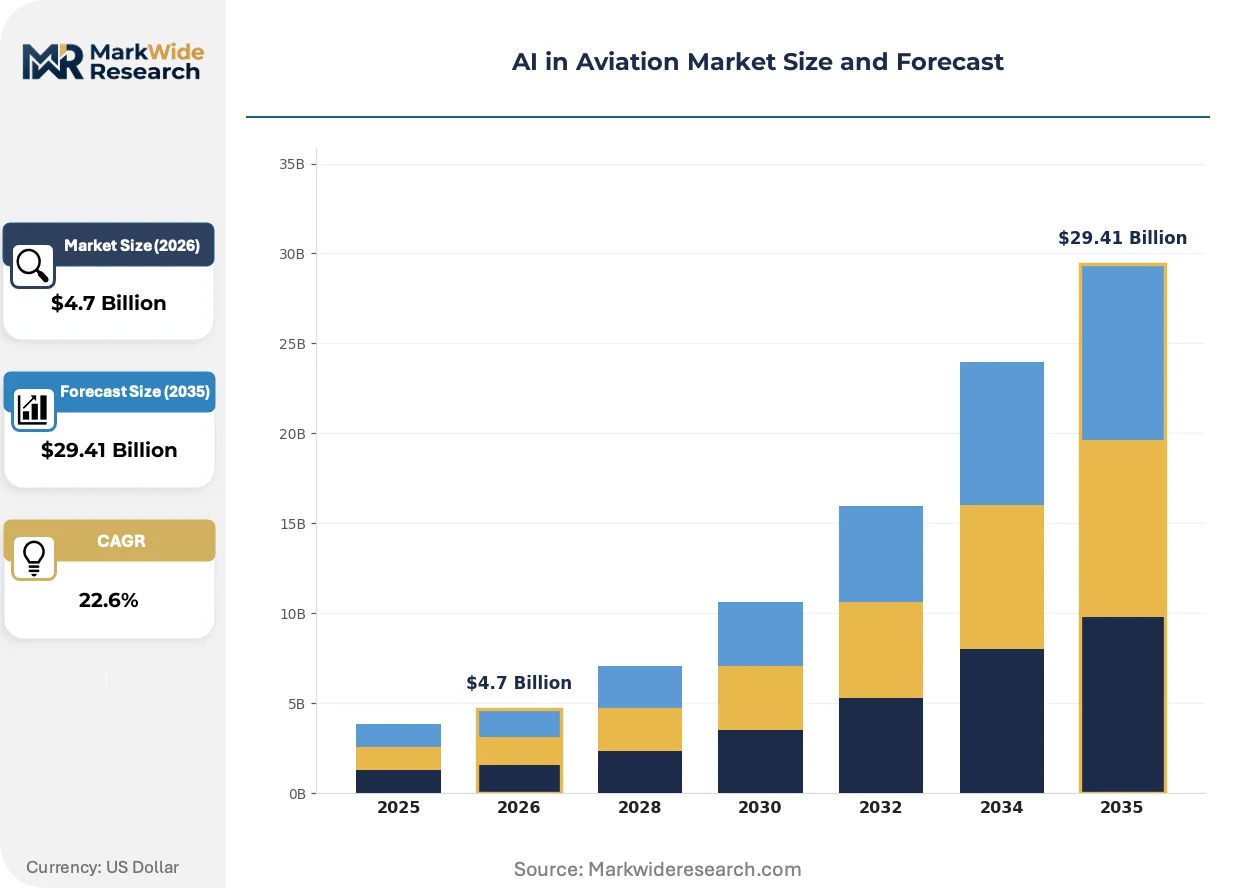
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Operations Management, Predictive Maintenance, Crew Management, Air Traffic Control Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics Application: Safety Management, Fuel Efficiency, Customer Experience, Risk Assessment End User: Airlines, Manufacturers, Airports, Regulatory Bodies |
| Companies Covered | Airbus SE, Raytheon Technologies Corporation, General Electric Company, Rolls-Royce plc, L3Harris Technologies, Inc., Honeywell International Inc., Thales S.A., Leonardo S.p.A, The Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Aviation Market Emerging Trajectories
Federated learning architectures are redistributing computational load away from centralized cloud infrastructure. This shift enables real-time decision support without transmitting sensitive flight data across jurisdictions.
Edge-native AI inference is decentralizing predictive maintenance workloads from ground-based data centers to onboard aircraft processors. Carriers retrofitting Boeing 737 and Airbus A320 fleets adopt these systems fastest where satellite connectivity remains intermittent. The technology is decentralizing vendor competitive advantage toward hardware-software integration capability rather than pure algorithmic sophistication.
EASA's forthcoming AI certification framework for safety-critical aviation systems imposes mandatory explainability requirements on black-box machine learning models. Vendors must reconstruct decision pathways for regulatory auditors. Deep learning-based computer vision for runway incursion detection faces the steepest compliance redesign.
Airline procurement teams now unbundle predictive maintenance software licenses from engine OEM service contracts. LCCs and hybrid carriers in Southeast Asia lead this disintermediation, sourcing diagnostics from specialized AI vendors while retaining MRO relationships. This pattern concentrates in markets where antitrust scrutiny of vertical integration has intensified.
AI in Aviation Market Segmentation
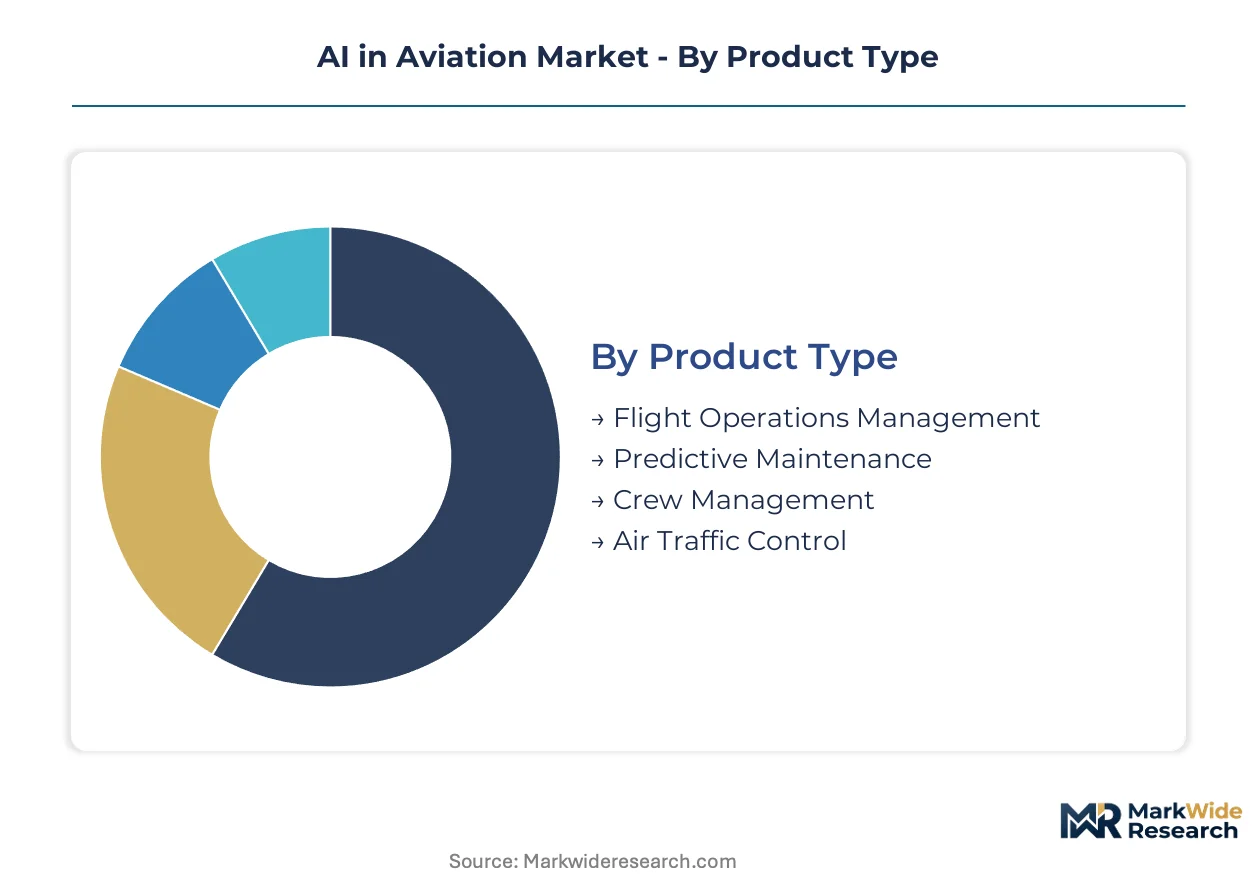
Segmentation in aviation AI reveals how vendor specialization aligns with distinct operational pain points. Each dimension—product, technology, application, and end user—carries unique certification burdens and procurement cycles that reshape competitive entry.
Product Type:
Supply concentration clusters around platforms with the clearest ROI measurement and lowest regulatory friction for initial deployment.
- Predictive Maintenance:Sensor-driven failure prediction algorithms process vibration, thermal, and oil debris data from turbine engines and auxiliary power units. Demand concentrates among United States-based Part 135 operators facing FAA pressure to replace calendar-based inspections with condition-based monitoring, though legacy ARINC 429 bus integration remains a deployment bottleneck.
- Flight Operations Management:Real-time route optimization and fuel burn analytics integrate with flight management computers to adjust trajectories based on wind, temperature, and congestion. European full-service carriers under EU ETS pressure prioritize these systems for transatlantic routes where marginal fuel savings compound across high-frequency operations.
- Crew Management:Pairing optimization and fatigue risk modeling tools automate pilot and cabin staff scheduling. These platforms expand most quickly at hybrid carriers in Southeast Asia where rapid fleet growth outpaces manual rostering capacity.
- Air Traffic Control:Conflict detection and sequencing algorithms augment human controller decision-making. Deployment remains constrained by ICAO harmonization timelines and sovereign airspace control sensitivities.
Today's leader: Predictive Maintenance. Tomorrow's challenger: Flight Operations Management.
Technology:
Cost tier differentiation separates mature toolchains with established certification pathways from emerging modalities facing explainability mandates.
- Machine Learning:Supervised and unsupervised statistical models dominate current deployments, with interpretable failure-mode frameworks satisfying EASA's forthcoming algorithmic transparency requirements. Airlines retrofitting Boeing 737 and Airbus A320 fleets favor these systems for their mature validation against DO-178C software standards.
- Computer Vision:Convolutional neural networks process runway imagery, foreign object debris detection, and gate occupancy monitoring. Airports in the United States and Germany lead procurement where ground infrastructure automation lags airborne system sophistication.
- Natural Language Processing:Crew scheduling automation and passenger communication workflows show the steepest expansion trajectory as carriers automate multilingual disruption management and cockpit voice data transcription.
- Robotics:Autonomous ground handling equipment and drone-based inspection systems remain experimental, with regulatory frameworks for autonomous movement on tarmacs still fragmented across jurisdictions.
Volume concentration favors Machine Learning. Margin expansion concentrates in Natural Language Processing.
Application:
Customer type priorities diverge between safety-critical mandates and operational efficiency targets.
- Safety Management:Anomaly detection and incident prediction systems process flight data recorder outputs and maintenance logs. Regulatory pressure from FAA and EASA drives procurement at legacy carriers with extensive historical datasets for model training.
- Fuel Efficiency:Trajectory optimization and continuous descent approach algorithms reduce burn per available seat mile. Low-cost carriers with thin margin structures prioritize these applications where percentage gains translate directly to route viability.
- Customer Experience:Personalized booking, disruption rebooking, and loyalty program optimization tools. These systems gain traction at Gulf carriers competing on service differentiation rather than price.
- Risk Assessment:Weather routing, geopolitical corridor evaluation, and cybersecurity threat modeling. Demand clusters at cargo operators and executive jet fleets with flexible routing authority.
Maturity advantage rests with Safety Management. Fastest adoption velocity belongs to Fuel Efficiency.
End User:
Procurement authority fragmentation creates distinct sales cycles and technical requirements across buyer categories.
- Airlines:Fleet-wide deployment decisions driven by chief technical officers and operations executives. United States majors and European network carriers represent the deepest procurement budgets, with narrowbody retrofit programs consuming the largest platform volumes.
- Manufacturers:Airbus and Boeing embed AI into original equipment for predictive maintenance and flight envelope protection. Their supplier qualification processes impose multi-year validation timelines that filter out early-stage vendors.
- Airports:Ground operations automation and passenger flow management procurement. Large hub operators in the United Arab Emirates and Singapore lead investment where capacity constraints demand throughput optimization.
- Regulatory Bodies:FAA, EASA, and national aviation authorities procure validation tools and simulation environments for certification pathway development. These contracts carry long sales cycles but establish vendor credibility for commercial markets.
Revenue concentration centers on Airlines. Emerging opportunity concentrates with Airports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation AI originated in United States military and NASA research programs during the 1980s, with predictive maintenance algorithms first deployed by American carriers in the early 2000s. This historical foundation established regulatory precedents and engineering talent clusters that continue shaping geographic deployment patterns today.
United States
FAA Part 135 automation guidance drives retrofit demand among regional operators upgrading legacy fleets with sensor-driven diagnostics. The agency's 2023 advisory circular on condition-based maintenance accelerates procurement timelines for certified platforms. Seattle and Atlanta anchor the deepest engineering concentrations, with Delta Air Lines and Alaska Airlines deploying predictive maintenance across narrowbody operations.
Germany
EASA's forthcoming AI certification framework for safety-critical systems imposes mandatory explainability requirements that reshape vendor compliance architectures. The EU AI Act's high-risk system classification adds material overhead for predictive maintenance platforms processing operational data. Munich and Hamburg host specialized aerospace machine learning clusters where Lufthansa Group validates autonomous flight systems.
France
Airbus SE's Toulouse headquarters anchors European predictive maintenance R&D through its Skywise platform, extending digital twin capabilities across carrier fleets. ANSM and CNIL oversight of health-adjacent aviation data triggers additional GDPR compliance layers for crew fatigue monitoring systems. The Paris-Saclay corridor concentrates computer vision research for runway safety applications.
United Kingdom
Rolls-Royce plc's Derby engineering center drives digital twin deployments for turbine engine diagnostics, integrating AI inference with legacy ARINC 429 bus architectures. The UK Civil Aviation Authority's post-Brexit certification pathway divergence from EASA standards fragments validation requirements for vendors serving British operators. London Gatwick and Manchester airports pilot autonomous ground handling equipment under fragmented regulatory timelines.
India
DGCA regulatory modernization creates procurement windows for predictive maintenance platforms serving IndiGo and Air India's narrowbody expansion programs. The PLI scheme for aerospace components attracts foreign AI vendors establishing local validation partnerships. Bangalore and Hyderabad concentrate software engineering talent for aviation machine learning applications.
AI in Aviation Market Vendor Landscape
The competitive structure tilts toward diversified aerospace conglomerates with captive MRO relationships and certified platform histories. Tier-one vendors leverage existing airframe and engine OEM service contracts to embed predictive maintenance software, while specialized AI firms compete on algorithmic sophistication without equivalent certification credibility. Two archetypes dominate: integrated aerospace-industrial hybrids and pure-play aviation analytics specialists. Competitive moves concentrate on strategic partnerships bridging hardware-software gaps and technology licensing arrangements that accelerate regulatory validation.
Among the integrated aerospace-industrial tier, Airbus SE, Raytheon Technologies Corporation, and General Electric Company exemplify divergent strategic positioning. Airbus SE anchors predictive maintenance through its Skywise platform, representing the OEM-embedded archetype that bundles diagnostics with airframe service contracts. Raytheon Technologies Corporation occupies a defense-commercial hybrid position, with computer vision investments spanning military and civilian runway safety applications. General Electric Company sits within the engine-centric digital twin tradition, extending Edison platform capabilities from turbine diagnostics toward full flight operations optimization. These three entities collectively demonstrate how certification history and captive customer relationships determine competitive access in safety-critical aviation AI procurement cycles.
| Leading Market Players |
|---|
| Airbus SE |
| Raytheon Technologies Corporation |
| General Electric Company |
| Rolls-Royce plc |
| L3Harris Technologies, Inc. |
| Honeywell International Inc. |
| Thales S.A. |
| Leonardo S.p.A |
| The Boeing Company |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between DO-178C validated platforms and uncertified diagnostic tools creates parallel supply chains serving distinct buyer risk appetites. Premium-tier vendors command pricing power through captive MRO relationships and airframe OEM service bundling, while commodity AI providers compete on retrofit cost for legacy fleet operators outside Part 135 mandates.
Pricing Analysis
Bundled engine-MRO service contracts versus unbundled software licensing splits procurement patterns across carrier archetypes. Subscription SaaS-tiered models dominate predictive maintenance platforms, with price differentiation resting on EASA certification tier and edge computing hardware integration depth. Cost compression in the unbundled tier intensifies as LCCs disintermediate OEM service relationships. Regional Part 135 operators exhibit highest price sensitivity; Gulf network carriers show lowest.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing for AI inference hardware serving DGCA-certified platforms. Supply concentration centers on the United States, Germany, and Taiwan for aerospace-grade semiconductors and sensor arrays. Component dependencies include GPU accelerators, ARINC 429 bus interface modules, and vibration transducers. Single-source vulnerability runs through specialized foundry partnerships for DO-254 compliant chips. Distribution runs through airframe OEM captive service networks and independent aviation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aviation AI rests on predictive maintenance automation reducing unplanned downtime costs for fleet operators. The shift from calendar-based to condition-based maintenance creates premium-tier pricing power for certified platforms.
For Market Incumbents: Acquire specialized edge computing hardware-software integration capabilities to defend against pure-play AI vendors eroding service contract bundling. Deepen captive MRO relationships through exclusive predictive maintenance data sharing. Invest in multi-jurisdictional certification pathways ahead of EASA's forthcoming explainability mandates.
For New Entrants and Emerging Players: Natural language processing crew scheduling automation offers a technology-first wedge into Southeast Asian hybrid carriers outpacing manual rostering capacity. Target India's DGCA modernization window for first-mover validation partnerships with IndiGo and Air India. Lead with cloud-native deployment models lowering capital barriers for excluded regional operators.
For Investors and Strategic Acquirers: Asymmetric upside sits with aviation analytics specialists holding EASA pre-certification for safety-critical explainable AI models. Long-term viability favors vendors bridging hardware-software gaps rather than pure algorithmic plays. Watch for ICAO harmonization timeline acceleration as the inflection signal for autonomous flight system market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Certification Investment | Dual FAA-EASA validation pathways compress product launch windows for autonomous systems vendors. |
| Edge Computing Hardware Partnership | DO-178C compliant AI inference chips at sub-100ms latency demand specialized foundry alliances. |
| Federated Learning Architecture Deployment | Decentralized computation enables real-time decision support without cross-border data transmission. |
| Crew Management NLP Platform Launch | Multilingual disruption automation opens adjacent revenue pools beyond hardware diagnostics. |
| Digital Twin-as-a-Service Expansion | Cloud-native simulation lowers capital barriers for regional operators excluded from legacy ecosystems. |
Methodological Framework
Direct dialogue with airline CTOs, predictive maintenance platform engineers, FAA certification specialists, and MRO procurement directors grounded qualitative findings in operational reality. Secondary validation drew from FAA advisory circulars, EASA AI certification framework drafts, ICAO safety management documentation, and carrier fleet modernization disclosures. Bottom-up and top-down triangulation reconciled vendor shipment data with operator deployment timelines.
Bottom-up modeling segmented volume and value across the analysis window by product type, technology modality, application priority, and end-user procurement authority. An additional segmentation dimension captured certification pathway status—FAA Part 135 approved, EASA pre-certified, or uncertified experimental. CAGRs were derived from fitted adoption curves incorporating regulatory timeline acceleration scenarios and fleet retrofit saturation patterns. Forecast inputs included narrowbody order backlogs, regional carrier consolidation activity, and sovereign airspace automation mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EASA explainability mandate timing and ICAO harmonization progress. Forecasts reflect documented assumptions regarding regulatory pathway convergence and edge computing hardware qualification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market