
 Artificial Intelligence in Aviation Market | 2026-2036
Artificial Intelligence in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Aviation Market Intelligence
The delivery channel for aviation AI solutions is tilting from bespoke, on-premises systems toward scalable, cloud-based platforms. This shift benefits hyperscalers like Amazon Web Services and Microsoft Corporation, which provide the core infrastructure. Aerospace incumbents such as Thales S.A. and The Boeing Company compete by integrating AI directly into their avionics and operational software suites. General Electric Company leverages its extensive engine performance data to specialize in predictive maintenance solutions.
Artificial intelligence in aviation applies computational systems to automate complex decision-making. It leverages machine learning algorithms trained on terabytes of flight telemetry and maintenance data to improve operational safety and efficiency. Within applications, predictive maintenance and flight path optimization drive significant investment from airlines and aircraft manufacturers. Machine learning continues to be the dominant technology, with computer vision finding new use cases in airport security and ground operations.
Regulatory bodies, including the U.S. Federal Aviation Administration (FAA) and its European counterparts, are developing stringent certification pathways for safety-critical AI. Data governance is shaped by frameworks like the EU AI Act, which dictates requirements for algorithm transparency and risk management. Stakeholders must now navigate the challenge of balancing innovation in areas like passenger experience enhancement with the rising costs of regulatory compliance and system validation.
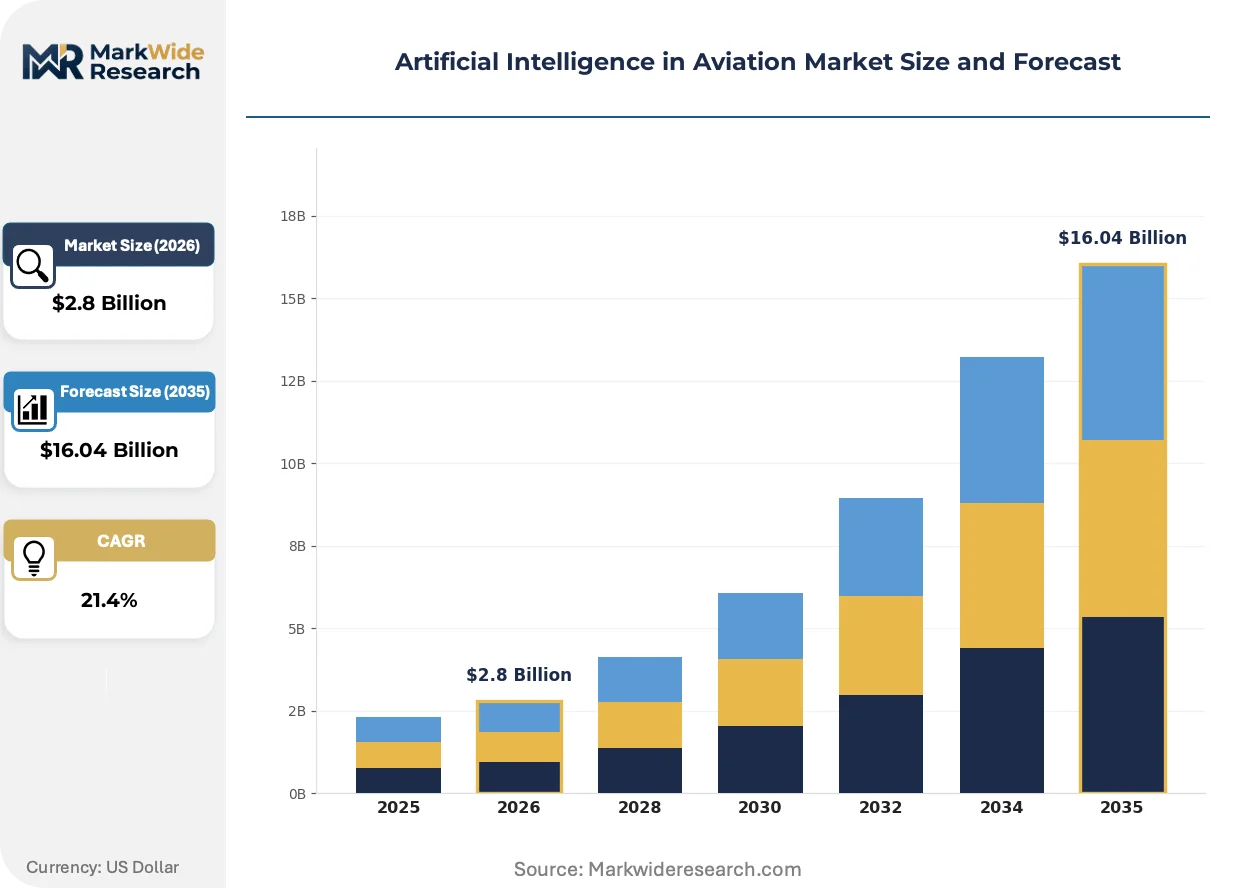
Market Dynamics
The economic viability of artificial intelligence in aviation is driven by the convergence of scalable cloud infrastructure with the vast data streams generated by modern aircraft. This enables the deployment of computationally intensive machine learning models for applications previously limited by on-premises processing power.
Growth Catalysts
- Predictive Maintenance Demand:Airlines are adopting AI-driven predictive maintenance to minimize aircraft on ground (AOG) situations and reduce unscheduled maintenance costs, directly improving fleet availability and operational reliability.
- Fuel Efficiency Imperatives:Volatile fuel prices and sustainability mandates from bodies like the International Civil Aviation Organization (ICAO) push carriers to invest in AI-powered flight path optimization tools to cut consumption.
- Algorithm Advancement:The proliferation of more sophisticated machine learning and deep learning algorithms enables more accurate predictions and automated decision-making, expanding the scope of viable AI applications in aviation.
Market Restraints
- High Integration Cost:The significant capital and time required to integrate new AI systems with fragmented legacy IT infrastructure and avionics suites across airline fleets acts as a major barrier to adoption.
- Stringent Certification Pathways:Regulatory bodies like the U.S. Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) have long, complex validation processes for safety-critical software, slowing innovation.
- Explainability Challenges:The "black box" nature of some advanced neural networks creates difficulties in validating their decision-making processes, a critical requirement for certification in safety-critical flight applications.
Strategic Opportunities
- Autonomous Ground Operations:AI and computer vision present opportunities to automate airport ground support functions, such as baggage handling, aircraft towing, and tarmac security monitoring, improving efficiency and safety.
- Digital Twin Simulation:The convergence of AI with digital twin technology allows for the creation of high-fidelity virtual models of aircraft and engines for advanced simulation, testing, and predictive analysis.
- Emerging Market Adoption:Rapid fleet expansion and new airport construction in regions like the Middle East and Southeast Asia provide a greenfield opportunity for deploying modern, AI-native operational systems from the outset.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage of data scientists and AI developers who also possess the necessary aerospace engineering and aviation domain expertise limits development and implementation capacity.
- Data Sharing and Governance:Establishing secure and standardized protocols for sharing sensitive operational and maintenance data between manufacturers, airlines, and MRO providers remains a complex technical and commercial hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Aviation Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $16.04 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Flight Path Optimization, Predictive Maintenance, Passenger Experience Enhancement, Crew Scheduling, Air Traffic Management Technology: Machine Learning, Natural Language Processing, Computer Vision, Expert Systems, Robotic Process Automation End User: Airlines, Airport Authorities, Aircraft Manufacturers, Maintenance Providers, Air Navigation Service Providers Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Airbus SE, Thales S.A., General Electric Company, Amazon Web Services, Inc., Raytheon Technologies Corporation, Honeywell International Inc., Microsoft Corporation, Amadeus IT Group SA, The Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Aviation Market Strategic Shifts & Innovations
The market is shifting from bespoke, single-point AI solutions toward integrated, platform-based ecosystems. This transition favors scalable cloud architectures and is redefining how airlines procure and deploy intelligence across their operations, from the cockpit to the maintenance hangar.
Generative AI models are being developed using extensive libraries of technical manuals and historical aircraft maintenance records. Maintenance, Repair, and Overhaul (MRO) organizations are beginning to adopt these tools to dramatically accelerate diagnostic procedures for complex avionic and mechanical faults. This application of advanced AI is rendering obsolete the manual, time-consuming process of searching through thousands of pages of documentation for fault isolation.
The EU AI Act establishes a risk-based framework that classifies many aviation systems as high-risk. This regulation imposes stringent requirements for data quality, algorithm transparency, and human oversight on applications such as autonomous flight controls. In response, aerospace technology suppliers are intensifying their focus on developing explainable AI (XAI) to ensure their products meet future compliance standards for access to the European market.
Airlines are increasingly moving from one-time software license purchases to subscription-based consumption of AI capabilities. This change disrupts the traditional model of on-premises system development, creating an opening for cloud-native platforms that offer a suite of applications for a recurring fee. The preference for opex-based procurement is most visible in the United States, where carriers seek scalable solutions without the large upfront capital investment.
Artificial Intelligence in Aviation Market Segmentation
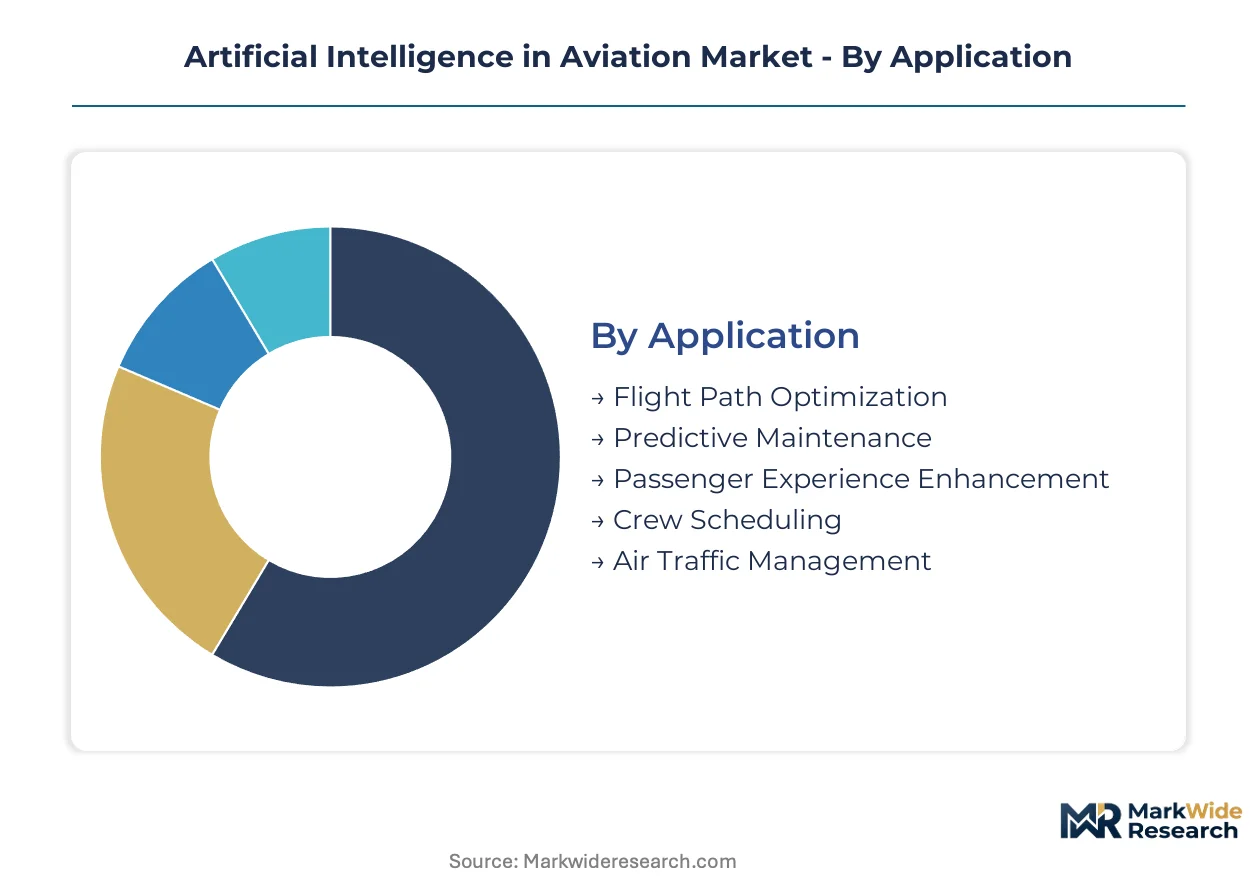
The Artificial Intelligence in Aviation Market's intricate structure reflects diverse technological applications and operational needs across the aerospace ecosystem. Understanding these distinct segments provides clarity on investment priorities and strategic development pathways for market participants. This segmentation highlights areas of established AI integration alongside emerging opportunities for innovation and expansion.
Application:
This category delineates the maturity spectrum of AI applications, from established operational efficiencies to nascent passenger-facing innovations.
- Predictive Maintenance:These systems leverage machine learning algorithms to forecast equipment failures based on real-time sensor data and historical performance. Demand concentrates in the United States, where major airlines prioritize minimizing aircraft on ground (AOG) events and reducing unscheduled maintenance costs.
- Flight Path Optimization:AI models analyze meteorological data, air traffic control information, and aircraft performance metrics to recommend the most fuel-efficient and timely routes. Global sustainability mandates from bodies like ICAO drive carrier investment in reducing fuel consumption and carbon emissions.
- Passenger Experience Enhancement:AI supports personalized services, intelligent chatbots for customer support, and biometric identification for streamlined airport processes.
- Crew Scheduling:Algorithms optimize crew rosters considering regulatory limits, operational constraints, and individual preferences for airlines.
- Air Traffic Management:AI assists air traffic controllers by predicting congestion, optimizing runway usage, and enhancing safety protocols in busy airspace.
Predictive Maintenance handles the majority of throughput; Flight Path Optimization is the fastest mover on share.
Technology:
The market's technological landscape indicates where computational power and data processing capabilities are most concentrated within the aviation sector.
- Machine Learning:This foundational technology involves algorithms trained on vast datasets to identify patterns and make predictions without explicit programming. Its widespread deployment across predictive maintenance and flight optimization drives significant investment from aerospace incumbents.
- Natural Language Processing:NLP enables computers to understand, interpret, and generate human language, supporting applications like intelligent chatbots and automated documentation analysis. Airlines in Europe are increasingly deploying NLP for customer service automation and technical manual processing.
- Computer Vision:This technology allows systems to interpret and understand visual information from cameras, enhancing airport security and ground operations monitoring.
- Expert Systems:Rule-based AI systems encode human expertise to solve complex problems, often used for diagnostic support in maintenance.
- Robotic Process Automation:RPA automates repetitive, rule-based tasks in back-office operations, improving administrative efficiency for aviation companies.
Machine Learning maintains the broadest market penetration, while Computer Vision exhibits the steepest expansion trajectory due to new security applications.
End User:
End user segmentation highlights the distinct types of organizations driving demand and integrating AI solutions across the aviation value chain.
- Airlines:These operators leverage AI for operational efficiency, cost reduction, and enhancing passenger experience across their vast fleets and networks. Carriers globally, particularly in the Middle East, are investing heavily in AI for fuel efficiency and predictive maintenance to manage large aircraft orders.
- Aircraft Manufacturers:OEMs integrate AI into aircraft systems, design processes, and after-sales support, focusing on performance optimization and safety. Companies like The Boeing Company utilize AI for digital twin simulations and advanced avionics development.
- Airport Authorities:These entities deploy AI for security screening, crowd management, ground operations optimization, and facility maintenance.
- Maintenance Providers:MRO organizations use AI for fault diagnostics, inventory management, and optimizing maintenance schedules for various aircraft types.
- Air Navigation Service Providers:ANSPs apply AI to enhance air traffic flow management, conflict detection, and airspace capacity optimization.
Airlines represent the largest investment segment, with Airport Authorities showing increasing strategic focus on AI-driven operational improvements.
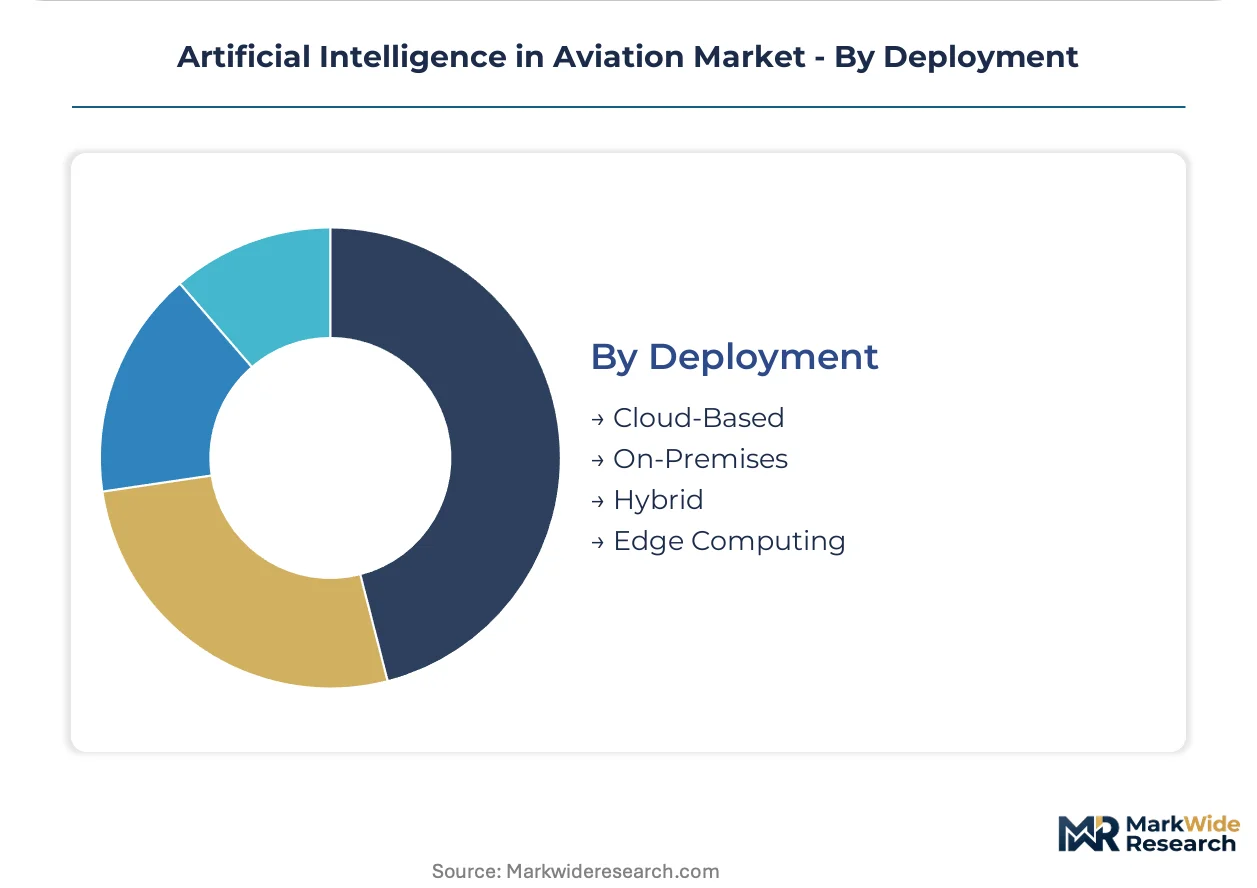
Deployment:
This category differentiates AI solution delivery models based on infrastructure requirements and operational flexibility for aviation stakeholders.
- Cloud-Based:AI solutions hosted on remote servers and accessed over the internet, offering scalability, reduced upfront costs, and flexible resource allocation. Hyperscalers like Amazon Web Services benefit from this shift as airlines prioritize opex-based procurement models, especially in the United States.
- On-Premises:AI systems installed and run directly on an organization's own physical infrastructure, providing maximum control and data security. Aerospace incumbents often maintain on-premises systems for highly sensitive data and legacy integration requirements.
- Hybrid:A combination of cloud and on-premises deployment, allowing organizations to manage sensitive workloads locally while leveraging cloud scalability for others.
- Edge Computing:Processing AI algorithms closer to the data source, such as on an aircraft or at an airport gate, for real-time decision-making and reduced latency.
Cloud-Based solutions are gaining significant market traction due to their inherent scalability, while On-Premises deployments remain critical for established, safety-critical systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Federal Aviation Administration (FAA) sets stringent certification pathways for AI, influencing global standards for safety-critical aviation systems. The United States leads in AI adoption due to major aircraft manufacturers and carriers being early adopters. This region prioritizes predictive maintenance and flight path optimization applications.
United States
Demand for predictive maintenance and flight path optimization drives significant investment from American airlines. The FAA's regulatory framework ensures rigorous validation for safety-critical AI applications in commercial aviation. Silicon Valley and Seattle serve as innovation hubs, fostering AI development for aerospace and defense sectors.
Germany
German airlines and manufacturers prioritize AI for operational efficiency and advanced maintenance solutions. The European Union Aviation Safety Agency (EASA) works on certifying AI-driven avionics and ground support systems. Munich and Hamburg are major centers for aerospace engineering and AI research, attracting specialized talent.
France
French investment in AI focuses on integrated avionics and advanced air traffic management solutions. The EU AI Act influences transparency and risk management requirements for new AI systems in safety-critical contexts. Toulouse, a prominent aerospace cluster, sees AI integrated into aircraft design, manufacturing, and operational software.
United Arab Emirates
Rapid fleet expansion and new airport infrastructure drive AI adoption for ground operations and passenger experience in the UAE. The General Civil Aviation Authority (GCAA) supervises AI deployment in national airspace and airport security. Dubai and Abu Dhabi are investing in smart airport technologies and AI-native operational systems to enhance efficiency.
Singapore
Singapore's AI applications enhance air traffic management and airport security for this critical regional hub. The Civil Aviation Authority of Singapore (CAAS) promotes innovation while maintaining strict safety standards. Changi Airport is a testbed for computer vision and automation in ground services, improving throughput and security.
Artificial Intelligence in Aviation Market Key Industry Players
Hyperscale cloud providers and established aerospace incumbents split the market for artificial intelligence in aviation, each leveraging distinct strengths. Cloud providers offer scalable infrastructure and platform-based solutions, attracting airlines with opex-based procurement models. Aerospace incumbents integrate AI directly into their proprietary avionics and operational software suites, focusing on safety-critical applications. Companies compete through strategic partnerships, continuous integration of advanced algorithms, and specialized expertise in aviation data.
Across the competitive spectrum, Amazon Web Services, Inc. represents the growing influence of cloud-native platforms, offering scalable infrastructure for AI deployment across various aviation stakeholders. The Boeing Company exemplifies traditional aircraft manufacturers that embed AI into aircraft systems, focusing on digital twin simulations and advanced avionics development. Thales S.A., a French multinational, occupies a position as a key aerospace incumbent, specializing in integrated operational software suites and air traffic management solutions. These entities collectively shape the market by providing foundational infrastructure, integrated hardware-software solutions, and specialized AI applications tailored for the aviation sector.
| Leading Market Players |
|---|
| Airbus SE |
| Thales S.A. |
| General Electric Company |
| Amazon Web Services, Inc. |
| Raytheon Technologies Corporation |
| Honeywell International Inc. |
| Microsoft Corporation |
| Amadeus IT Group SA |
| The Boeing Company |
| Others |
Cost & Logistics Intelligence
Silicon Valley's concentration of AI development talent and cloud infrastructure capacity influences the pricing of advanced aviation AI solutions, shaping their accessibility for global carriers. This regional dominance impacts the competitive landscape for scalable platforms.
Pricing Analysis
Price disparities for aviation AI solutions emerge between regions, reflecting varying regulatory compliance costs and market maturity. Subscription-based models dominate, replacing traditional perpetual licenses, driven by airlines' preference for operational expenditure. Price differentiation stems from solution scalability, integration complexity, and the level of regulatory certification. Pricing pressure increases on highly specialized, safety-critical AI systems due to stringent validation requirements, while airlines exhibit higher price sensitivity towards large upfront capital investments.
Supply Chain Analysis
The upstream supply for aviation AI heavily relies on specialized computational components and cloud infrastructure, primarily originating from the United States and East Asian technology hubs. Key dependencies include advanced machine learning accelerators and high-capacity data storage solutions. A significant structural risk involves the scarcity of specialized AI talent with aerospace domain expertise, limiting development capacity. Distribution runs through scalable cloud platforms provided by hyperscalers and integrated directly into avionics by aerospace incumbents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Artificial Intelligence in Aviation Market presents a fragmentation opportunity, driven by diverse demand for specialized applications beyond core predictive maintenance. This creates niches for focused solutions addressing unique operational and regulatory needs.
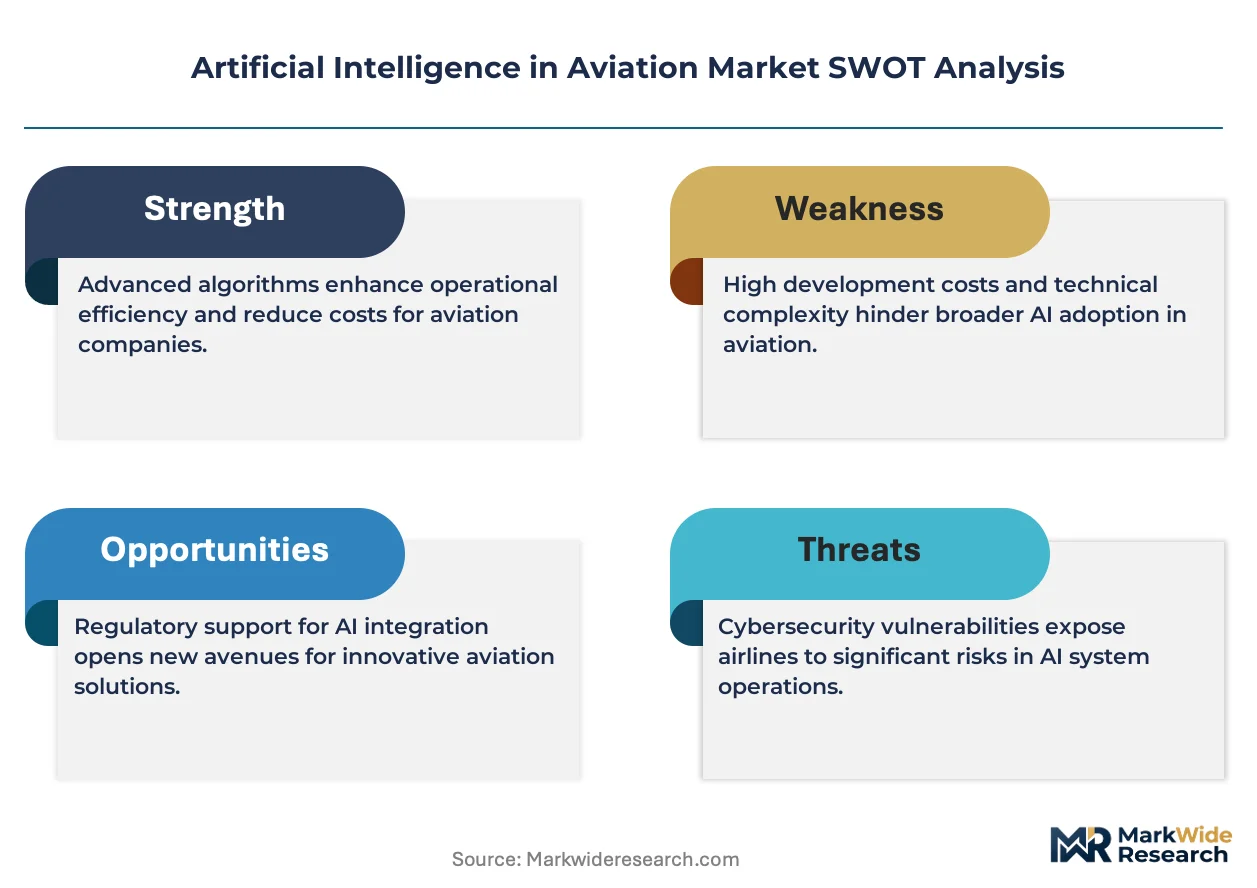
For Market Incumbents: Harden existing avionics and operational software suites by integrating advanced explainable AI capabilities. This counters the threat from cloud-native platforms and addresses stringent regulatory certification pathways, particularly the EU AI Act. Investment in robust data governance protocols and specialized talent development will reinforce their market position against niche challengers.
For New Entrants and Emerging Players: Build out specialized AI solutions targeting underpenetrated segments like autonomous ground operations and digital twin simulation. The most penetrable segments are airport authorities in emerging markets, where new infrastructure provides greenfield opportunities. A cloud-native, subscription-based go-to-market strategy enables rapid deployment and lower upfront costs for adoption.
For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace incumbents seeking to divest non-core AI units or from successful startups specializing in niche aviation AI applications. Long-term viability for AI in aviation remains strong over the next decade, driven by efficiency and safety imperatives. Acquisition profiles should focus on companies with proven explainable AI capabilities or unique access to operational data. The signal to watch is the acceleration of clear regulatory certification pathways from bodies like the FAA.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Certification Investment | Ensures compliance with stringent regulatory bodies like the FAA, opening access to safety-critical applications. |
| Cloud Platform Partnership | Leverages hyperscaler infrastructure for scalable AI deployment, reducing operational expenditure for airlines. |
| Explainable AI (XAI) Development | Addresses "black box" challenges, crucial for validating AI decisions in safety-critical flight applications. |
| Digital Twin Integration | Enhances predictive maintenance and advanced simulation capabilities for aircraft manufacturers and MROs. |
| Talent Development Programs | Mitigates the scarcity of specialized data scientists with aerospace engineering and aviation domain expertise. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform this analysis of the Artificial Intelligence in Aviation Market. Primary interviews with airline operations managers, aircraft design engineers, airport security heads, and MRO technicians were conducted. This was validated against secondary sources including FAA and EASA regulatory documents, ICAO reports, and SEC filings. Bottom-up and top-down triangulation ensured data integrity.
The quantitative model was calibrated through a rigorous process integrating historical market performance with projected adoption rates across the analysis window. Segmentation dimensions modeled include application, technology, end user, deployment, and regulatory compliance tier. Compound annual growth rates were derived from a synthesis of primary insights and secondary data. Key industry-specific inputs included anticipated fuel price volatility and global air traffic growth projections.
Stress conditions across geopolitical stability and technological innovation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and sustained investment in aviation AI. Cross-checking against ICAO or EASA industry benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Mexico Aerospace Market