
 AI in Defense Market | 2026-2036
AI in Defense Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Defense Market Insights
Platform licensing revenue is reshaping competitive economics as defense primes pivot from hardware sales to recurring software subscriptions. Lockheed Martin Corporation leverages its classified AI infrastructure contracts to sustain long-term revenue visibility. Palantir Technologies dominates the government intelligence analytics layer through its data fusion platforms.
AI in Defense encompasses machine learning algorithms, computer vision architectures, and autonomous decision systems engineered to operate in contested electromagnetic environments with sub-second inference latency. These technologies serve military command structures by compressing sensor-to-shooter timelines and automating threat prioritization. Surveillance Systems and Cybersecurity Solutions command the largest current revenue pools, while Autonomous Vehicles represents the fastest-expanding segment as unmanned platforms proliferate across air, ground, and maritime domains. Edge Computing deployment is gaining traction where cloud connectivity remains tactically vulnerable.
The U.S. Department of Defense, the UK's Ministry of Defence, and NATO standardization bodies impose stringent algorithmic transparency and data sovereignty requirements that filter vendor eligibility and shape procurement specifications. The EU AI Act adds compliance complexity for transatlantic defense technology transfers. Stakeholders must monitor evolving export control classifications and sovereign data localization mandates to anticipate contract eligibility shifts.
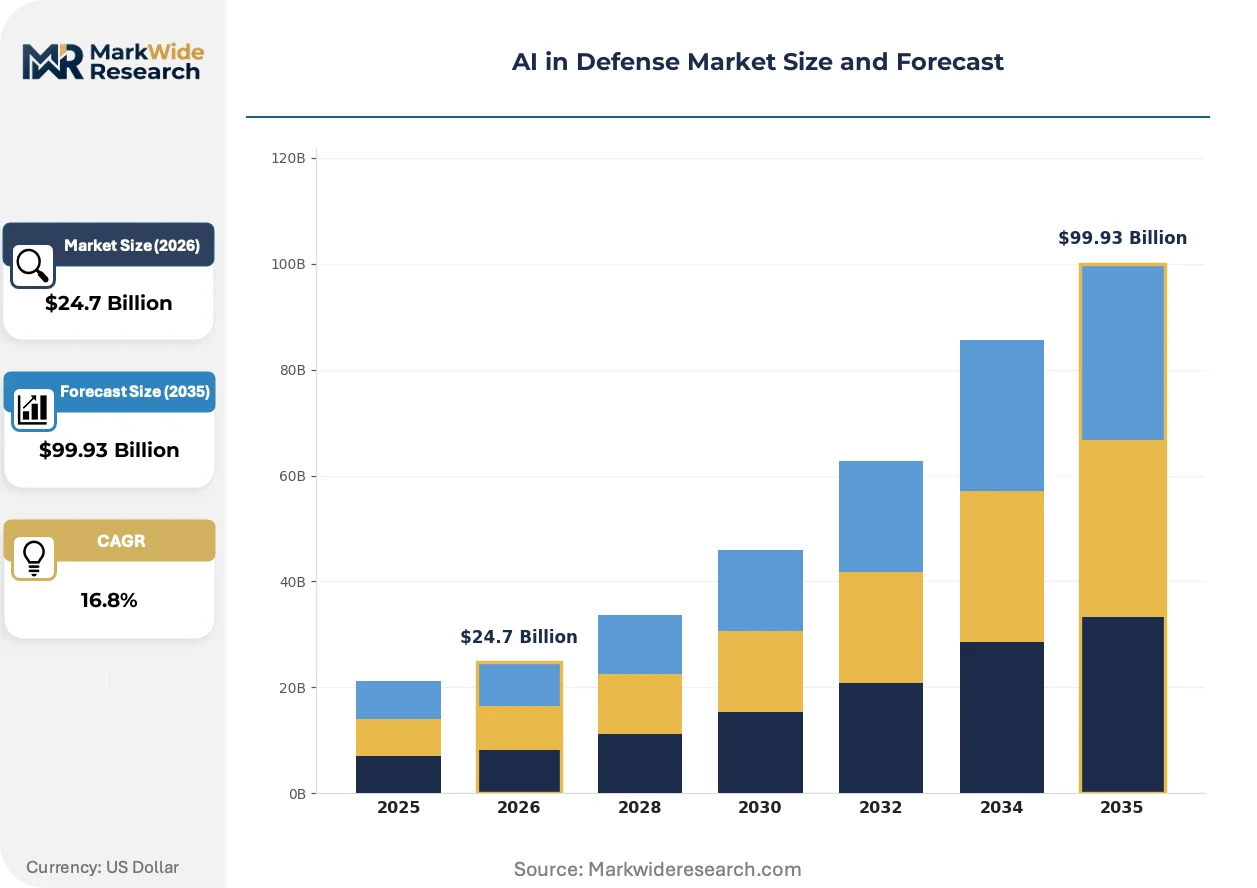
Market Dynamics
Platform licensing revenue is collapsing the traditional hardware-centric business model across defense procurement, as primes pivot toward recurring software subscriptions that embed algorithmic updates and sovereign data controls directly into long-term contracts.
Growth Catalysts
- Autonomous Surveillance Systems:Naval operations in contested maritime zones drive demand for unmanned platforms capable of persistent underwater and surface monitoring without crew exposure.
- EU AI Act Compliance Framework:Mandates for algorithmic transparency and human oversight create procurement specifications that favor vendors with pre-certified ethical AI governance structures.
- Edge Computing Deployment:Sub-second inference requirements in electromagnetic-denied environments accelerate hardware-software co-design for tactical decision nodes.
Market Restraints
- Semiconductor Supply Concentration:Advanced GPU and neuromorphic chip fabrication concentrates in East Asian foundries, exposing defense programs to export control volatility and supply interruption risks.
- Data Sovereignty Fragmentation:NATO members, Israel, and the United Kingdom impose conflicting localization mandates that complicate multi-national platform deployment and interoperability certification.
- Legacy System Integration Costs:Existing command-and-control architectures built on proprietary protocols require expensive middleware development to interface with modern AI inference engines.
Strategic Opportunities
- Underpenetrated Maritime Domain:Autonomous underwater vehicles and unmanned surface vessels remain below saturation in littoral surveillance applications across Southeast Asian and Northern European waters.
- Neuromorphic-Quantum Convergence:Hybrid computing architectures combining spiking neural networks with quantum random number generators promise breakthrough resilience against adversarial AI attacks.
- UK Ministry of Defence AI Strategy:Sovereign capability investments under the 2023 Defence AI Centre roadmap create dedicated procurement channels for domestic and Five Eyes vendors.
Industry Challenges
- Adversarial Machine Learning Expertise Gap:Military AI red teams lack sufficient personnel trained in evasion, poisoning, and model extraction attack methodologies specific to defense-grade systems.
- Cross-Domain Certification Timelines:Air, land, sea, and space platform qualification boards operate non-harmonized safety standards that delay multi-domain autonomous system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Defense Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $99.93 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Surveillance Systems, Cybersecurity Solutions, Autonomous Vehicles, Data Analytics Tools Deployment Model: On-Premises, Cloud-Based, Hybrid Model, Edge Computing End User: Military, Government Agencies, Defense Contractors, Research Institutions Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation, Raytheon Technologies Corporation, BAE Systems plc, Thales Group, L3Harris Technologies, General Dynamics Corporation, Palantir Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Defense Market Trends and Innovations
Defense AI development is collapsing traditional acquisition timelines through continuous integration pipelines that deploy algorithmic updates directly to operational platforms without hardware refresh cycles.
Neuromorphic computing architectures are collapsing the power-performance tradeoff that constrained prior generations of embedded AI. The U.S. Department of Defense's Rapid Capabilities Office is fielding pilot programs for event-based vision sensors that reduce inference energy by orders of magnitude. This compression enables persistent autonomous operations on platforms with severe weight and thermal constraints.
The EU AI Act's high-risk system classification is reshaping transatlantic technology transfer protocols. Defense contractors must now maintain parallel development tracks for European and non-European deployments to satisfy divergent transparency and human-in-the-loop mandates. Israeli and UK primes with pre-established ethical AI governance frameworks are capturing early-mover advantage in NATO procurement competitions.
Software subscription models are displacing perpetual licensing across intelligence analytics and command-and-control segments. Defense ministries in the United States and United Kingdom now prioritize vendors offering algorithm-as-a-service architectures with guaranteed update frequencies. This transformation concentrates procurement authority within technical evaluation teams capable of assessing continuous deployment pipelines rather than static capability demonstrations.
AI in Defense Market Segmentation
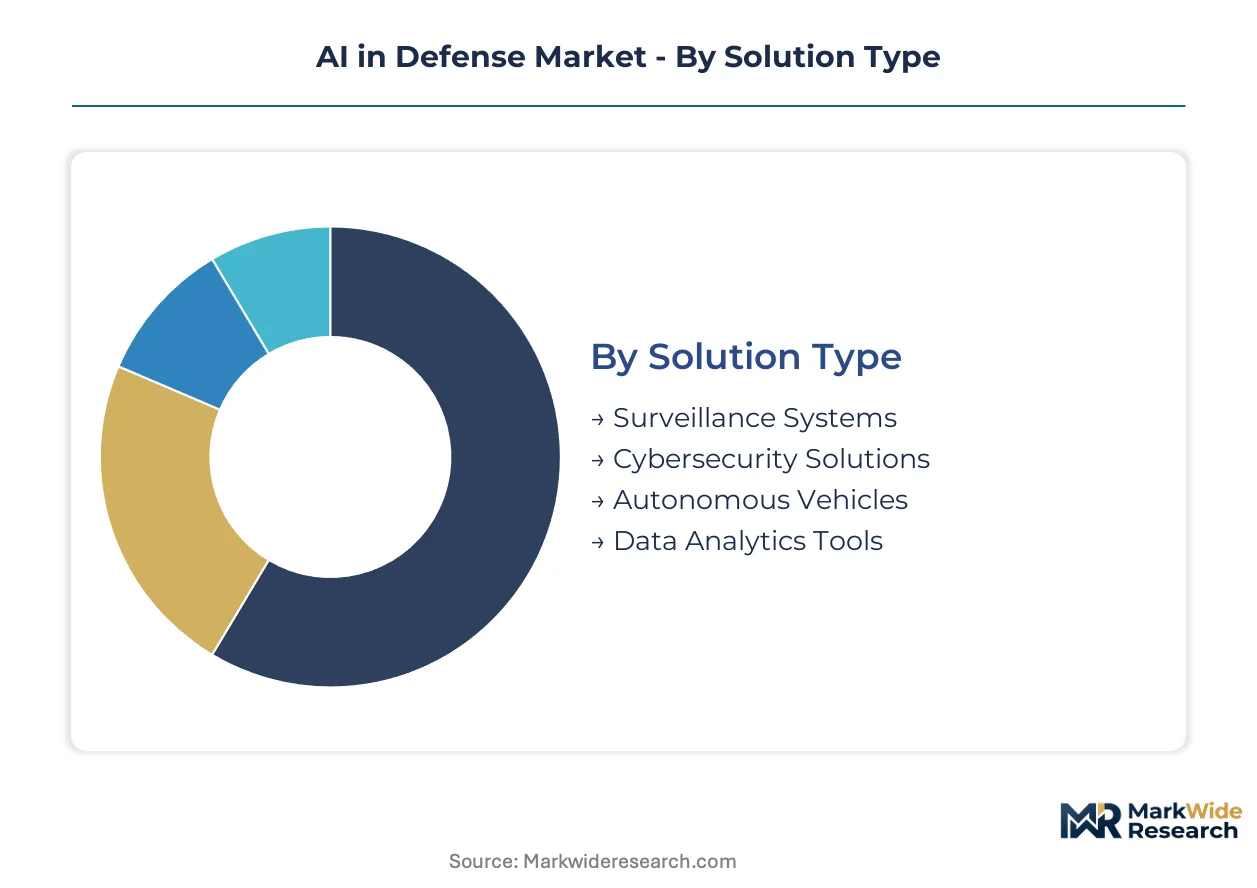
Defense AI procurement channels fragment across solution architectures, deployment topologies, and end-user security classifications. Segmentation clarity enables vendors to align R&D roadmaps with sovereign capability mandates and operational tempo requirements.
Solution Type:
Mature surveillance platforms coexist with emerging autonomous vehicle stacks across current defense budgets.
- Surveillance Systems:Persistent monitoring architectures fuse multi-spectral sensors with real-time anomaly detection for littoral and border applications. The United Kingdom and Israel concentrate procurement for maritime domain awareness under sovereign data controls.
- Cybersecurity Solutions:Adversarial AI defense modules protect classified networks through behavioral biometrics and automated threat hunting. Military command centers in the United States drive specification requirements for zero-trust inference environments.
- Autonomous Vehicles:Unmanned platforms with embedded decision nodes for contested electromagnetic operations.
- Data Analytics Tools:Intelligence fusion pipelines compress multi-source data into prioritized threat matrices.
Surveillance Systems handles the majority of throughput; Autonomous Vehicles is the fastest mover on share.
Deployment Model:
Cost tier separation distinguishes sovereign-controlled infrastructure from scalable cloud alternatives.
- On-Premises:Air-gapped installations within classified facilities satisfy NATO and Five Eyes data localization mandates. Defense ministries in the United States and United Kingdom require hardware roots of trust and tamper-evident enclosures for sensitive model training.
- Edge Computing:Sub-second inference on tactical platforms operates without persistent connectivity. Maritime and airborne applications in contested Pacific theaters prioritize thermal-efficient neural accelerators.
- Cloud-Based:Elastic compute for unclassified logistics and training simulation workloads.
- Hybrid Model:Tiered classification routing between secure enclaves and scalable backends.
On-Premises absorbs the largest capital allocation; Edge Computing climbs the fastest on operational deployment timelines.
End User:
Customer type determines security clearance depth and procurement authority levels.
- Military:Operational commands require battle-ready inference with formal verification of decision logic. The U.S. Department of Defense and UK Ministry of Defence issue capability requirements through classified acquisition channels.
- Defense Contractors:Prime integrators embed AI subsystems into platform deliveries with sovereign IP transfer clauses. Israeli and United States vendors dominate prime-tier relationships through cleared personnel pipelines.
- Government Agencies:Intelligence community consumers of finished analytic products.
- Research Institutions:Academic and national laboratory partners for algorithmic validation.
Military commands direct the preponderance of program funding; Defense Contractors are expanding their share fastest through platform integration mandates.
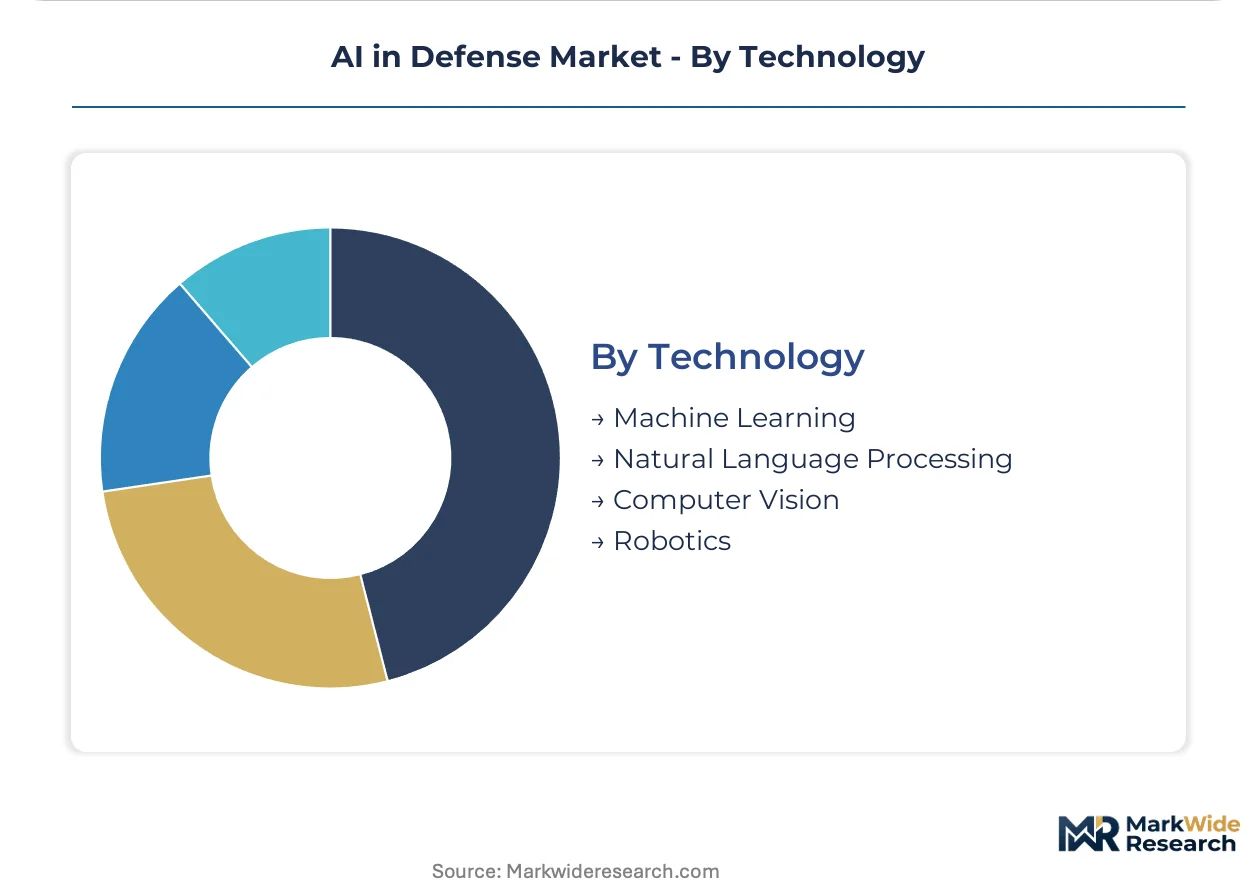
Technology:
Application focus separates perception-layer systems from cognitive automation stacks.
- Machine Learning:Supervised and reinforcement learning pipelines optimize logistics, maintenance forecasting, and electronic warfare parameter selection. The U.S. Department of Defense's Chief Digital and Artificial Intelligence Office sets interoperability standards.
- Computer Vision:Real-time target recognition and sensor fusion for manned-unmanned teaming. Israeli defense primes lead in low-light and adverse-weather classification accuracy.
- Natural Language Processing:Multi-source intelligence summarization and cross-lingual document exploitation.
- Robotics:Physical actuation and manipulation for explosive ordnance disposal and logistics.
Machine Learning underpins the widest capability portfolio; Computer Vision is gaining share fastest on unmanned platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries in Israel and the United Kingdom demonstrate the least price elasticity for sovereign AI capabilities, while procurement authorities in Germany and Japan impose stricter cost-performance thresholds on autonomous platform acquisitions.
United States
The U.S. Department of Defense's Chief Digital and Artificial Intelligence Office drives demand for sub-second inference systems and manned-unmanned teaming architectures. The Pentagon's updated ethical AI deployment guidelines filter vendor eligibility through algorithmic transparency mandates. Defense primes cluster around Washington D.C., Northern Virginia, and Greater Boston, where classified AI infrastructure contracts concentrate procurement authority within technical evaluation teams.
United Kingdom
The UK Ministry of Defence's 2023 Defence AI Centre roadmap accelerates sovereign capability investments across autonomous surveillance and maritime domain awareness. The EU AI Act's high-risk system classification creates parallel development requirements for European deployments. London and the Southeast anchor prime-tier relationships, while Scotland's defense electronics corridor hosts cleared personnel pipelines for Five Eyes intelligence fusion platforms.
Israel
Israeli Defense Forces operational requirements prioritize low-light computer vision and contested electromagnetic environment resilience. The country's national AI regulator imposes stringent data localization mandates that complicate transatlantic technology transfers. Tel Aviv and Haifa host dense concentrations of defense AI specialists with pre-certified ethical governance frameworks capturing early-mover advantage in NATO procurement competitions.
Germany
The Bundeswehr's procurement office demands cost-verified integration pathways for legacy command-and-control architectures. Germany's federal data protection authority enforces sovereign data controls that delay multi-national platform certification. Munich and Stuttgart industrial clusters specialize in middleware development for proprietary protocol interfacing with modern inference engines.
Japan
The Japan Ministry of Defense accelerates unmanned maritime platform acquisitions for Indo-Pacific littoral surveillance. METI's semiconductor supply chain resilience initiatives reduce exposure to East Asian foundry concentration risks. Tokyo and Nagoya defense electronics corridors prioritize thermal-efficient neural accelerators for airborne applications in contested Pacific theaters.
AI in Defense Market Competitive Landscape
Capability concentration sits with classified infrastructure specialists; scale advantage sits with platform integrators with established defense ministry relationships. The vendor base separates into three tiers: primes with air-gapped facility clearances, mid-tier analytics specialists, and emerging autonomy stack providers. Dominant competitive moves include sovereign IP transfer clauses in prime contracts and continuous integration pipelines that collapse traditional hardware refresh cycles.
Within the classified infrastructure tier, Lockheed Martin Corporation and Northrop Grumman Corporation represent primes with long-term revenue visibility through sustained technical evaluation team relationships. Palantir Technologies occupies a position among analytics specialists dominating government intelligence fusion layers. These three exemplify the shift from perpetual licensing to algorithm-as-a-service architectures with guaranteed update frequencies.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| RTX Corporation |
| Raytheon Technologies Corporation |
| BAE Systems plc |
| Thales Group |
| L3Harris Technologies |
| General Dynamics Corporation |
| Palantir Technologies |
| Others |
Pricing and Supply Chain Analysis
East Asian foundry concentration for advanced GPU and neuromorphic chip fabrication anchors cost structures across defense AI procurement, with margin pools accumulating in algorithm-as-a-service tiers rather than hardware deliveries. Sovereign data localization mandates in NATO member states and Israel fragment procurement into compliance-bounded contract vehicles that resist pure price competition.
Pricing Analysis
Platform licensing and extended algorithm update subscriptions generate lifetime value multiples exceeding perpetual software licenses by embedding sovereign data controls and continuous deployment pipelines into multi-year contracts. Pricing stratifies across premium, standard, and economy tiers based on security clearance depth and inference latency guarantees. Cost compression in unclassified logistics and training simulation workloads intensifies as cloud-based alternatives commoditize baseline analytics. Defense contractors exhibit the least price sensitivity due to prime-tier relationship lock-in, while government agencies face strict cost-performance thresholds on autonomous platform acquisitions.
Supply Chain Analysis
Tariff exposure between East Asian semiconductor manufacturing hubs and Western defense procurement channels dominates supply chain risk assessment for neuromorphic and advanced GPU components. Advanced chip fabrication concentrates in Taiwan, South Korea, and select Chinese facilities, while rare earth processing and neural accelerator packaging draw from China and Japan. Single-source vulnerability in photolithography equipment and advanced substrate materials threatens program continuity. Distribution runs through cleared prime integrators with air-gapped facility certifications rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense AI procurement operates as a defensive-moat market where regulatory entrenchment through classified facility clearances and sovereign algorithm certification creates durable competitive barriers. Network effects concentrate in intelligence fusion platforms where data volume improves model performance.
For Market Incumbents: Build switching-cost moats through embedded sovereign IP transfer clauses and continuous integration pipelines that collapse hardware refresh cycles. Deepen backward integration into classified AI infrastructure by acquiring cleared personnel pipelines in Washington D.C. and Greater Boston clusters. Counter emerging autonomy stack providers by accelerating manned-unmanned teaming certification timelines across air and maritime domains. For New Entrants and Emerging Players: Mid-tier analytics specialists serving UK Ministry of Defence and Israeli Defense Forces intelligence fusion layers represent the most penetrable entry point for vendors without prime-tier relationships. Autonomous underwater vehicles for Southeast Asian littoral surveillance offer white-space expansion beneath saturation levels of established naval primes. Pursue ethical AI governance pre-certification under EU AI Act frameworks to unlock NATO procurement competitions. For Investors and Strategic Acquirers: Capital is best deployed toward classified infrastructure specialists with air-gapped facility clearances and sustained technical evaluation team relationships. Long-term viability hinges on algorithm-as-a-service revenue visibility rather than transactional hardware margins. Monitor UK Defence AI Centre roadmap funding allocations and U.S. Chief Digital and Artificial Intelligence Office capability requirements as inflection indicators for sovereign procurement priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Ethical AI Governance Certification | EU AI Act compliance unlocks NATO procurement channels for transatlantic vendors. |
| Edge Computing Hardware Co-Design | Thermal-efficient neural accelerators enable persistent operations in contested Pacific theaters. |
| Continuous Integration Pipeline Deployment | Algorithm-as-a-service architectures collapse traditional hardware refresh acquisition timelines. |
| Sovereign Data Localization Infrastructure | Air-gapped installations satisfy Five Eyes mandates and resist cloud commoditization pressure. |
| Neuromorphic-Quantum Hybrid R&D | Spiking neural network architectures promise resilience against adversarial AI extraction attacks. |
Research Methodology
Cross-validation between primary interviews with defense procurement officers and secondary validation through U.S. Department of Defense budget justification documents anchors the qualitative findings. Chief Digital and Artificial Intelligence Office capability requirement filings, UK Ministry of Defence equipment plan disclosures, and NATO standardization body technical specifications constitute core secondary sources. Bottom-up triangulation aggregates segment-specific deployment timelines while top-down calibration cross-checks against aggregate sovereign defense AI budget trajectories.
Calibration against historical procurement cycle timing and platform qualification board throughput shapes the analytical framework across the analysis window. Segmentation dimensions modeled include solution architecture, deployment topology, end-user security classification, and sovereign data governance tier. CAGRs derive from weighted capacity deployment schedules and algorithm-as-a-service contract renewal velocity. Neuromorphic chip fielding timelines and ethical AI certification queue lengths serve as industry-specific forecast inputs.
Practitioners should monitor export control classification revisions and semiconductor supply interruption events for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Aerospace TIC Market