
 Aerospace TIC Market | 2026-2036
Aerospace TIC Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace TIC Market Analysis
Market Context
Aerospace NDT technician availability is bifurcating market growth between established aviation hubs and emerging manufacturing zones. SGS SA leverages its global laboratory network to sustain certification capacity across multiple regulatory jurisdictions. Bureau Veritas anchors its competitive position through specialized aerospace testing protocols that dominate European OEM supply chains.
Technical Definition and Segments
Aerospace TIC encompasses the independent verification of materials, components, and systems against airworthiness standards through destructive and non-destructive methods, including ultrasonic phased-array inspection of titanium fan discs and radiographic evaluation of aluminum-lithium fuselage joints. The primary purpose is to certify that aircraft structures, avionics, and propulsion systems meet operational safety thresholds before entry into service and throughout their lifecycle. Inspection services command the largest revenue pool within service type segments due to mandatory recurring airframe checks, while non-destructive testing leads technology adoption as composite-intensive aircraft designs require defect detection without material damage. Maintenance, repair, and overhaul applications are expanding fastest as aging fleets in North America and Europe drive teardown and recertification volumes.
Regulatory Frame
FAA airworthiness directives, EASA Part 145 maintenance organization approvals, and ISO 17025 laboratory accreditation standards collectively shape market access and service pricing across jurisdictions. Regulatory bodies mandate specific NDT methods and inspector qualification levels, creating compliance-driven demand that insulates certified providers from commodity competition. Stakeholders must monitor evolving sustainability-linked certification requirements and digital audit trail mandates as regulators integrate environmental performance into airworthiness frameworks.
Market Dynamics
The transition to composite-intensive airframes and the resulting recertification burden for legacy aluminum fleets is compressing inspection intervals while fragmenting technician capacity across manufacturing clusters. This structural pressure is redrawing competitive boundaries between established aviation hubs and emerging production zones.
Growth Catalysts
- FAA Airworthiness Directives:Mandatory structural inspection intervals for aging Boeing 737 and Airbus A320 fleets are expanding recurring revenue pools for certified NDT providers.
- Titanium fan disc manufacturing:Next-generation geared turbofan programs require ultrasonic phased-array validation at multiple production stages, embedding TIC services into OEM supply chains.
- China MRO hub expansion:COMAC C919 production ramp and domestic fleet growth are concentrating demand for EASA-aligned certification capacity in Shanghai and Tianjin.
Market Restraints
- Helium supply volatility:Radiographic testing and leak detection methods depend on constrained helium reserves, creating input cost instability for penetrant and radiographic inspection providers.
- NDT technician scarcity:ASNT Level III certification pathways require multi-year apprenticeship commitments, limiting workforce elasticity in the United States and Germany.
- EASA Part 145 approval timelines:Maintenance organization certification processes extending 12-18 months create regulatory friction for new market entrants.
Strategic Opportunities
- Urban air mobility certification:eVTOL airframe and battery system validation protocols remain undefined, creating first-mover advantage for TIC providers developing specialized composite inspection methodologies.
- Digital audit trail mandates:FAA and EASA integration of blockchain-based maintenance records creates service expansion potential for cybersecurity-accredited laboratories.
- India defense aerospace:Indigenization requirements under the Defense Acquisition Procedure are localizing TIC demand for fighter airframe and engine programs.
Industry Challenges
- ASNT Level III certification pipelines:The 4-7 year qualification timeline for advanced ultrasonic and eddy current inspection methods is constraining workforce deployment flexibility.
- Legacy analog equipment integration:Phased-array ultrasonic systems must interface with decades-old airframe maintenance databases, creating data format incompatibility costs.
- Multi-jurisdiction accreditation stacking:Providers serving Boeing, Airbus, and COMAC simultaneously must maintain parallel ISO 17025, NADCAP, and CAAC laboratory certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace TIC Market |
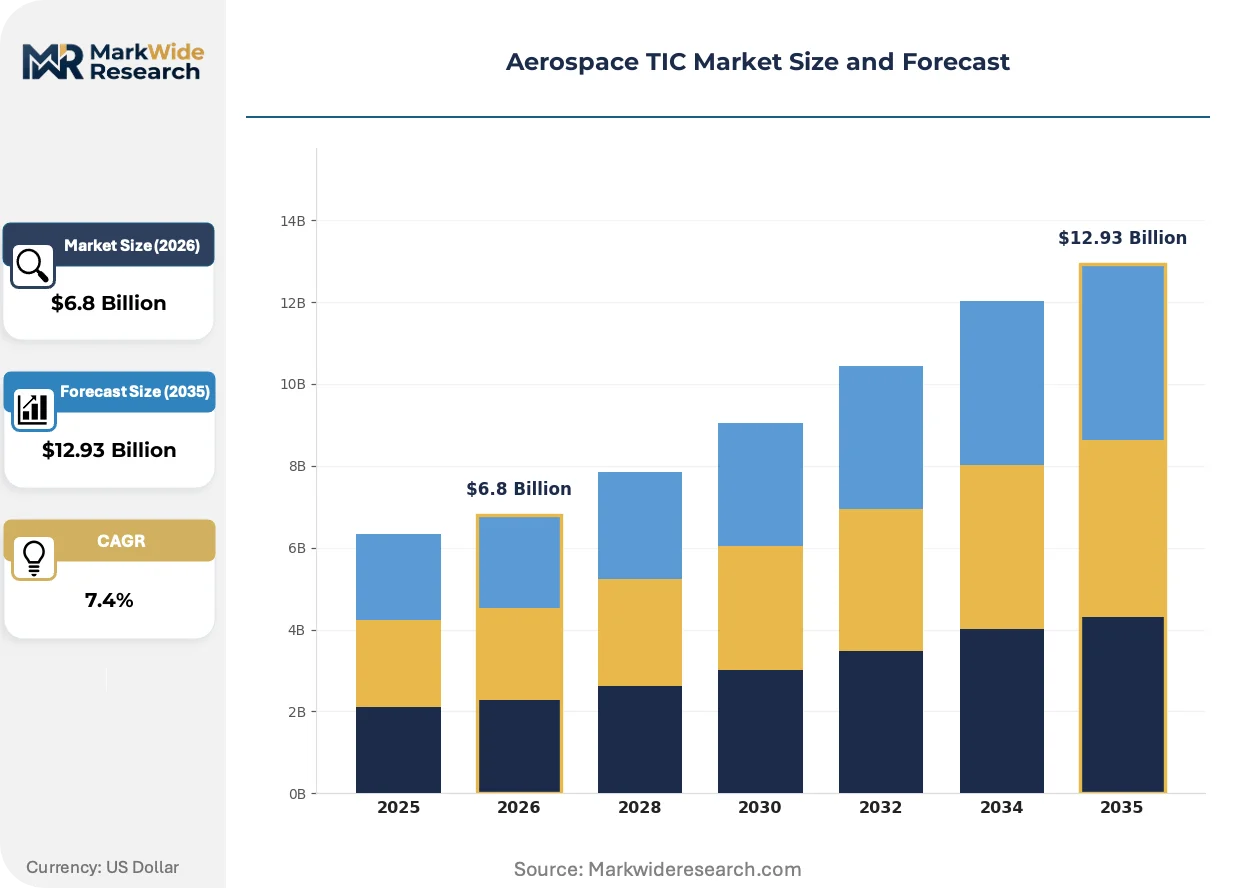
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Testing, Certification, Consultancy Technology: Non-Destructive Testing, Material Testing, Electromagnetic Testing, Radiographic Testing Application: Aerospace Manufacturing, Maintenance, Repair, Overhaul End User: Airlines, OEMs, Maintenance Providers, Regulatory Bodies |
| Companies Covered | TUV SUD, Applus+, Intertek Group plc, MISTRAS Group, DNV GL, Bureau Veritas, TUV Rheinland, Element Materials Technology, SGS SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace TIC Market Emerging Trajectories
Digital inspection methodologies and automated defect recognition are compressing cycle times while raising the technical threshold for market participation. These shifts are favoring laboratories with integrated data infrastructure over equipment-centric service models.
Phased-array ultrasonic testing is bifurcating the NDT service landscape. Major MRO facilities in the United States and Germany are deploying automated scanning systems for composite delamination detection. This technology is bifurcating market share between capital-intensive laboratories capable of real-time 3D imaging and smaller providers restricted to manual pulse-echo methods.
EASA's evolving Part 145 requirements for composite damage tolerance assessment are mandating thermographic inspection protocols for specific airframe zones. Airlines operating Airbus A350 and Boeing 787 fleets must now document thermal signature baselines during heavy maintenance checks. European MROs are responding by retrofitting existing hangars with active thermography suites.
Airline procurement departments are unbundling inspection services from traditional airframe maintenance contracts. Carriers including Lufthansa and Delta are issuing standalone TIC RFPs for specific aircraft programs, enabling direct relationships with specialized NDT laboratories. This pattern is most visible in North America and Western Europe where fleet complexity justifies supplier diversification.
Aerospace TIC Market Segmentation
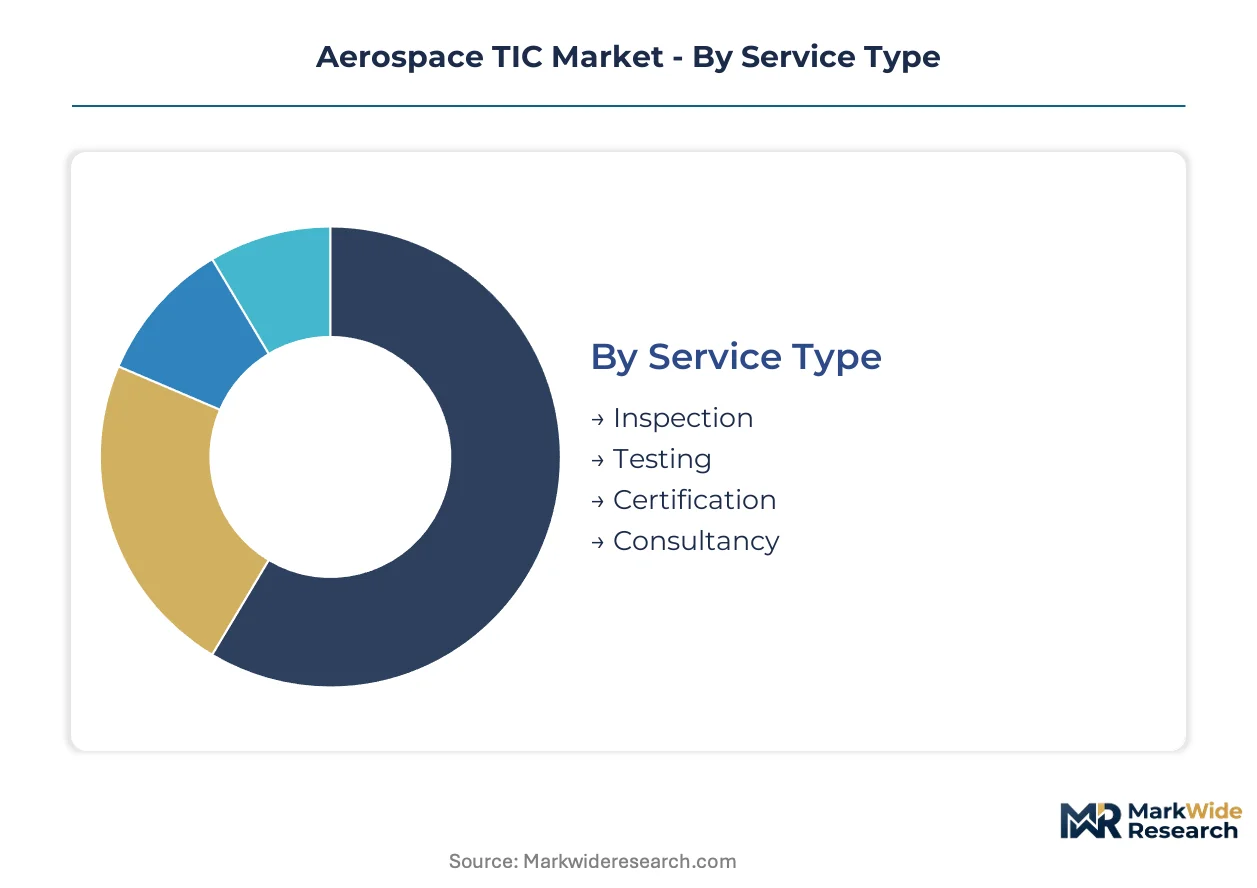
Segmentation in Aerospace TIC reveals how regulatory mandates and airframe material transitions concentrate revenue across distinct service modalities. Each category maps to specific compliance pathways that determine provider capabilities and customer procurement patterns.
Service Type:
Inspection services face the strongest substitution pressure from automated in-house OEM quality systems, while certification maintains structural insulation through regulatory monopoly.
- Inspection:Recurring airframe checks mandated by FAA airworthiness directives and EASA Part 145 requirements generate the largest revenue pool. Airlines operating aging Boeing 737 and Airbus A320 fleets in the United States and Germany drive volume through compressed inspection intervals.
- Testing:Destructive and non-destructive validation of titanium fan discs and composite laminates embeds TIC providers into OEM supply chains. Geared turbofan programs concentrate demand for ultrasonic phased-array validation at multiple production stages.
- Certification:ISO 17025 and NADCAP laboratory accreditation creates regulatory barriers that protect incumbent providers. EASA and FAA mandates on structural airworthiness ensure sustained demand for third-party certification services.
- Consultancy:Advisory services on multi-jurisdiction compliance stacking support providers serving Boeing, Airbus, and COMAC simultaneously. Technical guidance on ASNT Level III certification pathways addresses workforce scarcity constraints.
Inspection anchors the volume base while testing gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive automated systems from manual methods, with premium pricing attached to real-time 3D imaging capabilities.
- Non-Destructive Testing:Phased-array ultrasonic and eddy current methods dominate composite airframe validation. Major MRO facilities in the United States and Germany deploy automated scanning systems for delamination detection in Boeing 787 and Airbus A350 structures.
- Material Testing:Mechanical property validation of aluminum-lithium alloys and carbon fiber reinforced polymers supports next-generation airframe programs. OEM manufacturing clusters in China and Germany concentrate demand for tensile and fatigue testing.
- Electromagnetic Testing:Eddy current inspection of fastener holes and surface cracks in aging aluminum fleets sustains recurring revenue. ASNT Level III certification requirements constrain workforce availability in established aviation hubs.
- Radiographic Testing:Helium-dependent leak detection and X-ray evaluation face input cost volatility from constrained gas reserves. Radiographic protocols remain mandatory for critical titanium and nickel superalloy castings.
Non-destructive testing commands the premium tier while material testing expands most quickly.
Application:
Customer type differentiation separates OEM-integrated programs from aftermarket services, with procurement unbundling enabling direct airline-laboratory relationships.
- Aerospace Manufacturing:First-article inspection and production process validation embed TIC services into OEM supply chains. COMAC C919 production ramp in Shanghai concentrates demand for EASA-aligned certification capacity.
- Maintenance:Line maintenance checks and A-check intervals generate recurring revenue through contracted service agreements. Lufthansa and Delta unbundling of inspection services from traditional airframe contracts creates standalone TIC procurement opportunities.
- Repair:Damage tolerance assessment and structural repair documentation requires specialized composite inspection methodologies. EASA evolving requirements for thermographic inspection protocols mandate thermal signature baselines during heavy checks.
- Overhaul:Aging fleet teardown and recertification volumes in North America and Europe drive the fastest application expansion. D-check intervals for legacy Boeing 737 and Airbus A320 fleets compress turnaround requirements.
Maintenance anchors the volume base while overhaul climbs the fastest.
End User:
Margin concentration follows regulatory proximity, with direct OEM and airline relationships commanding premium pricing over intermediary maintenance providers.
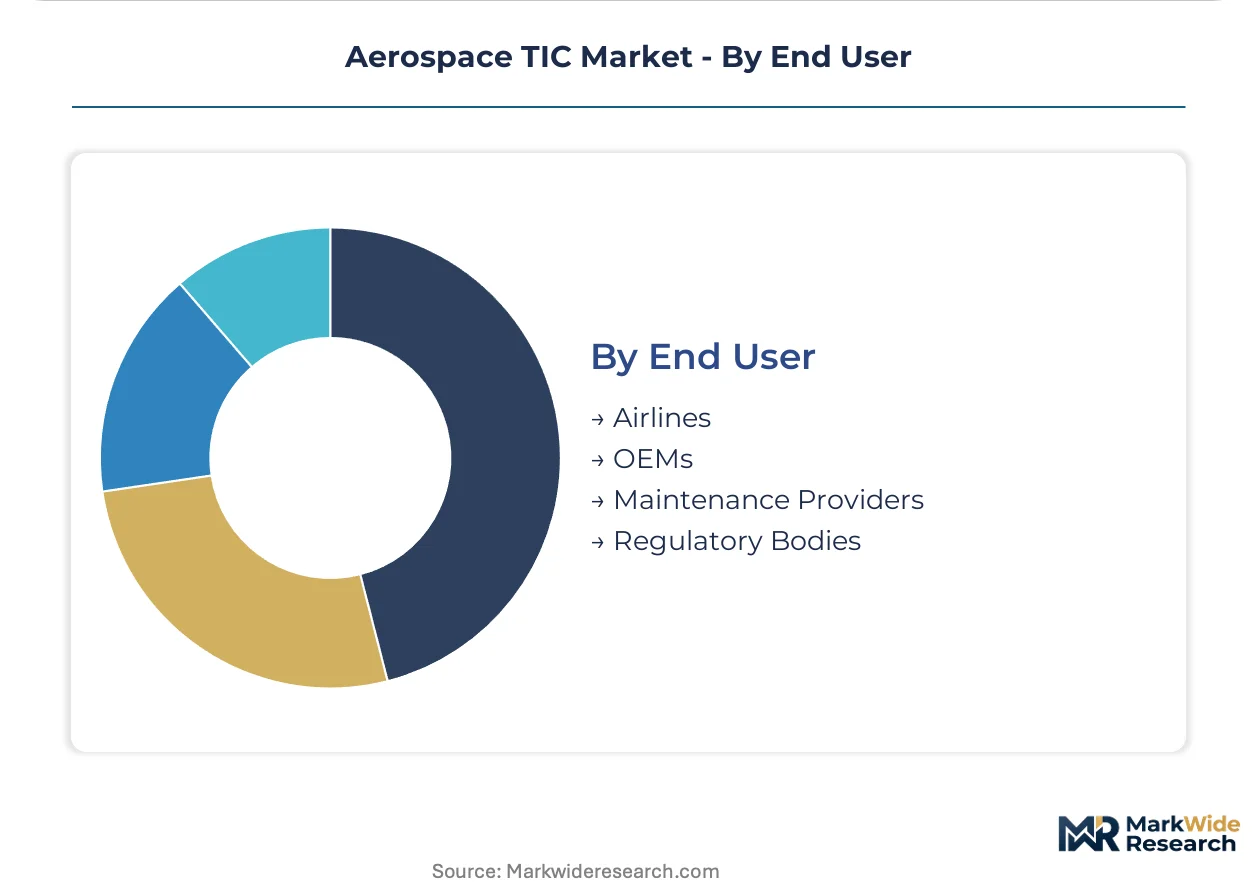
- Airlines:Procurement departments issue standalone TIC RFPs for specific aircraft programs, enabling direct relationships with specialized NDT laboratories. Fleet complexity in North America and Western Europe justifies supplier diversification strategies.
- OEMs:Boeing, Airbus, and COMAC integrate TIC validation into production milestones for next-generation composite airframes. Ultrasonic phased-array requirements for geared turbofan programs embed certification into manufacturing workflows.
- Maintenance Providers:EASA Part 145 and FAA-certified repair stations represent intermediary demand with compressed margin structures. Approval timelines extending 12-18 months create regulatory friction for facility expansion.
- Regulatory Bodies:FAA, EASA, and CAAC accreditation requirements shape market access and service pricing across jurisdictions. Digital audit trail mandates and blockchain-based maintenance records create service expansion potential for cybersecurity-accredited laboratories.
Airlines anchor the volume base while regulatory bodies gain influence at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premiums over 40% above Chinese market rates, reflecting EASA accreditation density and ASNT Level III technician scarcity. This asymmetry redistributes contract flows toward regulatory-proximate jurisdictions.
United States
FAA airworthiness directives on aging Boeing 737 fleets compress inspection intervals, expanding recurring revenue for certified NDT providers. The FAA mandates ultrasonic phased-array validation for critical titanium components. Seattle-Tacoma and Wichita manufacturing clusters concentrate demand for production-embedded TIC services.
Germany
EASA Part 145 maintenance approvals and composite damage tolerance assessments drive premium pricing for thermographic inspection capabilities. The EASA evolving requirements for Airbus A350 fleets mandate thermal signature documentation. Hamburg and Munich MRO hubs anchor European certification capacity for geared turbofan programs.
China
COMAC C919 production ramp and domestic fleet expansion concentrate demand for EASA-aligned certification capacity. CAAC laboratory accreditation requirements shape market access for foreign TIC providers. Shanghai and Tianjin aerospace clusters integrate validation services into OEM supply chains for next-generation airframes.
France
Airbus manufacturing milestones and supplier quality mandates embed TIC providers into A350 and A320 production workflows. EASA composite inspection protocols for damage tolerance assessment create specialized service requirements. Toulouse and Nantes aerospace corridors sustain certification demand through OEM-integrated testing programs.
United Kingdom
Rolls-Royce geared turbofan supply chain requirements drive ultrasonic validation demand at multiple production stages. The UK Civil Aviation Authority alignment with EASA standards maintains regulatory continuity for post-Brexit certification services. Bristol and Derby manufacturing zones concentrate propulsion system testing capacity.
Aerospace TIC Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium accreditation density separates pricing power from volume scale. The vendor base clusters around three strategic positions: global laboratory networks with multi-jurisdiction ISO 17025 coverage, specialized aerospace testing boutiques with NADCAP depth, and regional maintenance-integrated providers serving single regulatory domains. Dominant competitive moves include geographic accreditation stacking to serve Boeing-Airbus-COMAC simultaneously, and automated inspection system deployment to compress cycle times against manual-method competitors.
Among European-origin diversified testing groups, Bureau Veritas and SGS SA exemplify the global-network archetype with multi-continent laboratory footprints. Element Materials Technology occupies a position within the specialized aerospace tier, anchoring NADCAP-intensive validation services for OEM supply chains. These three represent distinct competitive positions: accreditation breadth, technical depth, and manufacturing-proximate scale respectively.
| Leading Market Players |
|---|
| TUV SUD |
| Applus+ |
| Intertek Group plc |
| MISTRAS Group |
| DNV GL |
| Bureau Veritas |
| TUV Rheinland |
| Element Materials Technology |
| SGS SA |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month EASA Part 145 approval timelines concentrate pricing power among incumbent laboratories with stacked multi-jurisdiction accreditations, compressing margins for new entrants while rewarding established providers with regulatory-proximate capacity. This lead-time asymmetry shapes how airlines and OEMs source TIC services across manufacturing clusters.
Pricing Analysis
Configured-to-order pricing for ASNT Level III technician deployment commands premiums exceeding standard inspection rates by substantial margins, reflecting scarcity-driven cost structures. Pricing stratifies across NADCAP-accredited laboratories, ISO 17025-certified facilities, and non-accredited regional providers based on audit trail capabilities and inspector qualification density. Cost compression in manual pulse-echo inspection tiers is intensifying because automated phased-array systems displace labor-intensive methods at major MRO facilities. Airlines operating aging Boeing 737 fleets exhibit highest price sensitivity due to compressed D-check intervals, while OEMs integrating TIC into geared turbofan production milestones show lowest sensitivity.
Supply Chain Analysis
Just-in-time helium sourcing for radiographic testing and leak detection methods has shifted toward strategic stockpiling among major laboratories, reflecting supply volatility from constrained gas reserves. Geographic supply concentration centers on the United States, Germany, and China, where FAA, EASA, and CAAC accreditation requirements anchor certification capacity. Raw material and component dependencies include phased-array ultrasonic equipment, thermographic inspection suites, and ASNT-certified technician pipelines. Single-source vulnerability in helium supply chains creates structural risk for penetrant and radiographic inspection providers. Distribution runs through OEM-embedded production validation contracts and standalone airline RFPs for heavy maintenance programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EASA and FAA accreditation requirements create switching costs that lock airlines and OEMs into established provider relationships.
For Market Incumbents: Compound defensive positioning by deepening NADCAP laboratory density in Shanghai and Tianjin to capture COMAC C919 production ramp demand, while deploying automated thermographic inspection suites to compress cycle times against manual-method competitors facing ASNT Level III technician scarcity. For New Entrants and Emerging Players: Anchor in urban air mobility certification white space where eVTOL airframe and battery system validation protocols remain undefined, targeting first-mover advantage through specialized composite inspection methodologies for emerging electric aircraft programs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial testing conglomerates with underperforming aerospace divisions lacking NADCAP depth, presenting acquisition opportunities for platforms seeking technical specialization. Long-term viability hinges on regulatory accreditation density rather than equipment scale. Signal to monitor: FAA and EASA integration timelines for blockchain-based maintenance record mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Accreditation Stacking | Parallel ISO 17025, NADCAP, and CAAC certifications enable simultaneous Boeing-Airbus-COMAC service provision. |
| Automated Phased-Array System Deployment | Real-time 3D imaging capabilities displace manual pulse-echo methods at major United States and German MRO facilities. |
| Urban Air Mobility Certification Development | Specialized composite inspection protocols for eVTOL structures capture undefined regulatory white space. |
| Blockchain Audit Trail Capability Investment | Cybersecurity-accredited laboratories position for FAA and EASA digital maintenance record mandates. |
| ASNT Level III Technician Pipeline Development | Multi-year apprenticeship programs address workforce scarcity constraining ultrasonic and eddy current inspection capacity. |
Methodological Framework
Initial hypotheses were tested against primary input from NDT laboratory directors, airline procurement executives, MRO maintenance planners, and OEM quality assurance managers and refined through secondary validation against FAA airworthiness directive databases, EASA Part 145 approval registries, NADCAP audit reports, and ISO 17025 accreditation listings. Bottom-up technician capacity modeling and top-down aerospace manufacturing output projections were triangulated to anchor demand estimates.
Variance decomposition across service type, technology modality, application segment, and end-user category shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling against fleet age distributions and regulatory inspection interval mandates. Forecast inputs included COMAC C919 production ramp schedules, geared turbofan program milestones, and EASA evolving thermographic inspection protocol requirements.
Material uncertainties — helium supply disruptions, ASNT certification pipeline bottlenecks, and eVTOL regulatory timeline shifts — sit outside the modeled envelope. Forecasts reflect assumptions on accreditation approval velocities and composite airframe penetration rates. Revision becomes warranted when FAA or EASA inspection interval mandates cross threshold changes exceeding current directive trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market