
 AI in Modern Warfare Market | 2026-2036
AI in Modern Warfare Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Modern Warfare Market Outlook
Modular AI payload architectures is rebalancing procurement decisions across defense ministries, allowing commanders to swap perception algorithms between drone platforms without vendor lock-in. Lockheed Martin leverages its classified facility network to sustain sovereign code development for sensitive targeting pipelines. Anduril Industries differentiates through vertical software-hardware integration, controlling sensor-to-shooter latency in contested electromagnetic environments.
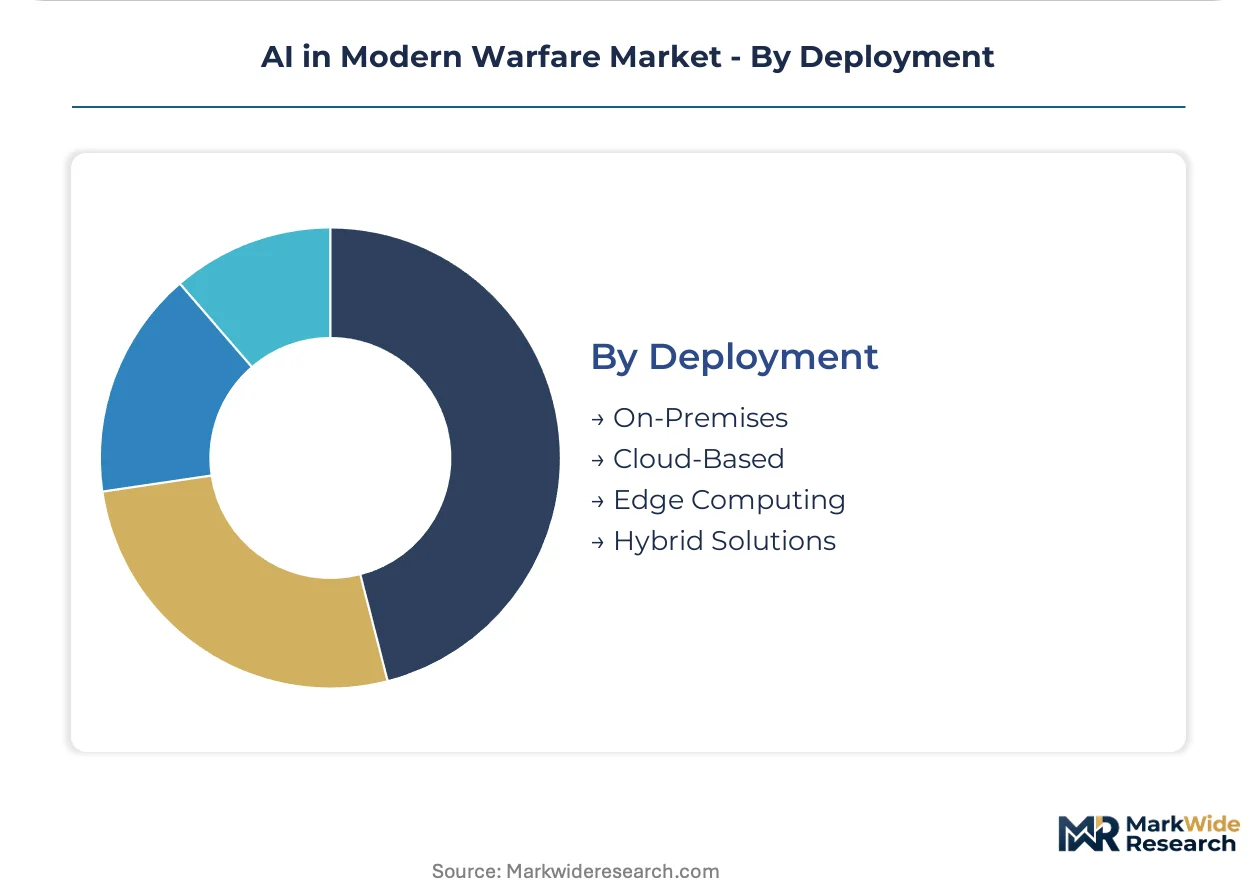
AI in modern warfare encompasses machine perception, predictive analytics, and autonomous decision systems operating at sub-second speeds in denied communications environments, typically hardened against jamming through edge-computing nodes with on-board inference accelerators. Its primary purpose is to compress the observe-orient-decide-act loop below adversary reaction times. Machine Learning and Computer Vision segments lead current procurement volumes, with Data Analytics representing the fastest-expanding margin pool as commanders demand post-mission forensic capabilities. Deployment through Edge Computing architectures dominates operational budgets, while Cloud-Based backbones support training and model refinement cycles.
The US Department of Defense governs algorithmic weapon systems through its Responsible AI guidelines, while the EU AI Act imposes strict human oversight requirements on exportable military AI components, directly constraining product roadmaps for transatlantic suppliers. NATO's standardization agreements on interoperable data fabrics further shape procurement specifications for coalition-compatible systems. Stakeholders must monitor whether emerging national sovereignty mandates fragment model training datasets and degrade cross-border system interoperability.
Market Dynamics
The Pentagon's rapid software acquisition pathways are compressing vendor selection cycles from years to months, forcing defense contractors to restructure development pipelines around continuous integration rather than milestone-based delivery.
Growth Catalysts
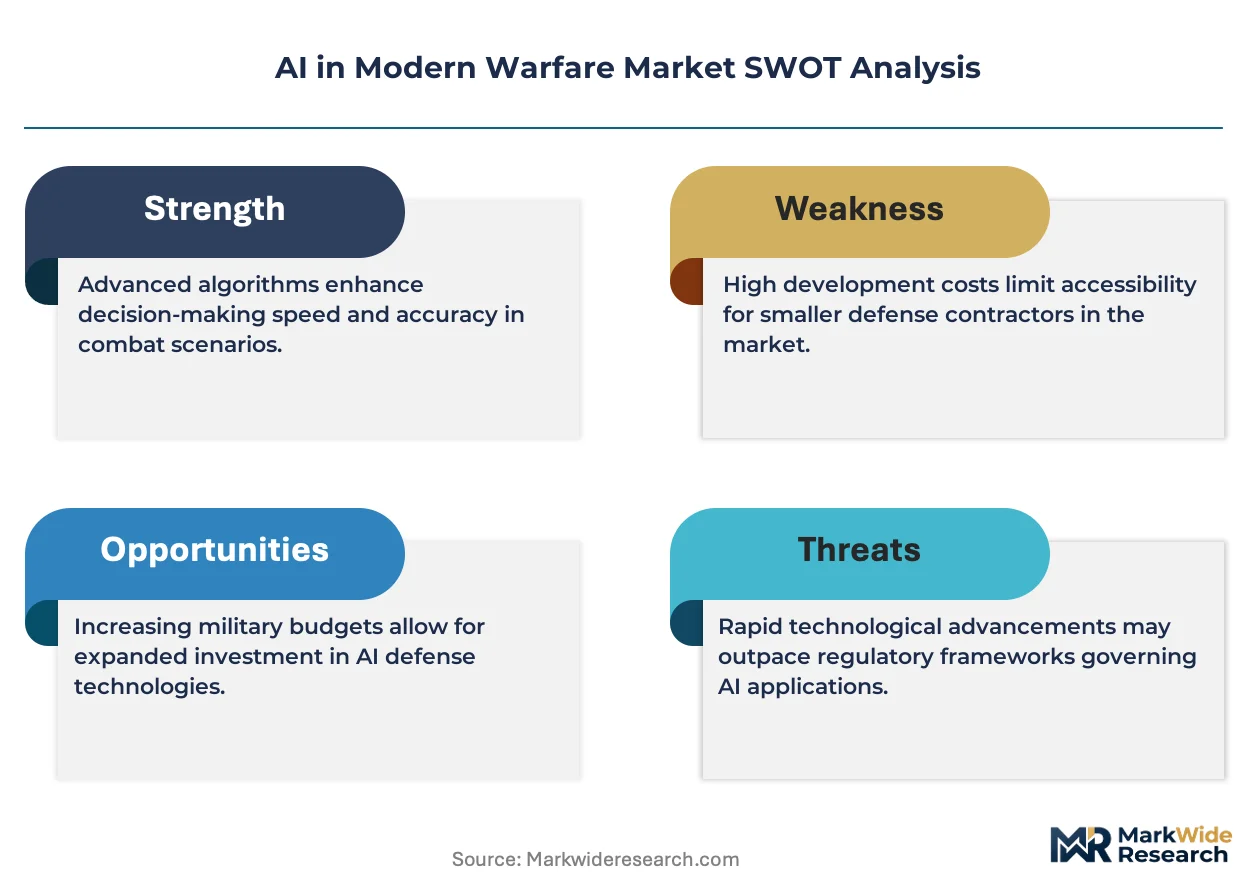
- Export Control Frameworks:Tightened dual-use AI technology restrictions across NATO member states are accelerating sovereign procurement of autonomous targeting systems, creating captive demand for domestic suppliers.
- Edge Computing Architectures:Hardened on-board inference accelerators are enabling sub-second decision loops in denied communications environments, driving procurement of modular payload systems.
- Coalition Interoperability Mandates:NATO standardization agreements on data fabrics are forcing procurement specifications toward compatible systems, consolidating vendor selection around proven integrators.
Market Restraints
- Specialized Semiconductor Supply:Inference accelerator chips face concentration risk in East Asian foundries, exposing defense programs to single-source vulnerabilities.
- Human Oversight Requirements:The EU AI Act imposes strict human-in-the-loop mandates on exportable military components, constraining product roadmaps for transatlantic suppliers.
- Dataset Sovereignty Fragmentation:Emerging national mandates are Balkanizing training data pools, degrading cross-border model interoperability for coalition operations.
Strategic Opportunities
- Post-Mission Forensics:Data Analytics capabilities represent underexploited margin pools as commanders demand algorithmic audit trails for targeting decisions.
- Swappable Perception Algorithms:Modular payload architectures allow commanders to transfer computer vision models between drone platforms without vendor lock-in, opening aftermarket service revenue.
- Responsible AI Certification:US Department of Defense guidelines on algorithmic weapon systems create first-mover advantages for suppliers with established ethical review pipelines.
Industry Challenges
- Specialized Talent Scarcity:Machine learning engineers with security clearances and combat systems experience command premium compensation, constraining program scaling.
- Legacy System Integration:Fielded platforms with decades-old data bus architectures require expensive middleware development to host modern inference engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Modern Warfare Market |
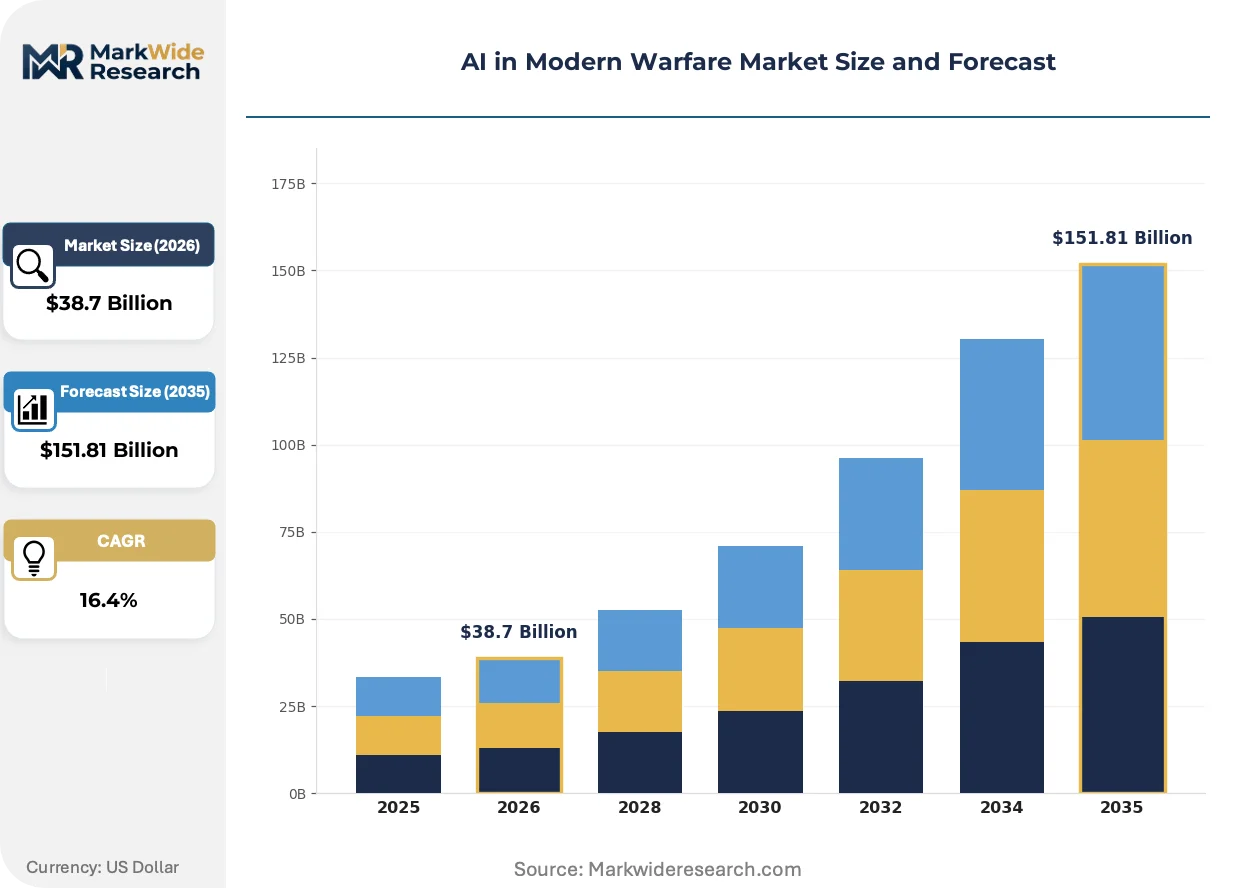
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Neural Networks, Computer Vision, Data Analytics Application: Surveillance, Target Recognition, Autonomous Systems, Cyber Defense End User: Defense Contractors, Military Organizations, Government Agencies, Research Institutions Deployment: On-Premises, Cloud-Based, Edge Computing, Hybrid Solutions |
| Companies Covered | Raytheon Technologies, BAE Systems, Palantir Technologies, Kratos Defense & Security Solutions, General Dynamics, Lockheed Martin, AeroVironment, Anduril Industries, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Modern Warfare Market Strategic Shifts
Algorithmic warfare is shifting from centralized cloud training to distributed edge inference, with procurement patterns increasingly favoring software-defined payloads over hardware-locked systems.
Neuromorphic computing architectures are unifying sensor fusion and target recognition into single-chip designs. The US Air Force Research Laboratory is accelerating testing of these brain-inspired processors for unmanned wingman programs. This convergence is unifying previously separate perception and decision layers, collapsing latency budgets in contested electromagnetic environments.
The EU AI Act's human oversight requirements are reshaping export licensing for military AI components. European defense ministries must now document algorithmic decision chains for any system leaving the bloc. Transatlantic suppliers with dual US-EU footprints are responding by bifurcating product lines into sovereign-code and exportable variants.
Defense procurement officers are compressing vendor evaluation cycles from multi-year source selections to iterative software drops. The Pentagon's rapid acquisition pathways now prioritize demonstrated inference performance over exhaustive requirements documents. This behavioral shift is most pronounced in special operations commands, where classified field trials increasingly precede formal program-of-record commitments.
AI in Modern Warfare Market Segmentation
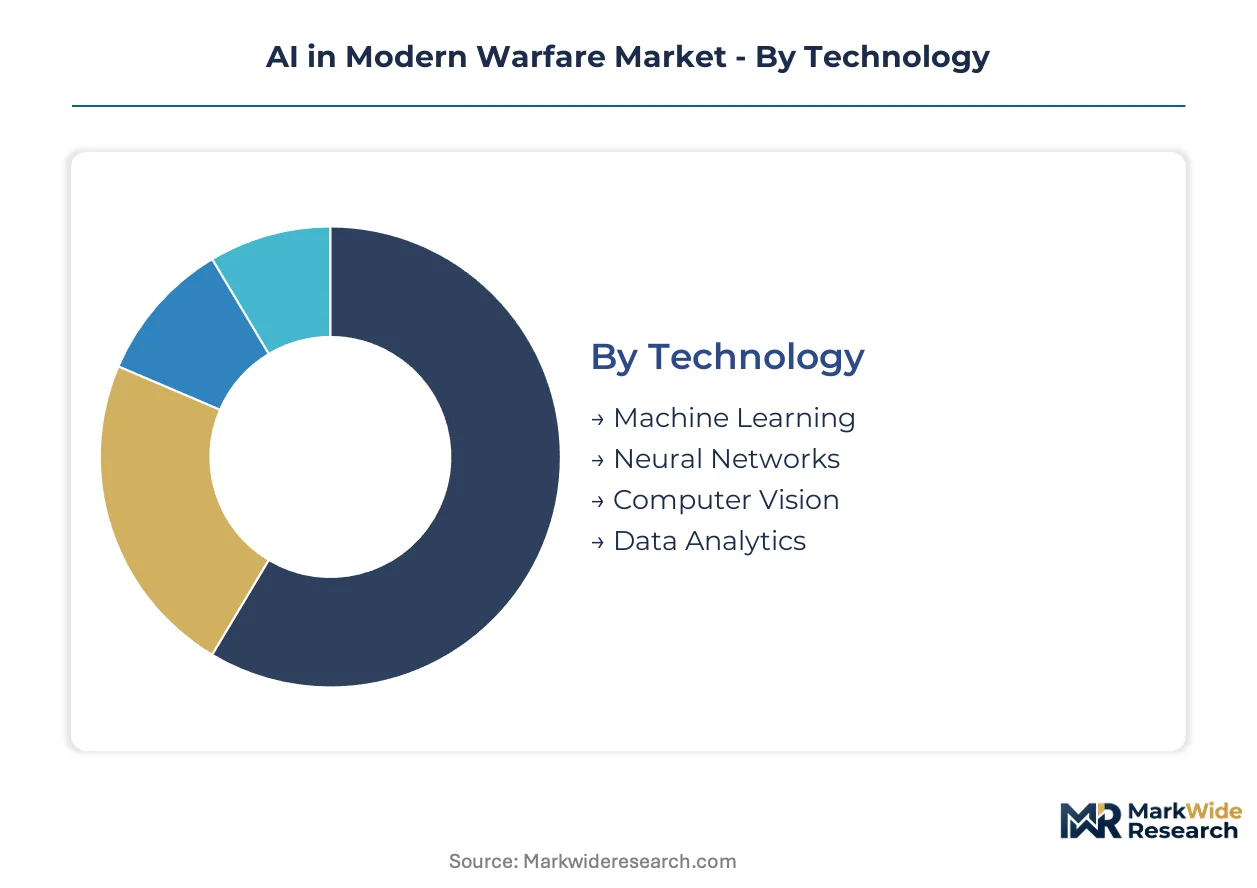
Segmentation in military AI procurement reveals how procurement officers balance legacy system constraints against emerging operational requirements. Each dimension reflects distinct budget cycles, security classification levels, and coalition interoperability mandates that reshape vendor selection criteria.
Technology:
Upgrade cycles in military AI concentrate where inference performance gaps threaten operational overmatch against peer adversaries.
- Machine Learning:Pattern recognition algorithms trained on classified operational datasets enable predictive maintenance for armored vehicle fleets and ammunition consumption forecasting. Demand clusters in United States Army Futures Command programs modernizing brigade-level decision support, constrained by the scarcity of cleared personnel capable of validating model outputs against ground truth.
- Computer Vision:Real-time object detection pipelines process electro-optical and synthetic aperture radar feeds for target identification at standoff distances. Procurement accelerates in NATO member states following standardization agreements on interoperable data formats, though EU AI Act human oversight requirements complicate transatlantic code sharing.
- Neural Networks:Deep learning architectures power natural language processing for signals intelligence triage.
- Data Analytics:Post-mission forensic capabilities aggregate sensor feeds for algorithmic audit trails and operational debriefs.
Machine Learning sits at the top of the volume ranking, with Data Analytics climbing the fastest.
Application:
Cost tier differentiation separates sovereign-code development from exportable variants subject to foreign disclosure restrictions.
- Target Recognition:Multi-sensor fusion algorithms correlate electro-optical, infrared, and radar returns to generate firing solutions within sub-second latency budgets. United States Special Operations Command compresses vendor selection cycles through rapid software acquisition pathways, prioritizing demonstrated kill-chain performance over exhaustive requirements documentation.
- Autonomous Systems:Swarming coordination protocols enable unmanned platforms to execute missions in GPS-denied environments with minimal human intervention. Procurement concentrates in United States Navy unmanned surface vessel programs and United Kingdom Royal Navy mine countermeasures, constrained by specialized semiconductor supply concentration in East Asian foundries.
- Surveillance:Persistent wide-area motion imagery analysis monitors border regions and forward operating bases.
- Cyber Defense:Anomaly detection models identify adversarial intrusions into tactical data networks.
Target Recognition captures the largest procurement allocation, with Autonomous Systems expanding most quickly.
End User:
Customer type determines security clearance requirements and foreign disclosure thresholds that gate software delivery models.
- Military Organizations:Combatant commands operate classified inference pipelines on hardened edge nodes disconnected from commercial cloud infrastructure. United States Indo-Pacific Command drives demand for contested electromagnetic environment resilience, while United States European Command prioritizes coalition interoperability with NATO allies.
- Defense Contractors:Prime integrators embed AI subsystems into weapon platforms subject to milestone-based acquisition regulations. Lockheed Martin and Anduril Industries compete through contrasting approaches—sovereign code development versus vertical software-hardware integration—to satisfy Pentagon rapid acquisition timelines.
- Government Agencies:Intelligence community elements consume finished algorithmic products for strategic analysis.
- Research Institutions:Federally funded laboratories advance neuromorphic computing and brain-inspired processor architectures.
Military Organizations dominate operational deployment volumes, with Defense Contractors gaining share fastest through compressed vendor selection cycles.
Deployment:
Supply concentration in specialized inference accelerators shapes architecture decisions between sovereign fabrication and foreign sourcing risk acceptance.
- Edge Computing:On-board inference accelerators execute target recognition and navigation algorithms in denied communications environments without cloud dependency. United States Air Force Research Laboratory tests neuromorphic processors for unmanned wingman programs, collapsing sensor-to-shooter latency in contested electromagnetic spectrum.
- Cloud-Based:Centralized training infrastructure refines models on aggregated datasets before edge deployment. United States National Security Agency and United Kingdom Government Communications Headquarters operate classified facilities for model development, constrained by emerging national dataset sovereignty mandates fragmenting cross-border training pools.
- On-Premises:Air-gapped installations host sensitive targeting pipelines in cleared facilities.
- Hybrid Solutions:Tiered architectures train in cloud environments and infer at the tactical edge.
Edge Computing leads operational budget allocation, with Hybrid Solutions showing the steepest expansion trajectory as commanders demand training-to-inference flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern military AI procurement traces its institutional lineage to Pentagon research initiatives of the 1980s, when DARPA-funded autonomous vehicle competitions seeded the algorithmic targeting pipelines now fielded across NATO forces. This foundational investment created procurement pathways that contemporary defense ministries now replicate with sovereign adaptations.
United States
United States Special Operations Command compresses vendor selection cycles through rapid software acquisition pathways, prioritizing demonstrated kill-chain performance over exhaustive requirements documentation. The Department of Defense's Responsible AI guidelines govern algorithmic weapon systems through mandatory ethical review pipelines. Lockheed Martin and Anduril Industries anchor the defense industrial base in California and Virginia, competing through contrasting sovereign-code and vertical-integration approaches.
United Kingdom
United Kingdom Royal Navy mine countermeasures programs drive procurement of autonomous surface vessels with swarming coordination protocols for GPS-denied environments. The UK Government Communications Headquarters operates classified facilities for model development, constrained by emerging dataset sovereignty mandates fragmenting cross-border training pools. London and Bristol host prime integrator clusters embedding AI subsystems into coalition-compatible weapon platforms.
Germany
Bundeswehr modernization programs concentrate procurement on interoperable data fabrics compliant with NATO standardization agreements. The EU AI Act imposes strict human-in-the-loop mandates on exportable military components, forcing bifurcated product lines for transatlantic suppliers. Munich and Stuttgart industrial clusters specialize in middleware development bridging legacy platform architectures with modern inference engines.
Israel
Israel Defense Forces field hardened edge-computing nodes with on-board inference accelerators optimized for contested electromagnetic environments. National security doctrine emphasizes sovereign code development for sensitive targeting pipelines without foreign disclosure dependencies. Tel Aviv and Haifa metropolitan areas concentrate specialized machine learning engineering talent with combat systems experience commanding premium compensation.
Australia
Australian Defence Force Indo-Pacific posture drives demand for persistent wide-area motion imagery analysis monitoring forward operating bases and maritime approaches. The country's national security regulator coordinates with Five Eyes partners on algorithmic audit trail standards for coalition operations. Canberra and Adelaide host research institutions advancing neuromorphic computing architectures for unmanned wingman programs.
AI in Modern Warfare Market Competitive Environment
Premium-margin players sit above commodity-margin players across the security-cleared development tier, where machine learning engineers with combat systems experience command compensation multiples exceeding commercial technology markets. The vendor base concentrates around three strategic archetypes: prime integrators with classified facility networks, vertical software-hardware specialists controlling sensor-to-shooter latency, and emerging challengers exploiting rapid acquisition pathways. Consolidation pressure operates through strategic partnerships bridging legacy platform integration gaps and technology licensing arrangements accelerating sovereign-code development.
Within the prime integrator tier, Lockheed Martin and Northrop Grumman exemplify established positions sustained through classified facility networks and milestone-based acquisition relationships. Anduril Industries occupies a distinct position as a vertical integration specialist, representing the challenger archetype that rapid software acquisition pathways have enabled. These three entities anchor competitive dynamics as defense procurement officers compress evaluation cycles from multi-year source selections toward iterative software drops.
| Leading Market Players |
|---|
| Raytheon Technologies |
| BAE Systems |
| Palantir Technologies |
| Kratos Defense & Security Solutions |
| General Dynamics |
| Lockheed Martin |
| AeroVironment |
| Anduril Industries |
| Northrop Grumman |
| Others |
Value Chain & Pricing Dynamics
The EU AI Act's human oversight mandates gate both qualified supply and premium-tier pricing access for military AI components, bifurcating product lines into sovereign-code and exportable variants while compressing margins on transatlantic deliveries.
Pricing Analysis
Three-tier pricing structure across sovereign-code, coalition-compatible, and commercial-off-the-shelf levels dominates procurement, with security clearance requirements and NATO interoperability certification as the primary price differentiation drivers. Cost compression in the exportable tier is intensifying because EU AI Act compliance adds documentation overhead without operational performance gains. Defense contractors with classified facility networks face the least price sensitivity, while emerging challengers competing on rapid acquisition timelines absorb the most margin pressure.
Supply Chain Analysis
ITAR and EU AI Act qualification requirements filter supplier participation, concentrating specialized inference accelerator fabrication in Taiwan, South Korea, and the United States. Supply chains draw from gallium nitride substrates, high-bandwidth memory modules, and radiation-hardened packaging materials. Single-source vulnerability in East Asian foundries exposes defense programs to export restriction risk. Distribution runs through prime integrator networks with cleared facility access, bypassing commercial technology channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI in Modern Warfare Market functions as a stable compounder, with sovereign defense procurement commitments insulating revenue streams from commercial technology cyclicality.
For Market Incumbents: Anticipate margin compression from rapid software acquisition pathways by accelerating sovereign-code development in cleared facilities and securing NATO standardization agreement compliance ahead of coalition procurement cycles. Lockheed Martin's classified facility network and Anduril Industries' vertical software-hardware integration represent divergent defensive templates for sustaining premium positioning against emerging challengers exploiting compressed vendor selection timelines. For New Entrants and Emerging Players: The Pentagon's rapid software acquisition pathways open a window for specialized inference acceleration and post-mission forensic analytics, where incumbent prime integrators maintain weaker positions. Target United States Special Operations Command and United Kingdom Royal Navy autonomous vessel programs as the most penetrable segments, deploying iterative software demonstrations ahead of formal program-of-record commitments to bypass milestone-based procurement barriers. For Investors and Strategic Acquirers: Roll-up economics work for vertical software-hardware specialists because sensor-to-shooter latency control creates defensible moats in contested electromagnetic environments. Focus acquisition screening on machine learning engineering teams with security clearances and combat systems experience, where talent scarcity sustains premium valuation multiples. Monitor Pentagon Responsible AI certification timelines as the critical inflection signal for first-mover advantage in algorithmic weapon system procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Code Development | Lockheed Martin's classified facilities satisfy ITAR restrictions without foreign disclosure dependencies. |
| Neuromorphic Processor Integration | United States Air Force Research Laboratory testing collapses sensor-to-shooter latency for unmanned wingman programs. |
| Post-Mission Forensics Platform | Data analytics capabilities address United States Department of Defense algorithmic audit trail requirements. |
| NATO Data Fabric Compliance | Interoperable standards enable coalition-compatible procurement across European defense ministries. |
| Responsible AI Certification | Ethical review pipelines create first-mover advantage in Pentagon rapid acquisition pathways. |
Study Parameters
Coverage spans the United States, United Kingdom, Germany, Israel, and Australia, with primary inputs from each defense procurement jurisdiction combining program executive interviews, prime integrator strategy sessions, and cleared facility engineering assessments. Secondary validation draws from Department of Defense budget justification materials, NATO standardization agreement documentation, EU AI Act regulatory filings, and defense industrial base SEC disclosures. Bottom-up procurement volume estimates triangulate against top-down defense budget allocation analysis.
Rate-of-change decomposition separates technology adoption velocity from procurement cycle compression effects across the modeling period. Segmentation dimensions include technology type, application function, end-user category, and deployment architecture, with additional modeling of security clearance tier and coalition interoperability requirements. CAGRs derive from fitted growth curves benchmarked against historical defense procurement patterns and peer adversary capability investment trajectories, incorporating specialized semiconductor supply constraints and sovereign dataset fragmentation risks.
Revisions become necessary when export control frameworks tighten, foundry supply concentration shifts, or national dataset sovereignty mandates proliferate beyond current NATO coordination mechanisms. A model refresh is warranted upon material change in Pentagon rapid acquisition pathway scope or EU AI Act enforcement interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
AI in Defense Market