
 Artificial Intelligence and Robotics in Aerospace and Defense Market | 2026-2036
Artificial Intelligence and Robotics in Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence and Robotics in Aerospace and Defense Market Analysis
Unmanned combat aerial systems is consolidating as the fastest-expanding end-use vertical within defense procurement. Lockheed Martin leverages decades of classified program experience to anchor high-value autonomous flight contracts. Anduril competes aggressively on AI-native defense platforms, while Boston Dynamics specializes in legged robotics for tactical ground operations.
Artificial intelligence and robotics in aerospace and defense encompasses autonomous hardware platforms, machine-learned decision systems, and sensor-fusion software operating at latency thresholds below 50 milliseconds for real-time threat response. These technologies enable predictive maintenance, swarm coordination, and precision targeting across contested environments. Combat Operations applications dominate current procurement volumes, while Autonomy Software captures expanding margin pools as militaries prioritize algorithmic superiority over hardware scale. Sensor Technology leads capital deployment in undersea and satellite domains where perception gaps persist.
The US Department of Defense, the EU AI Act framework, and China's MIIT standards collectively govern cross-border technology transfer, lethal autonomy protocols, and data sovereignty in defense AI systems. Compliance with these overlapping regimes shapes vendor eligibility and program access across NATO and Indo-Pacific allied nations. Stakeholders must monitor divergence between permissive and restrictive AI governance models to anticipate which national procurement channels will absorb next-generation autonomy investments.
Market Dynamics
Military procurement officers are prioritizing algorithmic decision speed over platform payload capacity, compressing vendor evaluation cycles from multi-year development programs to rapid software iteration contracts.
Growth Catalysts
- US DoD AI Ethics Guidelines:The Pentagon's responsible AI framework is creating compliant procurement pathways for autonomous systems, accelerating vendor onboarding for ethical algorithm suppliers.
- Swarm Coordination Architectures:Distributed autonomous vehicle networks are displacing single-platform doctrines across contested airspace scenarios, driving sensor-fusion software demand.
- Israeli Sovereign Defense Programs:Tel Aviv's concentrated investment in unmanned ground systems is establishing export-ready technology clusters for allied nations.
Market Restraints
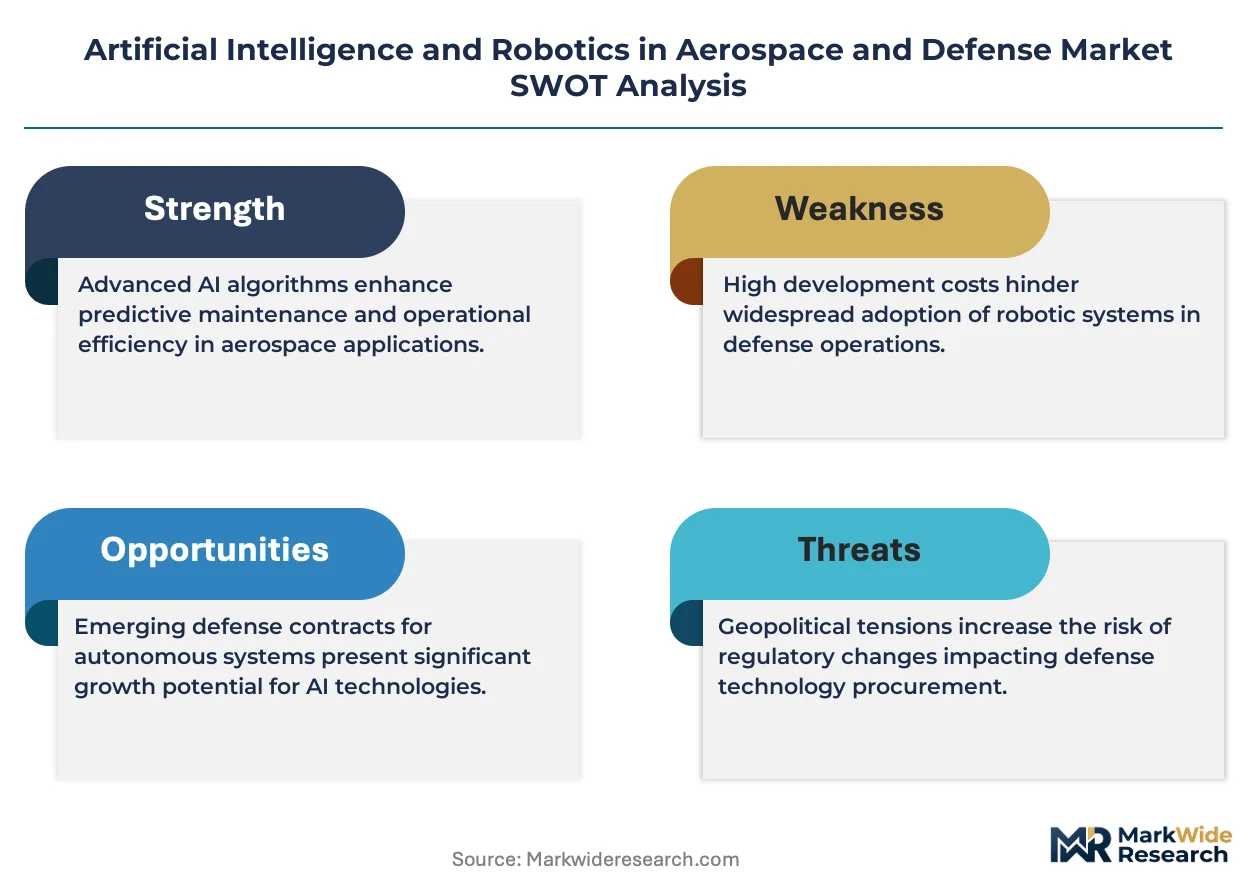
- Semiconductor Supply Concentration:Advanced GPU and neuromorphic chip fabrication concentrates in Taiwan and South Korea, creating single-point vulnerability for defense AI compute infrastructure.
- EU AI Act Lethal Autonomy Protocols:Brussels' restrictions on fully autonomous weapons systems are fragmenting NATO interoperability standards and complicating joint program development.
- Legacy Platform Integration Costs:Existing manned aircraft and ground vehicle fleets require expensive retrofit architectures to host AI decision layers, stretching defense budgets.
Strategic Opportunities
- Undersea Autonomous Perception:Australia's AUKUS submarine technology sharing is opening demand for AI-powered acoustic processing in deep-ocean surveillance platforms.
- Predictive Maintenance Convergence:Digital twin technology fused with satellite telemetry is creating new service revenue streams for aerospace OEMs operating military transport fleets.
- India's Defense PLI Scheme:New Delhi's production-linked incentives for autonomous systems manufacturing are attracting component suppliers to establish domestic assembly operations.
Industry Challenges
- AI/ML Talent Scarcity:Defense-cleared machine learning engineers with security clearances remain critically short, forcing primes to poach from commercial technology firms.
- Cross-Domain Certification Timelines:Airworthiness standards for autonomous flight software lag software release cycles by 18-24 months, creating deployment gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence and Robotics in Aerospace and Defense Market |
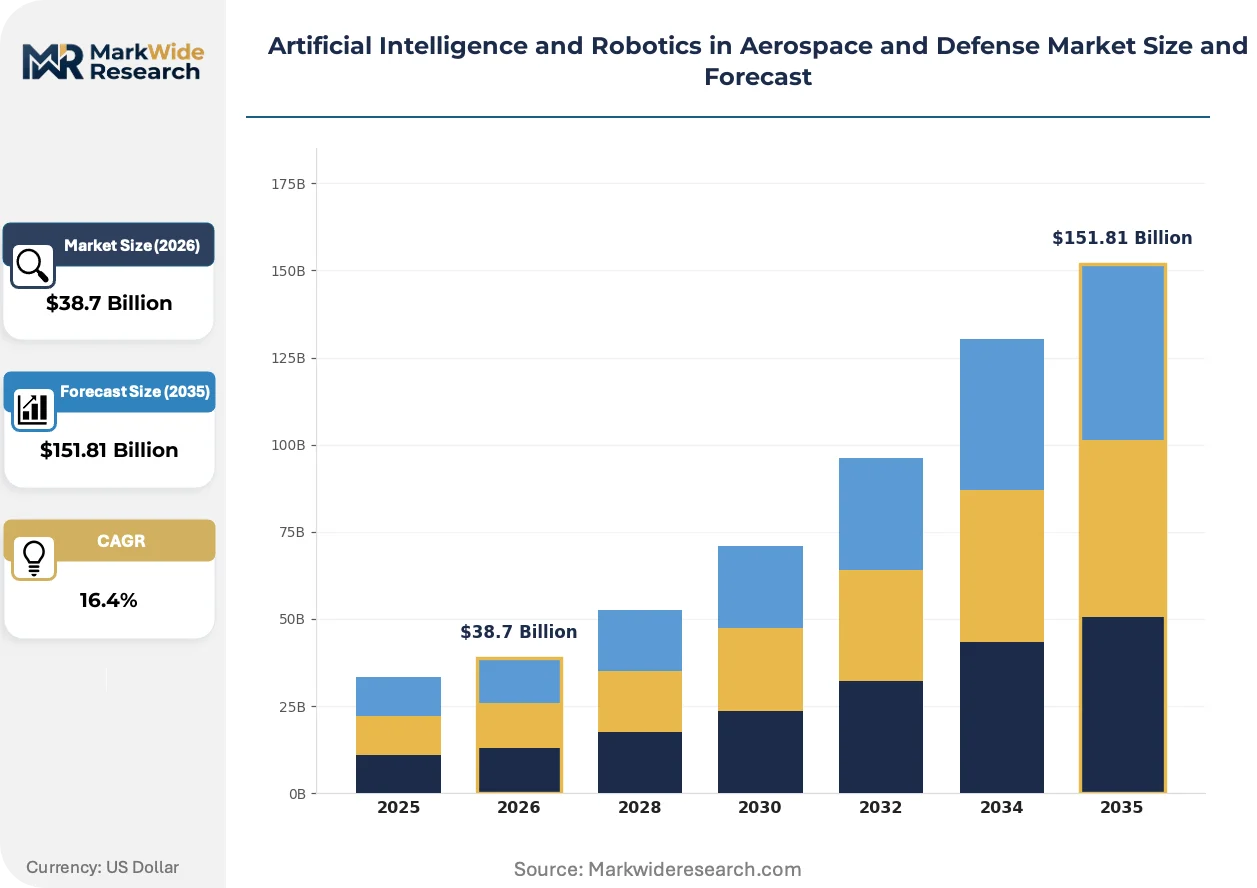
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, AI Algorithms, Autonomy Software, Sensor Technology Application: Surveillance, Maintenance, Navigation, Combat Operations End User: Government Agencies, Defense Contractors, Research Institutions, Commercial Aviation Technology: Machine Learning, Computer Vision, Natural Language Processing, Data Analytics |
| Companies Covered | Redwire Corporation, Anduril, Starfighters Space, Lockheed Martin, BAE Systems, Archer Aviation, V2X, Boston Dynamics, AeroVironment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence and Robotics in Aerospace and Defense Market Emerging Trajectories
Edge computing architectures are compressing sensor-to-shooter timelines below human reaction thresholds, forcing doctrinal revisions across NATO and Indo-Pacific allied forces.
Neuromorphic computing chips are electrifying on-board pattern recognition for hypersonic intercept scenarios. The Missile Defense Agency is integrating these processors into next-generation kill vehicles. This capability compression is eliminating ground-station dependency for time-critical targeting decisions.
The EU AI Act's risk-based classification system is mandating human-in-the-loop protocols for lethal autonomous systems. European defense contractors are redesigning command interfaces to satisfy Brussels compliance requirements. NATO procurement officers are navigating divergent US permissive and EU restrictive governance models.
Defense ministries are unbundling hardware acquisition from software sustainment contracts. The US Air Force's software acquisition pathway is displacing traditional prime-led integration models with direct vendor relationships for autonomy stacks. This channel restructuring is most advanced in Space Force satellite operations and Army Futures Command robotics programs.
Artificial Intelligence and Robotics in Aerospace and Defense Market Segmentation
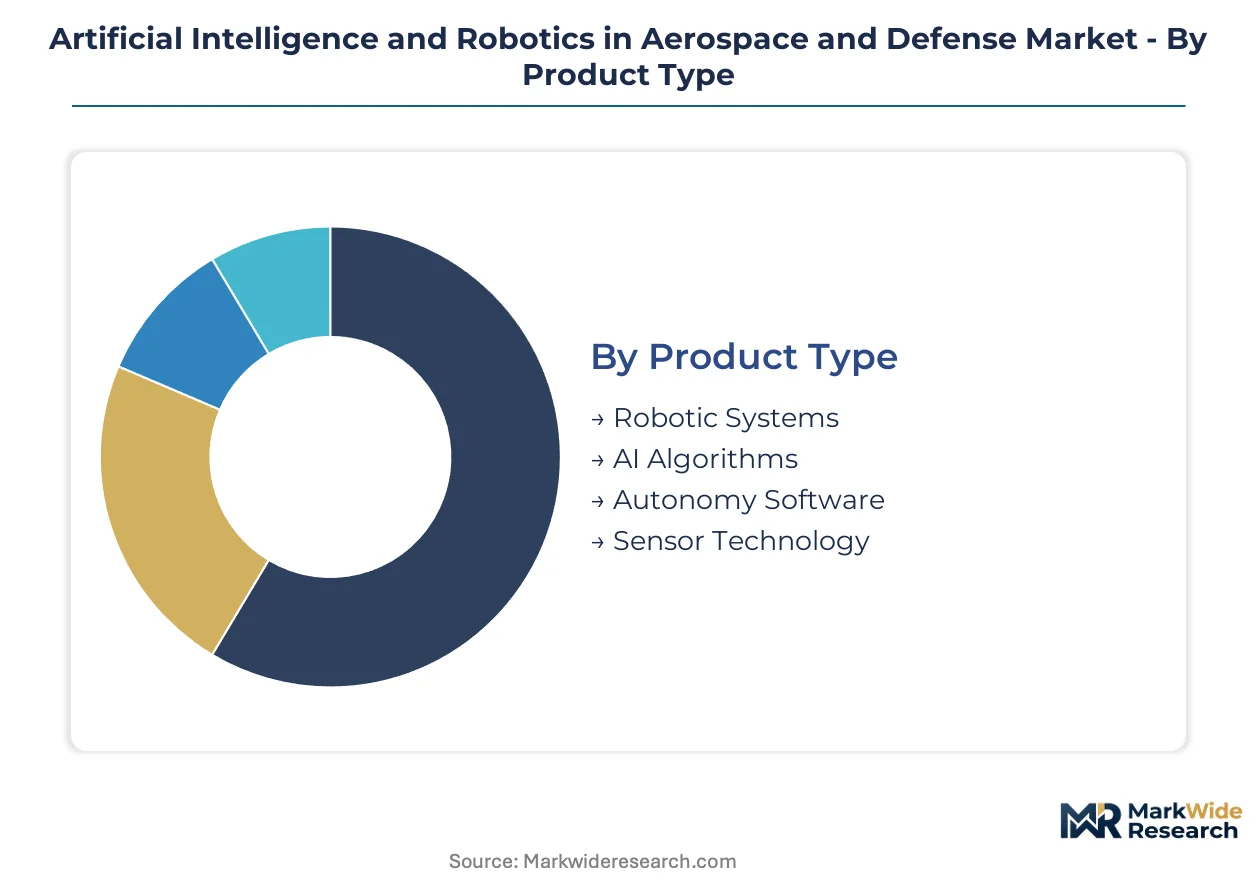
Defense procurement officers segment AI and robotics investments by integration depth, distinguishing between standalone platforms requiring full system certification and embedded modules that retrofit existing fleets. These boundaries determine contracting pathways, vendor eligibility, and compliance obligations across military acquisition programs.
Product Type:
Standalone platforms demand complete airworthiness validation, while embedded components leverage host system certifications for faster deployment cycles.
- Robotic Systems:Physical autonomous platforms encompassing unmanned aerial vehicles, ground robots, and maritime drones with hardened chassis and propulsion. The US Department of Defense concentrates procurement in tactical ground systems for contested logistics environments, driven by swarm coordination requirements in Indo-Pacific theater scenarios.
- AI Algorithms:Decision-making software modules operating at sub-50-millisecond latency for real-time threat classification and response prioritization. Israeli sovereign defense programs anchor demand for target-recognition algorithms, constrained by EU AI Act human-in-the-loop protocols affecting NATO interoperability.
- Autonomy Software:Middleware enabling multi-platform coordination and mission replanning without operator intervention.
- Sensor Technology:Perception hardware including LiDAR, synthetic aperture radar, and acoustic arrays for degraded-environment operation.
Volume placements concentrate in Robotic Systems; the faster expansion belongs to AI Algorithms.
Application:
Mission-critical deployments prioritize latency performance, while support functions emphasize reliability metrics and maintenance interval extension.
- Combat Operations:Lethal and non-lethal engagement systems requiring positive identification protocols and collateral damage estimation. China's MIIT standards and the US DoD AI Ethics Guidelines create divergent compliance baselines for autonomous targeting, fragmenting vendor participation across allied procurement channels.
- Surveillance:Persistent intelligence collection platforms operating at extended ranges with minimized signature profiles. Australian AUKUS submarine technology sharing is accelerating demand for undersea acoustic processing in deep-ocean surveillance architectures.
- Navigation:Autonomous route planning and obstacle avoidance for GPS-denied environments.
- Maintenance:Predictive diagnostics and automated repair scheduling for fleet availability optimization.
Procurement volume clusters in Combat Operations; Surveillance climbs the fastest as contested-area intelligence gaps widen.
End User:
Budget scale and security clearance requirements separate national programs from contractor-led development and academic research.
- Government Agencies:Sovereign defense ministries and intelligence services with classified program authority and direct budget allocation. The US Department of Defense, Israel's Ministry of Defense, and China's Central Military Commission concentrate procurement for strategic autonomy systems, with each imposing distinct data sovereignty and technology transfer restrictions.
- Defense Contractors:Prime integrators and subsystem suppliers executing government-funded development programs. India's Defense PLI Scheme is attracting component suppliers to establish domestic assembly operations for autonomous platforms.
- Research Institutions:University and national laboratory programs advancing foundational capabilities without immediate operational deployment.
- Commercial Aviation:Civil aerospace operators adopting military-derived autonomy for cargo and eventually passenger applications.
Contract flow concentrates through Government Agencies; Defense Contractors gain share fastest as software acquisition pathways displace traditional prime-led integration.
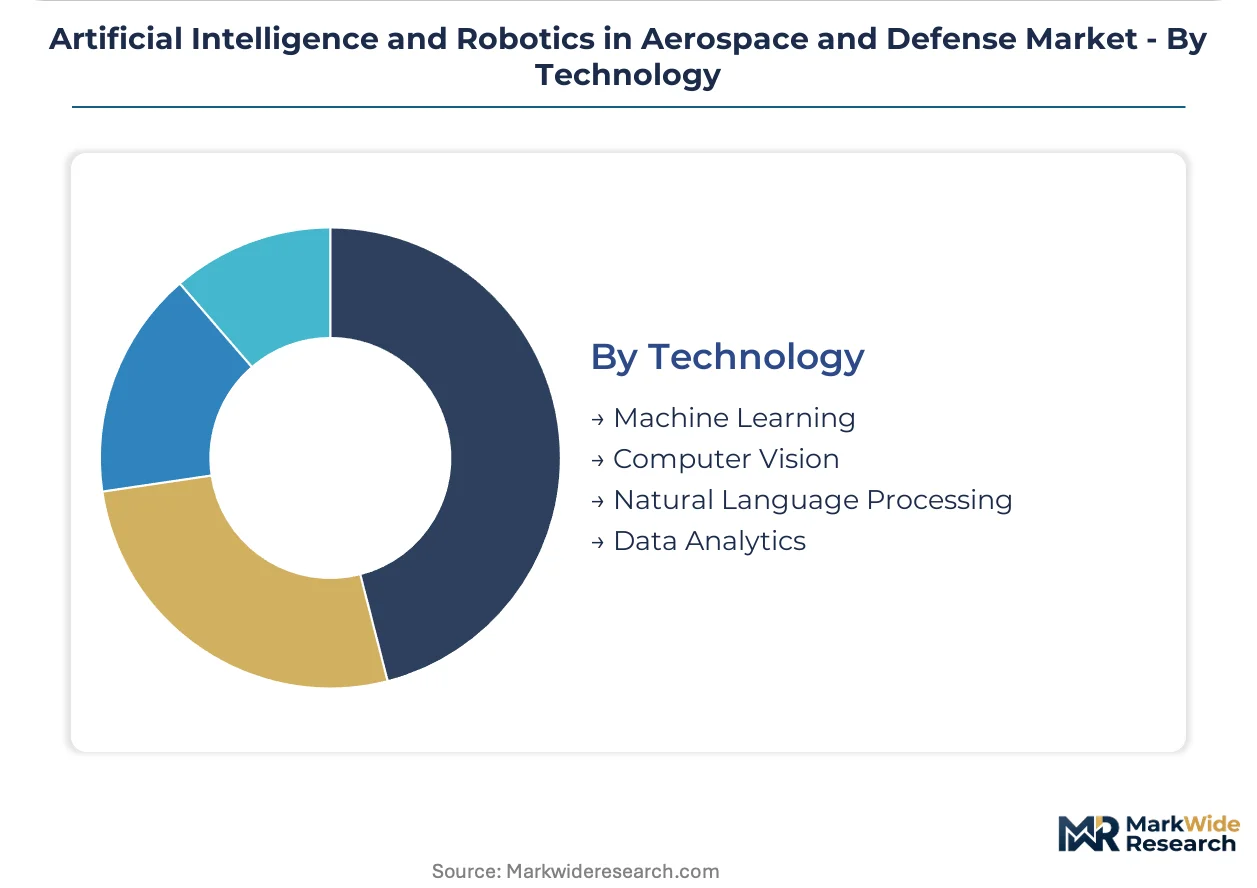
Technology:
Perception and decision layers compete for investment priority based on operational readiness and certification timeline alignment.
- Machine Learning:Statistical pattern recognition systems trained on classified operational data for threat classification and anomaly detection. The Missile Defense Agency integrates neuromorphic computing variants into hypersonic intercept kill vehicles, eliminating ground-station dependency for time-critical targeting.
- Computer Vision:Image and video processing for object detection, tracking, and scene understanding in degraded visual environments. Taiwan and South Korea's semiconductor fabrication concentration creates supply vulnerability for GPU-dependent training infrastructure.
- Natural Language Processing:Human-machine interface systems for command interpretation and multilingual intelligence processing.
- Data Analytics:Post-mission analysis and predictive modeling for operational pattern extraction.
Investment concentrates in Machine Learning; Computer Vision expands most quickly as sensor-fusion demands intensify across multi-domain operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of autonomous defense platforms while Israel and China accelerate sovereign production capacity. Taiwan and South Korea anchor semiconductor fabrication for AI compute infrastructure. European procurement fragments between permissive and restrictive governance models.
United States
The Department of Defense concentrates procurement in unmanned combat aerial systems and tactical ground robotics for Indo-Pacific theater scenarios. The Pentagon's responsible AI framework creates compliant pathways for autonomous vendors. Boston anchors classified program development while Anduril drives AI-native platform competition in California.
China
Beijing's Central Military Commission prioritizes swarm coordination architectures and hypersonic intercept autonomy under MIIT standards. Domestic GPU and neuromorphic chip fabrication expands to reduce Taiwan dependency. Shenzhen and Chengdu clusters concentrate unmanned aerial vehicle production for military export programs.
Israel
Tel Aviv's Ministry of Defense channels investment into unmanned ground systems and target-recognition algorithms for contested logistics. Sovereign defense programs establish export-ready technology clusters. Haifa and Beersheba house concentrated R&D facilities for autonomous perception systems.
United Kingdom
The Ministry of Defence accelerates AUKUS submarine technology integration with AI-powered acoustic processing requirements. BAE Systems anchors domestic autonomous platform development. Glasgow and Bristol clusters specialize in undersea surveillance and satellite autonomy software.
Australia
Canberra's AUKUS commitment drives demand for deep-ocean autonomous perception and predictive maintenance for submarine fleets. Defense procurement prioritizes algorithmic decision speed over legacy platform retrofit. Adelaide and Perth concentrate maritime autonomy testing and sovereign capability development.
Artificial Intelligence and Robotics in Aerospace and Defense Market Vendor Landscape
Top-tier vendors anchor classified program integration, while mid-tier specialists compete on rapid software iteration cycles. The vendor structure stratifies between legacy primes with decades of defense relationships and AI-native entrants unbundling hardware from software sustainment. Two archetypes dominate: full-system integrators managing airworthiness certification and modular autonomy suppliers selling directly to program offices. Competitive moves concentrate on strategic partnerships with semiconductor fabricators and direct software acquisition pathway capture.
Within the legacy prime tier, Lockheed Martin and BAE Systems occupy positions defined by classified program heritage and multi-domain integration authority. Anduril exemplifies the AI-native archetype competing on rapid deployment timelines and direct government relationships outside traditional prime channels. Boston Dynamics represents specialized legged robotics capability for tactical ground operations. These three anchors illustrate the structural tension between incumbent certification advantages and insurgent software velocity.
| Leading Market Players |
|---|
| Redwire Corporation |
| Anduril |
| Starfighters Space |
| Lockheed Martin |
| BAE Systems |
| Archer Aviation |
| V2X |
| Boston Dynamics |
| AeroVironment |
| Others |
Supply Flow & Price Mechanics
US Department of Defense program offices and allied sovereign defense ministries concentrate procurement authority in a narrow buyer pool that enforces cost-plus contracting with fixed-fee ceilings for autonomous platforms. This buyer concentration compresses vendor margins while rewarding rapid software iteration cycles over hardware scale economies.
Pricing Analysis
Margin tightening in embedded AI modules reflects the Pentagon's software acquisition pathway displacing traditional prime-led integration models. Three-tier pricing structure across classified, ITAR-restricted, and commercial-off-the-shelf levels separates vendors by security clearance depth and certification timeline. Cost-down pressure on autonomy software accelerates because defense contractors unbundle hardware from sustainment contracts. Government agencies exhibit lowest price sensitivity for combat operations applications, while research institutions face strict budget caps.
Supply Chain Analysis
Workforce-availability constraints in Taiwan and South Korea semiconductor fabrication centers are forcing neuromorphic chip suppliers to expand packaging operations in Israel and the United States. Advanced GPU and acoustic sensor arrays draw from concentrated East Asian foundry capacity, creating single-point vulnerability for defense AI compute infrastructure. Tariff exposure on Taiwan-sourced components threatens hypersonic intercept kill vehicle production timelines. Distribution runs through prime integrator channels with direct vendor relationships displacing legacy procurement hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic decision systems are displacing hardware-centric procurement doctrines across NATO and Indo-Pacific allied forces, compressing vendor evaluation cycles from multi-year development to rapid software iteration.
For Market Incumbents: To counter AI-native platform competitors unbundling software from hardware sustainment, Lockheed Martin and BAE Systems must accelerate direct program office relationships outside traditional prime channels. Certification investment in cross-domain airworthiness standards for autonomous flight software closes deployment gaps against insurgent software velocity. For New Entrants and Emerging Players: The premium-economy pricing gap in predictive maintenance services for military transport fleets creates entry opportunity for digital twin specialists. India's Defense PLI Scheme offers the most penetrable geography for component suppliers establishing domestic assembly. Go-to-market through direct software acquisition pathways bypasses prime integration bottlenecks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier autonomy software vendors with cleared engineering teams in Israel and Australia. Long-term viability hinges on algorithmic superiority positioning over hardware scale across the next defense procurement supercycle. Watch divergence between US permissive and EU restrictive AI governance models as inflection indicator for NATO interoperability investment flows.| Strategic Initiative | Industry Significance |
|---|---|
| Neuromorphic Computing Integration | The Missile Defense Agency accelerates hypersonic intercept kill vehicle deployment without ground-station dependency. |
| Direct Software Acquisition Pathway Capture | US Air Force and Space Force displace traditional prime-led integration with vendor-direct autonomy stack procurement. |
| AUKUS Submarine Technology Sharing | Australian defense procurement opens demand for deep-ocean autonomous perception and AI-powered acoustic processing. |
| India Defense PLI Scheme Participation | Component suppliers establish domestic assembly operations for unmanned platform manufacturing in New Delhi's incentive zones. |
| EU AI Act Compliance Architecture | European contractors redesign command interfaces to satisfy Brussels human-in-the-loop protocols for lethal autonomous systems. |
Methodological Framework
Multi-period observation of military procurement contract awards, vendor onboarding timelines, and algorithmic decision system deployment rates anchored the trend analysis, supplemented by interviews with defense program executives, autonomy software engineers with security clearances, semiconductor procurement leads at prime integrators, and military acquisition officers at NATO allied ministries. Secondary validation drew from DoD budget justification materials, EU AI Act regulatory filings, MIIT standards documentation, and customs data on GPU and neuromorphic chip trade flows. Bottom-up contract aggregation and top-down defense budget allocation modeling enabled triangulation across estimation approaches.
Segment-weighting across product type, application, end user, and technology dimensions shaped the analytical framework across the projection horizon. Machine learning investment intensity, swarm coordination architecture adoption curves, and human-in-the-loop protocol compliance timelines informed defense-specific forecast inputs. CAGRs derived from contract value run-rates and procurement officer stated intent surveys.
Inputs from classified program announcements and sovereign defense ministry budget disclosures were available through the study window; gaps in Israeli and Chinese unmanned systems production data introduce uncertainty bands around Middle East and Asia-Pacific regional estimates. Forecasts reflect documented assumptions on AUKUS technology sharing implementation pace and EU AI Act enforcement consistency. A small set of triggers—Taiwan semiconductor supply disruption, lethal autonomy protocol divergence between NATO allies, and clearance backlog resolution timelines—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Artificial Intelligence in Space Market