
 Stealth Technology Market | 2026-2036
Stealth Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Stealth Technology Market Analysis
Aftermarket platform sustainment revenue is rewriting profitability expectations across prime contractors. Lockheed Martin Corporation leverages its F-35 global supply chain to capture recurring modernization contracts. Northrop Grumman Corporation anchors its position through dominance in low-observable flying-wing architectures. BAE Systems competes via specialized electronic warfare integration that extends platform lifecycles.
Stealth technology encompasses engineered systems and materials designed to reduce detection by radar, infrared, acoustic, and visual sensors through controlled electromagnetic signature management, typically achieving radar cross-section reductions of 30 to 40 decibels below conventional platforms. Its primary purpose is enabling military assets to penetrate contested airspace and maritime zones without triggering adversary targeting chains. Aircraft platforms command the largest value pool given program scale and complexity, while absorption materials represent the fastest-expanding technology segment as multi-spectral coatings displace legacy single-band solutions. Surveillance applications are gaining share as unmanned systems proliferate, though defense end users retain absolute spending dominance.
The United States Department of Defense mandates MIL-STD-461 and MIL-STD-464 electromagnetic compatibility standards that constrain supplier qualification and sustain incumbent advantages. China's SAMR and MIIT enforce GB standards on dual-use exports, fragmenting supply access for foreign component vendors. The EU AI Act and CSRD disclosure rules are beginning to shape procurement transparency for member state defense ministries. Stakeholders must monitor how export control harmonization between the US ITAR regime and emerging European frameworks reshapes cross-border program participation.
Market Dynamics
Additive manufacturing of radar-absorbent structures is compressing qualification timelines and fragmenting supplier bases as defense primes bypass traditional forging networks.
Growth Catalysts
- US DoD Electromagnetic Standards:MIL-STD-461 and MIL-STD-464 mandates sustain incumbent supplier advantages while accelerating platform refresh cycles.
- Multi-Spectral Coating Adoption:Advanced metamaterials combining radar, infrared, and visual signature suppression displace legacy single-band treatments across fighter and UAV programs.
- China's Sovereign Capability Push:MIIT and SAMR enforcement of GB standards on dual-use exports fragments foreign vendor access and redirects procurement toward domestic supply chains.
Market Restraints
- Rare Earth Concentration:Ferrite and carbonyl iron precursor supply concentrates in Chinese processing facilities, exposing Western primes to export restriction vulnerability.
- Qualification Timeline Rigidity:Airworthiness certification for novel RAM formulations extends 18-36 months, freezing material substitution even when performance advantages emerge.
- Platform Life Extension Tradeoffs:Legacy aircraft structural modifications for signature reduction compete with unmanned system procurement for constrained defense budgets.
Strategic Opportunities
- UK Electronic Warfare Integration:BAE Systems' specialized sensor fusion architectures create aftermarket modernization pathways for European Typhoon and Tempest fleets.
- Unmanned Maritime Surface Vessels:Naval drone proliferation opens demand for compact, conformal RAM applications absent manned-platform volume constraints.
- EU CSRD Transparency Mandates:Sustainability disclosure requirements for defense procurement are reshaping supplier qualification criteria toward traceable material sourcing.
Industry Challenges
- Electromagnetic Simulation Talent Scarcity:Computational signature modeling expertise concentrates at a handful of national laboratories and prime contractor captive teams.
- Legacy Platform Architecture Lock-In:F-35 and B-21 program-specific tooling and fixturing resist rapid reconfiguration for next-generation low-observable designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stealth Technology Market |
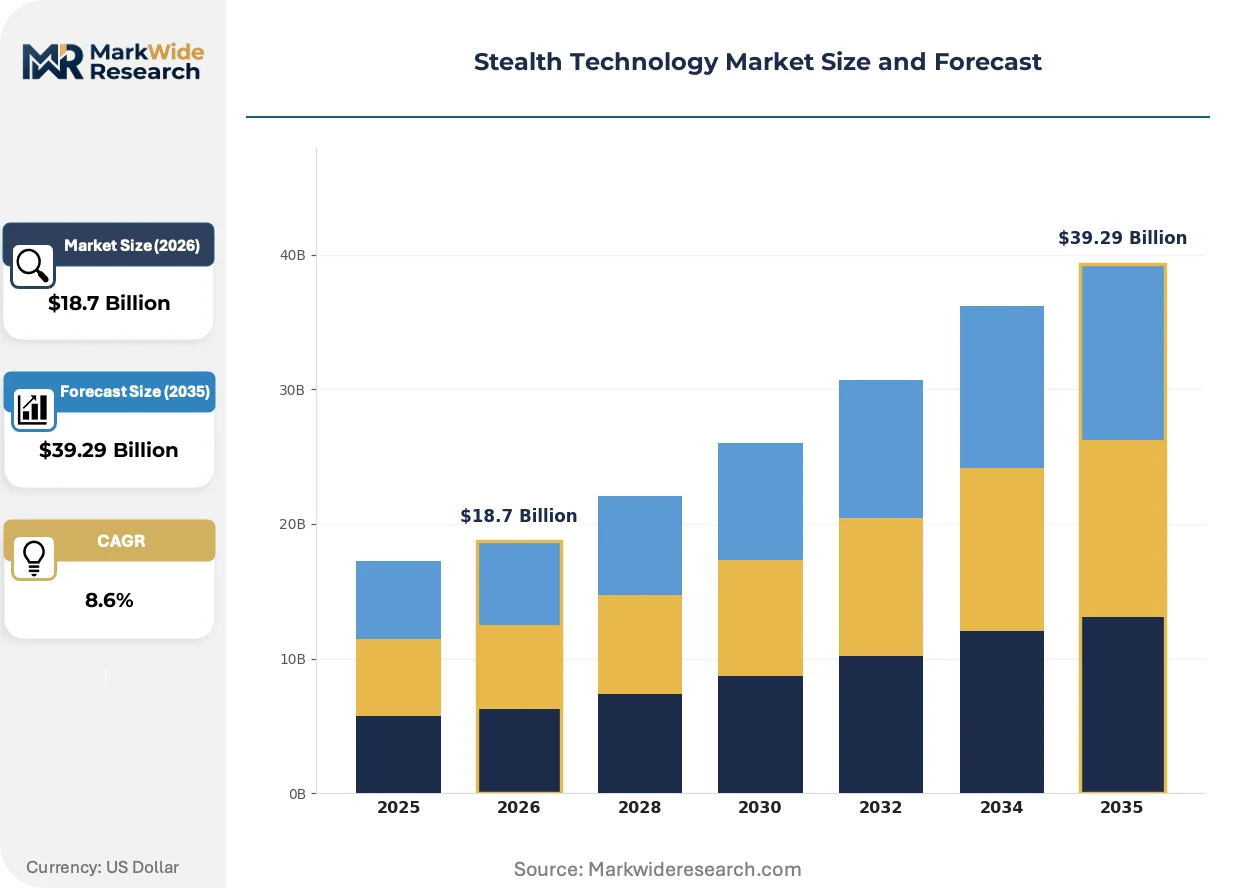
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
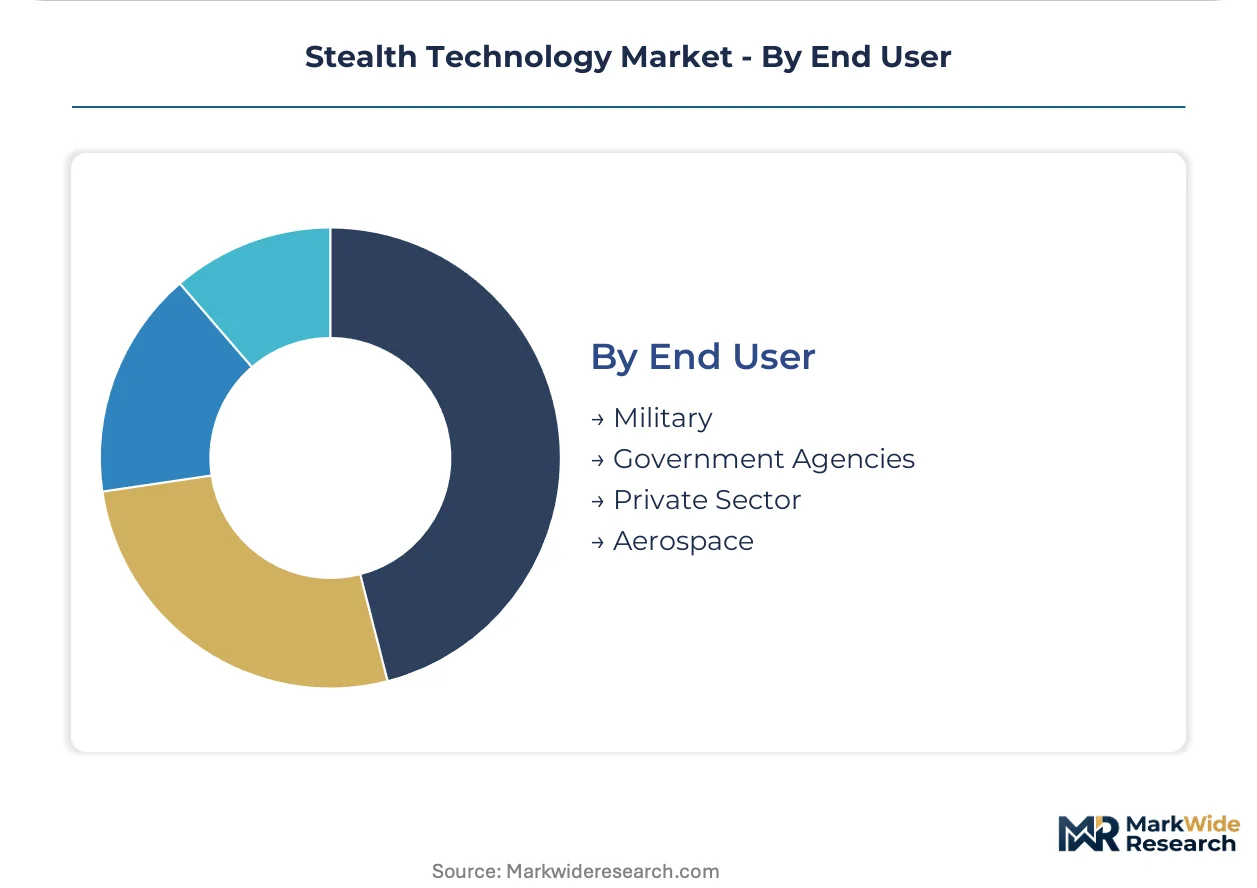
| Segmentation | Product Type: Radars, Aircraft, Ships, Submarines Application: Defense, Surveillance, Reconnaissance, Research Technology: Waveform Manipulation, Absorption Materials, Shape Optimization, Signal Processing End User: Military, Government Agencies, Private Sector, Aerospace |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, RTX Corporation, Boeing, General Dynamics Corporation, Thales Group, Saab AB, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stealth Technology Market Emerging Trajectories
Digital engineering workflows are collapsing the traditional design-build-test cycle for signature-managed platforms, compressing decade-long development programs into single-digit-year timelines.
Metamaterial surface coatings are virtualizing the physical radar-absorbent layer stack through engineered electromagnetic impedance gradients. Naval Research Laboratory and Air Force Research Laboratory programs are transitioning these formulations from laboratory demonstration to platform qualification. The technology is virtualizing the tradeoff between broadband absorption and mechanical durability that constrained legacy ferrite-polymer composites.
EU AI Act algorithmic transparency requirements are extending into military procurement frameworks through member state defense ministry adoption. Automated target recognition systems aboard stealth platforms face new explainability mandates affecting sensor software architecture. French and German procurement offices are embedding these criteria into unmanned combat air vehicle specifications ahead of broader NATO harmonization.
Performance-based logistics contracts are displacing transactional spare-part purchasing across F-35 sustainment networks. Lockheed Martin and international partner depots now guarantee availability metrics rather than delivering discrete components, transferring operational risk to primes. This restructuring concentrates most visibly in Pacific theater pre-positioning agreements where readiness requirements override unit-cost optimization.
Stealth Technology Market Segmentation
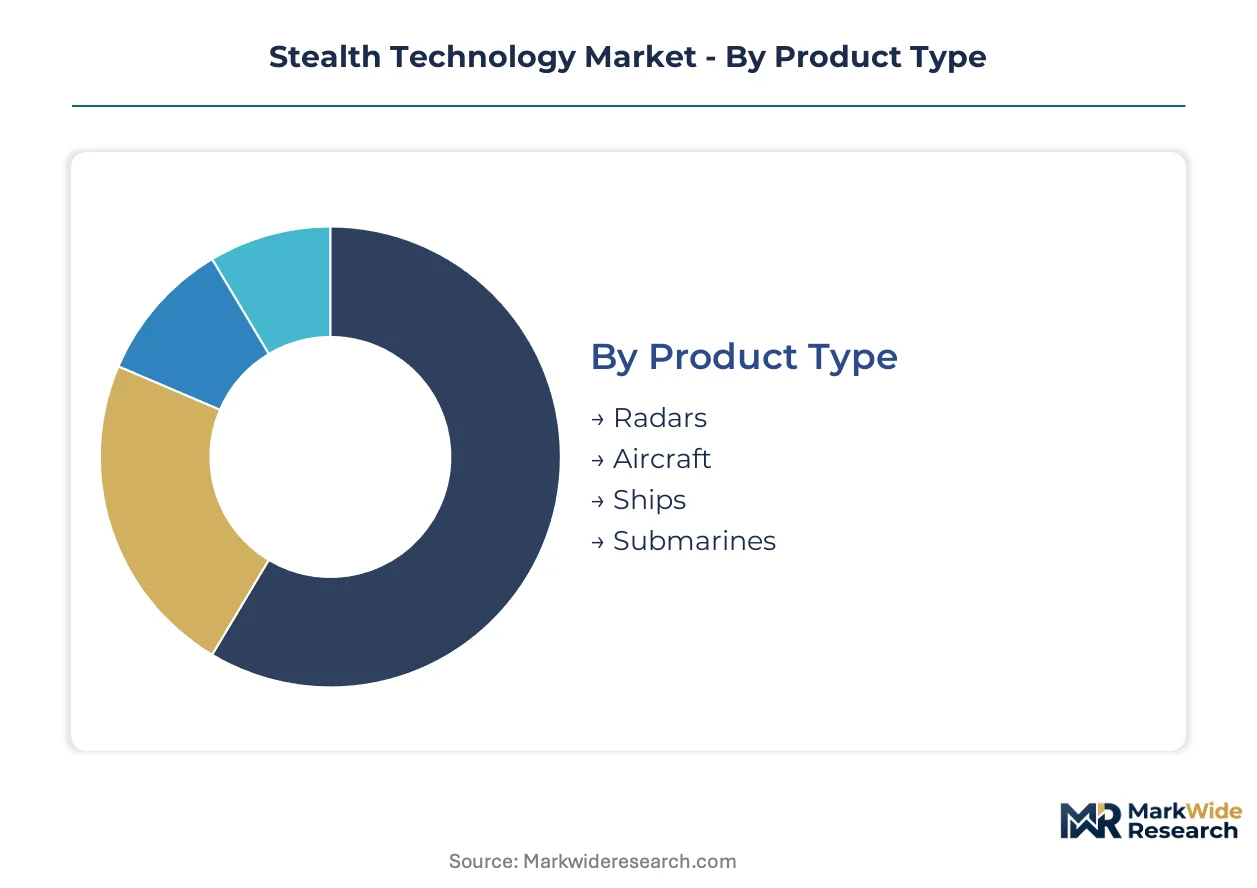
Stealth technology procurement splits across platform generations, mission profiles, and signature management approaches. Understanding these divisions reveals where development budgets concentrate and where emerging specifications are rewriting supplier qualification criteria.
Product Type:
Platform-scale programs absorb capital differently than component-level systems, with manned assets demanding decade-long development cycles while sensor packages refresh faster.
- Aircraft:Low-observable manned and unmanned platforms integrate conformal radar-absorbent structures with planform alignment. Demand clusters in United States fifth-generation fighter production and China's sovereign J-20 and H-20 programs.
- Ships:Naval surface combatants employ infrared suppression stacks and radar cross-section shaping through angled superstructures. Procurement is accelerating in United Kingdom Type 26 frigate builds and United States DDG(X) next-generation destroyer planning.
- Radars:Passive and low-probability-of-intercept arrays minimize electromagnetic emissions that betray platform positions.
- Submarines:Acoustic signature management through anechoic tiling and machinery isolation dominates undersea stealth investment.
Established volume favors Aircraft; emerging adoption favors Ships.
Application:
Mission duration and threat exposure dictate whether platforms prioritize penetration endurance or sensor persistence.
- Defense:Strike and air superiority missions demand all-aspect signature suppression across radar, infrared, and visual bands. Pentagon procurement through F-35 and B-21 programs anchors this segment's technology maturation pathways.
- Surveillance:Unmanned systems prioritize low-observable loiter over multi-spectral suppression, with sensor fusion architectures from BAE Systems and Northrop Grumman driving specification evolution.
- Reconnaissance:Penetrating intelligence platforms balance speed against signature, with legacy U-2 and emerging RQ-180 programs illustrating competing design philosophies.
- Research:Experimental platforms test metamaterial formulations and plasma-based signature reduction before operational transition.
Defense commands the deepest program funding; Surveillance exhibits the steepest expansion trajectory as unmanned platforms proliferate.
Technology:
Material science advances are fragmenting the traditional dominance of ferrite-based absorption, with engineered surfaces offering broadband performance.
- Absorption Materials:Metamaterial coatings and additive-manufactured radar-absorbent structures virtualize impedance matching layers. Naval Research Laboratory programs are transitioning these from demonstration to platform qualification.
- Shape Optimization:Computational electromagnetic design tools enable planform refinement before physical prototyping, compressing development timelines.
- Waveform Manipulation:Active cancellation systems generate counter-signals to nullify reflections, though power and processing constraints limit deployment.
- Signal Processing:Low-probability-of-intercept radar modes and emission control protocols reduce detectability without physical platform modification.
Absorption Materials attract the most rapid technology investment; Shape Optimization delivers the most immediate cost leverage for new platform designs.
End User:
Budget authority and classification requirements segment procurement sophistication, with sovereign military programs setting specifications that flow downstream.
- Military:United States Department of Defense MIL-STD-461 and MIL-STD-464 standards constrain supplier bases while mandating electromagnetic compatibility across tri-service platforms. China's MIIT enforces parallel GB standards that fragment foreign vendor access.
- Government Agencies:Intelligence community requirements for penetrating reconnaissance drive specialized low-observable specifications beyond standard military procurement.
- Aerospace:Commercial satellite and high-altitude platform manufacturers adopt adapted military absorption techniques for reduced radar visibility.
- Private Sector:Limited dual-use access restricts participation to non-classified material research and simulation software development.
Military procurement sets the dominant technical baseline; Government Agencies pursue the most specialized performance thresholds outside standard program structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply across geographies, with the United States prioritizing multi-domain platform integration while China pursues sovereign supply chain closure and European states emphasize interoperability standards.
United States
The Department of Defense anchors global stealth platform investment through F-35 and B-21 production lines, with MIL-STD-461 and MIL-STD-464 electromagnetic compatibility standards constraining supplier qualification to incumbent defense primes. Congressional appropriations through the National Defense Authorization Act sustain decade-long development cycles. Lockheed Martin's Fort Worth, Texas facility concentrates low-observable manufacturing expertise alongside Northrop Grumman's Palmdale, California operations for flying-wing architectures.
China
MIIT and SAMR enforcement of GB standards on dual-use exports fragments foreign vendor access while redirecting procurement toward domestic supply chains for J-20 and H-20 programs. State-directed investment through defense industry conglomerates accelerates rare earth processing capabilities for ferrite precursor independence. Chengdu and Xi'an aerospace clusters house sovereign fighter and bomber development facilities with vertically integrated radar-absorbent material production.
United Kingdom
BAE Systems drives Tempest sixth-generation fighter development alongside Typhoon fleet modernization, with Ministry of Defence procurement emphasizing electronic warfare integration over pure signature reduction. The UK's Defence and Security Industrial Strategy prioritizes sovereign capability in sensor fusion architectures. Warton and Samlesbury manufacturing sites concentrate low-observable structure assembly for European collaborative programs.
France
Dassault Aviation and Thales Group anchor FCAS program participation with Direction Générale de l'Armement specifications emphasizing spectral management across radar and infrared bands. The EU AI Act's algorithmic transparency requirements are embedding into unmanned combat air vehicle procurement ahead of broader NATO harmonization. Saint-Cloud and Bordeaux-Mérignac defense clusters specialize in active cancellation systems and conformal antenna integration.
Israel
Israel Aerospace Industries and Elbit Systems pursue compact stealth applications for unmanned platforms and precision munitions, with Ministry of Defense procurement prioritizing rapid fielding cycles over multi-decade development. The country's national defense regulator maintains classification frameworks that limit foreign supplier penetration. Lod and Haifa technology corridors concentrate electromagnetic simulation expertise and metamaterial prototyping capabilities.
Stealth Technology Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The stealth technology market structures around a consolidated prime contractor base with captive low-observable manufacturing expertise, while specialized material suppliers compete for platform qualification slots. Three archetypes dominate: integrated platform primes controlling end-to-end development, electronic warfare specialists capturing sensor fusion modernization contracts, and metamaterial research houses transitioning laboratory formulations to production. Competitive moves center on performance-based logistics contracting that transfers operational risk to primes and strategic partnerships securing rare earth precursor supply.
Within the integrated platform tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify scale-driven positions through multi-decade fighter and bomber program execution, while BAE Systems occupies a specialized role in European electronic warfare integration. These entities represent contrasting strategic postures: the former anchor global production volume through established supply chains, while the latter exemplifies regional sovereignty in sensor architecture development.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| RTX Corporation |
| Boeing |
| General Dynamics Corporation |
| Thales Group |
| Saab AB |
| Leonardo S.p.A. |
| Others |
Supply Flow & Price Mechanics
Rare earth export restriction exposure determines both pricing tier spreads and supply chain shape across Western stealth platform programs. Chinese dominance in ferrite and carbonyl iron precursor processing concentrates cost volatility risk in absorption material supply, while MIL-STD-461 qualification mandates lock prime contractors into long-term offtake structures that resist spot-market arbitrage.
Pricing Analysis
Long-term performance-based offtake agreements dominate stealth technology procurement, with Lockheed Martin and Northrop Grumman guaranteeing platform availability metrics rather than transacting discrete components. Price differentiation rests on certification grade against MIL-STD-464 electromagnetic compatibility tiers and volume scale across multi-year fighter production runs. Cost compression in metamaterial coating segments is intensifying because additive manufacturing bypasses traditional forging networks. Government defense agencies exhibit lowest price sensitivity given mission-critical requirements, while aerospace satellite manufacturers face tighter budget constraints.
Supply Chain Analysis
US ITAR and emerging European export-control regimes fragment cross-border technology flows and enforce captive supply chain architectures. Raw material sourcing draws from Chinese rare earth processing facilities, South Korean carbonyl iron production, and domestic US additive manufacturing feedstock suppliers. Single-source vulnerability concentrates in ferrite precursor supply where Chinese export licensing creates chokepoint exposure. Distribution runs through defense prime contractor captive networks with limited spot-market participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cyclicality anchors this market's recovery trajectory, with Congressional appropriations through the National Defense Authorization Act providing predictable multi-year funding visibility.
For Market Incumbents: Harden electromagnetic simulation talent retention through captive national laboratory partnerships that resist poaching by emerging metamaterial research houses. Deepen backward integration into rare earth precursor processing via strategic offtake with Australian and Canadian mining ventures to offset Chinese supply concentration. Lockheed Martin's F-35 global supply chain exemplifies how platform-scale programs resist substitution through qualification timeline inertia.
For New Entrants and Emerging Players: European unmanned maritime surface vessel programs represent the most penetrable white-space target given absent manned-platform volume constraints and limited incumbent electronic warfare integration. Compact conformal radar-absorbent material applications for naval drones offer faster qualification pathways than fighter programs. A direct contracting angle with UK Ministry of Defence procurement offices bypasses prime contractor gatekeeping that dominates US Department of Defense channels.
For Investors and Strategic Acquirers: EU AI Act algorithmic transparency mandates reshaping unmanned combat air vehicle specifications alter the acquisition landscape toward sensor software architecture specialists. Long-term viability across the analysis window favors metamaterial research houses transitioning laboratory formulations to platform qualification over traditional ferrite-polymer composite suppliers. Watch for harmonization between US ITAR and European export control frameworks as the signal indicating cross-border program participation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contracting | Transfers operational risk to primes through F-35 availability guarantees across Pacific theater pre-positioning agreements. |
| Additive Manufacturing Qualification | Compresses radar-absorbent structure development timelines at Naval Research Laboratory demonstration-to-platform transition programs. |
| Rare Earth Supply Agreement | Secures ferrite precursor independence for Western primes facing Chinese SAMR export licensing uncertainty. |
| Metamaterial Coating Development | Virtualizes impedance matching layers through Air Force Research Laboratory broadband absorption programs. |
| Electronic Warfare Integration Partnership | Extends Typhoon and Tempest fleet lifecycles via BAE Systems sensor fusion architecture modernization. |
Methodological Framework
Desk research of defense procurement databases, electromagnetic compatibility standards documentation, and rare earth trade flow records preceded structured interviews with low-observable manufacturing engineers, defense prime contractor procurement leads, national laboratory program managers, and Ministry of Defence acquisition specialists. Primary fieldwork combined with secondary validation against SEC 10-K filings, Congressional appropriations records, and EU defense procurement transparency disclosures. Bottom-up platform production estimates triangulated against top-down defense budget allocation analysis.
Assumptions held fixed include current US ITAR and Chinese GB standards enforcement intensity, while rare earth export licensing stringency and EU AI Act adoption timelines were varied across scenarios. The forecast framework segments by platform type, signature management technology, end-user classification, and sovereign supply chain closure status. CAGRs were derived from defense budget trajectory modeling and platform refresh cycle analysis. Industry-specific inputs included F-35 production rate disclosures and B-21 program development milestones.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-directed aerospace conglomerates would shift outcomes. Material shifts in US-European export control harmonization or Chinese rare earth export restriction severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
AI in Aviation Market