
 Optical Satellite Communication Market | 2026-2036
Optical Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Satellite Communication Market Intelligence
Europe's photonics manufacturing corridor is reconfiguring supply chains for space-qualified optical components. Mynaric AG anchors German production of laser communication terminals for government and commercial constellations. Thales Alenia Space leverages Franco-Italian satellite integration expertise to compete on European institutional programs. Ball Corporation sustains US defense contracting relationships through precision optical payload manufacturing.
Optical satellite communication employs laser beams to transmit data between satellites, ground stations, and airborne platforms using wavelengths typically in the 1550 nanometer range for atmospheric transmission efficiency and eye safety compliance. This technology serves missions requiring terabit-class throughput, ultra-low latency, and resistance to radio frequency jamming or interception. Laser transceivers and optical terminals command the dominant share of hardware value, driven by constellation deployment scale and terminal replacement cycles. Free space optics technology leads current implementations, while quantum key distribution represents the fastest-growing segment as sovereign encryption requirements intensify among defense agencies and financial infrastructure operators.
The FCC governs spectrum coordination and orbital licensing for US-based optical satellite networks, while the EU Space Programme Agency supervises European secure connectivity initiatives under government funding frameworks. ITU-R recommendations on inter-satellite link interference protection shape international deployment standards and cross-border operational approvals. Stakeholders must monitor evolving debris mitigation rules and national security classification requirements that will determine market access for foreign component suppliers and terminal manufacturers.
Market Dynamics
Defense procurement acceleration is compressing development cycles for space-qualified optical terminals, while constellation operators demand terabit throughput at unit economics that strain current manufacturing capacity.
Growth Catalysts
- Streamlined FCC Licensing:The FCC's expedited approval framework for optical inter-satellite links reduces deployment barriers for commercial constellation operators seeking rapid orbital placement.
- NATO Secure Connectivity Mandates:Defense agencies across NATO member states are accelerating laser-based satellite link procurement to achieve jam-resistant command infrastructure.
- 1550nm Wavelength Standardization:Atmospheric transmission efficiency and eye safety compliance at this wavelength is enabling terrestrial integration without specialized ground station enclosures.
Market Restraints
- Indium Phosphide Supply Concentration:Foundry capacity for space-qualified laser diodes concentrates in limited geographies, creating input cost volatility and allocation risk.
- ITU-R Interference Coordination Delays:Cross-border operational approvals for inter-satellite links face procedural friction that extends deployment timelines.
- Radio Frequency Fallback Systems:Mature RF ground infrastructure persists as a technically adequate substitute for applications not requiring quantum-secure encryption.
Strategic Opportunities
- Quantum Key Distribution Expansion:Sovereign encryption requirements among financial infrastructure operators are opening white space for quantum-secured optical links.
- Airborne Platform Integration:High-altitude relay aircraft present an underpenetrated application layer for optical terminal retrofits requiring stabilized beam tracking.
- EU Space Programme Agency Funding:European secure connectivity initiatives under government frameworks are creating procurement channels independent of commercial constellation economics.
Industry Challenges
- Precision Optics Talent Scarcity:Workforce gaps in free-space optical alignment and wavefront engineering are constraining terminal production scaling.
- Debris Mitigation Certification Burden:Evolving end-of-life disposal requirements and collision avoidance protocols are extending qualification timelines for new terminal designs.
- Legacy RF Ground Architecture Integration:Hybrid network management systems require complex protocol bridging that complicates operational deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Satellite Communication Market |
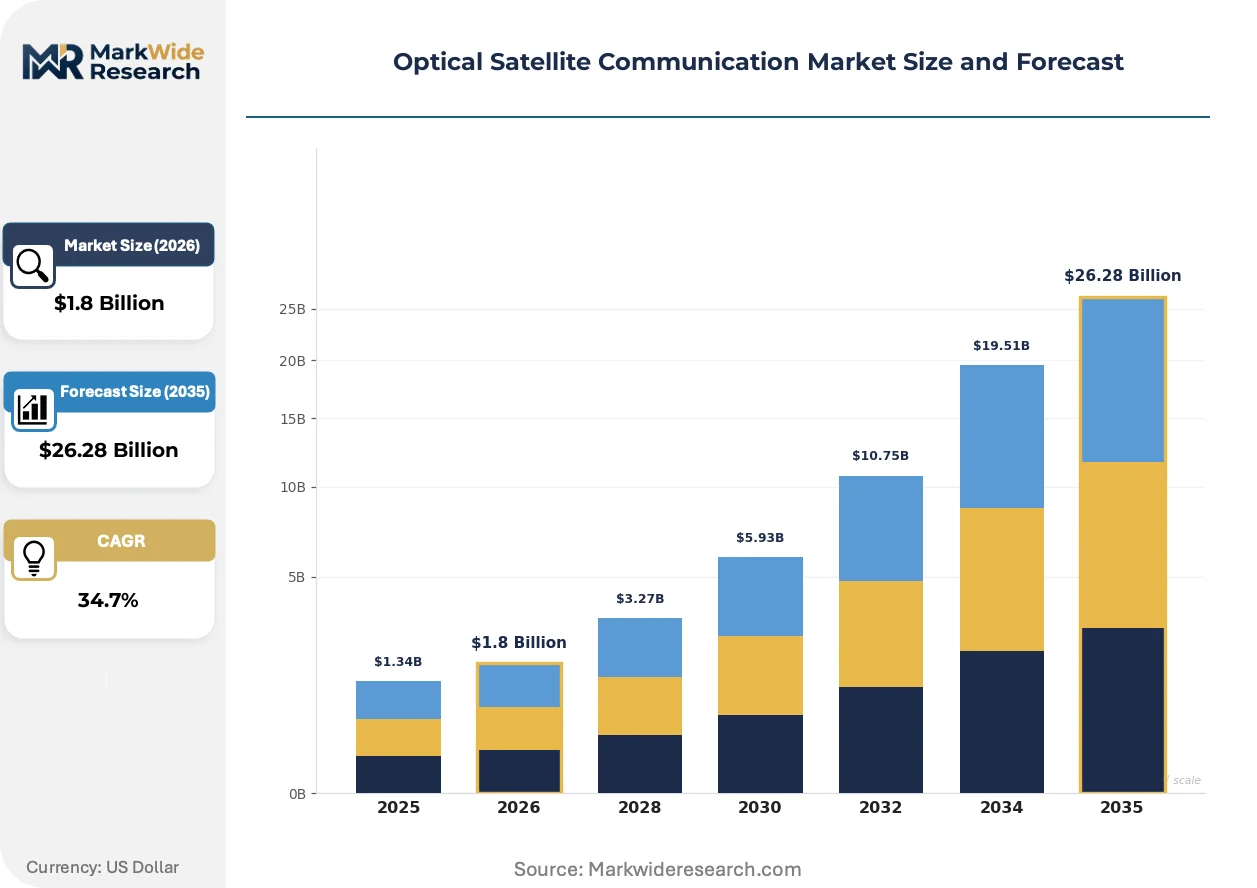
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Transceivers, Optical Terminals, Modulators, Photodetectors Technology: Free Space Optics, Coherent Optical Communication, Quantum Key Distribution, Wavelength Division Multiplexing Application: Earth Observation, Deep Space Communication, Military Reconnaissance, High-speed Data Transfer End User: Satellite Operators, Defense Agencies, Telecom Providers, Research Organizations |
| Companies Covered | SpaceX, Mynaric AG, Ball Corporation, Thales Alenia Space, Tesat-Spacecom, BridgeComm, Inc., Honeywell International Inc., Lockheed Martin Corporation, L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Satellite Communication Market Strategic Shifts & Innovations
Photonic integration is compressing terminal form factors while sovereign encryption mandates are redirecting R&D investment toward quantum-ready architectures.
Coherent optical detection with digital signal processing is digitizing receiver sensitivity thresholds that previously required analog hardware compensation. Defense procurement offices are specifying these terminals for next-generation surveillance constellations. The technology is digitizing supply chain requirements by collapsing discrete component counts into single-chip solutions.
REACH substance restrictions are forcing reformulation of optical coating chemistries used in space-qualified mirrors and beam expanders. European terminal manufacturers are accelerating qualification of alternative deposition processes to maintain access to institutional programs. German production clusters are most affected, with supply contracts requiring documented compliance across coating vendor tiers.
Long-term service agreements are displacing unit sales for optical terminal procurement, with constellation operators preferring availability-based contracts covering replacement cycles. This restructuring concentrates vendor risk while transferring operational complexity to manufacturers. The United States exhibits this pattern most visibly, particularly around SpaceX's supplier ecosystem in Washington State.
Optical Satellite Communication Market Segmentation
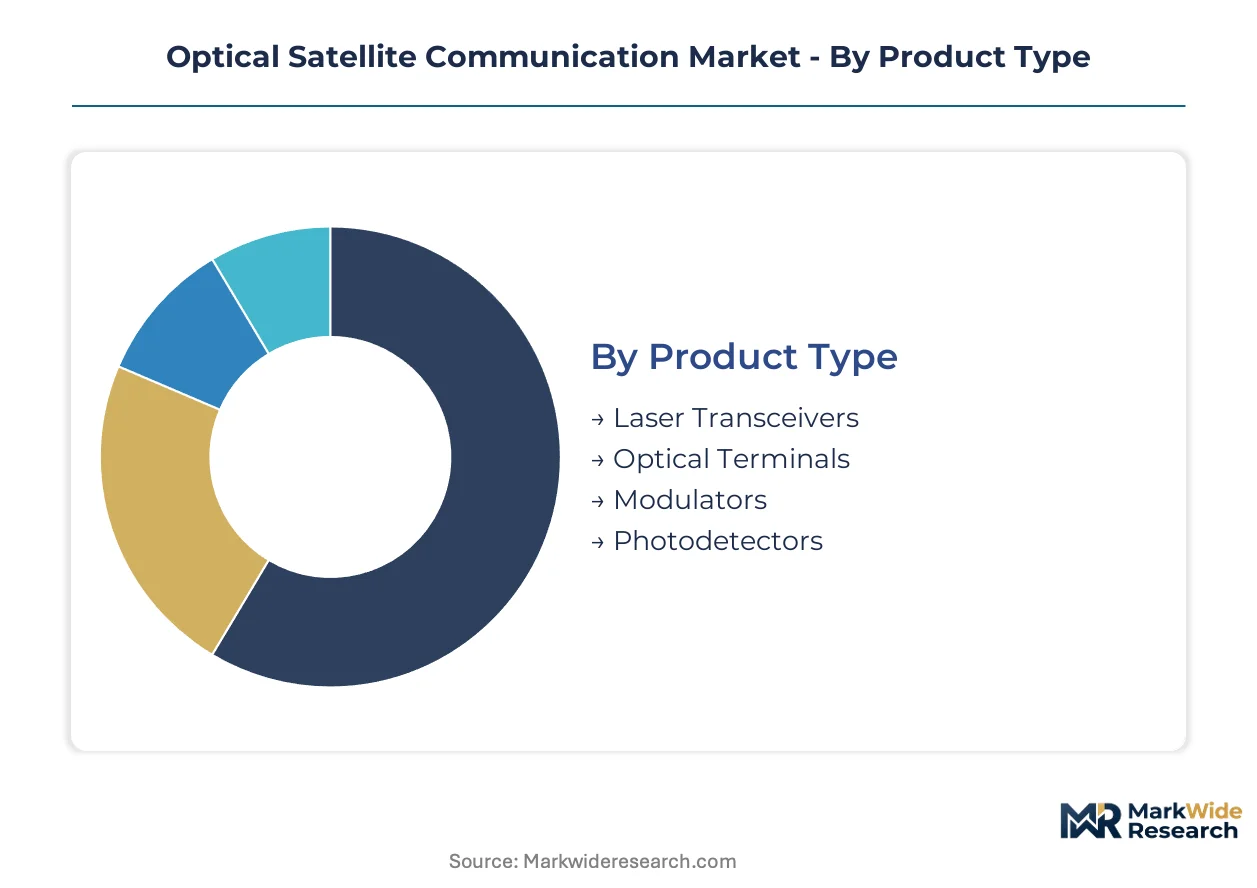
Optical satellite communication hardware exhibits steep after-sales service intensity, with terminal replacement cycles and orbital maintenance requirements driving recurring revenue streams. Component-level segmentation reveals divergent margin profiles between commoditized photodetectors and precision-aligned laser transceivers requiring field calibration. Understanding these structural differences enables vendors to allocate engineering resources across product lines with varying technical support burdens.
Product Type:
After-sales intensity varies dramatically across terminal subsystems, with precision optics demanding orbital replacement services and electronic components following standard warranty models.
- Laser Transceivers:Integrated transmitter-receiver modules operating at 1550nm wavelength incorporate indium phosphide laser diodes and coherent detection electronics. Demand concentrates at SpaceX's Redmond manufacturing hub and adjacent supplier clusters in Washington State, driven by constellation-scale procurement with compressed qualification timelines. These units command premium pricing due to beam tracking complexity and thermal management requirements in orbital environments.
- Optical Terminals:Complete ground-to-space or inter-satellite communication systems housing beam expanders, fine pointing assemblies, and control electronics. NATO defense agencies across member states are accelerating procurement of these terminals for jam-resistant command infrastructure, creating sovereign encryption-compliant demand channels distinct from commercial constellation economics.
- Modulators:Electro-optic devices encoding data onto laser carriers through phase or amplitude modulation. Mynaric AG's German production cluster specializes in space-qualified variants for government and commercial programs.
- Photodetectors:Semiconductor sensors converting optical signals to electrical output, typically indium gallium arsenide PIN or avalanche photodiode architectures. Thales Alenia Space integrates Franco-Italian sourced detectors into satellite platforms.
Laser transceivers hold the largest share; momentum sits with optical terminals as sovereign encryption mandates intensify.
Technology:
Cost tier stratification separates mature free-space implementations from quantum-ready architectures commanding development-stage premiums.
- Free Space Optics:Line-of-sight laser transmission through atmospheric or vacuum channels without fiber waveguiding, using direct detection or coherent reception. Commercial constellation operators in the United States deploy this technology at scale around SpaceX's Starlink manufacturing hub, prioritizing terabit throughput at unit economics that strain current manufacturing capacity.
- Quantum Key Distribution:Cryptographic key exchange exploiting quantum mechanical properties to detect eavesdropping attempts. Financial infrastructure operators across Europe are opening procurement channels for quantum-secured optical links, with EU Space Programme Agency funding creating demand independent of commercial constellation economics. This segment is expanding most quickly as sovereign encryption requirements intensify.
- Coherent Optical Communication:Digital signal processing-based detection with phase and polarization diversity enabling sensitivity thresholds previously requiring analog compensation. Ball Corporation sustains US defense contracting relationships through precision payload manufacturing in this category.
- Wavelength Division Multiplexing:Parallel channel multiplication across optical spectrum segments to multiply aggregate throughput without additional terminals. Research organizations leverage this technology for high-capacity experimental links.
Free space optics dominates current deployment volumes; quantum key distribution shows the steepest expansion trajectory.
Application:
Customer type differentiation separates mission-critical defense procurement from commercial throughput optimization with divergent specification tolerances.
- Military Reconnaissance:Surveillance constellation inter-satellite and downlink connectivity requiring resistance to radio frequency jamming or interception. Defense procurement acceleration across NATO member states is compressing development cycles for space-qualified terminals, with coherent detection specifications digitizing supply chain requirements.
- High-speed Data Transfer:Terabit-class commercial communication services for enterprise and consumer broadband. Demand concentrates in the United States, particularly around SpaceX's supplier ecosystem in Washington State, with availability-based long-term service agreements displacing unit sales.
- Earth Observation:Downlink connectivity for remote sensing satellites transmitting high-resolution imagery. European photonics manufacturing corridors are reconfiguring supply chains for space-qualified optical components serving this application.
- Deep Space Communication:Long-range links to lunar or planetary missions requiring extreme sensitivity and pointing precision. Research organizations drive specialized procurement with extended qualification timelines.
High-speed data transfer commands the largest addressable base; military reconnaissance exhibits the fastest policy-driven acceleration.
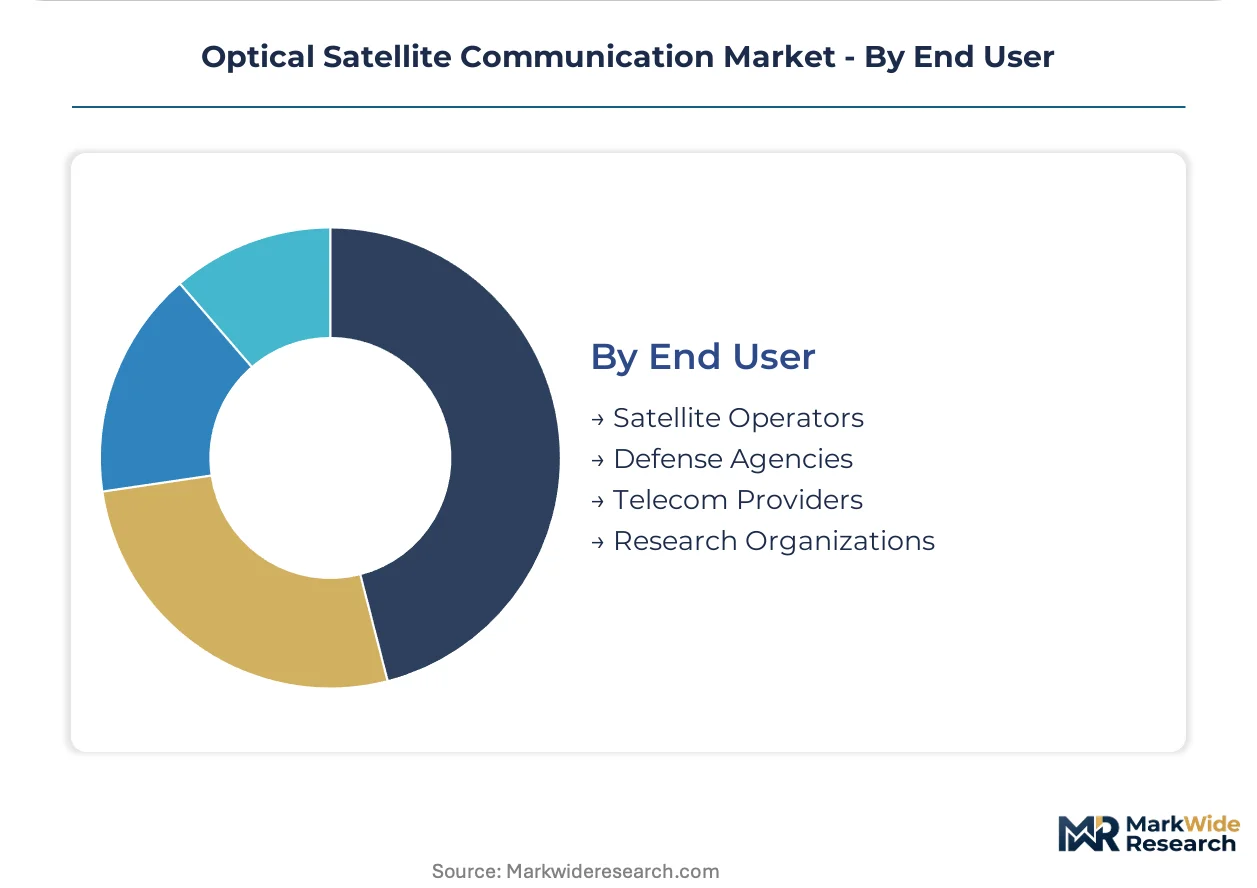
End User:
Volume concentration among constellation operators contrasts with margin protection available in defense and research channels.
- Satellite Operators:Commercial constellation deployers procuring terminals at scale for orbital replacement and network expansion. Long-term service agreements are restructuring vendor risk in the United States, particularly around SpaceX's manufacturing hub, with availability-based contracts transferring operational complexity to manufacturers.
- Defense Agencies:National security organizations specifying jam-resistant, quantum-secure optical links for command infrastructure. FCC streamlined licensing for optical inter-satellite links is reducing deployment barriers, while NATO secure connectivity mandates are accelerating laser-based procurement across member states.
- Telecom Providers:Terrestrial network operators integrating satellite optical backhaul for rural or maritime connectivity. ITU-R recommendations on interference protection shape their cross-border operational approval requirements.
- Research Organizations:Experimental mission proponents advancing deep space or quantum communication technology readiness. EU Space Programme Agency supervision creates procurement channels under European government funding frameworks.
Satellite operators represent the largest volume concentration; defense agencies provide the most durable margin protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC anchors United States market development through streamlined licensing frameworks for optical inter-satellite links, while procurement concentration around SpaceX's Redmond manufacturing hub shapes supplier geography across multiple jurisdictions.
United States
Defense agencies and commercial constellation operators drive terminal demand through separate procurement channels. FCC expedited approval processes reduce deployment barriers for orbital placement. SpaceX's Starlink manufacturing hub in Redmond, Washington anchors supplier clustering across the Pacific Northwest with compressed qualification timelines.
Germany
Government and commercial constellation programs sustain demand for laser communication terminals with distinct specification requirements. EU Space Programme Agency funding frameworks create procurement channels independent of commercial economics. Mynaric AG's production cluster in Bavaria specializes in space-qualified terminal manufacturing for institutional clients.
France
Franco-Italian satellite integration expertise supports European secure connectivity initiatives with government backing. REACH substance restrictions force reformulation of optical coating chemistries for space-qualified mirrors. Thales Alenia Space leverages Toulouse-area engineering capacity to compete on institutional programs requiring sovereign encryption compliance.
United Kingdom
Research organizations and defense procurement offices generate specialized demand for coherent detection terminals. ITU-R recommendations on interference protection shape cross-border operational approval requirements for UK-based operators. Harwell Space Cluster in Oxfordshire concentrates photonics engineering talent for free-space optical alignment applications.
Japan
Deep space communication missions and terrestrial network integration projects sustain precision optics demand. METI industrial policy supports domestic laser communication terminal development for sovereign infrastructure. Kanto region engineering centers advance coherent optical detection with digital signal processing for next-generation surveillance constellations.
Optical Satellite Communication Market Key Industry Players
Defense contractors and commercial constellation suppliers split the market along divergent procurement timelines and specification tolerances. The vendor base concentrates around three strategic archetypes: vertically integrated prime contractors, specialized optical terminal manufacturers, and subsystem component suppliers. Consolidation pressure intensifies as long-term service agreements displace unit sales and transfer operational complexity to manufacturers. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Within the specialized optical terminal tier, Mynaric AG and Tesat-Spacecom exemplify European engineering-focused positioning, while Ball Corporation occupies a position bridging defense contracting relationships with precision payload manufacturing. These three entities represent contrasting geographic anchors for supplier ecosystem development across NATO procurement channels and commercial constellation economics.
| Leading Market Players |
|---|
| SpaceX |
| Mynaric AG |
| Ball Corporation |
| Thales Alenia Space |
| Tesat-Spacecom |
| BridgeComm, Inc. |
| Honeywell International Inc. |
| Lockheed Martin Corporation |
| L3Harris Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific air freight corridors connecting Bavarian optics clusters to Redmond, Washington terminals impose cost dynamics that amplify price spreads between European institutional procurement and commercial constellation volume contracts. These logistics pressures concentrate supplier pricing power among indium phosphide foundries while forcing terminal manufacturers to absorb freight volatility or pass through to defense agencies with cost-plus contracting flexibility.
Pricing Analysis
Geographic price spreads between German institutional programs and US commercial procurement exceed three-to-one ratios for equivalent terminal specifications. Three-tier pricing structure across sovereign-encryption, enterprise-grade, and commercial-volume levels reflects certification burden and after-sales service bundling. Cost compression in commercial tiers is intensifying because SpaceX's consolidated procurement extracts volume concessions from adjacent Washington State suppliers. Defense agencies exhibit the lowest price sensitivity due to jam-resistance mandates, while satellite operators demand unit economics that strain current manufacturing capacity.
Supply Chain Analysis
Extended payment terms from prime contractors to indium phosphide foundries in Germany and the United States are straining working capital across the tier-two supplier base. Space-qualified laser diodes draw from concentrated foundry capacity in Germany, the United States, and Japan. Supply chain risk centers on single-source vulnerability for indium phosphide substrates subject to export control classifications. Distribution runs through direct OEM relationships for defense procurement and long-term service agreements for commercial constellation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as NATO secure connectivity mandates accelerate laser-based satellite link procurement beyond current manufacturing capacity. Sovereign encryption requirements among financial infrastructure operators extend the adoption runway independent of commercial constellation economics.
For Market Incumbents: Insulate terminal production margins by securing captive indium phosphide foundry capacity in Germany or the United States before export control tightening restricts foreign sourcing. Accelerate coherent detection R&D investment to digitize receiver architectures and collapse discrete component counts, defending against emerging photonic integration specialists threatening analog hardware incumbency. For New Entrants and Emerging Players: Airborne platform optical retrofits for high-altitude relay aircraft represent the most penetrable entry point, with stabilized beam tracking requirements creating specification barriers lower than space qualification. EU Space Programme Agency funding channels for European secure connectivity initiatives offer procurement access independent of SpaceX-dominated commercial economics. Target defense-adjacent research organizations with quantum key distribution pilot programs as reference customers. For Investors and Strategic Acquirers: Specialized optical terminal manufacturers with demonstrated space qualification heritage and existing NATO defense contracting relationships offer the strongest acquisition profile for portfolio exposure to sovereign encryption spending. Long-term viability hinges on vendor consolidation as availability-based contracts displace unit sales and transfer operational complexity to manufacturers. Watch for FCC licensing backlogs as an early signal of demand inflection exceeding supply response capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integration Investment | Single-chip coherent detection architectures from Ball Corporation collapse discrete component supply chains. |
| Indium Phosphide Foundry Acquisition | Captive laser diode production insulates Mynaric AG against allocation risk from limited geographies. |
| Long-Term Service Agreement Restructuring | Availability-based contracts transfer orbital replacement risk to Thales Alenia Space manufacturing operations. |
| Quantum Key Distribution Pilot Expansion | EU Space Programme Agency funding opens procurement channels for financial infrastructure operators. |
| REACH-Compliant Coating Process Qualification | Alternative deposition methods preserve German production cluster access to institutional programs. |
Research Approach
A standing panel of satellite procurement directors at constellation operators, laser communication terminal engineering leads, defense agency program managers, and FCC licensing specialists provided ongoing calibration across the study period. Primary interviews combined with secondary validation from SEC filings, ITU-R recommendation documents, EU Space Programme Agency procurement disclosures, and customs records for indium phosphide substrate trade flows. Bottom-up terminal shipment estimates triangulated against top-down defense budget allocation analysis.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, technology readiness level, application mission class, and end-user procurement channel. CAGRs derived from terminal replacement cycle modeling and constellation deployment schedules. Industry-specific forecast inputs included NATO secure connectivity mandate implementation timelines and FCC licensing throughput capacity assumptions.
Practitioners should monitor indium phosphide foundry allocation decisions, REACH substance restriction enforcement actions, and debris mitigation rule revisions for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Communications Service Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
Reconnaissance Satellite Market
Satellite
Satellite Parts and Components Market
Satellite
Satellite Signal Meter Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
Satellite Backhaul Market
Satellite
M2M Satellite Communication Market
Satellite
LEO and GEO Satellite Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
Broadband Satellite System Market
Satellite
Satellite Launch Vehicle (SLV) Market
Satellite
Middle East Satellite Imagery Services Market