
 Global Flight Navigation System Market | 2026-2036
Global Flight Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flight Navigation System Market Intelligence
The market's end-use composition is pivoting away from a sole focus on commercial aviation towards the rapidly expanding UAVs and general aviation segments. Honeywell International Inc. leverages its extensive portfolio to serve both legacy and emerging aircraft platforms. Thales Group differentiates through its strong position in air traffic management solutions and satellite-based systems. Meanwhile, Garmin Ltd. specializes in integrated flight decks for the general aviation and light jet markets.
A flight navigation system is an integrated suite of avionics that calculates and displays an aircraft's position, orientation, and velocity. These systems rely on inputs from multiple sources, such as inertial measurement units (IMUs) and GNSS receivers, to ensure a positional accuracy often within a few meters. Satellite-Based Navigation, including GPS and Galileo technologies, represents the core of modern systems due to its precision and global coverage. Inertial Navigation Systems remain a critical product type, providing autonomous navigation redundancy in environments where satellite signals are unavailable or compromised.
Compliance with stringent airworthiness standards from regulators like the US Federal Aviation Administration (FAA) is mandatory for market entry in North America. In parallel, adherence to European CE marking requirements and the globally recognized ISO 9100 standard governs component quality and system interoperability across supply chains. Future system development will hinge on integrating multi-constellation GNSS capabilities while meeting evolving cybersecurity protocols for connected aircraft.
Market Dynamics
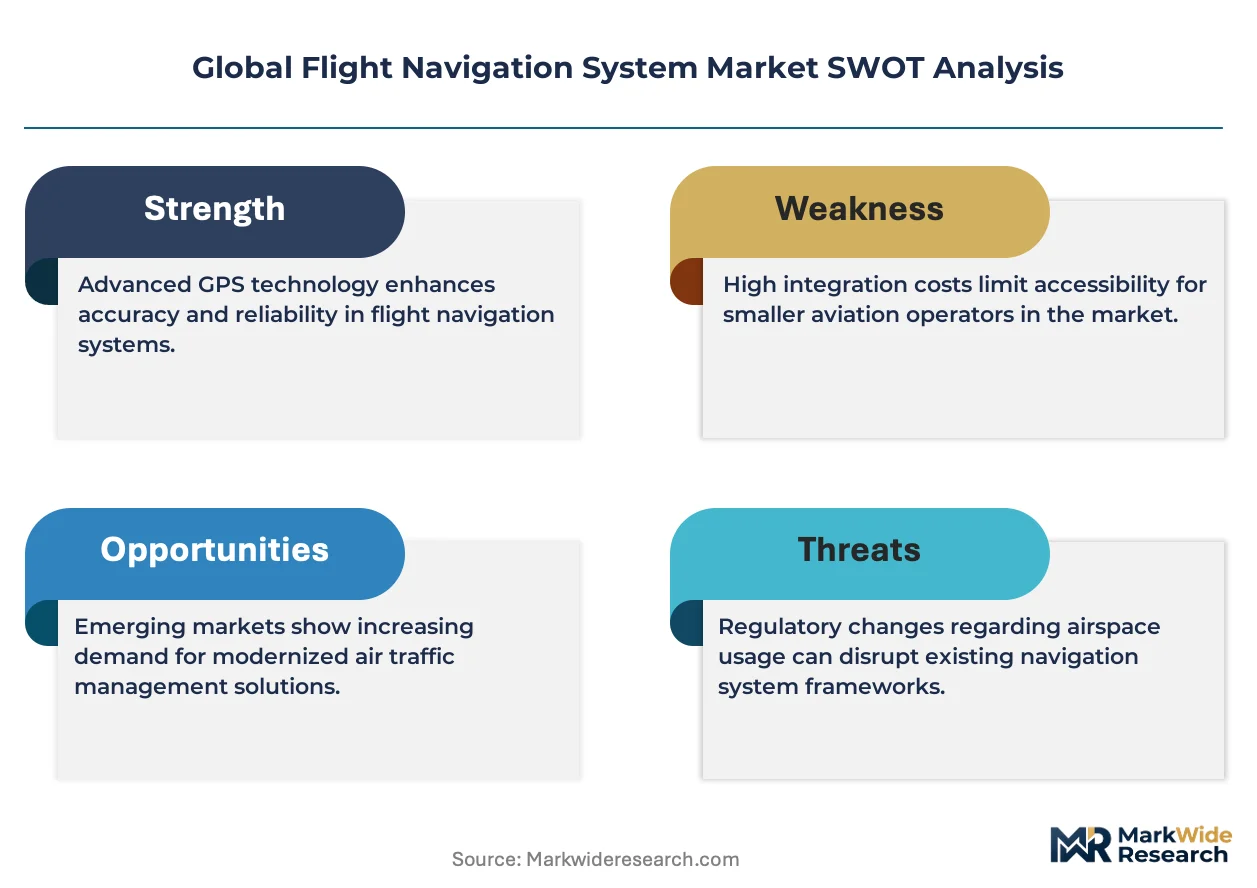
The mandatory global transition toward Performance-Based Navigation (PBN) protocols serves as the central structural force shaping the market. This shift compels aircraft operators to invest in upgraded or new navigation systems to meet airspace efficiency and capacity requirements.
Growth Catalysts
- UAV Proliferation:The rapid expansion of the Unmanned Aerial Vehicle sector for logistics and surveillance applications creates substantial demand for miniaturized, high-precision navigation systems capable of operating in complex, low-altitude environments.
- Airspace Modernization in China:Large-scale investment in new airport infrastructure and air traffic management modernization programs across China generates concentrated demand for advanced flight navigation systems for both new aircraft and ground control stations.
- PBN Mandates:Regulatory requirements from bodies like the International Civil Aviation Organization (ICAO) for PBN compliance force airlines worldwide to retrofit their fleets, sustaining a consistent upgrade cycle for navigation avionics.
Market Restraints
- Certification Costs:The high expense and long timelines associated with obtaining airworthiness certifications from regulators like the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) act as a significant barrier for new entrants.
- GNSS Vulnerabilities:The inherent susceptibility of Global Navigation Satellite System signals to intentional jamming and spoofing necessitates the integration of costly and complex inertial navigation systems for redundancy, increasing overall system price.
- Component Concentration:A reliance on a limited number of suppliers for critical components like high-performance inertial measurement units (IMUs) and radiation-hardened processors exposes the supply chain to potential bottlenecks and price volatility.
Strategic Opportunities
- Urban Air Mobility (UAM):Developing specialized navigation systems for electric vertical take-off and landing (eVTOL) aircraft presents a new market, requiring solutions tailored for high-density, automated urban airspace operations.
- Multi-Constellation GNSS Integration:Incorporating receivers that can process signals from multiple satellite constellations, including GPS, Galileo, and BeiDou, offers a path to improved positional accuracy, reliability, and service availability for end-users.
- Subscription-Based Services:Offering navigation database updates, cybersecurity monitoring, and predictive maintenance analytics as a recurring subscription service provides a new revenue stream beyond the initial hardware sale and fosters long-term customer relationships.
Industry Challenges
- Legacy System Integration:The engineering complexity and cost of integrating modern, PBN-compliant navigation systems with older, disparate avionics and autopilot systems in aging aircraft fleets pose a significant challenge for retrofit projects.
- Cybersecurity Threat Mitigation:Ensuring the security of connected aircraft and their navigation systems against evolving cyber threats requires continuous software updates and adherence to new security standards, increasing lifecycle management costs.
- Specialized Talent Scarcity:A shortage of software engineers with expertise in safety-critical avionics development, particularly with knowledge of standards like DO-178C, constrains the industry's capacity for innovation and product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flight Navigation System Market |
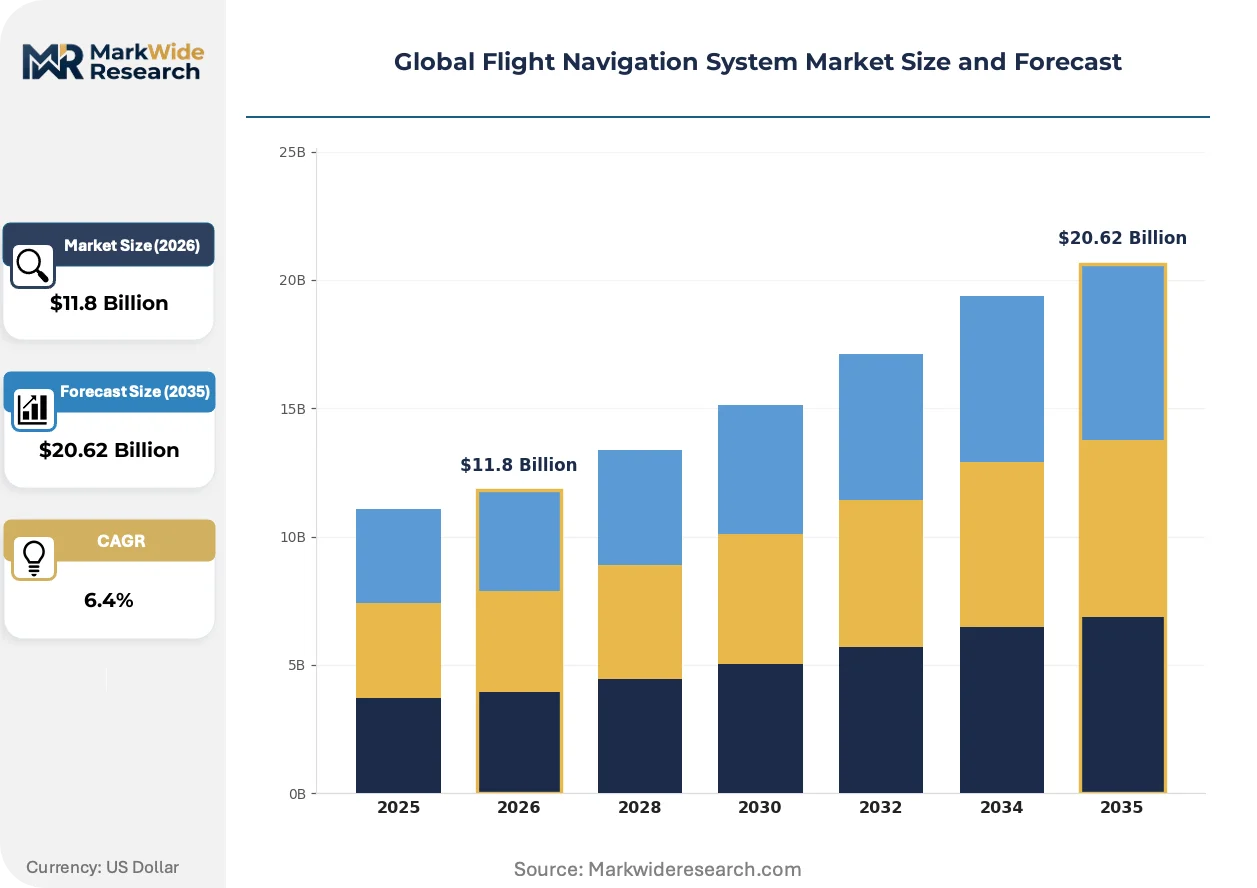
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inertial Navigation System, Satellite-Based Navigation, Radio Navigation, Magnetic Navigation, Visual Navigation, Others Technology: GPS, GLONASS, Galileo, BeiDou, ADS-B, VOR Application: Commercial Aviation, Military Aviation, UAVs, General Aviation, Cargo Aircraft, Air Traffic Management End User: Airlines, Defense Forces, Drone Operators, Corporate Aviation, Freight Carriers, Air Navigation Service Providers |
| Companies Covered | Honeywell International Inc., RTX Corporation, Thales Group, Northrop Grumman Corporation, Garmin Ltd., BAE Systems plc, Leonardo S.p.A., L3Harris Technologies Inc., Safran S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flight Navigation System Market Strategic Shifts & Innovations
The convergence of satellite-based positioning with autonomous control logic is fundamentally altering system architectures. This evolution prioritizes data integrity and multi-sensor redundancy to support increasingly automated flight operations across commercial, general, and unmanned aviation.
Sensor fusion technology combines inputs from GNSS receivers, Inertial Measurement Units (IMUs), and sometimes vision-based systems to produce a single, robust position and velocity solution. The unmanned and advanced air mobility sectors are rapidly adopting this approach to enable safe operations in signal-degraded environments. This fusion is automating critical navigation and collision avoidance functions, reducing pilot workload.
Mandates from the US Federal Aviation Administration (FAA) regarding its NextGen modernization program, particularly for Automatic Dependent Surveillance–Broadcast (ADS-B) Out, are driving technology adoption. This policy requires aircraft to broadcast their precise position, which improves situational awareness for air traffic control. The general aviation segment is most impacted, creating a large retrofit market for compliant avionics to maintain access to controlled airspace.
A demand-side shift toward fully integrated flight decks, rather than individual standalone navigation instruments, is apparent in new aircraft production. This pattern disrupts the traditional model of selling separate avionics boxes, favoring suppliers who offer a complete, pre-certified cockpit solution. This preference is most visible in the business and light jet markets, where airframe manufacturers seek to simplify supply chains.
Global Flight Navigation System Market Segmentation
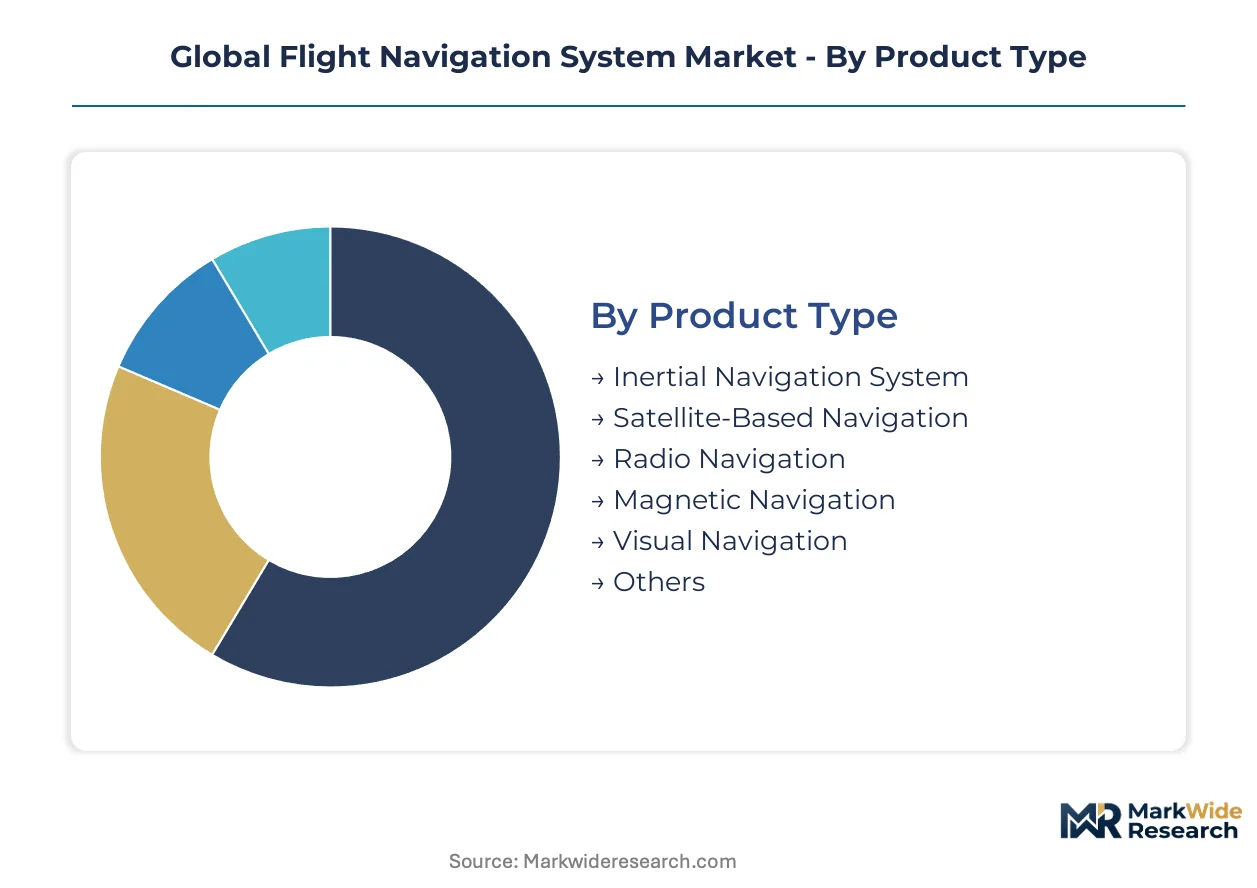
The Global Flight Navigation System Market is analyzed across critical dimensions to understand the diverse demands and technological preferences shaping its trajectory. Different segments exhibit unique requirements for precision, reliability, and integration, influencing product development and market penetration strategies.
Product Type:
Buyers in the flight navigation system market differentiate their product choices based on required autonomy, environmental resilience, and precision levels.
- Inertial Navigation System:Provides autonomous navigation redundancy using accelerometers and gyroscopes, critical in environments where satellite signals are unavailable or compromised. Demand is strong in military platforms and high-end commercial aircraft for operational security.
- Satellite-Based Navigation:Represents the core of modern systems, leveraging constellations like GPS and Galileo for high-precision positional data and global coverage. Demand concentrates in commercial aviation due to PBN mandates and in UAVs for accurate logistics operations.
- Radio Navigation:Utilizes ground-based beacons and signals for guidance, primarily serving as a backup or for specific approach procedures in general aviation.
- Magnetic Navigation:Employs Earth's magnetic field for heading reference, offering a simple, independent navigation aid, particularly in smaller aircraft.
- Visual Navigation:Relies on pilot observation of external landmarks and maps, fundamental for general aviation and low-altitude UAV operations.
- Others:Includes advanced sensor fusion systems and emerging quantum-based navigation solutions, targeting niche applications requiring extreme accuracy.
Satellite-Based Navigation leads volumes today; Inertial Navigation System is gaining share fastest.
Technology:
Technology adoption within flight navigation systems is largely driven by the specific operational requirements of various aircraft platforms and airspace regulations.
- GPS:The foundational Global Navigation Satellite System, offering widespread positional data and established infrastructure for various aviation sectors. Demand is ubiquitous across commercial and general aviation due to its reliability and global availability.
- Galileo:Europe's independent GNSS, providing enhanced accuracy, signal integrity, and authentication services for safety-critical applications. Demand is increasing in European commercial fleets and high-precision UAV operations.
- GLONASS:Russia's GNSS constellation, offering an alternative or supplementary signal source, particularly for aircraft operating in northern latitudes.
- BeiDou:China's indigenous GNSS, providing robust coverage within the Asia-Pacific region, driving its adoption in Chinese domestic and military aircraft.
- ADS-B:Automatic Dependent Surveillance–Broadcast, a surveillance technology broadcasting aircraft position, crucial for airspace modernization and air traffic control.
- VOR:Very High Frequency Omnidirectional Range, a ground-based radio navigation system providing bearing information, serving as a critical backup.
Multi-constellation GNSS integration represents the steepest expansion trajectory, enhancing resilience and accuracy across all aviation sectors.
Application:
Customer types dictate navigation system specifications, with each segment prioritizing distinct performance characteristics and regulatory compliance.
- Commercial Aviation:Demands highly reliable, PBN-compliant systems for passenger transport and air carrier operations, integrating with advanced flight decks. Demand is driven by fleet upgrades and new aircraft deliveries in China and other growing markets.
- Military Aviation:Requires robust, jam-resistant, and secure navigation systems for defense and reconnaissance missions, often integrating advanced inertial platforms for resilience.
- UAVs:Requires miniaturized, low-power, and highly precise navigation solutions for autonomous flight and complex missions. Demand is surging for logistics, surveillance, and urban air mobility applications.
- General Aviation:Needs cost-effective, user-friendly navigation solutions for private pilots and smaller aircraft, with a focus on ease of installation.
- Cargo Aircraft:Utilizes navigation systems optimized for long-haul operations and efficient freight delivery, prioritizing reliability and fuel efficiency.
- Air Traffic Management:Leverages navigation data for airspace optimization and collision avoidance, integrating with ground-based surveillance systems.
Commercial Aviation holds the largest share, while UAVs are climbing the fastest due to their diverse operational expansion.
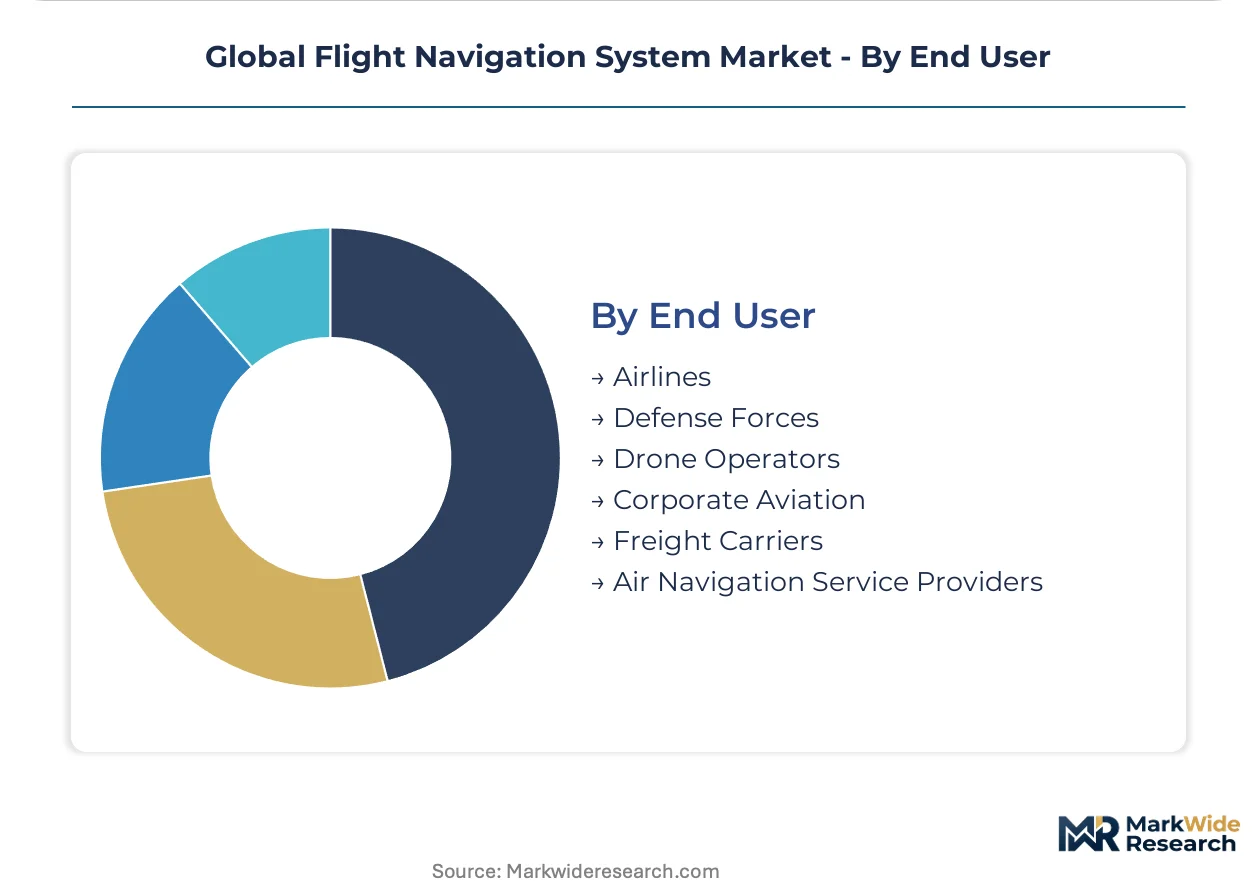
End User:
Volume and operational scale significantly influence the procurement decisions of end-users for flight navigation systems.
- Airlines:Procure advanced navigation suites for large commercial fleets, driven by PBN mandates and efficiency gains in global operations. Demand concentrates on integrated flight decks and multi-constellation GNSS solutions.
- Defense Forces:Demand highly secure, anti-jamming navigation systems for military aircraft and strategic platforms, often prioritizing resilience and stealth capabilities over cost.
- Drone Operators:Require compact, energy-efficient, and highly accurate navigation modules for diverse unmanned aerial vehicle applications. Demand is particularly high for logistics, agriculture, and infrastructure inspection services.
- Corporate Aviation:Seeks sophisticated, integrated navigation solutions for business jets, emphasizing passenger comfort and direct route efficiency.
- Freight Carriers:Invest in reliable navigation systems for their cargo fleets, focusing on on-time performance and optimized flight paths.
- Air Navigation Service Providers:Utilize navigation data and systems to manage airspace, ensure safety, and enhance air traffic flow efficiency.
Airlines represent the largest segment by procurement value, with Drone Operators showing the most significant expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence often influences market development, prompting manufacturers to optimize production and certification pathways. High compliance costs in certain regions can shift component sourcing or assembly to areas with more streamlined regulatory frameworks. This dynamic impacts the flight navigation system market by creating varied investment landscapes.
China
Large-scale investment in new airport infrastructure and air traffic management modernization programs drives demand for advanced flight navigation systems. The adoption of the indigenous BeiDou GNSS and adherence to national GB standards for avionics shape market entry. Shanghai and Beijing are centers for aviation manufacturing and air traffic control system integration.
United States
Significant military procurement and ongoing commercial fleet upgrades create consistent demand for sophisticated navigation solutions. US Federal Aviation Administration (FAA) mandates for NextGen modernization, particularly ADS-B Out, compel technology adoption. Seattle, Washington, and Wichita, Kansas, host major aerospace manufacturers driving system integration efforts.
Germany
Strong aerospace research and development, coupled with a focus on high-precision systems, support market expansion for commercial and defense applications. Adherence to European Union Aviation Safety Agency (EASA) standards and CE marking requirements governs product development. Munich and Hamburg are key hubs for avionics development and aircraft assembly operations.
India
Rapid expansion of domestic air travel and military modernization initiatives contribute to the rising demand for flight navigation systems. The Directorate General of Civil Aviation (DGCA) mandates for Performance-Based Navigation (PBN) protocols influence fleet upgrades. Bengaluru serves as a prominent center for aerospace research and development and manufacturing.
France
A robust defense sector procurement and a leading position in commercial aircraft manufacturing generate substantial demand for advanced navigation systems. Compliance with EASA airworthiness standards and active support for the Galileo satellite navigation system are critical. Toulouse, a major aerospace hub, drives innovation in integrated avionics solutions.
Global Flight Navigation System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. The flight navigation system market exhibits consolidation among established aerospace and defense contractors, while a fragmented ecosystem of niche providers serves specialized applications. Dominant archetypes include integrated avionics suppliers, satellite navigation system developers, and general aviation solution providers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Specialists in integrated flight systems include Honeywell International Inc., which leverages an extensive portfolio across legacy and emerging aircraft platforms, serving a broad customer base. Thales Group represents a strong position in air traffic management solutions and satellite-based systems, emphasizing differentiation through its comprehensive offerings for both civil and military applications. Garmin Ltd. exemplifies leadership in integrated flight decks for the general aviation and light jet markets, demonstrating a focus on user-friendly and cost-effective solutions for specific end-user segments. These firms anchor various tiers within the competitive landscape, each with distinct strategic focuses.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| RTX Corporation |
| Thales Group |
| Northrop Grumman Corporation |
| Garmin Ltd. |
| BAE Systems plc |
| Leonardo S.p.A. |
| L3Harris Technologies Inc. |
| Safran S.A. |
| Others |
Cost & Logistics Intelligence
Publicly traded aerospace and defense contractors, often with diverse portfolios, influence both supply chain stability and pricing discipline within the flight navigation system market. Their extensive R&D budgets and certification capabilities dictate component availability and system costs for smaller players and end-users.
Pricing Analysis
Direct-to-OEM discounts and long-term contract pricing dominate the market for integrated flight navigation systems. Value-based pricing is common for advanced solutions, reflecting high R&D investment and stringent certification requirements from bodies like the FAA and EASA. Price differentiation stems from multi-constellation GNSS capabilities and specific airworthiness certifications. Pricing pressure remains moderate due to the specialized nature of components and high barriers to entry. General aviation buyers exhibit the highest price sensitivity, while military procurement prioritizes performance over cost.
Supply Chain Analysis
Specialized logistics for sensitive avionics components, often requiring controlled environments, contribute significantly to overall system costs. Supply concentration for critical components primarily resides in the United States, Germany, and France. The supply chain draws from high-performance inertial measurement units (IMUs), GNSS chipsets, and radiation-hardened processors. Single-source vulnerability for these specialized inputs represents a structural risk. Distribution runs through direct sales channels to aircraft OEMs and airlines, with specialized avionics integrators handling retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, driven by a pervasive demand-shift toward premium specifications like multi-constellation GNSS and advanced sensor fusion for enhanced reliability.
For Market Incumbents: Anticipate continued investment in multi-constellation GNSS integration and robust cybersecurity solutions to counter evolving digital threats. Deepen partnerships with aircraft OEMs to secure long-term supply agreements for next-generation platforms. Acquire niche technology firms specializing in quantum sensing or advanced sensor fusion to maintain a competitive edge. Investment in next-generation sensor fusion remains a key lever.
For New Entrants and Emerging Players: Launch via subscription-based services for navigation data updates and predictive maintenance analytics to build recurring revenue streams. Target the rapidly expanding Unmanned Aerial Vehicle (UAV) and Urban Air Mobility (UAM) segments, which require miniaturized, low-power navigation solutions. Developing specialized navigation solutions for high-density, automated urban airspace operations represents a penetrable segment. Focus on rapid certification for specific low-altitude applications.
For Investors and Strategic Acquirers: Valuations sit cheapest among traditional aerospace component suppliers with strong intellectual property in core navigation technologies. The market offers long-term viability, essential for global air traffic modernization and the proliferation of autonomous aircraft. Acquisition targets should include specialized sensor fusion developers and firms with expertise in AI-driven navigation algorithms. Regulatory approvals for Urban Air Mobility operations serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation GNSS Integration | Enhances reliability and accuracy for safety-critical commercial aviation operations. |
| Cybersecurity Protocol Development | Secures connected aircraft systems against evolving digital threats. |
| UAV-Specific System Miniaturization | Addresses demand from logistics and surveillance applications in complex environments. |
| PBN Compliance Certification | Enables airlines to meet global airspace efficiency and capacity mandates. |
| Sensor Fusion Technology Investment | Improves autonomous navigation capabilities in signal-degraded environments. |
Research Approach
Bottom-up UAV and commercial aviation end-use modeling reconciled against top-down avionics manufacturer and component supplier tracking forms the analytical core of this study. Primary interviews with avionics engineers, airline procurement heads, air traffic control specialists, and drone fleet operators informed qualitative insights. Secondary validation drew from FAA and EASA airworthiness directives, ICAO standards, aerospace industry reports, and company financial filings.
Historical trendline analysis of market volume and value across the analysis window established the baseline for projections. The forecast framework modeled segmentation across product type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates were derived through a synthesis of historical performance and anticipated technological advancements. PBN mandate compliance rates and UAV market growth projections served as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including specific military classified programs and rapid quantum navigation breakthroughs. The forecasts reflect assumptions regarding regulatory stability and technological evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Air Traffic Management Software Market