
 Europe Intelligence Surveillance and Reconnaissance Market | 2026-2036
Europe Intelligence Surveillance and Reconnaissance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Intelligence Surveillance and Reconnaissance Market Foresight
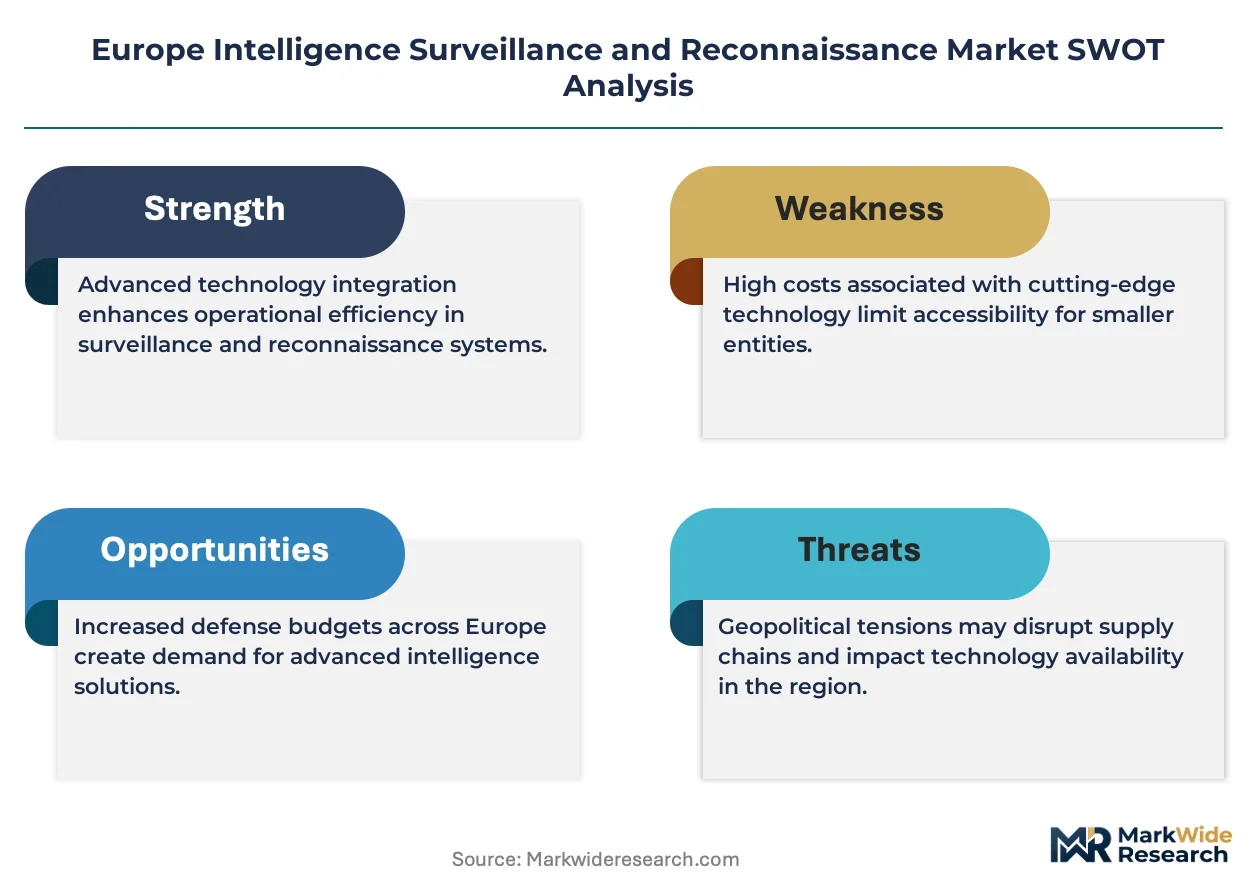
The capability gap between full-spectrum platform providers and sensor-specialist suppliers is redrawing competitive boundaries across Europe. BAE Systems leverages sovereign British manufacturing to sustain integrated naval-air ISR programs. Thales anchors Franco-European satellite and signals-intelligence architectures through its Paris-based defense electronics division. Rheinmetall AG competes in ground-based sensor networks with a focus on Baltic-border surveillance infrastructure.
Intelligence Surveillance and Reconnaissance denotes the integrated collection, processing, and dissemination of timely, accurate, and relevant information to support decision-making across military and security operations, typically involving multi-spectral sensors operating across 0.4–14 micrometer wavelengths with real-time data fusion at edge-computing nodes. Unmanned Aerial Vehicles dominate procurement volumes as European militaries replace manned reconnaissance flights with persistent-drone orbits over contested airspace. AI-Powered Analytics commands the fastest expansion trajectory, with image-recognition algorithms reducing analyst workload in border-security applications. Satellite Systems retain the deepest margin pools due to sovereign launch infrastructure and restricted technology-transfer regimes.
The EU AI Act imposes strict conformity assessments on autonomous targeting algorithms, while CE marking under the Radio Equipment Directive governs spectrum compliance for cross-border datalinks. EDA coordination frameworks pool member-state R&D spending to reduce duplication in next-generation airborne early-warning platforms. Stakeholders must weigh national sovereignty requirements against collaborative procurement economics as multi-national programs face divergent threat-perception timelines.
Market Dynamics
The EU AI Act's risk-classification framework for autonomous defense systems is compressing procurement timelines as European militaries race to field compliant AI-powered ISR platforms before conformity assessment deadlines tighten.
Growth Catalysts
- EU AI Act compliance windows:The regulation's phased implementation for high-risk autonomous systems is pulling forward defense procurement cycles. Member-state militaries are accelerating platform acquisitions to secure grandfathered operational status.
- Baltic-border surveillance infrastructure:NATO's eastern flank states are deploying persistent ground-sensor networks. Estonian and Latvian defense ministries have issued successive tenders for multi-spectral border monitoring arrays.
- Multi-domain situational awareness mandates:National defense modernization programs in Germany, France, and the United Kingdom are fusing naval, air, and space ISR architectures into unified command systems.
Market Restraints
- Gallium and germanium supply concentration:Export controls on critical semiconductor substrate materials from China are constraining infrared sensor foundry capacity across European defense electronics suppliers.
- Sovereign launch infrastructure bottlenecks:Restricted access to Ariane 6 slots and limited European heavy-lift alternatives are extending satellite constellation deployment timelines for signals-intelligence programs.
- Cross-border datalink spectrum fragmentation:Divergent national implementations of CE marking under the Radio Equipment Directive are creating interoperability gaps in multinational NATO ISR exercises.
Strategic Opportunities
- Polish defense modernization acceleration:Warsaw's procurement authority has unbundled legacy Soviet-era reconnaissance systems, creating entry points for NATO-standard sensor integrators in ground-based radar and signals intelligence.
- AI-edge computing convergence with 5G military networks:The European Defence Agency's pooled R&D frameworks are funding trials combining low-latency tactical datalinks with onboard neural processing for real-time target recognition.
- Swedish-Finnish Arctic ISR corridors:NATO accession protocols are unlocking joint funding for polar-orbiting synthetic aperture radar constellations covering Greenland-Iceland-UK gaps.
Industry Challenges
- AI systems engineering talent scarcity:Defense contractors in France and Germany are competing with civilian technology firms for machine-learning specialists cleared to handle classified training datasets.
- Legacy platform integration complexity:Eurofighter Typhoon and Rafale fleets require certified middleware to ingest real-time drone feeds, extending software qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Intelligence Surveillance and Reconnaissance Market |
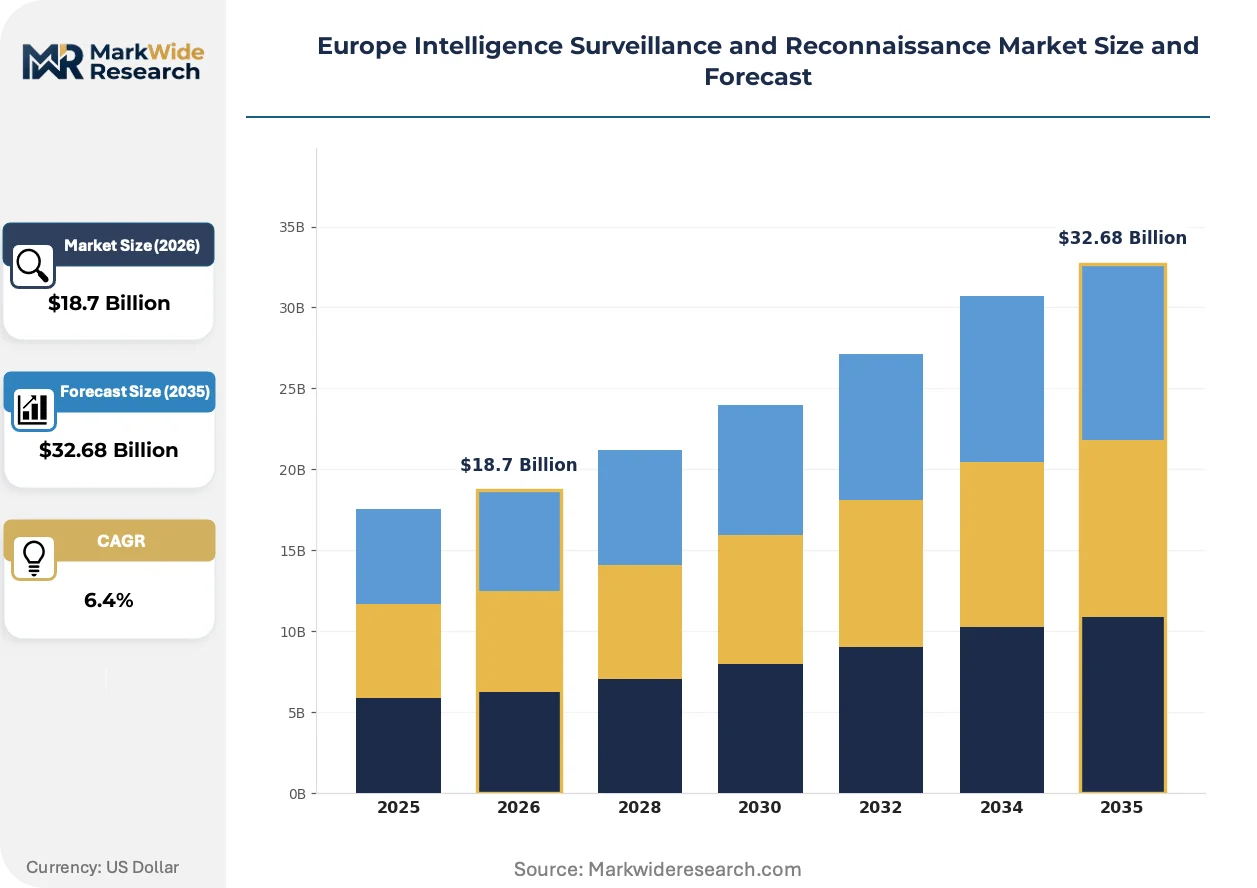
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unmanned Aerial Vehicles, Ground Surveillance Radars, Satellite Systems, Electro-Optical Sensors Technology: AI-Powered Analytics, Image Recognition, IoT Connectivity, Advanced Communication Systems Application: Border Security, Urban Surveillance, Battlefield Management, Disaster Response End User: Military Agencies, Government Organizations, Private Security Firms, Law Enforcement |
| Companies Covered | BAE Systems plc, L3Harris Technologies, Inc., Thales, Rheinmetall AG, Leonardo S.p.A., General Dynamics Corporation, The Boeing Company, Elbit Systems Ltd., Saab AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Intelligence Surveillance and Reconnaissance Market Shifts & Advancements
Active electronically scanned array radars paired with machine-learning target classifiers are compressing the sensor-to-shooter loop. European procurement authorities are rewriting technical specifications to mandate open architecture standards that prevent vendor lock-in across multi-decade platform lifecycles.
Hyperspectral imaging payloads operating across 0.4–2.5 micrometer wavelengths are supplanting traditional electro-optical/infrared sensors in high-altitude drone programs. The French Direction Générale de l'Armement has specified hyperspectral requirements for its next-generation Patroller replacement. This shift is enabling sub-pixel material identification for camouflage detection and chemical signature tracking, collapsing the distinction between strategic and tactical reconnaissance missions.
The EU AI Act's conformity assessment procedures for autonomous targeting algorithms are forcing defense electronics divisions to restructure software development workflows. Thales and BAE Systems have established dedicated algorithmic audit trails to satisfy notified body requirements for high-risk AI systems. Satellite-based autonomous navigation aids face the steepest compliance burden, with cross-border datalink protocols requiring bilateral equivalence agreements between national regulators.
Defense ministries are consolidating ISR procurement through framework contracts rather than discrete platform acquisitions. The UK Defence Equipment and Support organization has moved to five-year managed service agreements for intelligence analysis, transferring analyst workforce costs to prime contractors. This restructuring is most advanced in maritime patrol and border security verticals, where Royal Air Force P-8 Poseidon operations already blend military crews with contractor-maintained sensor suites.
Europe Intelligence Surveillance and Reconnaissance Market Segmentation
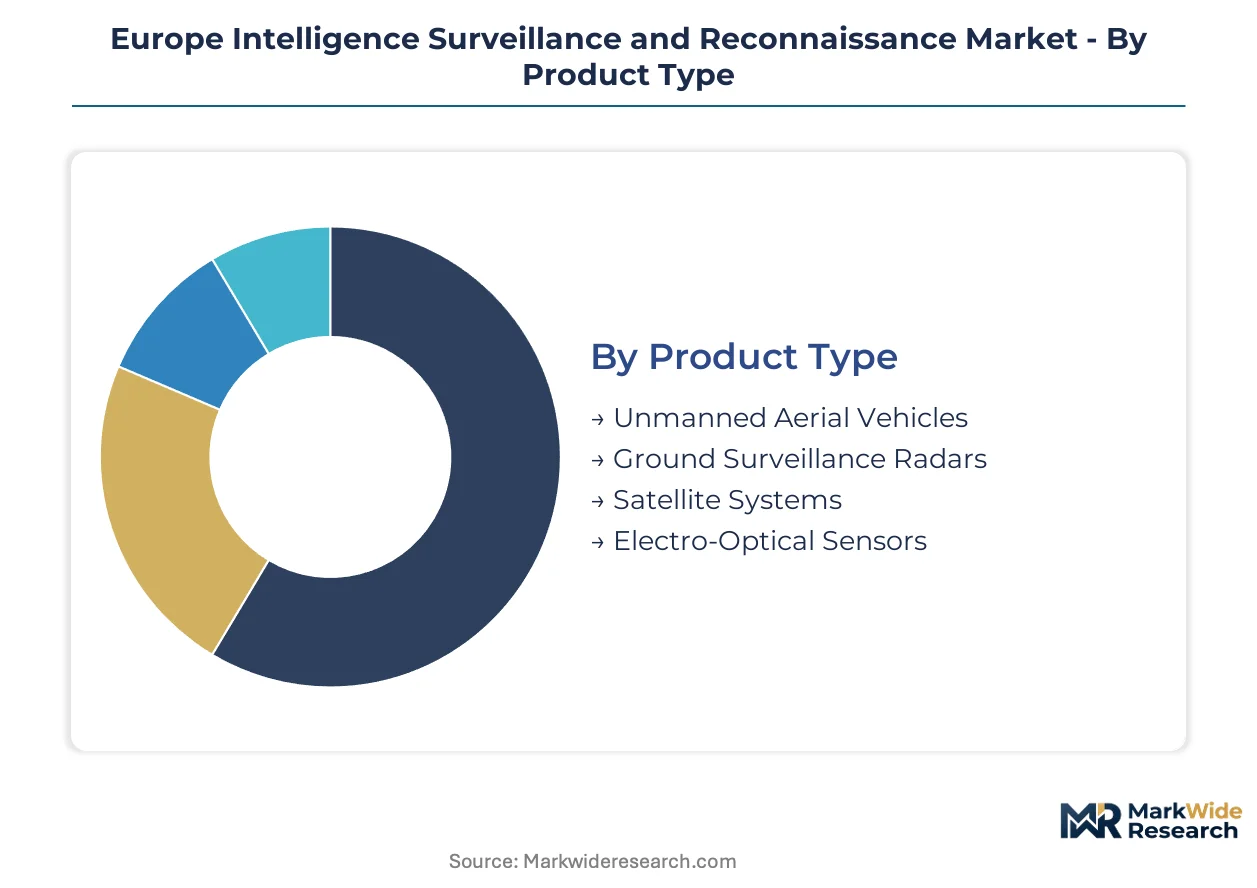
ISR procurement channels diverge sharply by capability maturity and sovereign control requirements. Military agencies route classified programs through national defense procurement offices, while dual-use technologies increasingly flow via framework contracts with managed service obligations.
Product Type:
Channel mix varies by platform complexity — unmanned systems and ground radars move through competitive tender processes, while satellite programs require bilateral government-to-government negotiations.
- Unmanned Aerial Vehicles:Persistent-drone orbits with multi-spectral sensor payloads dominate procurement volumes. French and German defense ministries are replacing manned reconnaissance flights with certified unmanned platforms for contested airspace operations.
- Satellite Systems:Sovereign launch infrastructure and restricted technology-transfer regimes protect margin pools. British and French signals-intelligence constellations face deployment delays due to Ariane 6 slot constraints.
- Ground Surveillance Radars:Active electronically scanned array systems with machine-learning target classifiers anchor Baltic-border infrastructure. Estonian and Latvian tenders specify multi-spectral monitoring arrays.
- Electro-Optical Sensors:Infrared and visible-spectrum imagers operating across 0.4–14 micrometer wavelengths integrate into layered ISR architectures.
Unmanned Aerial Vehicles dominate installed base. Satellite Systems is where expansion concentrates.
Technology:
Cost tier stratification separates proven mission-systems software from experimental AI layers requiring conformity assessment.
- AI-Powered Analytics:Image-recognition algorithms reducing analyst workload in border-security applications are climbing the fastest. Thales and BAE Systems have established dedicated algorithmic audit trails to satisfy EU AI Act notified body requirements.
- Image Recognition:Neural processing for real-time target recognition combines with 5G military networks in EDA-funded trials. Edge-computing nodes compress sensor-to-shooter loops.
- Advanced Communication Systems:Cross-border datalinks governed by CE marking under the Radio Equipment Directive face spectrum fragmentation in multinational NATO exercises.
- IoT Connectivity:Sensor mesh networks for persistent ground surveillance integrate tactical edge nodes with command infrastructure.
Image Recognition dominates installed base. AI-Powered Analytics is where expansion concentrates.
Application:
Volume concentration tracks threat perception timelines — eastern flank states prioritize border infrastructure while western European programs emphasize multi-domain fusion.
- Border Security:Multi-spectral monitoring arrays with hyperspectral imaging payloads enable sub-pixel material identification for camouflage detection. Polish defense modernization has unbundled Soviet-era reconnaissance systems.
- Battlefield Management:Unified command systems fusing naval, air, and space ISR architectures anchor German, French, and British modernization programs. Real-time data fusion requirements drive open architecture mandates.
- Urban Surveillance:Dense sensor networks for population-center monitoring face GDPR compliance constraints on data retention.
- Disaster Response:Dual-use drone fleets with rapid deployment protocols serve civil protection agencies under pooled EU mechanisms.
Battlefield Management dominates installed base. Border Security is where expansion concentrates.
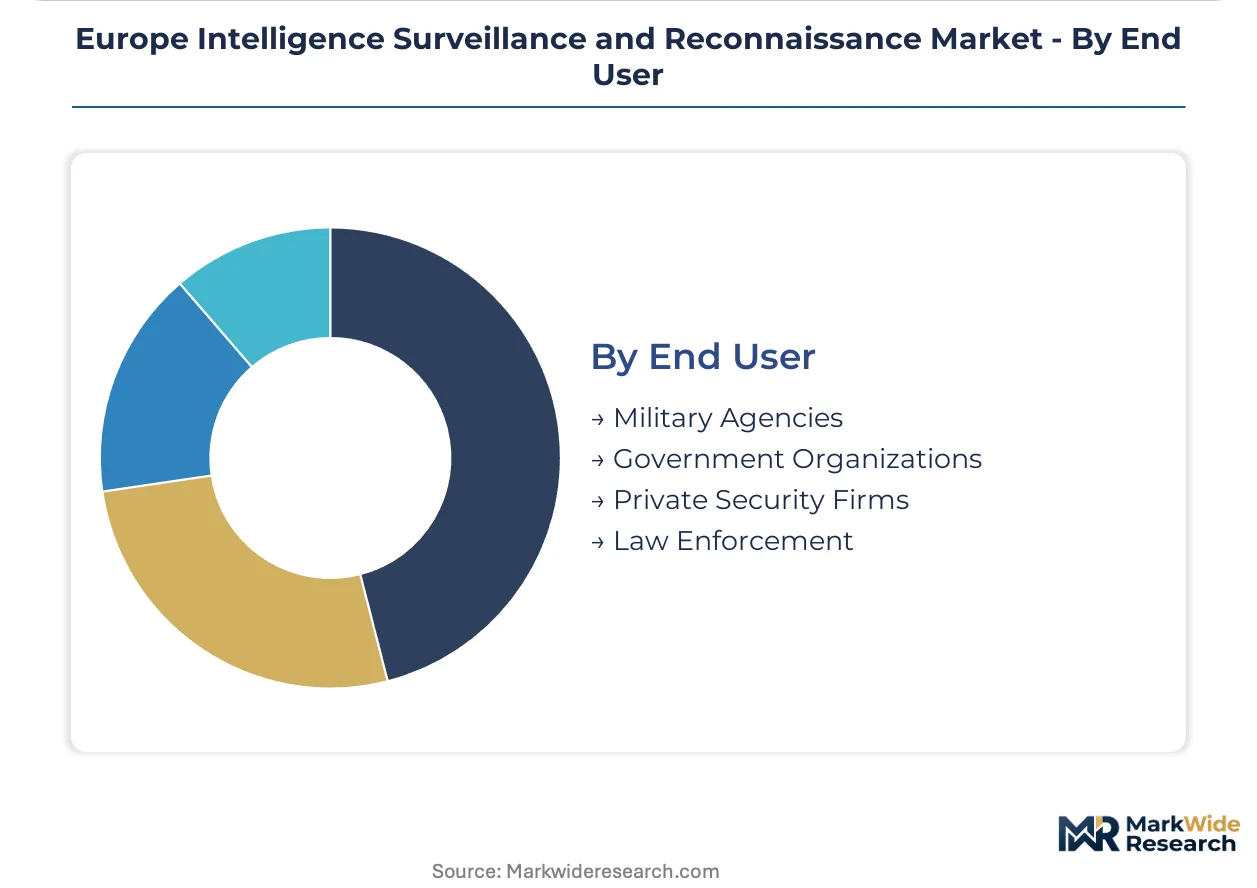
End User:
Customer type determines contract structure — military agencies retain sovereign control over source selection, while private security firms operate under stricter export licensing.
- Military Agencies:National defense procurement offices in Germany, France, and the United Kingdom prioritize multi-domain situational awareness. Framework contracts with five-year managed service agreements transfer analyst workforce costs to primes.
- Government Organizations:Civil intelligence services and coast guard authorities procure through separate budget lines with distinct security clearance requirements.
- Law Enforcement:Police-led surveillance programs face tighter judicial oversight and data protection impact assessments under national implementations of EU directives.
- Private Security Firms:Commercial operators are restricted to non-classified sensor tiers and dual-use platforms without cryptographic modules.
Military Agencies dominate installed base. Government Organizations is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baltic-border states exhibit the highest demand elasticity as procurement authorities prioritize rapid deployment over platform longevity, while France and the United Kingdom sustain premium pricing for sovereign satellite architectures with multi-decade service horizons.
Germany
Bundeswehr modernization programs are fusing naval, air, and space ISR architectures into unified command systems under the National Security Strategy. The EU AI Act's conformity assessment deadlines are compressing procurement cycles for autonomous targeting platforms. Bavaria-based defense electronics clusters around Munich anchor ground-sensor network development for Baltic-border surveillance infrastructure.
France
The Direction Générale de l'Armement has specified hyperspectral imaging requirements for next-generation Patroller replacements, collapsing strategic-tactical mission distinctions. CE marking under the Radio Equipment Directive governs cross-border datalink spectrum compliance for multinational NATO exercises. Paris-based Thales anchors Franco-European satellite and signals-intelligence architectures through sovereign launch infrastructure.
United Kingdom
UK Defence Equipment and Support has shifted to five-year managed service agreements for intelligence analysis, transferring analyst workforce costs to prime contractors. The UK Space Agency coordinates sovereign launch slot allocation for signals-intelligence constellations amid Ariane 6 bottlenecks. BAE Systems leverages sovereign British manufacturing to sustain integrated naval-air ISR programs from its Lancashire and Hampshire facilities.
Poland
Warsaw's procurement authority has unbundled legacy Soviet-era reconnaissance systems, creating entry points for NATO-standard sensor integrators in ground-based radar and signals intelligence. The Polish Ministry of National Defense operates under accelerated timelines to replace Eastern-origin equipment before EU AI Act grandfathering windows close. Poznań and Wrocław defense technology corridors are attracting foreign sensor specialists for border-security modernization.
Sweden
NATO accession protocols are unlocking joint funding with Finland for polar-orbiting synthetic aperture radar constellations covering Greenland-Iceland-UK gaps. The Swedish Defence Materiel Administration pools R&D spending through European Defence Agency frameworks to reduce duplication in airborne early-warning platforms. Linköping's aerospace cluster hosts Saab AB's development of next-generation electronic warfare and ISR fusion systems.
Europe Intelligence Surveillance and Reconnaissance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-spectrum platform providers commanding multi-domain program awards while sensor-specialist suppliers capture discrete subsystem contracts. The competitive terrain stratifies between sovereign manufacturing champions and multinational systems integrators. Three archetypes dominate: vertically integrated national champions with captive supply chains, cross-border consortium partners leveraging pooled R&D frameworks, and agile specialists in AI-edge computing or hyperspectral payloads. Consolidation pressure is intensifying through strategic partnerships for satellite constellation deployment and technology licensing for algorithmic audit trails.
Among British and French integrated primes, BAE Systems plc and Thales exemplify the sovereign manufacturing archetype, anchoring national naval-air and satellite-signals programs respectively. Rheinmetall AG occupies a specialist position within the ground-sensor tier, with its German engineering base aligned to Baltic-border infrastructure demand. These three entities represent distinct competitive vectors: platform integration, space-based architectures, and terrestrial sensor networks.
| Leading Market Players |
|---|
| BAE Systems plc |
| L3Harris Technologies, Inc. |
| Thales |
| Rheinmetall AG |
| Leonardo S.p.A. |
| General Dynamics Corporation |
| The Boeing Company |
| Elbit Systems Ltd. |
| Saab AB |
| Others |
Supply & Pricing Matrix
CE marking under the Radio Equipment Directive gates both supplier qualification and price differentiation simultaneously, as cross-border datalink certification costs stratify vendors into compliant prime contractors and excluded specialist tiers. This regulatory filter concentrates pricing power with sovereign manufacturers who absorb conformity overhead into multi-year managed service agreements.
Pricing Analysis
After-sales service contracts and algorithmic audit trail maintenance drive lifetime value beyond initial platform acquisition. Three-tier pricing structure across premium sovereign-integrated, standard NATO-interoperable, and economy dual-use levels separates BAE Systems and Thales from Baltic-border specialist suppliers. Price differentiation rests on EU AI Act conformity certification and sovereign launch infrastructure access. Cost compression in sensor-specialist tiers is intensifying because export controls on gallium and germanium are constraining infrared foundry capacity. Eastern flank defense ministries exhibit highest price sensitivity; British and French satellite programs show lowest sensitivity due to multi-decade sovereignty mandates.
Supply Chain Analysis
Extended lead times for Ariane 6 launch slots and certified neural processor chips are forcing inventory pre-positioning among prime contractors. Geographic supply concentrates in Germany for ground-sensor arrays, France for satellite payloads, and the United Kingdom for naval-air integration platforms. Raw material dependencies center on gallium arsenide substrates, germanium infrared optics, and radiation-hardened semiconductors. Single-source vulnerability runs through Chinese-controlled critical mineral refining. Distribution runs through national defense procurement offices with framework contract consolidation accelerating.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from procurement cycle compression as EU AI Act grandfathering deadlines pull forward platform acquisitions. Defense modernization program restarts across NATO's eastern flank provide the cyclical impetus.
For Market Incumbents: Consolidate algorithmic audit trail capabilities and sovereign launch slot reserves to defend against Polish and Baltic specialist entrants. Thales and BAE Systems should deepen backward integration into radiation-hardened semiconductor sourcing. Capture EDA pooled R&D coordination to lock out consortium competitors from next-generation airborne early-warning platforms.
For New Entrants and Emerging Players: EU AI Act fast-track certification for high-risk autonomous targeting systems offers entry into British and French managed service agreements. White-space targets include Polish ground-based radar modernization and Swedish-Finnish Arctic ISR corridor sensor networks. Position as algorithmic compliance specialists for prime contractor subcontracting.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across satellite constellation deployment as Ariane 6 bottlenecks extend financing horizons. Long-term viability favors vertically integrated primes with captive sovereign launch access over sensor-specialist suppliers. Acquisition target archetype: AI-edge computing firms with cleared personnel for classified training datasets. Signal to watch: bilateral equivalence agreements between national regulators for cross-border datalink protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Audit Trail Investment | EU AI Act conformity certification enables participation in French and British managed service frameworks. |
| Sovereign Launch Slot Reservation | Ariane 6 access secures multi-year deployment timelines for signals-intelligence constellations. |
| EDA Pooled R&D Participation | European Defence Agency coordination reduces duplication costs in airborne early-warning development. |
| Hyperspectral Payload Integration | Direction Générale de l'Armement specifications for Patroller replacement collapse strategic-tactical mission boundaries. |
| Polish Defense Corridor Establishment | Poznań and Wrocław technology clusters capture Warsaw's Soviet-era system replacement demand. |
Research Methodology
A spread of perspectives from defense procurement officers, satellite systems engineers, algorithmic compliance specialists, and EDA program coordinators converged on the working assumptions. Primary interviews with Bundeswehr modernization planners, Direction Générale de l'Armement technical directors, and UK Defence Equipment and Supply framework contract managers combined with secondary validation against EDA coordination documents, national defense white papers, and EU AI Act implementation guidance. Bottom-up platform deployment estimates and top-down defense budget allocation analysis provided triangulation.
Segmentation dimensions modeled include product type, technology layer, application vertical, and end-user category across the projection horizon. Unmanned aerial vehicle procurement volumes, satellite constellation deployment timelines, and AI-powered analytics adoption curves informed analytical framework construction. CAGRs were derived from defense budget trajectory analysis and platform replacement cycle assessment.
Decision-makers should treat outputs as directional under assumptions of sustained NATO eastern flank threat perception and EU AI Act implementation adherence; material deviation in regulatory timelines or alliance posture would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
UXO Detection Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
Military Radar Market
Military Surveillance
Manportable Radar Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Laser Telemetry Binoculars Market