
 Linear Particle Accelerators Market | 2026-2036
Linear Particle Accelerators Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Particle Accelerators Market Outlook
The capital-intensity divergence between superconducting and normal-conducting system manufacturers is reorganizing competitive tiers in the Linear Particle Accelerators Market. Siemens Healthineers leverages its integrated imaging-to-therapy platform to anchor hospital procurement decisions across European and North American installations. Varian Medical Systems sustains dominance in proton therapy through dedicated cyclotron and synchrotron supply chains. IBA specializes in compact single-room proton systems that compete for limited hospital capital budgets against multi-room footprints.
Linear particle accelerators are electromagnetic devices that propel charged particles along a straight beamline using oscillating radiofrequency fields, achieving beam energies from MeV to GeV ranges depending on application requirements. These systems generate ionizing radiation for tumor destruction in oncology, produce synchrotron light for materials characterization, or drive neutron sources for industrial imaging. Proton accelerators command premium positioning in cancer treatment due to superior dose deposition profiles compared to photon alternatives. Electron accelerators occupy mature industrial sterilization and medical imaging segments with stable replacement cycles. Superconducting technology represents the fastest-growing technology category as niobium-titanium cryomodules reduce RF power consumption and enable continuous-wave operation.
FDA clearance pathways for new radiation therapy modalities shape product development timelines and clinical trial requirements for manufacturers targeting United States installations. CE marking under the EU Medical Device Regulation and compliance with IEC 60601-2-1 standards govern market access across European clinical environments. The International Atomic Energy Agency safety standards influence national licensing frameworks for nuclear facility installations in member states. Stakeholders must monitor evolving reimbursement decisions for proton therapy across Medicare and major European health systems to align capital deployment with payer acceptance trajectories.
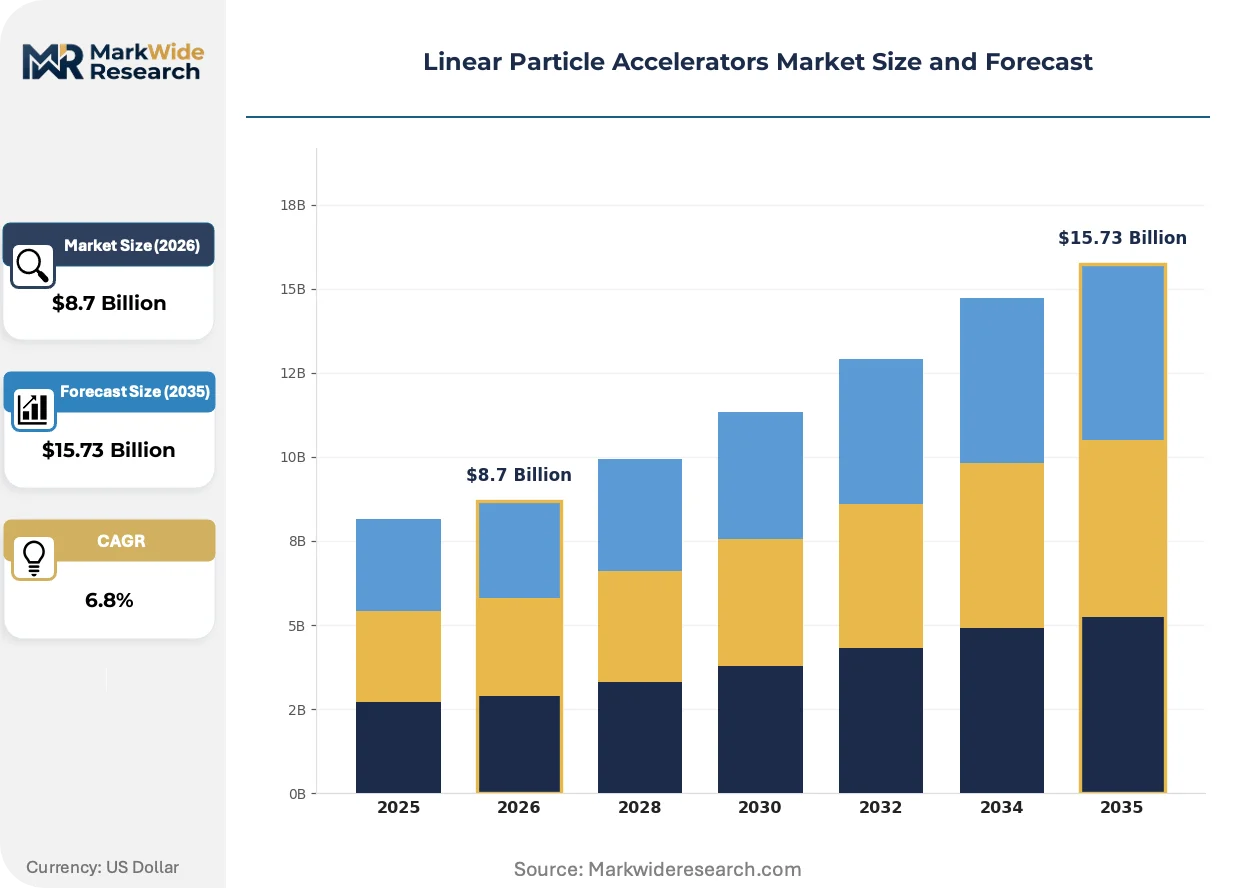
Market Dynamics
Superconducting niobium-titanium cryomodules are compressing operational energy thresholds and enabling continuous-wave proton beam delivery, forcing capital allocation decisions between conventional copper-cavity systems and next-generation superconducting architectures across major cancer treatment centers.
Growth Catalysts
- Proton Therapy Reimbursement Evolution:Medicare coverage determinations for intensity-modulated proton therapy in the United States are expanding eligible patient populations and validating hospital capital investments.
- Superconducting RF Technology:Niobium-titanium cryomodules reduce RF power consumption by enabling higher quality factors, lowering total cost of ownership for continuous clinical operation.
- Germany's Heavy Research Infrastructure:Helmholtz Association facilities and university hospital networks sustain procurement pipelines for high-energy physics and clinical dual-use accelerators.
Market Restraints
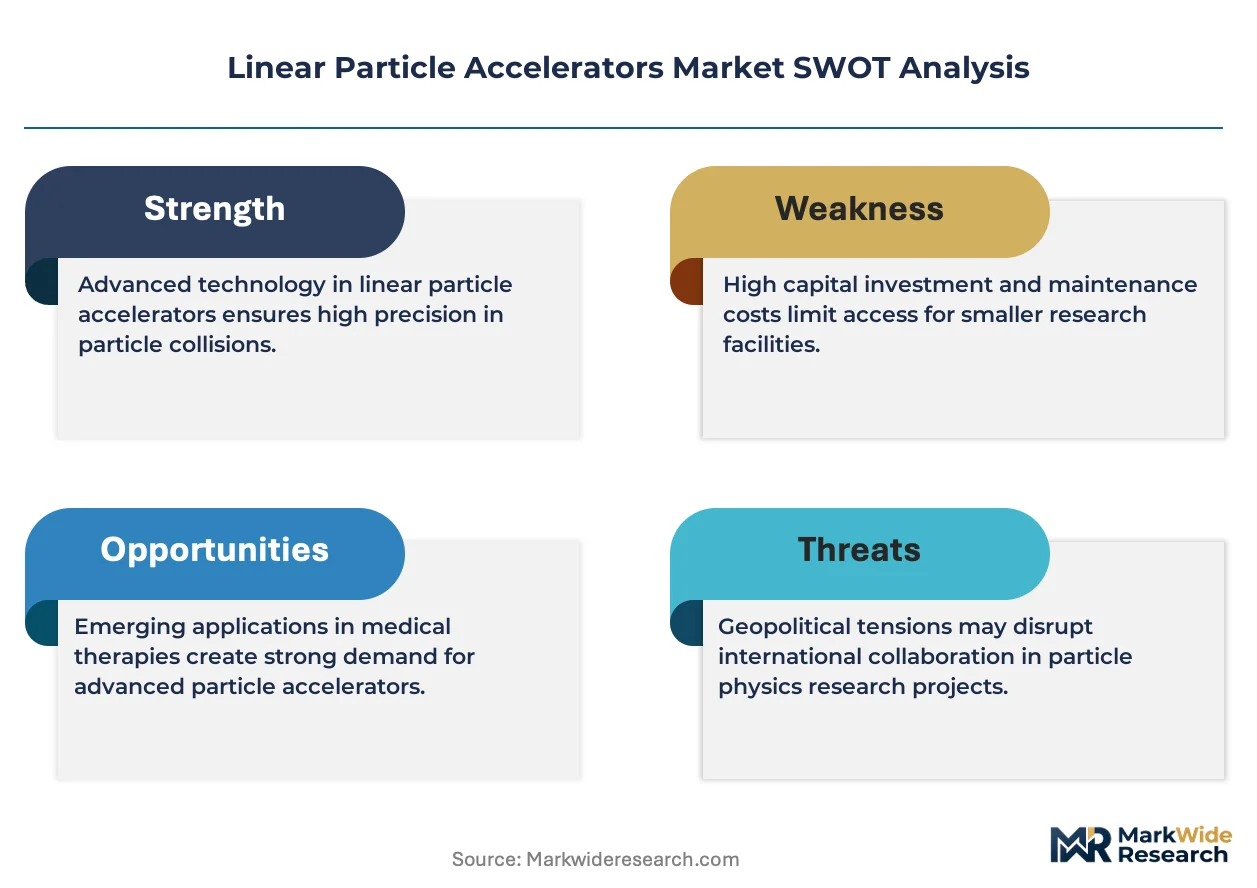
- Helium Supply Concentration:Superconducting magnet cooling depends on liquid helium from concentrated natural gas extraction regions, exposing operational continuity to geopolitical supply disruptions.
- Site Preparation Complexity:Multi-room proton facilities require radiation shielding concrete volumes exceeding 10,000 cubic meters and precision vibration isolation, extending installation timelines.
- Photon Radiotherapy Substitution:Advanced VMAT and MR-linac systems deliver competitive dose conformality at substantially lower capital and operational expenditure levels.
Strategic Opportunities
- Japan's Aging Demography:Elevated cancer incidence projections and government healthcare infrastructure investments are expanding proton therapy center commissioning targets.
- Flash Radiobiology Translation:Ultra-high dose-rate electron and proton delivery protocols promise normal tissue sparing advantages, opening new clinical trial and regulatory pathways.
- Compact Single-Room Systems:Superconducting synchrocyclotron miniaturization enables hospital-based deployment without dedicated accelerator buildings, penetrating mid-tier medical centers.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Superconducting system commissioning and maintenance require specialized expertise in liquid helium handling and 2K refrigeration plant operation that outpaces training pipeline output.
- Beam Commissioning Duration:Multi-room proton facilities require 18-24 month clinical validation periods for each treatment room, compressing revenue recognition timelines against capital deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Particle Accelerators Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electron Accelerators, Proton Accelerators, Heavy Ion Accelerators, Synchrotron Light Sources Application: Medical Imaging, Cancer Treatment, Research & Development, Industrial Applications End User: Hospitals, Research Institutes, Academic Institutions, Nuclear Facilities Technology: Superconducting, Normal Conducting, RF Acceleration, Variable Energy |
| Companies Covered | ViewRay, Inc., Siemens Healthineers, Varian Medical Systems, Brainlab AG, IBA, Elekta, Shinva Medical Instrument, Carl Zeiss Meditec AG, Accuray Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Particle Accelerators Market Strategic Shifts
Radiofrequency source architectures and beam delivery modalities are undergoing fundamental revision as clinical evidence requirements tighten and energy efficiency mandates intensify across major healthcare procurement jurisdictions.
Superconducting spoke cavities and elliptical cell geometries are displacing normal-conducting copper drift-tube linacs in next-generation proton therapy systems. University hospital consortia in Germany and Japan are specifying these architectures for new facilities. The technology is displacing established supply chain relationships as cryomodule fabrication capabilities concentrate among specialized superconducting RF vendors.
CE marking under the EU Medical Device Regulation now mandates clinical performance data for novel radiation therapy modalities beyond basic safety documentation. Manufacturers must submit post-market surveillance plans and real-world evidence commitments as conditions of market authorization. European proton therapy installations are experiencing extended regulatory review periods while adapting quality management systems to MDR Annex IX requirements.
Hospital procurement committees are unbundling equipment acquisition from long-term service contracts, separating capital expenditure approval from operational maintenance commitments. Independent service organizations are capturing aftermarket technical support contracts previously held by original equipment manufacturers. This pattern is most visible in United States academic medical centers with established in-house medical physics and biomedical engineering capabilities.
Linear Particle Accelerators Market Segmentation
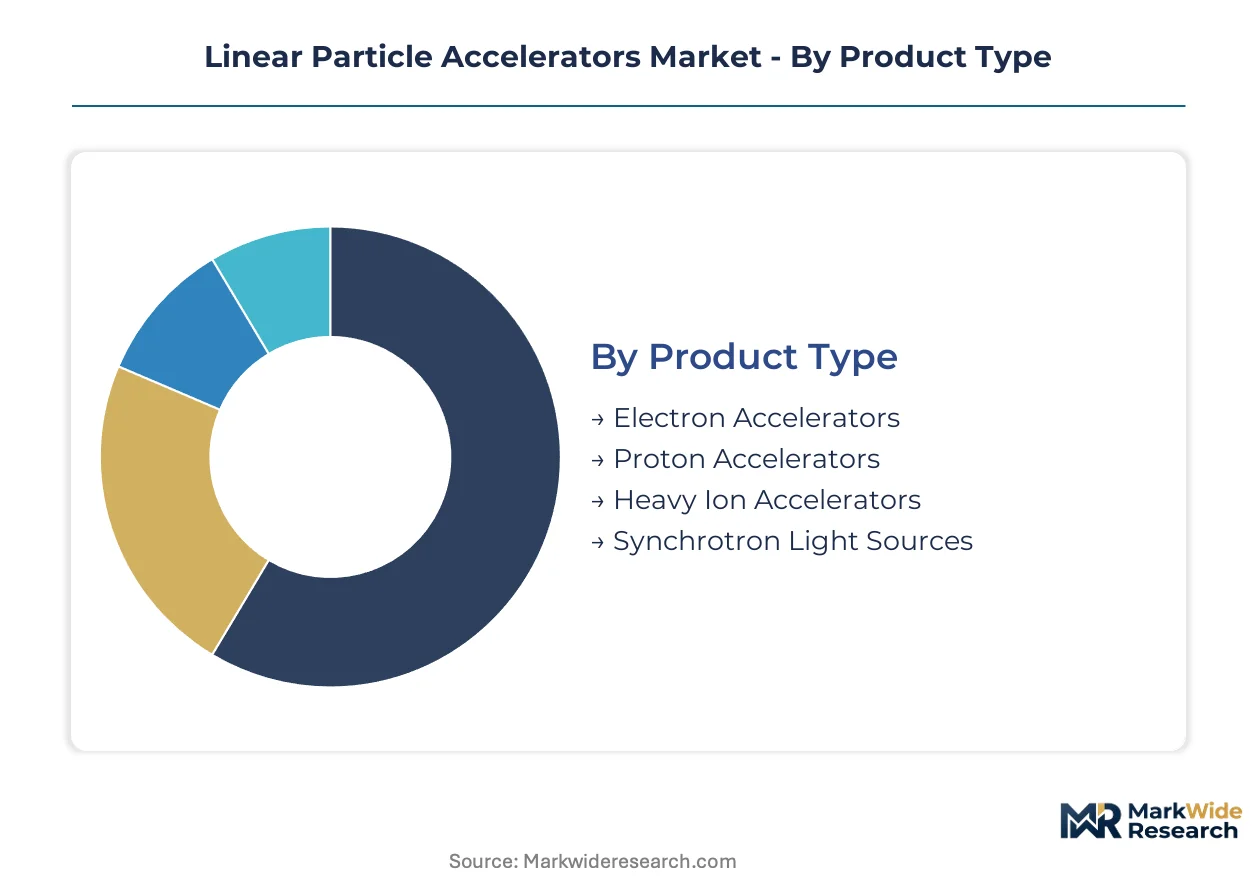
Segmentation in the Linear Particle Accelerators Market reveals divergent regulatory pathways and capital deployment patterns across clinical, research, and industrial domains. Technology choices and end-user procurement authority determine competitive positioning more sharply than in conventional medical device markets.
Product Type:
FDA 510(k) clearance timelines and CE marking under EU MDR vary substantially across particle species, with proton systems facing the most stringent clinical evidence requirements.
- Proton Accelerators:Superconducting synchrocyclotron and synchrotron architectures deliver Bragg peak dose deposition for tumor targeting with minimal exit dose. United States cancer treatment centers dominate procurement as Medicare reimbursement frameworks mature for intensity-modulated proton therapy.
- Electron Accelerators:Standing-wave and travelling-wave linac designs operate at S-band and X-band frequencies for intraoperative radiation therapy and industrial sterilization. Germany's university hospital networks sustain replacement cycles for aging cobalt-60 facilities.
- Heavy Ion Accelerators:Carbon ion beam systems require dedicated accelerator complexes with extended beam transport lines; Japan's National Institute of Radiological Sciences operates the primary clinical reference installation.
- Synchrotron Light Sources:Storage ring and energy-recovery linac configurations generate tunable X-ray beams for protein crystallography and materials science; Helmholtz Association facilities in Germany anchor European demand.
Proton accelerators handle the majority of clinical throughput; heavy ion systems are gaining share fastest in Asia-Pacific research consortia.
Application:
Reimbursement codes and research grant funding mechanisms create distinct demand profiles across clinical and non-clinical use cases.
- Cancer Treatment:External beam radiation therapy using proton, electron, and photon modalities accounts for the dominant installed base. United States hospital systems prioritize proton therapy expansion as private payer coverage broadens beyond Medicare.
- Research & Development:High-energy physics, materials characterization, and radiobiology investigations drive multi-GeV facility specifications. Japan's KEK and Germany's DESY sustain procurement for next-generation light source upgrades.
- Medical Imaging:Compact electron linacs power linear accelerator-based computed tomography and portal imaging systems for treatment verification. Replacement demand concentrates in mature European and North American markets.
- Industrial Applications:Electron beam processing serves food irradiation, polymer crosslinking, and semiconductor defect analysis. Germany's automotive supply chain drives specifications for high-throughput sterilization systems.
Cancer treatment commands the largest capital allocation; research and development applications are expanding most quickly in national laboratory networks.
End User:
Procurement authority and technical staffing depth determine system complexity tolerance across institutional categories.
- Hospitals:Academic medical centers and dedicated cancer hospitals specify integrated imaging-to-therapy platforms with vendor service commitments. United States proton therapy centers require 18-24 month commissioning timelines per treatment room.
- Research Institutes:National laboratories and dedicated accelerator facilities operate custom-designed systems with in-house cryogenic and RF engineering capabilities. Japan's RIKEN and Germany's GSI represent anchor installations.
- Academic Institutions:University hospitals balance clinical revenue generation with training and research missions, often prioritizing dual-use accelerator architectures. European consortia leverage shared infrastructure models.
- Nuclear Facilities:Spallation neutron sources and transmutation research installations require megawatt-class beam power with continuous-wave operation. IAEA safety standards govern licensing frameworks in member states.
Hospitals absorb the dominant share of clinical system deliveries; research institutes are climbing the fastest on funding allocation for next-generation facilities.
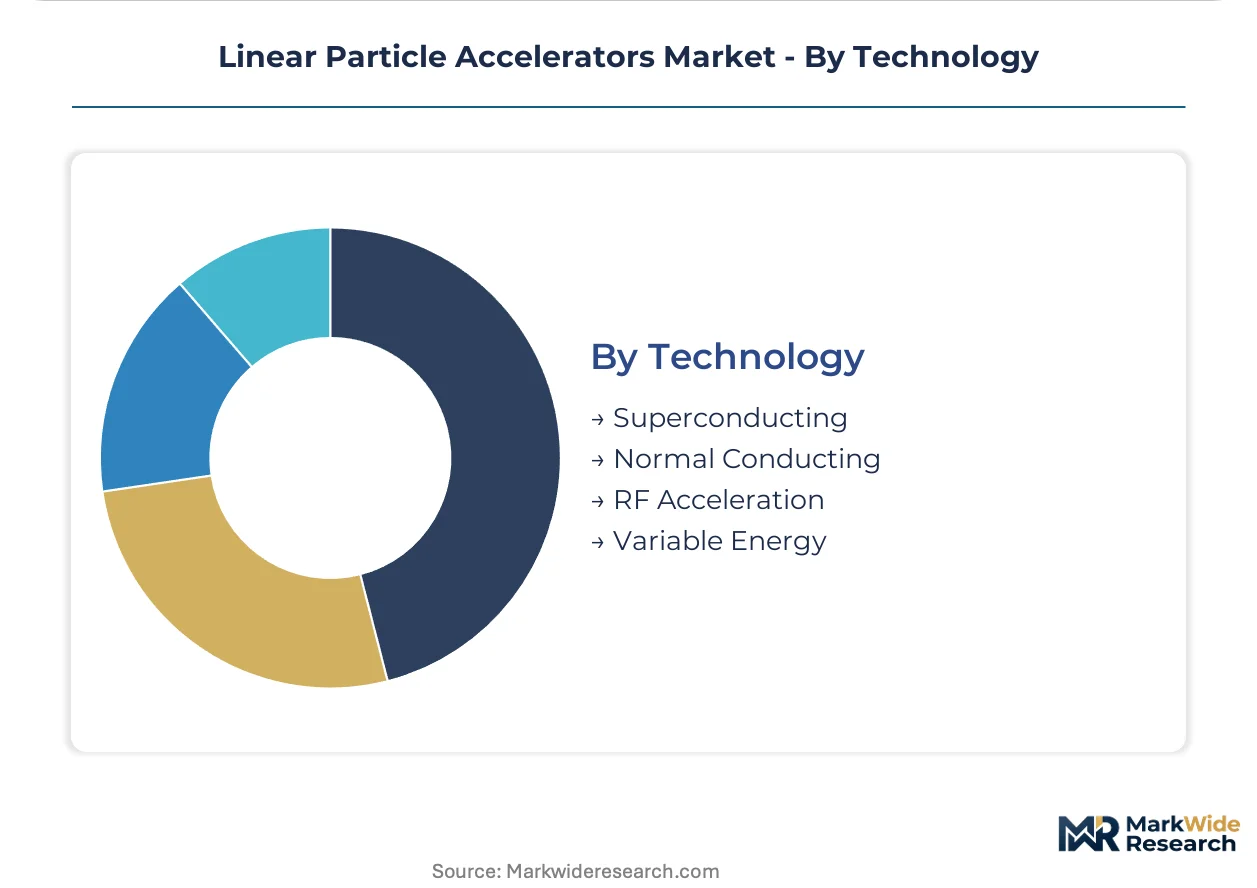
Technology:
Energy efficiency mandates and total cost of ownership calculations are compressing adoption timelines for superconducting architectures.
- Superconducting:Niobium-titanium cryomodules enable continuous-wave operation with quality factors exceeding 10^10, reducing RF power consumption by orders of magnitude. Germany's FAIR facility and Japan's ILC preparatory work anchor demand.
- Normal Conducting:Copper cavity systems dominate legacy installations and compact electron linacs where cryogenic infrastructure is impractical. Mature supply chains sustain replacement part availability.
- RF Acceleration:Klystron and solid-state amplifier architectures at 400 MHz to 3 GHz frequencies power conventional proton and electron systems. Frequency selection depends on beam current and energy requirements.
- Variable Energy:Rapid-cycling synchrotrons and energy-degrader systems enable treatment planning flexibility across tumor depths. Single-room proton systems increasingly specify this capability for competitive positioning.
Normal conducting technology retains the largest installed base; superconducting systems are expanding most quickly in new facility construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Japan demonstrate the lowest price elasticity for superconducting proton systems, while mid-tier United States medical centers exhibit acute sensitivity to total cost of ownership calculations. Germany's research infrastructure sustains demand regardless of capital intensity, creating a three-tier demand elasticity map across major installation markets.
United States
Medicare coverage determinations for intensity-modulated proton therapy are expanding eligible patient populations and validating hospital capital investments in multi-room facilities. FDA 510(k) clearance pathways shape product development timelines and clinical trial requirements for manufacturers targeting domestic installations. Texas Medical Center in Houston and MD Anderson Cancer Center anchor the nation's densest cluster of proton therapy commissioning activity.
Germany
Helmholtz Association facilities and university hospital networks sustain procurement pipelines for high-energy physics and clinical dual-use accelerators with minimal budget constraint sensitivity. CE marking under the EU Medical Device Regulation now mandates clinical performance data for novel radiation therapy modalities beyond basic safety documentation. FAIR facility construction in Darmstadt and DESY operations in Hamburg concentrate superconducting RF engineering expertise.
Japan
Elevated cancer incidence projections and government healthcare infrastructure investments are expanding proton therapy center commissioning targets across the archipelago. METI funding allocations and PMDA regulatory frameworks support next-generation light source upgrades and clinical translation of heavy ion research. KEK in Tsukuba and RIKEN in Wako represent anchor installations driving national accelerator specifications.
China
Government-backed cancer hospital construction programs are generating procurement demand for compact single-room proton systems that circumvent dedicated accelerator building requirements. NMPA medical device registration pathways and GB standards compliance govern market access for imported and domestically manufactured systems. Shanghai Proton and Heavy Ion Center and emerging installations in Guangdong Province concentrate clinical commissioning expertise.
Switzerland
Swissmedic regulatory frameworks and proximity to CERN technical infrastructure position the country as a testbed for superconducting technology validation in clinical environments. Federal research funding through the Swiss National Science Foundation sustains university hospital participation in European accelerator consortia. Geneva and Zurich medical centers leverage cross-border supply chains for cryogenic engineering talent and specialized component sourcing.
Linear Particle Accelerators Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Linear Particle Accelerators Market, creating a bifurcated competitive structure. Superconducting cryomodule specialists command premium positioning through proprietary niobium-titanium fabrication capabilities, while normal-conducting system fabricators compete on installation speed and lower upfront capital requirements. Three archetypes dominate: integrated imaging-to-therapy platform vendors, dedicated proton therapy system specialists, and compact single-room system innovators. M&A activity concentrates on cryogenic engineering talent acquisition, while strategic partnerships between research institutes and commercial vendors accelerate technology translation from national laboratory to hospital deployment.
Among diversified health technology conglomerates, Siemens Healthineers and Varian Medical Systems occupy positions that exemplify platform integration versus dedicated therapy specialization respectively. IBA represents the compact system archetype, anchoring the single-room proton market segment against multi-room facility competitors. These three companies illustrate the strategic choice between breadth of clinical workflow integration and depth of particle therapy technical focus.
| Leading Market Players |
|---|
| ViewRay, Inc. |
| Siemens Healthineers |
| Varian Medical Systems |
| Brainlab AG |
| IBA |
| Elekta |
| Shinva Medical Instrument |
| Carl Zeiss Meditec AG |
| Accuray Incorporated |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways and CE marking under EU MDR gate both supplier qualification and price differentiation in proton therapy systems, compressing margins for uncertified vendors while rewarding integrated platform vendors with premium positioning.
Pricing Analysis
After-sales service contracts and multi-year maintenance agreements drive lifetime value more than initial equipment sales, with superconducting cryomodule refurbishment cycles anchoring recurring revenue streams. Pricing stratifies across premium superconducting architectures, standard normal-conducting multi-room facilities, and economy compact single-room systems. Cost compression in normal-conducting segments intensifies as photon radiotherapy alternatives improve dose conformality. Academic medical centers in the United States exhibit lowest price sensitivity; mid-tier community hospitals face acute capital constraint pressure.
Supply Chain Analysis
Inbound logistics costs for liquid helium and niobium-titanium superconducting wire strain procurement budgets, with container availability on Asia-Europe trade lanes affecting cryomodule delivery schedules. Supply concentrates in Germany for precision RF cavity fabrication, Japan for superconducting magnet engineering, and the United States for integrated therapy platform assembly. Raw material dependencies include helium from natural gas extraction regions, high-purity niobium from Brazil and Canada, and specialized ceramics for RF windows. Single-source vulnerability in cryogenic engineering talent pools threatens commissioning timelines. Distribution runs through direct OEM-hospital relationships and emerging independent service organizations capturing aftermarket contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where imaging-to-therapy workflow integration and interoperability standards determine competitive survival, with hospital procurement committees unbundling equipment from service contracts to force vendor flexibility.
For Market Incumbents: Consolidate cryogenic engineering capabilities through targeted talent acquisition and captive niobium-titanium fabrication investments. Lock in hospital system partnerships with extended service agreements before independent service organizations capture aftermarket share. Defend against compact single-room proton system substitution by accelerating superconducting synchrocyclotron miniaturization roadmaps.
For New Entrants and Emerging Players: Remote beam commissioning and cryogenic plant maintenance services represent underserved white space where incumbents lack responsive coverage. Target Japan's expanding proton therapy center pipeline where government infrastructure investments reduce customer acquisition friction. Penetrate through superconducting RF component supply partnerships with established therapy platform vendors rather than competing on complete system integration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed proton therapy center operators facing reimbursement compression and extended commissioning timelines. Long-term viability hinges on Flash radiobiology translation success and Medicare coverage expansion trajectories. Watch for helium supply disruption signals and superconducting magnet technology maturation as inflection indicators for capital redeployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Engineering Talent Acquisition | Secures scarce expertise in liquid helium handling and 2K refrigeration plant operation for superconducting system commissioning. |
| Compact Single-Room System Development | Enables hospital-based proton deployment without dedicated accelerator buildings, penetrating mid-tier medical centers. |
| Independent Service Organization Partnership | Captures aftermarket technical support contracts as procurement committees unbundle equipment from maintenance commitments. |
| Flash Radiobiology Clinical Trial Investment | Opens new regulatory pathways for ultra-high dose-rate protocols promising normal tissue sparing advantages. |
| Superconducting RF Component Supply Agreement | Feeds next-generation proton therapy architectures displacing normal-conducting copper drift-tube linacs. |
Study Parameters
The analysis maps superconducting cryomodule, normal-conducting linac, and compact synchrocyclotron sub-sectors, each validated through biomedical engineers, hospital purchasing committee members, cryogenic plant operators, and proton therapy center administrators. Primary interviews combined with secondary validation against FDA 510(k) filings, CE marking databases under EU MDR, hospital procurement contract registries, and IAEA safety standard documentation. Bottom-up installed base enumeration and top-down healthcare capital expenditure triangulation anchored market sizing.
Consistency checks validated volume and value outputs against Helmholtz Association facility budgets, METI infrastructure allocations, and Medicare reimbursement trend analyses. Segmentation dimensions modeled include particle species, technology architecture, end-user institutional category, and regional regulatory cluster. CAGRs derived from facility commissioning pipeline analysis and replacement cycle pattern recognition. Forecast inputs incorporated helium supply trajectory assessments and superconducting magnet technology adoption curves.
Forecasts assume regulatory continuity in FDA clearance pathways and EU MDR enforcement; material policy shifts would require re-modeling. Reimbursement determination reversals for intensity-modulated proton therapy, helium export restrictions, or superconducting technology performance shortfalls could compress expansion timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
AI in Aviation Market