
 Europe Artificial Intelligence and Analytics in Defence Market | 2026-2036
Europe Artificial Intelligence and Analytics in Defence Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Artificial Intelligence and Analytics in Defence Market Foresight
Defence procurement channels across Europe are tilting toward direct government-to-industry partnerships, bypassing traditional integrator layers. Thales leverages its pan-European footprint to anchor multi-national AI development consortia. Helsing competes through specialized defence-focused machine learning models trained on classified operational data. Rheinmetall sustains manufacturing scale advantages in hardware-software integrated battlefield systems.
Europe Artificial Intelligence and Analytics in Defence encompasses algorithmic systems that process multi-source intelligence through machine learning pipelines, natural language processing of intercepted communications, computer vision for autonomous target recognition, and robotic platforms operating at the tactical edge, all designed to compress decision cycles in contested operational environments. Surveillance applications draw the largest current budget allocations across European ministries of defence, while threat detection represents the fastest-expanding segment as peer-conflict scenarios drive investment in predictive analytics. Deployment architectures increasingly favor edge computing configurations that enable real-time inference without continuous satellite uplink dependency.
The EU AI Act imposes conformity obligations on high-risk autonomous systems deployed by member state militaries, while the European Defence Agency coordinates capability roadmaps that steer national procurement toward interoperable standards. ECHA chemical registration requirements indirectly shape supply chains for sensor materials and battery chemistries powering unmanned platforms. Stakeholders must monitor whether forthcoming EU export control harmonization restricts cross-border transfer of trained defence AI models between allied programmes.
Market Dynamics
Defence procurement across European NATO members is pivoting from platform-centric acquisition to capability-as-a-service models, compressing vendor selection cycles and elevating software architecture above hardware specifications in contract awards.
Growth Catalysts
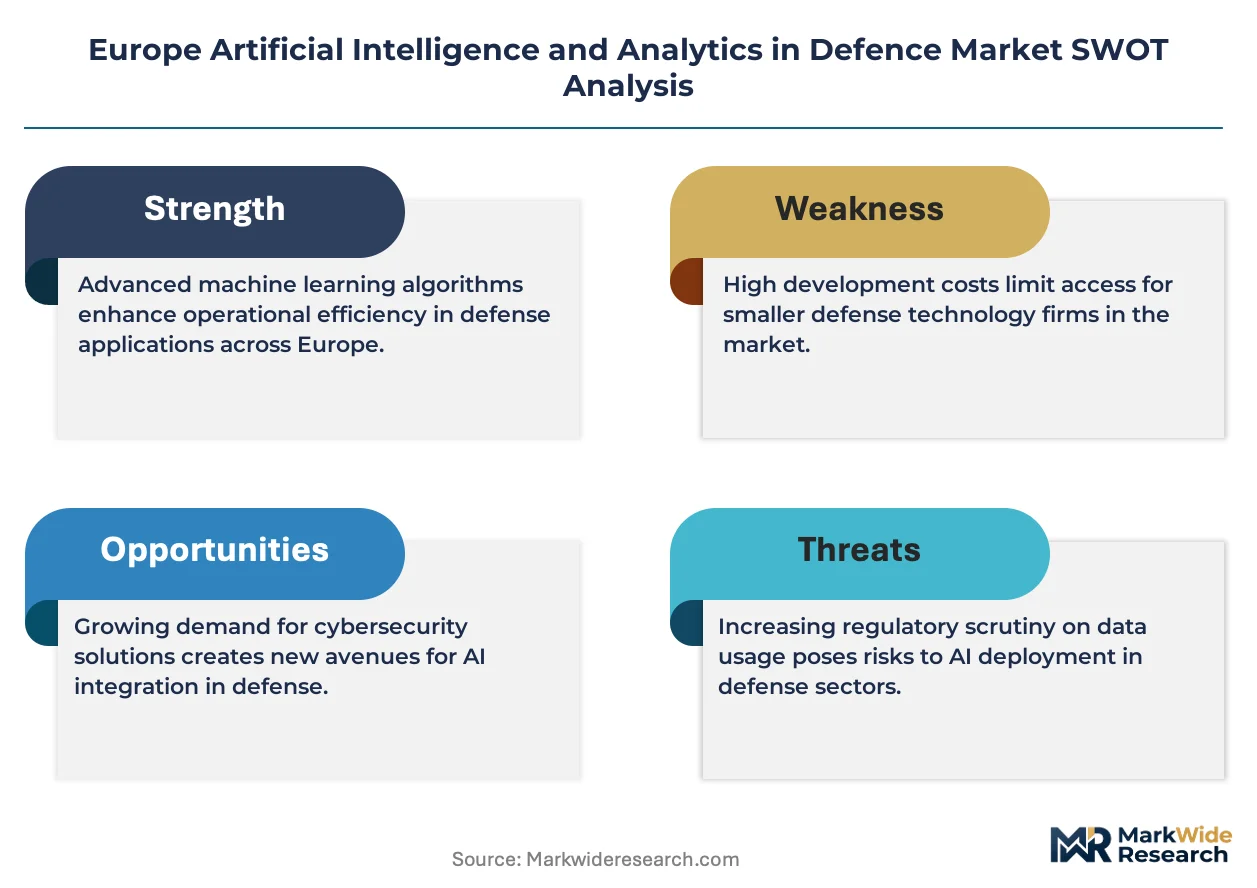
- EU AI Act compliance mandates:Mandatory risk classification for high-risk autonomous systems creates predictable demand pathways for certified AI developers serving member state militaries.
- France-Germany-UK sovereign capability programmes:Domestic sourcing requirements in these three markets channel public R&D funding toward national AI champions and specialized defence contractors.
- Edge computing architectures:Tactical deployments requiring real-time inference without continuous satellite uplink dependency accelerate procurement of hardened inference hardware and lightweight model optimization.
Market Restraints
- Export control fragmentation:Divergent national implementation of EU dual-use regulations creates compliance friction for cross-border transfer of trained defence AI models between allied programmes.
- Classified data scarcity:Limited pools of operational sensor data suitable for training high-fidelity threat detection models constrain model performance for peer-conflict scenarios.
- Specialized compute hardware concentration:Dependence on non-European suppliers for advanced GPUs and AI accelerators exposes procurement timelines to geopolitical supply disruptions.
Strategic Opportunities
- Poland and Baltic states:Accelerated NATO frontier defence modernisation creates demand for interoperable AI-enabled surveillance and predictive maintenance systems with limited incumbent vendor lock-in.
- Human-machine teaming protocols:Emerging doctrine for supervised autonomous weapon systems opens specification windows for explainable AI interfaces and operator-in-the-loop validation tools.
- European Defence Fund incentives:Collaborative R&D financing mechanisms reduce capital barriers for multi-national consortia developing shared AI training infrastructure and federated learning frameworks.
Industry Challenges
- Cleared AI engineering talent:Security clearance requirements and competition from commercial technology firms constrain recruitment of machine learning specialists with defence domain expertise.
- Interoperability certification timelines:NATO STANAG validation and national security accreditation processes extend product qualification cycles beyond typical software release velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Artificial Intelligence and Analytics in Defence Market |
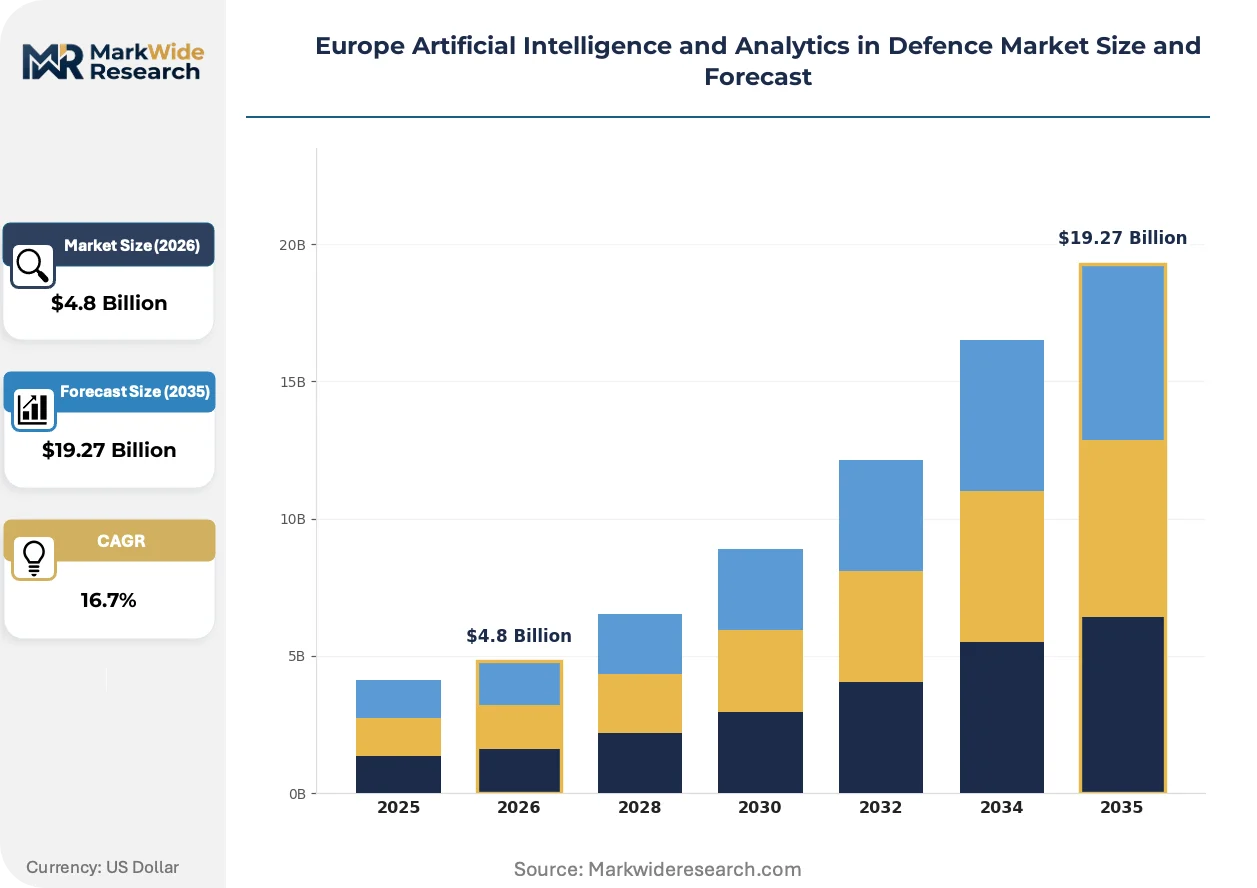
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics Application: Surveillance, Threat Detection, Decision Support, Logistics Management End User: Military, Homeland Security, Intelligence Agencies, Defense Contractors Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | BAE Systems, Indra, Thales, Harmattan AI, Helsing, Rheinmetall, Safran, Crown Cyber Defence, Leonardo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Artificial Intelligence and Analytics in Defence Market Shifts & Advancements
Algorithmic warfare is compressing decision cycles from hours to seconds, forcing structural adaptation across hardware, software, and organisational boundaries in European defence procurement.
Digital twin technology is virtualizing battlefield simulation and system lifecycle management. French and German defence ministries are deploying virtual replicas of naval and armoured platforms for predictive maintenance and mission rehearsal. This capability is virtualizing traditional physical prototyping stages, reducing platform development timelines while expanding scenario testing breadth beyond live-exercise constraints.
The EU AI Act establishes mandatory conformity assessment pathways for high-risk autonomous defence applications. Industrial consequence includes mandatory documentation of training data provenance and algorithmic explainability for systems deployed by member state militaries. Multi-national platform programmes such as the Future Combat Air System face heightened coordination costs to harmonise national interpretations of acceptable risk thresholds.
Defence ministries are unbundling software sustainment from platform acquisition contracts. Traditional prime contractors face disintermediation as national procurement offices negotiate direct licensing agreements with AI software vendors for model updates and retraining services. This pattern is most visible in United Kingdom intelligence-surveillance-reconnaissance programmes, where modular software architectures enable competitive recompetition of algorithm components independent of airframe providers.
Europe Artificial Intelligence and Analytics in Defence Market Segmentation
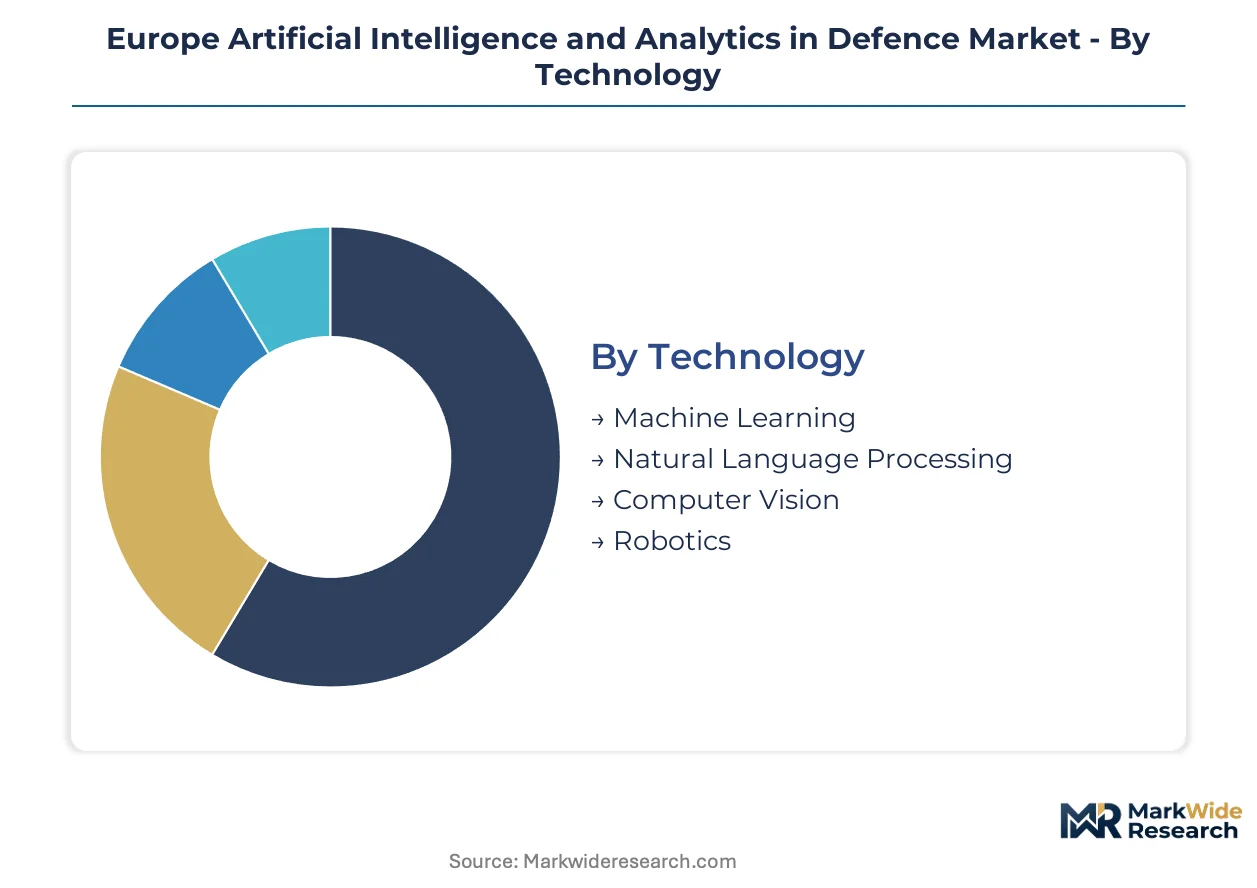
Segmentation in European defence AI markets reveals how procurement priorities diverge across operational domains and compliance architectures. Understanding these divisions exposes where sovereign capability investments concentrate and where interoperability standards create cross-border vendor opportunities.
Technology:
After-sales-service intensity varies sharply across technology segments, with computer vision and robotics demanding sustained field engineering support while machine learning platforms shift toward remote model retraining contracts.
- Machine Learning:Algorithmic systems process multi-source intelligence through neural network pipelines trained on classified operational data. French and German ministries of defence channel sovereign R&D funding toward domestic ML champions under EU AI Act high-risk system mandates. Demand concentrates in predictive maintenance and electronic warfare signal classification where explainability requirements shape architecture choices.
- Computer Vision:Autonomous target recognition systems fuse electro-optical and synthetic aperture radar feeds for real-time object detection. United Kingdom intelligence-surveillance-reconnaissance programmes deploy these capabilities at the tactical edge, driving procurement of hardened inference hardware that operates without continuous satellite uplink.
- Natural Language Processing:Intercepted communications analysis and multilingual document exploitation for intelligence fusion.
- Robotics:Autonomous ground and aerial platforms operating in contested electromagnetic environments with degraded communications.
By volume, machine learning leads technology procurement across European NATO members. By growth pace, computer vision is gaining share fastest as peer-conflict scenarios accelerate investment in autonomous targeting.
Application:
Cost tier differentiation separates surveillance platforms with decade-long sustainment obligations from threat detection systems requiring continuous algorithmic refresh cycles.
- Surveillance:Persistent wide-area monitoring through satellite constellations, unmanned aerial systems, and fixed sensor networks generating multi-intelligence fusion datasets. Current budget allocations across European ministries of defence concentrate here, with France and Germany deploying virtual replicas of naval and armoured platforms for mission rehearsal and predictive maintenance.
- Threat Detection:Predictive analytics identifying anomalous patterns in sensor feeds and communications metadata for preemptive engagement. This segment climbs the fastest as Russia-Ukraine conflict dynamics drive investment in AI-enabled early warning against peer-adversary capabilities.
- Decision Support:Command-and-control augmentation compressing operational planning cycles through automated course-of-action generation.
- Logistics Management:Supply chain optimization and predictive sparing for forward-deployed formations operating at extended lines of communication.
Surveillance maintains the largest installed base across European defence ministries. Threat detection exhibits the steepest expansion trajectory as predictive analytics capabilities mature.
End User:
Customer type determines security clearance thresholds and data handling protocols, with intelligence agencies imposing the most stringent compartmentalization requirements.
- Military:Operational commands across army, navy, and air force branches deploying AI at the tactical edge for real-time decision advantage. Sovereign capability programmes in France, Germany, and the United Kingdom channel procurement toward national suppliers with established security accreditation.
- Intelligence Agencies:Signals intelligence and human intelligence fusion operations requiring specialized natural language processing and cross-lingual information extraction. Limited pools of operational sensor data constrain model training for high-fidelity peer-conflict scenarios.
- Homeland Security:Border surveillance and critical infrastructure protection with dual-use technology transfer restrictions under EU export control frameworks.
- Defense Contractors:Prime and subsystem manufacturers integrating AI into platform development under NATO STANAG interoperability certification timelines.
Military end users dominate procurement volume through sovereign capability programmes. Intelligence agencies are expanding most quickly as classified data infrastructure investments accelerate.
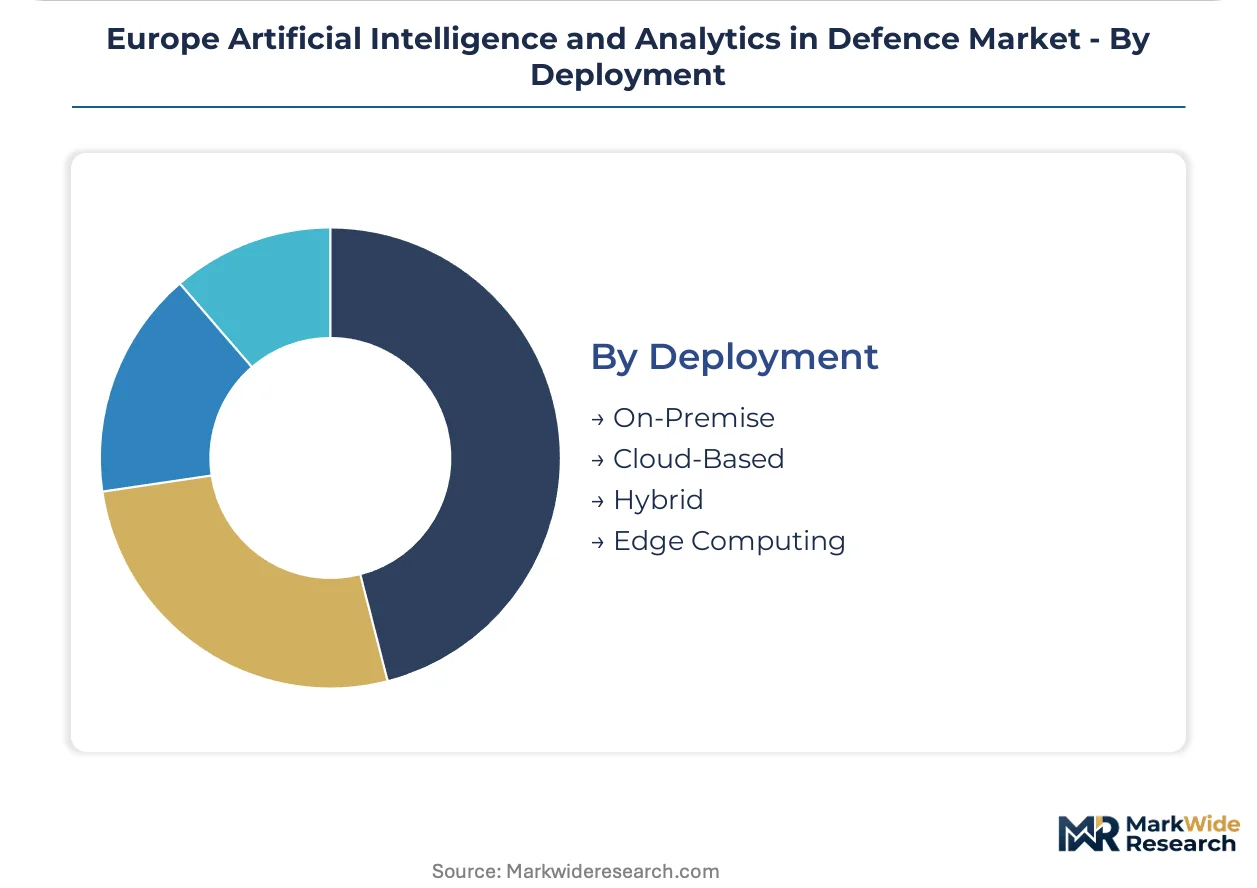
Deployment:
Volume scale separates edge computing architectures with unit-level fielding from cloud-based platforms serving enterprise intelligence analysis.
- Edge Computing:Hardened inference hardware enabling real-time processing aboard platforms operating in contested electromagnetic environments with intermittent connectivity. NATO frontier defence modernisation in Poland and Baltic states creates demand for interoperable edge-deployed surveillance systems.
- Cloud-Based:Centralized model training and federated learning frameworks leveraging European Defence Fund collaborative R&D financing. Multi-national platform programmes such as Future Combat Air System face coordination costs harmonising national risk threshold interpretations.
- On-Premise:Classified facility installations for intelligence community applications with air-gapped security requirements.
- Hybrid:Architectures combining edge inference with cloud-based model updates and periodic retraining on operational data.
Cloud-based deployments lead current procurement by aggregate compute capacity. Edge computing is gaining share fastest as tactical real-time requirements displace satellite-dependent architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube corridor and North Sea cable interconnects anchor Europe's defence data infrastructure, enabling cross-border AI model federation and satellite downlink redundancy for military command networks.
France
Dassault Aviation's Rafale F5 programme and the Future Combat Air System drive sovereign AI investment in autonomous targeting and predictive maintenance. Direction Générale de l'Armement mandates EU AI Act conformity assessments for all high-risk autonomous systems entering operational service. The Paris-Saclay cluster concentrates machine learning research for defence applications, with Thales anchoring multi-national consortia for federated training infrastructure.
Germany
The Main Ground Combat System and Boxer vehicle modernisation programmes channel procurement toward AI-enabled threat detection and logistics optimisation. Bundesamt für Ausrüstung, Informationstechnik und Nutzung der Bundeswehr enforces strict data provenance documentation under EU AI Act high-risk system classifications. The Munich-Stuttgart corridor hosts Rheinmetall's hardware-software integration facilities for battlefield robotics and edge computing architectures.
United Kingdom
Strategic Command's AI Lab accelerates procurement of natural language processing for intelligence fusion and computer vision for autonomous surveillance. Ministry of Defence software unbundling policies enable direct licensing agreements with AI vendors independent of platform primes. The London-Oxford-Cambridge arc concentrates cleared engineering talent for defence machine learning development, with GCHQ's Manchester hub expanding classified data infrastructure.
Poland
NATO frontier defence modernisation drives demand for interoperable AI-enabled surveillance systems and predictive maintenance for armoured formations. Polish Ministry of National Defence procurement aligns with European Defence Agency capability roadmaps for STANAG interoperability. The Warsaw-Łódź corridor attracts multi-national consortia seeking limited incumbent vendor lock-in for Baltic flank security programmes.
Sweden
Gripen E fighter and GlobalEye airborne early warning programmes integrate AI for electronic warfare signal classification and sensor fusion. Swedish Defence Materiel Administration coordinates with Finnish and Norwegian counterparts on Nordic-Baltic interoperability standards for autonomous systems. The Linköping-Stockholm corridor concentrates Saab's AI development for contested electromagnetic environment operations.
Europe Artificial Intelligence and Analytics in Defence Market Competitive Landscape
On the supply side, the industry is consolidating around sovereign capability programmes that privilege domestic accreditation over pan-European scale. Tiered vendor structures separate hardware-software integrators from specialised machine learning boutiques. Three archetypes dominate: legacy primes with security clearance infrastructure, defence-native AI specialists with classified data access, and dual-use technology firms pivoting from commercial applications. Competitive moves concentrate on consortium formation for European Defence Fund access and direct software licensing agreements that bypass traditional prime contractor layers.
Among legacy European defence primes, BAE Systems, Thales, and Rheinmetall occupy positions that exemplify contrasting strategic postures. BAE Systems represents the Anglo-Saxon model of deep intelligence community integration with sustained platform manufacturing scale. Thales anchors Franco-European consortia through its pan-European security accreditation footprint and multi-national programme leadership. Rheinmetall exemplifies hardware-software convergence in ground systems, leveraging manufacturing scale for battlefield robotics and edge computing integration. These three entities sit within distinct national procurement ecosystems yet compete directly for European Defence Fund collaborative financing and NATO interoperability certification mandates.
| Leading Market Players |
|---|
| BAE Systems |
| Indra |
| Thales |
| Harmattan AI |
| Helsing |
| Rheinmetall |
| Safran |
| Crown Cyber Defence |
| Leonardo |
| Others |
Supply & Pricing Matrix
Advanced GPU and AI accelerator fabrication concentrates in Taiwan and South Korea, concentrating pricing power with non-European semiconductor foundries and compressing margins for European defence primes integrating inference hardware into battlefield systems. This upstream concentration forces downstream buyers into long-term offtake agreements with limited price negotiation leverage, while EU AI Act compliance costs add fixed certification overhead that tiered vendors recover through differentiated service bundling.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with sovereign capability programmes in France, Germany, and the United Kingdom negotiating enterprise-scale licensing for federated training infrastructure while Poland and Baltic states absorb per-unit premiums for smaller edge-computing deployments. Price differentiation separates NATO STANAG-certified systems commanding compliance premiums from non-interoperable national alternatives. Cost compression in mid-tier computer vision hardware is intensifying as Rheinmetall and Thales scale manufacturing, though intelligence agencies remain least price-sensitive due to air-gapped security requirements that limit vendor choice.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for European defence AI programmes dependent on advanced chip imports. Component sourcing draws from Taiwan for GPUs, the Netherlands for EUV lithography equipment, and Japan for specialty sensor substrates. Single-source vulnerability concentrates in advanced packaging capabilities where ASE and Amkor control critical capacity. Distribution runs through national procurement offices negotiating direct government-to-industry partnerships that bypass traditional prime contractor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Artificial Intelligence and Analytics in Defence Market represents a high-growth disruption as the EU AI Act's mandatory risk classification creates predictable demand pathways for certified autonomous systems while compressing vendor qualification timelines.
For Market Incumbents: Harden sovereign accreditation moats by deepening security clearance infrastructure and anchoring multi-national consortia for European Defence Fund access. Invest in backward integration into classified data infrastructure to offset emerging competition from defence-native AI specialists with direct operational data pipelines. Prioritise explainable AI architecture development as the EU AI Act tightens algorithmic transparency mandates.
For New Entrants and Emerging Players: NATO frontier defence modernisation in Poland and the Baltic states represents the most penetrable entry point, with limited incumbent vendor lock-in and accelerated procurement timelines for interoperable surveillance systems. Human-machine teaming protocols for supervised autonomous weapons offer specification windows for operator-in-the-loop validation tools underserved by legacy primes. Pursue direct software licensing agreements with national procurement offices that bypass traditional prime contractor layers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dual-use technology firms pivoting from commercial computer vision to defence applications under EU AI Act high-risk system mandates. Long-term viability hinges on sustained sovereign R&D funding commitments and NATO interoperability certification durability. Monitor European Defence Fund collaborative R&D award velocity as an inflection indicator for multi-national programme momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Mandatory risk classification creates predictable demand pathways for certified developers serving member state militaries. |
| Edge Computing Hardware Integration | Hardened inference platforms enable real-time processing without satellite uplink dependency in contested environments. |
| Federated Learning Infrastructure | Multi-national training frameworks reduce classified data scarcity constraints while preserving operational security. |
| Direct Software Licensing Agreements | Bypass traditional prime contractor layers through modular architectures unbundling algorithm sustainment from platform acquisition. |
| Nordic-Baltic Interoperability Standards | Coordinated procurement with Finnish and Norwegian counterparts expands addressable market for STANAG-certified systems. |
Research Methodology
The analysis maps machine learning platforms, computer vision systems, natural language processing tools, and robotics applications, each validated through programme managers at European Defence Agency, procurement officers at Direction Générale de l'Armement, cleared AI engineering leads at GCHQ, and platform integration specialists at Rheinmetall and Thales. Secondary sources include EU AI Act regulatory filings, European Defence Fund award disclosures, NATO STANAG documentation, and national ministry of defence budget appropriations. Bottom-up segment sizing triangulates against top-down defence expenditure forecasts.
Assumptions held fixed include sustained NATO frontier defence modernisation commitment and EU AI Act enforcement continuity, while variables include export control harmonisation timelines and advanced semiconductor supply disruption scenarios. The projection horizon spans technology, application, end user, and deployment segmentation dimensions, with CAGRs derived from historical procurement velocity and peer-conflict scenario investment acceleration. Model inputs incorporate sovereign capability programme funding trajectories and federated learning framework adoption curves.
Practitioners should monitor EU export control harmonisation negotiations and Taiwan Strait supply disruption indicators for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
United States Satellite Communications Market
Aerospace & Defense
North America Remote Sensing Services Market
Aerospace & Defense
Charter Jet Services Market
Aerospace & Defense
Advanced Airport Technologies Market
Aerospace & Defense
Airport Moving Walkways Market
Aerospace & Defense
Asia-Pacific Unmanned Systems Market
Aerospace & Defense
Short Range Air Defense Systems Market
Aerospace & Defense
Europe Aerostat Systems Market
Aerospace & Defense
Europe Airport Operations Market
Aerospace & Defense
Recoilless Rifle Market
Aerospace & Defense
Indonesia Defense Market
Aerospace & Defense
Deep Space Exploration Market
Aerospace & Defense
Aircraft Cockpit Systems Market
Aerospace & Defense
High Altitude Long Endurance Market
Aerospace & Defense
Dismounted Soldier Systems Market
Aerospace & Defense
Armor Protection Systems Market