
 Aerospace and Defence MLCC Market | 2026-2036
Aerospace and Defence MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defence MLCC Market Insights
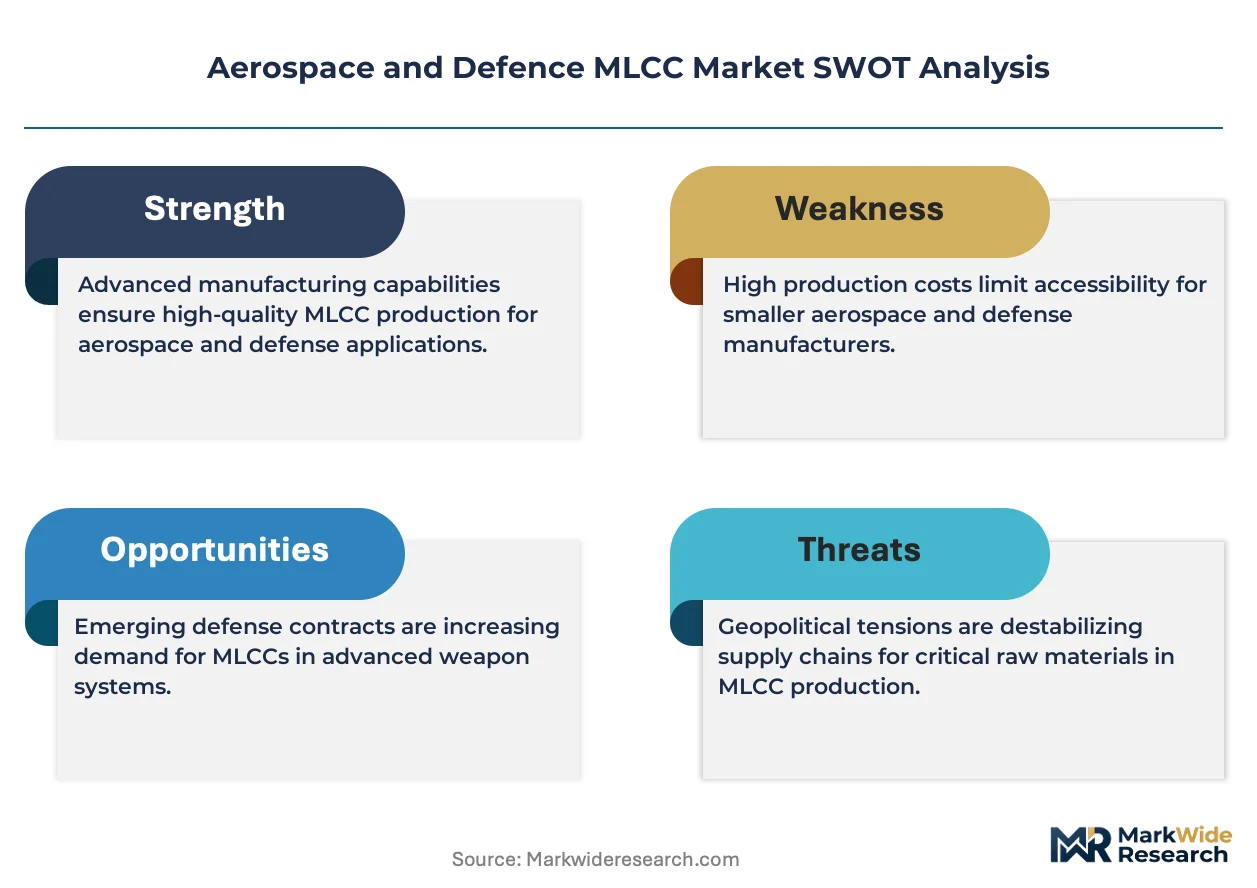
The capability gap between captive in-house ceramic formulation labs and outsourced specification buyers is redrawing competitive boundaries in aerospace-grade passive components. Murata Manufacturing Co., Ltd. leverages its proprietary barium titanate dielectric expertise to dominate high-voltage satellite bus applications. Samsung Electro-Mechanics anchors its position through backward integration into ceramic powder production, insulating margins from raw material volatility. Taiyo Yuden Co., Ltd. specializes in C0G-class temperature-stable formulations that sustain premium pricing for missile guidance systems.
Aerospace and Defence MLCCs are multilayer ceramic capacitors engineered with precious-metal electrodes and Class I or Class II dielectric ceramics, typically rated for operation from minus 55 degrees Celsius to 175 degrees Celsius with voltage tolerances exceeding 500 volts; their primary purpose is to filter, decouple, and store charge in electronic assemblies where failure carries mission-critical consequences. HighVoltage products lead absolute revenue owing to satellite power bus requirements, while C0G technology captures the fastest expansion as phased-array radar architectures multiply channel counts demanding near-zero capacitance drift. MissileSystems applications concentrate margin pools where sole-source qualification cycles lock out commodity competitors for decade-long production runs.
FAA airworthiness directives and ESA ECSS-Q-ST-60-05C standards jointly elevate reliability testing burdens, mandating 1000-hour life tests and destructive physical analysis for every production lot destined for crewed or strategic platforms. The Department of Defense's DFARS 252.225-7009 clause restricts foreign-sourced tantalum and ceramic materials in certain end-uses, forcing supply chain requalification investments. Stakeholders must monitor how NHTSA's emerging autonomous aircraft guidance intersects with MIL-PRF-123 baseline specifications, as urban air mobility platforms create a new certification category bridging commercial aviation and defence reliability tiers.
Market Dynamics
Reshoring mandates from the US Department of Defense are forcing defence prime contractors to rebuild captive ceramic capacitor supply chains, compressing qualification timelines while elevating dielectric performance thresholds for orbital-grade components.
Growth Catalysts
- ESA ECSS-Q-ST-60-05C qualification tightening:European space standards now mandate 1000-hour life tests and destructive physical analysis, accelerating replacement demand for legacy capacitor inventories across satellite platforms.
- Phased-array radar proliferation:Missile defence and electronic warfare systems require C0G-class temperature-stable formulations with near-zero capacitance drift, multiplying channel counts per platform.
- Commercial space constellation buildouts:Low Earth orbit broadband networks are driving procurement of high-voltage satellite bus capacitors rated for 500+ volt operation.
Market Restraints
- Palladium electrode cost volatility:Precious-metal electrode formulations expose margins to commodity price swings, particularly for Class II X7R dielectrics in high-reliability applications.
- Japanese ceramic powder concentration:Backward integration into barium titanate production concentrates among three suppliers, creating single-source vulnerability for non-integrated capacitor manufacturers.
- DFARS 252.225-7009 sourcing restrictions:US defence clauses limit foreign-sourced ceramic materials, forcing costly supply chain requalification investments for contractors with offshore feedstock dependencies.
Strategic Opportunities
- Urban air mobility certification gap:FAA and NHTSA are developing autonomous aircraft guidance standards that bridge commercial aviation and defence reliability tiers, creating a new component category.
- India defence indigenization:PLI scheme incentives and BIS standards alignment are attracting capacitor manufacturers to establish domestic formulation labs for tactical missile programmes.
- GaN power electronics convergence:Gallium nitride switching frequencies above 100 kHz demand MLCCs with ultra-low equivalent series resistance, opening premium sockets in satellite power conditioning units.
Industry Challenges
- Destructive physical analysis capacity:Lot-by-lot DPA requirements for space-grade components strain specialized metallography and acoustic microscopy infrastructure, extending lead times.
- MIL-PRF-123 baseline migration:Defence contractors face integration complexity when upgrading legacy platforms from established military specifications to newer high-reliability standards without redesigning entire subsystems.
- Ceramic formulation talent scarcity:Deep expertise in dielectric engineering and precious-metal electrode sintering concentrates among retiring specialists, constraining new facility ramp rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defence MLCC Market |
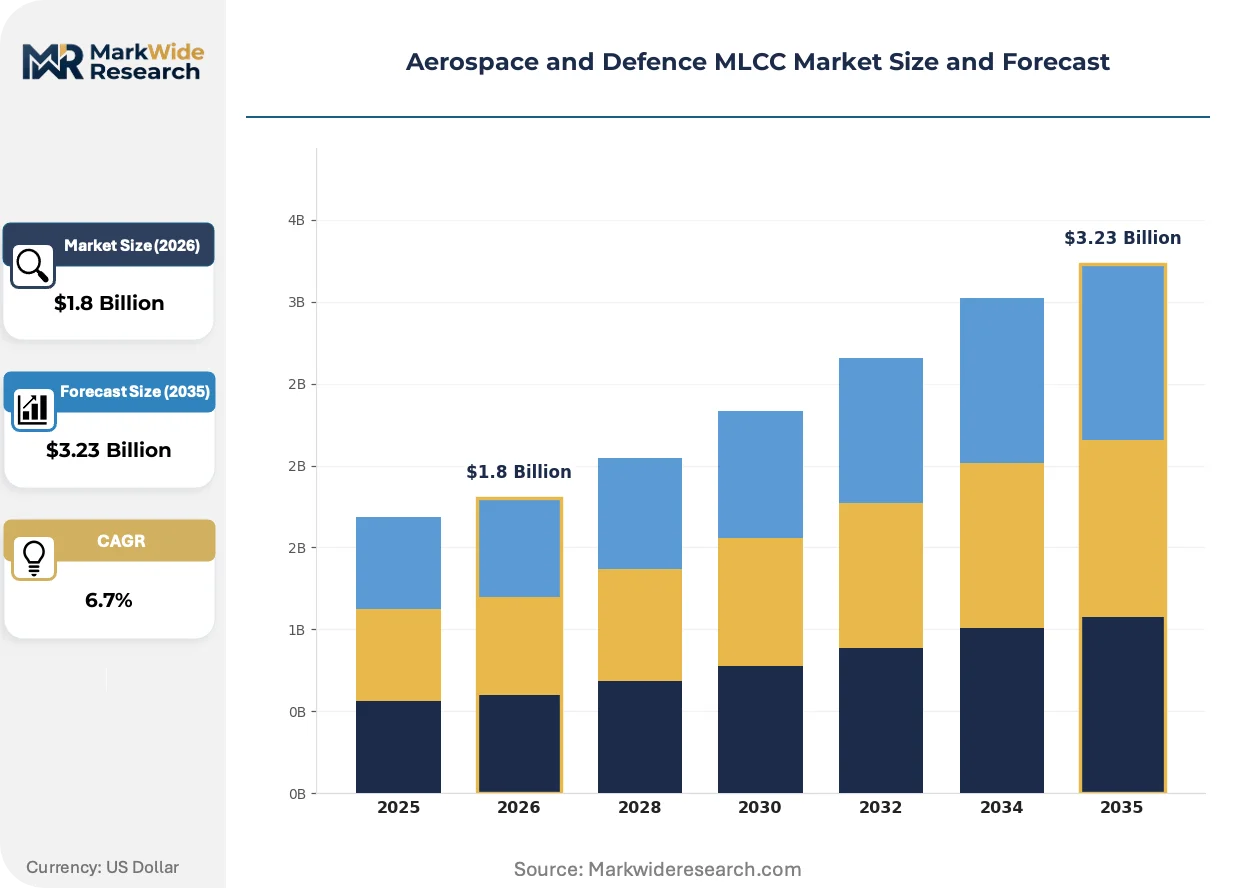
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HighVoltage, HighFrequency, Automotive, GeneralPurpose Application: CommunicationSystems, Radar, Avionics, MissileSystems End User: Military, CommercialAviation, SpaceExploration, DefenceContractors Technology: StandardMLCC, C0G, X7R, Y5V |
| Companies Covered | Murata Manufacturing Co., Ltd., Samsung Electro-Mechanics, Taiyo Yuden Co., Ltd., AVX Corporation, KEMET Corporation, Vishay Intertechnology Inc., Yageo Corporation, Nippon Chemi-Con Corporation, Walsin Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defence MLCC Market Trends and Innovations
Dielectric formulation science and qualification protocol evolution are splitting the aerospace MLCC landscape into distinct performance tiers, with satellite and missile applications diverging from legacy aviation standards.
Base-metal electrode technology is bifurcating the high-reliability segment. Nickel-based electrode systems reduce palladium dependency for cost-sensitive satellite constellations. Commercial space operators adopt these formulations aggressively for disposable LEO platforms. Defence strategic systems retain precious-metal electrodes, creating parallel supply chains with diverging qualification protocols.
REACH and RoHS substance restrictions are tightening electrode material specifications across European space programmes. ECHA candidate list updates now scrutinize nickel nanoparticle emissions from sintering processes. German and French prime contractors are qualifying alternative electrode chemistries ahead of anticipated substance restrictions, compressing development cycles for compliant formulations.
Prime contractors are consolidating vendor lists around qualified second sources. Raytheon and Lockheed Martin now mandate dual-source approval for mission-critical capacitors, displacing sole-source relationships that dominated prior procurement patterns. This concentration is most visible in US missile defence programmes, where DFARS compliance requirements accelerate supplier rationalisation.
Aerospace and Defence MLCC Market Segmentation
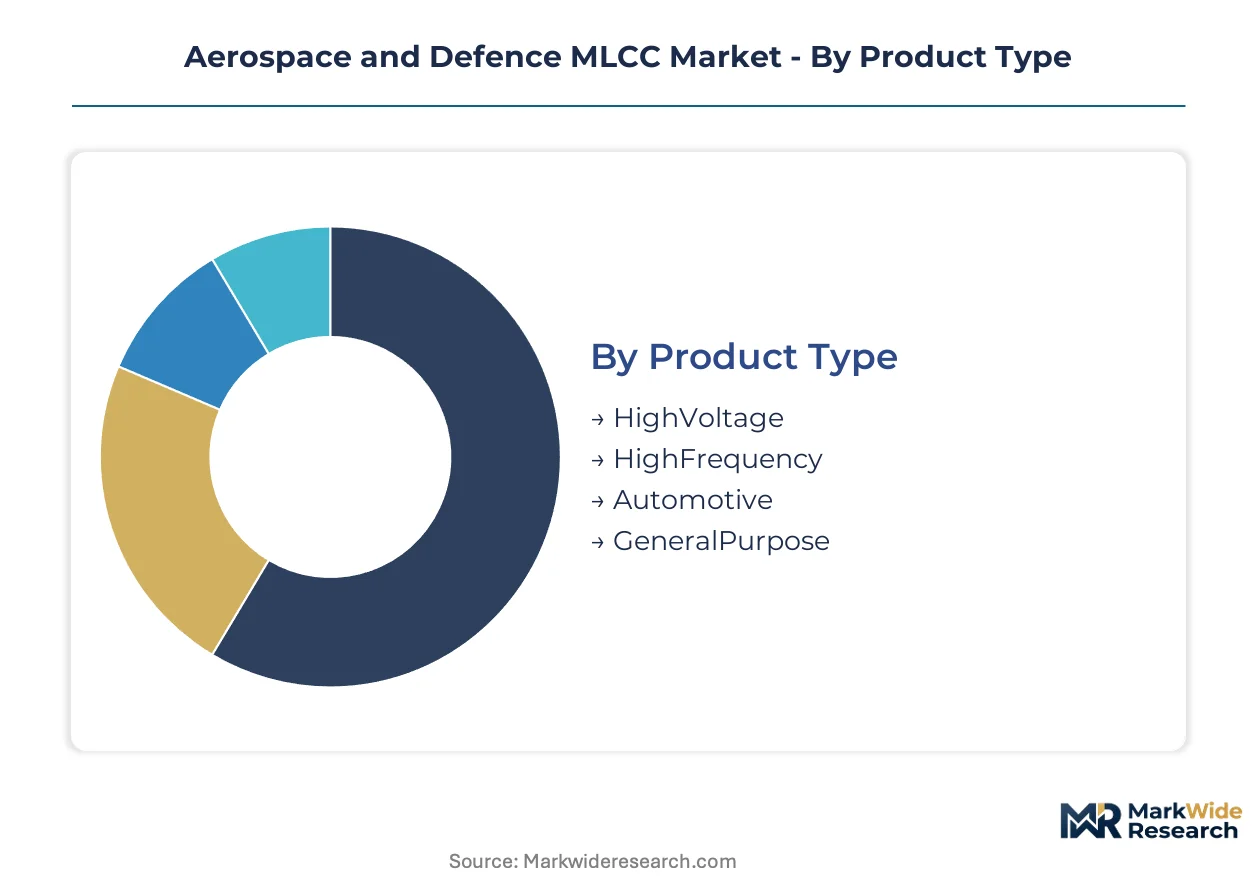
Segmentation in aerospace and defence MLCCs separates qualification-grade components from commercial-grade substitutes. Performance thresholds, precious-metal content, and mission-critical failure consequences create distinct margin architectures across each dimension.
Product Type:
HighVoltage products anchor absolute revenue pools due to satellite power bus requirements and defence prime procurement concentration.
- HighVoltage:These capacitors withstand 500+ volt operation with precious-metal electrodes and Class II dielectric ceramics. Satellite constellation operators in the United States drive procurement volumes as commercial space buildouts accelerate.
- HighFrequency:Engineered for gallium nitride switching frequencies above 100 kHz, these components feature ultra-low equivalent series resistance. GaN power electronics convergence in satellite power conditioning units is concentrating demand here.
- Automotive:Temperature-rated components bridging commercial aviation and ground vehicle specifications serve urban air mobility platforms.
- GeneralPurpose:Standard reliability grades support non-mission-critical avionics subsystems with relaxed qualification burdens.
HighVoltage holds installed capacity. HighFrequency is rotating up the share rankings.
Application:
MissileSystems concentrate the steepest margin premiums where sole-source qualification cycles lock out commodity competitors.
- MissileSystems:Guidance and fuzing applications demand C0G-class temperature stability with near-zero capacitance drift. DFARS compliance requirements and decade-long production runs insulate qualified suppliers from price competition.
- Radar:Phased-array architectures multiply channel counts per platform, driving dielectric performance thresholds upward. Electronic warfare and missile defence programmes in the United States dominate procurement patterns.
- CommunicationSystems:RF filtering and signal conditioning for tactical datalinks require stable capacitance across temperature extremes.
- Avionics:Flight control and navigation electronics operate under FAA airworthiness directives with 1000-hour life test mandates.
Radar captures the largest volume position. MissileSystems is climbing the fastest on margin contribution.
End User:
DefenceContractors control procurement aggregation, with reshoring mandates compressing qualification timelines for captive supply chains.
- DefenceContractors:Prime contractors like Raytheon and Lockheed Martin mandate dual-source approval for mission-critical capacitors, displacing prior sole-source relationships. DFARS 252.225-7009 sourcing restrictions force supply chain requalification investments.
- SpaceExploration:Commercial space operators deploying low Earth orbit broadband networks accelerate high-voltage satellite bus procurement. ESA ECSS-Q-ST-60-05C standards tighten dielectric performance thresholds for orbital-grade components.
- Military:Direct government procurement for strategic systems retains precious-metal electrode formulations with parallel qualification protocols.
- CommercialAviation:Crewed platform suppliers operate under joint FAA and ESA reliability testing burdens with destructive physical analysis requirements.
DefenceContractors dominate contract value. SpaceExploration is expanding most quickly on unit demand.
Technology:
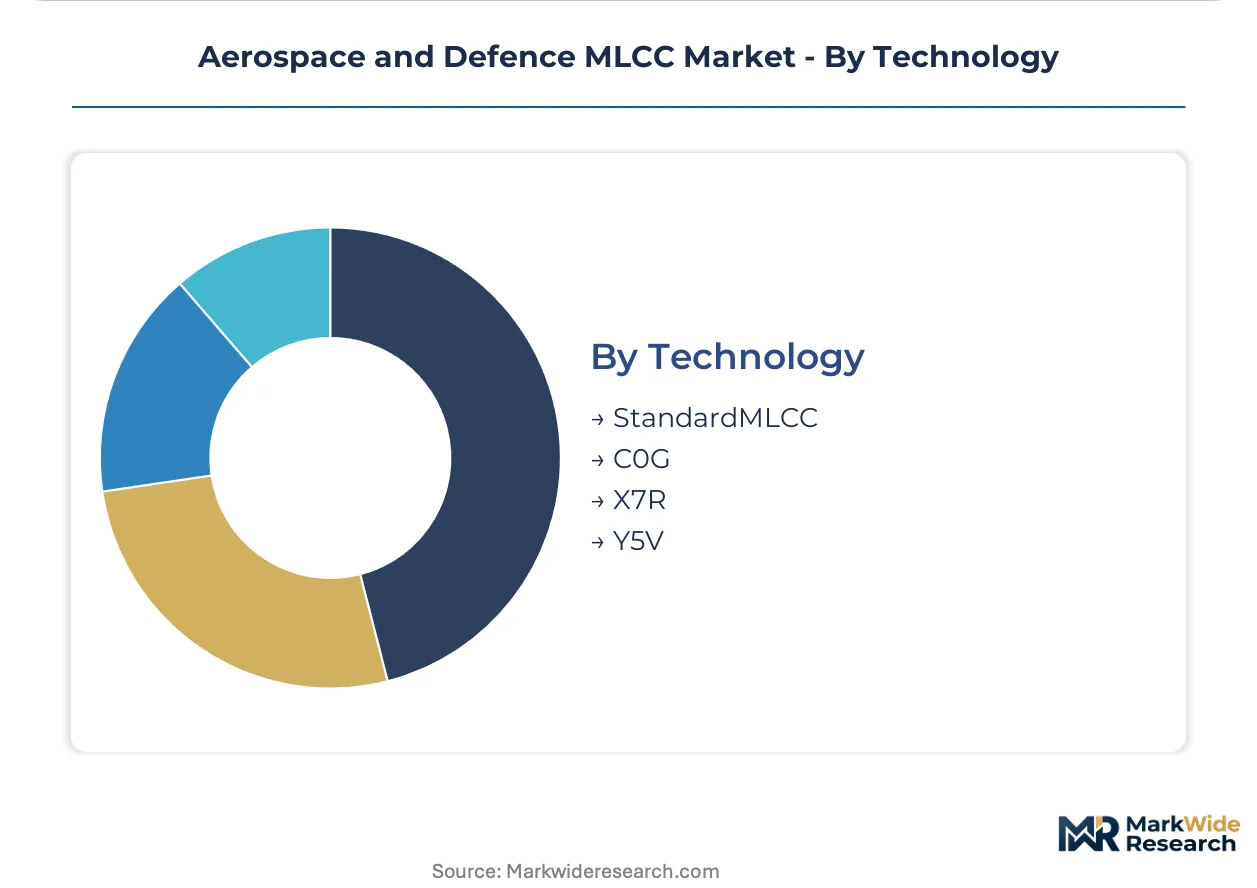
C0G formulations command premium pricing through temperature stability that sustains precision in guidance and radar applications.
- C0G:Class I dielectric ceramics deliver near-zero capacitance drift across minus 55 to 175 degrees Celsius. Phased-array radar channel multiplication and missile guidance precision requirements concentrate demand here.
- X7R:Class II dielectrics balance capacitance density with temperature stability for high-voltage satellite bus applications. Palladium electrode cost volatility exposes margins to commodity price swings.
- StandardMLCC:Baseline reliability grades serve non-critical avionics with reduced qualification overhead.
- Y5V:High-capacitance density formulations suit cost-tolerant consumer-grade applications with limited aerospace penetration.
X7R maintains volume leadership. C0G is gaining share fastest on revenue per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across aerospace MLCC procurement. Commercial satellite operators squeeze margins on high-voltage bus components. Defence strategic systems absorb premiums for C0G-class temperature stability without volume negotiation.
United States
Defence prime contractors drive procurement concentration through reshoring mandates and DFARS 252.225-7009 sourcing restrictions. The Department of Defense accelerates supply chain requalification timelines for captive ceramic capacitor production. Huntsville, Alabama hosts missile defence programme offices where sole-source qualification cycles lock in decade-long supplier relationships.
Japan
Integrated manufacturers control backward integration into barium titanate ceramic powder production. METI industrial policy supports domestic formulation lab capacity for high-reliability dielectric engineering. Kyoto-Osaka corridor concentrates precious-metal electrode sintering expertise that retiring specialists struggle to replace.
Germany
REACH and RoHS substance restrictions tighten electrode material specifications for European space programmes. ECHA candidate list scrutiny of nickel nanoparticle emissions compresses development cycles for compliant formulations. Munich aerospace cluster primes alternative electrode chemistry qualification ahead of anticipated regulatory tightening.
France
Thales and Safran prime contractors consolidate vendor lists around dual-source approval mandates for mission-critical capacitors. ANSM and CNIL data governance intersects with space component traceability requirements. Toulouse space industry concentration faces ESA ECSS-Q-ST-60-05C qualification tightening for orbital-grade dielectric performance thresholds.
India
PLI scheme incentives attract capacitor manufacturers to establish domestic formulation labs for tactical missile programmes. BIS standards alignment accelerates defence indigenization procurement preferences. Bengaluru-Telangana corridor concentrates emerging electronics manufacturing capacity targeting import substitution for strategic passive components.
Aerospace and Defence MLCC Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in aerospace MLCC supply. Japanese and Korean manufacturers dominate high-reliability dielectric formulation through captive ceramic powder production. Three strategic archetypes emerge: vertically integrated material-to-component producers, precious-metal electrode specialists, and satellite-optimized high-voltage fabricators. Competitive moves concentrate on dual-source qualification partnerships and ESA-compliant destructive physical analysis capacity expansion.
Within the integrated leader tier, Murata Manufacturing Co., Ltd. and Samsung Electro-Mechanics exemplify divergent approaches to supply chain control. Taiyo Yuden Co., Ltd. occupies a specialist position anchored in temperature-stable C0G-class formulations. These three Japanese and Korean entities represent the dominant geographic concentration in aerospace-grade passive component supply.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Samsung Electro-Mechanics |
| Taiyo Yuden Co., Ltd. |
| AVX Corporation |
| KEMET Corporation |
| Vishay Intertechnology Inc. |
| Yageo Corporation |
| Nippon Chemi-Con Corporation |
| Walsin Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week lead times for ESA-qualified C0G formulations concentrate pricing power among Japanese ceramic powder producers while compressing margin flexibility for non-integrated capacitor manufacturers dependent on outsourced dielectric feedstock.
Pricing Analysis
After-sales qualification support and decade-long production run warranties drive lifetime value more than unit pricing for defence prime contractors. Pricing stratifies across mission-critical, high-reliability, and standard avionics tiers based on DFARS compliance certification and destructive physical analysis inclusion. Cost compression in commercial satellite constellations intensifies as LEO operators negotiate nickel-based electrode formulations against palladium alternatives. Commercial space buyers exhibit highest price sensitivity; missile defence programmes absorb premiums without volume negotiation.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes expose inbound logistics costs for barium titanate ceramic powder shipments. Manufacturing concentrates in Japan, South Korea, and the United States. Production draws from palladium electrode formulations, nickel nanoparticle alternatives, and high-purity ceramic substrates. Single-source vulnerability concentrates in Japanese barium titanate production among three integrated suppliers. Distribution runs through defence prime contractor approved vendor lists with dual-source mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defence against solid-state capacitor technologies and thin-film alternatives encroaching on precision timing applications.
For Market Incumbents: Consolidate backward integration into ceramic powder production to insulate margins from palladium volatility and Japanese feedstock concentration. Lock in dual-source qualification partnerships with Raytheon and Lockheed Martin before DFARS requalification windows close. Prioritise ESA-compliant destructive physical analysis capacity expansion.
For New Entrants and Emerging Players: Anchor in India's PLI scheme incentives for domestic formulation labs serving tactical missile programmes. Target Bengaluru-Telangana corridor electronics manufacturing clusters with BIS standards-aligned qualification pathways. Pursue urban air mobility certification gap as FAA-NHTSA autonomous aircraft guidance standards crystallise.
For Investors and Strategic Acquirers: Carve-out targets emerge from defence prime contractor captive capacitor divisions facing reshoring mandate execution pressure. Five-to-ten year viability hinges on qualification cycle duration rather than manufacturing scale. Monitor GaN power electronics adoption above 100 kHz as inflection signal for ultra-low ESR premium socket expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Qualification Partnership | Lockheed Martin and Raytheon mandates displace sole-source supplier relationships. |
| Backward Integration into Ceramic Powder | Samsung Electro-Mechanics model insulates margins from barium titanate volatility. |
| ESA-Compliant DPA Capacity Expansion | ECSS-Q-ST-60-05C tightening strains metallography and acoustic microscopy infrastructure. |
| Urban Air Mobility Certification Positioning | FAA-NHTSA autonomous aircraft guidance bridges commercial aviation and defence reliability tiers. |
| India Domestic Formulation Lab Establishment | PLI scheme incentives and BIS alignment accelerate defence indigenization procurement. |
Research Methodology
Desk research of ESA ECSS standards documentation, DFARS clause compilations, and satellite constellation operator procurement disclosures preceded structured interviews with defence prime contractor sourcing directors, ceramic formulation lab technical leads, space qualification test facility managers, and commercial space operator supply chain executives. Secondary validation drew from FAA airworthiness directive filings, METI industrial policy briefings, and BIS standards registry updates. Bottom-up segment sizing triangulated against top-down procurement aggregation estimates.
Variance decomposition across product type, application, end user, and technology dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segment-level unit demand trajectories and pricing band migrations. GaN switching frequency adoption curves and satellite constellation deployment schedules served as aerospace-specific forecast inputs alongside palladium price scenario modelling.
Material uncertainties — ECHA substance restriction timing, DFARS clause scope expansion, and ceramic formulation specialist retirement rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about qualification cycle duration and dual-source mandate enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market