
 Spain Satellite Imagery Services Market | 2026-2036
Spain Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Satellite Imagery Services Market Insights
Spanish orbital data providers is repositioning toward higher-resolution commercial offerings. Hisdesat leverages its government contracting relationships to anchor defense and security applications. Satlantis specializes in compact high-performance optical payloads for emerging smallsat constellations. Elecnor Deimos competes through end-to-end mission control and ground segment integration capabilities.
Satellite imagery services encompass the acquisition, processing, and analytic delivery of Earth observation data captured by orbiting sensors, typically achieving spatial resolutions below one meter for commercial optical systems and operating across microwave frequencies for synthetic aperture radar platforms. These services support decision-making in agriculture, infrastructure, and environmental management by transforming raw sensor data into georeferenced intelligence products. Custom analytics and on-demand imagery currently command premium pricing due to specialized processing requirements and low latency delivery needs. Optical imaging dominates commercial volumes while radar imaging penetrates cloud-covered and nighttime operational environments where optical sensors fail.
Spain's space activities fall under the National Institute for Aerospace Technology oversight, with EU Copernicus regulations mandating free and open data policies that shape public-sector procurement frameworks. The Spanish Data Protection Agency and EU GDPR impose strict handling requirements on geospatial datasets containing identifiable features, directly influencing service provider data governance architectures. Stakeholders must monitor how Spain's evolving national security classification protocols affect foreign satellite operator market access and domestic imagery resale restrictions.
Market Dynamics
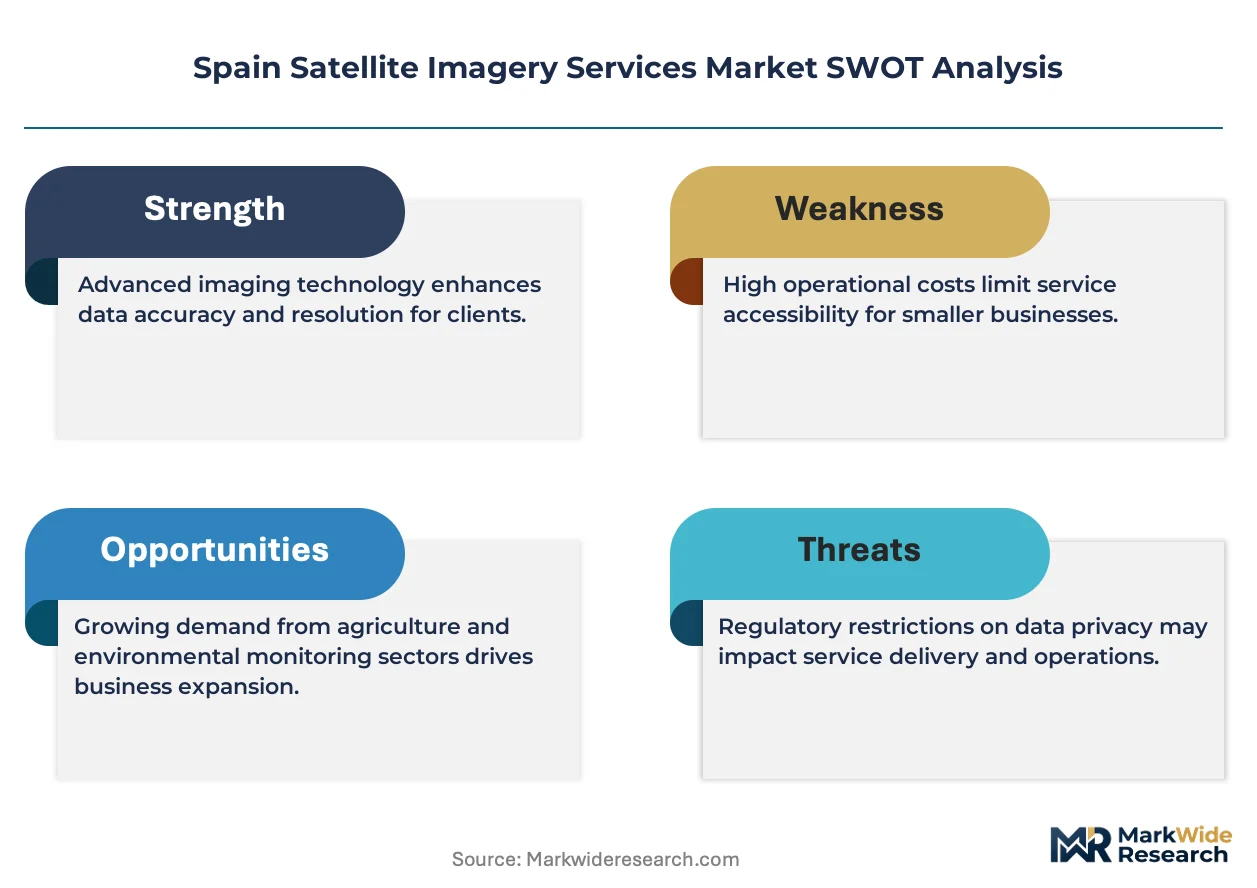
Spain's satellite imagery market is restructuring around the tension between EU Copernicus free data mandates and commercial providers' push toward premium analytics. This collision between public subsidy and private value-add is compressing raw data margins while expanding the addressable market for processed intelligence.
Growth Catalysts
- EU Copernicus Participation:Spain's integration into the Sentinel constellation program guarantees institutional buyers a baseline data stream. This foundation reduces customer acquisition costs for analytics vendors layering proprietary algorithms atop open archives.
- Precision Agriculture Expansion:Andalusia's olive and citrus cooperatives now mandate sub-meter resolution for irrigation optimization. Cooperative procurement pools aggregate demand that individual farms could not sustain independently.
- SmallSat Constellation Economics:Miniaturized optical payloads are collapsing launch cost barriers. Spanish payload specialists now contract with global constellation operators seeking European ground segment partners.
Market Restraints
- Input Cost Volatility:Launch slot pricing fluctuates with Ariane 6 schedule delays and SpaceX manifest congestion. Operators dependent on rideshare arrangements face mission timeline uncertainty.
- Technical Limitation:Optical sensors fail under persistent Iberian cloud cover during autumn and winter storm patterns. Radar penetration remains cost-prohibitive for mid-market agricultural buyers.
- Regulatory Friction:Spain's National Intelligence Centre classification protocols restrict foreign satellite operators from capturing imagery over military installations. Domestic resale of such data requires explicit authorization.
Strategic Opportunities
- Underpenetrated Geography:Extremadura and Castilla-La Mancha farming regions lag Andalusia in precision agriculture adoption. Regional development funds now subsidize first-time satellite data subscriptions for cooperative members.
- Technology Convergence:Synthetic aperture radar is fusing with IoT soil moisture sensors. Integrated platforms offer predictive irrigation recommendations that standalone imagery cannot match.
- Regulatory Tailwind:Spain's National Recovery and Resilience Plan allocates dedicated funding for Earth observation infrastructure. Public procurement thresholds for climate monitoring services have expanded substantially.
Industry Challenges
- Skill Concentration:Remote sensing analytics expertise clusters in Madrid and Barcelona. Providers seeking ground station operators in secondary cities face recruitment friction and compensation inflation.
- Integration Complexity:Legacy farm management software in Catalonia's wine cooperatives lacks API compatibility with modern satellite data feeds. Custom middleware development extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Satellite Imagery Services Market |
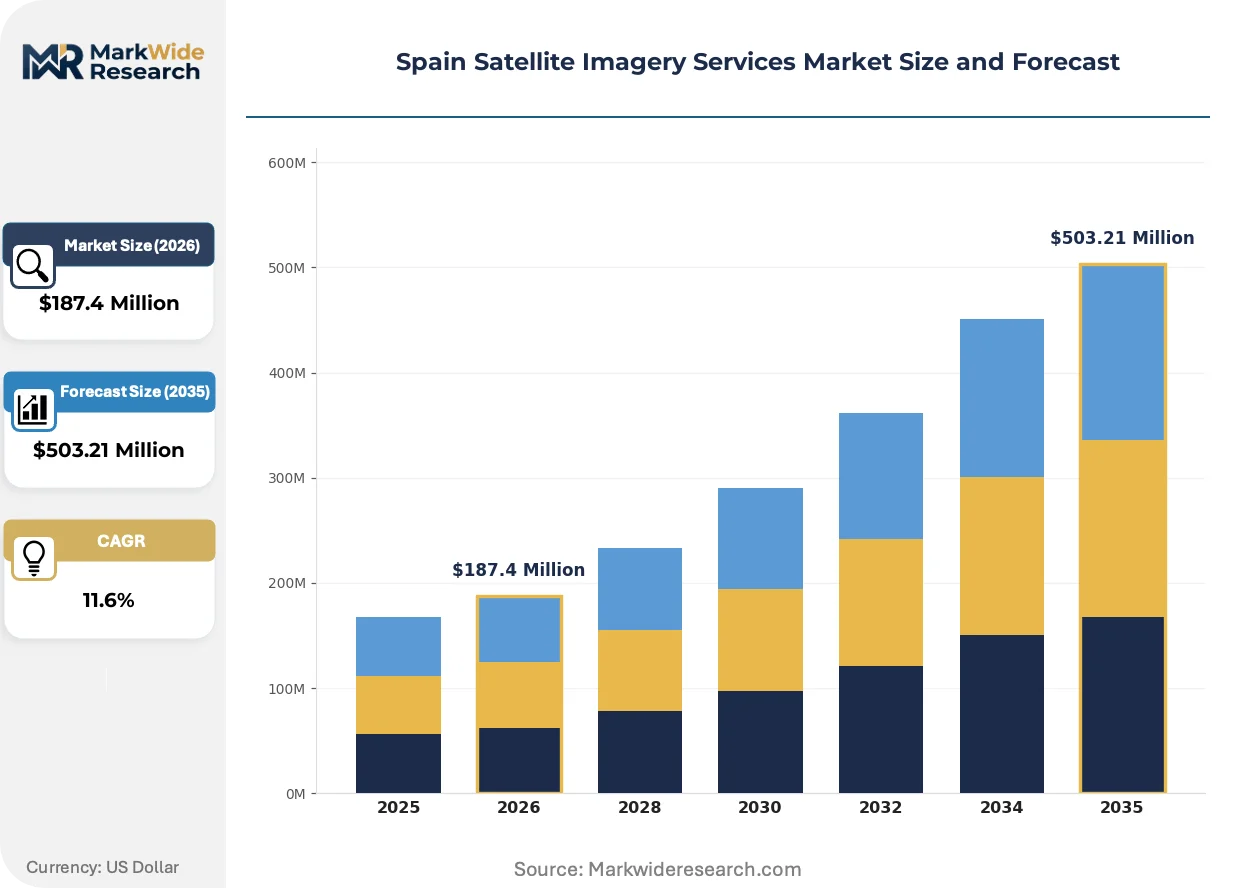
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-demand Imagery, Fixed Schedule Imagery, Custom Analytics, Historical Data Access Industry Vertical: Agriculture, Urban Planning, Environmental Monitoring, Defense Technology: Optical Imaging, Radar Imaging, Multispectral Sensors, Hyperspectral Sensors End User: Government Agencies, Research Institutions, Private Enterprises, NGOs |
| Companies Covered | European Space Imaging (EUSI) GmbH, Hisdesat, Satlantis, Telespazio Iberica, Elecnor Deimos, Airbus SE, Satellite Imaging Corporation, GMV, Geocento, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Satellite Imagery Services Market Trends and Innovations
Spanish satellite imagery services are pivoting from raw data resale toward embedded analytics. This transition demands new competencies in machine learning operations and sector-specific algorithm training.
Compact high-performance optical payloads are electrifying the smallsat value chain. Satlantis and comparable Spanish developers now supply cameras under 10 kilograms that match traditional 100-kilogram instrument resolution. Constellation operators in North America and Asia-Pacific are integrating these payloads into rapid-revisit architectures. The technology is electrifying competitive dynamics by enabling European providers to bypass launch capacity constraints through component exports rather than full-mission ownership.
Spain's national space strategy mandates alignment with EU Green Deal monitoring requirements. The policy framework compels domestic operators to prioritize carbon sequestration verification and deforestation detection capabilities. Agricultural insurance underwriters and carbon credit certifiers represent the fastest-adopting customer segments responding to these disclosure pressures.
Subscription-based data access is displacing per-image transactional purchasing among large farming cooperatives. Andalusia's leading olive oil producers now negotiate annual unlimited-access contracts with analytics providers. This shift compresses revenue volatility for vendors while locking buyers into single-source relationships that resist competitive switching.
Spain Satellite Imagery Services Market Segmentation
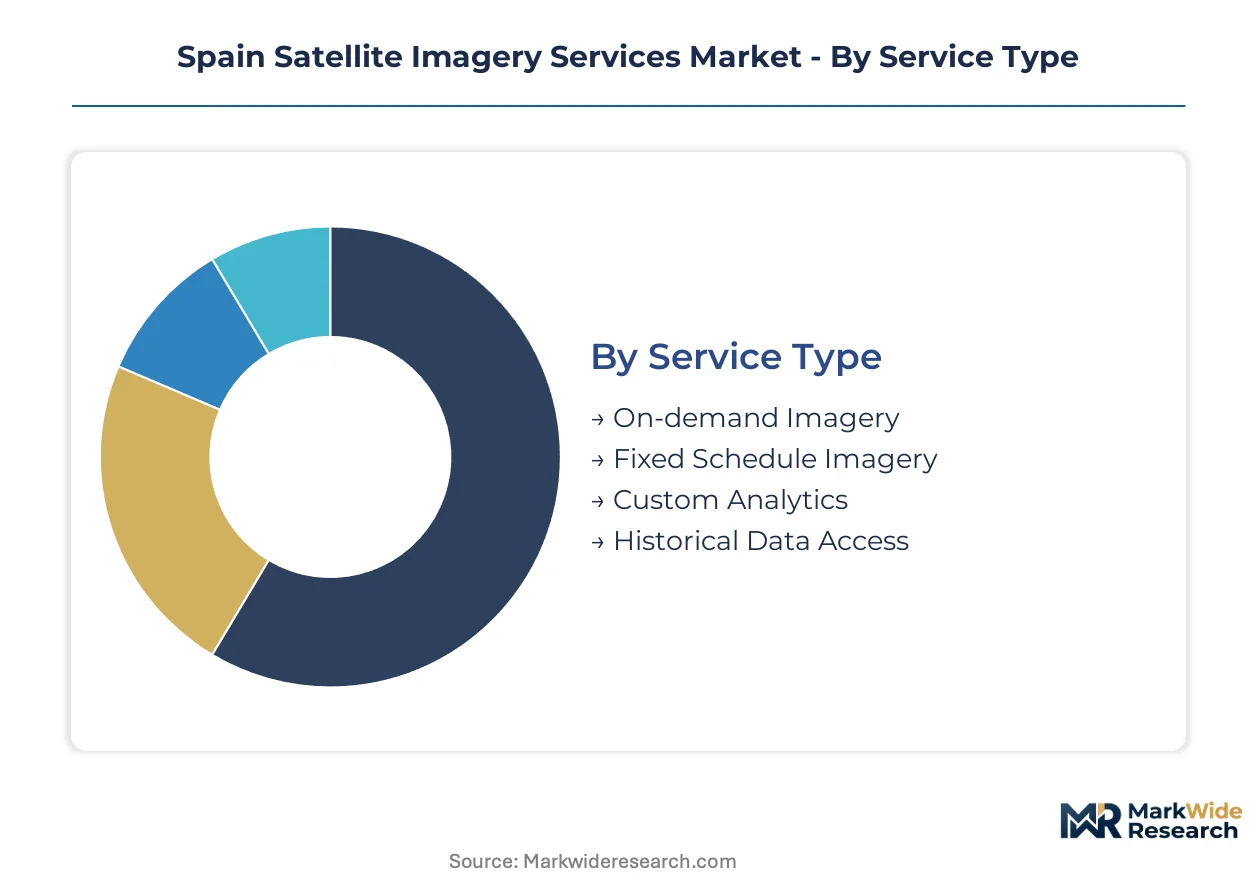
Spain's satellite imagery market segments along four distinct axes that shape procurement patterns and vendor positioning. Service delivery models, sensor technologies, industry applications, and buyer categories each create separate competitive battlegrounds with divergent margin profiles and growth trajectories.
Service Type:
Resolution and revisit frequency specifications determine pricing architecture across service tiers.
- On-demand Imagery:Tasking satellites for specific capture windows delivers sub-meter resolution within 24-48 hours. Premium latency commands elevated pricing from Catalonia's emergency response agencies and insurance underwriters assessing storm damage.
- Fixed Schedule Imagery:Pre-programmed acquisition cycles at weekly or bi-weekly intervals support longitudinal change detection. Andalusia's olive cooperatives anchor demand for predictable, cost-averaged data streams that enable seasonal crop health benchmarking.
- Custom Analytics:Machine learning pipelines transform raw pixels into actionable intelligence products. Yield prediction algorithms and deforestation detection models layer proprietary value atop baseline imagery.
- Historical Data Access:Archive subscriptions unlock decades of Earth observation records for trend analysis. Climate researchers and legal dispute resolution teams mine temporal sequences for baseline establishment.
Fixed Schedule Imagery leads on scale; Custom Analytics leads on momentum.
Industry Vertical:
Application-specific performance requirements fragment vendor specialization across end-use domains.
- Agriculture:Precision farming applications dominate Spanish commercial demand. Irrigation optimization and pest early warning systems drive subscription renewals across Extremadura and Castilla-La Mancha cooperative networks.
- Urban Planning:Cadastral updating and informal settlement detection absorb public sector budgets. Barcelona and Madrid municipal authorities procure annual coverage for zoning enforcement and infrastructure change tracking.
- Environmental Monitoring:EU Green Deal compliance obligations accelerate procurement from carbon credit verifiers and rewilding project managers. Wildfire scar mapping and coastal erosion quantification represent expanding use cases.
- Defense:Hisdesat's government relationships anchor classified requirements for border surveillance and maritime domain awareness. Spain's National Intelligence Centre classification protocols restrict foreign operator participation in this vertical.
Agriculture leads on scale; Environmental Monitoring leads on momentum.
Technology:
Sensor physics and atmospheric penetration capabilities determine operational envelope and cost structure.
- Optical Imaging:Panchromatic and multispectral sensors capture reflected sunlight across visible and near-infrared wavelengths. Iberian autumn cloud cover intermittently degrades utility, constraining year-round reliability for agricultural buyers.
- Radar Imaging:Synthetic aperture radar penetrates cloud and darkness through active microwave illumination. Maritime surveillance and all-weather infrastructure monitoring justify premium pricing despite higher processing complexity.
- Multispectral Sensors:Discrete band capture enables vegetation index calculation and mineral discrimination. Standardized products like NDVI support commoditized analytics pricing across broad agricultural markets.
- Hyperspectral Sensors:Continuous narrow-band sampling detects subtle spectral signatures for specialized applications. Soil composition analysis and invasive species identification remain niche due to data volume and interpretation expertise requirements.
Optical Imaging leads on scale; Radar Imaging leads on momentum.
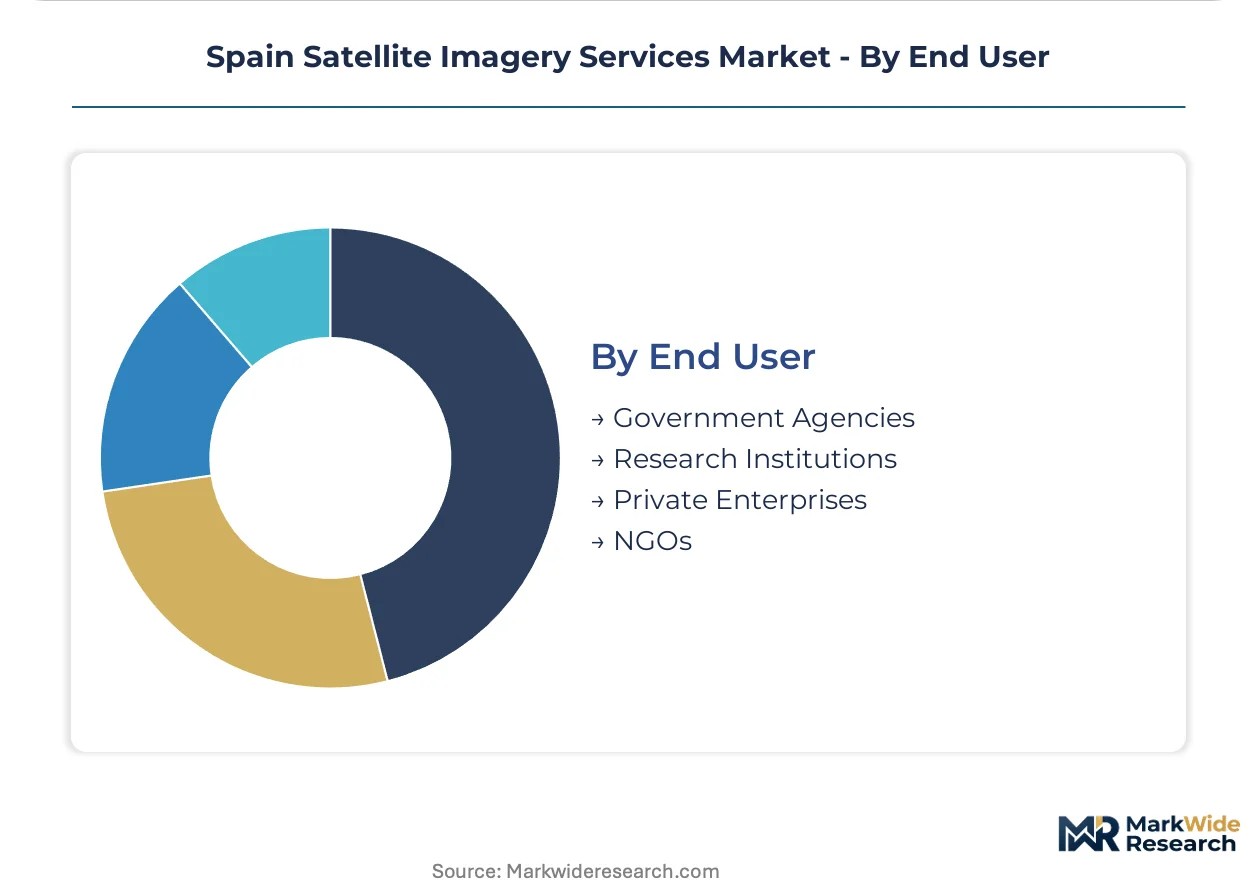
End User:
Procurement authority and budget stability segment buyer behavior and contract structure preferences.
- Government Agencies:National and regional administrations leverage EU Copernicus free data mandates while purchasing premium analytics. Spain's National Recovery and Resilience Plan has expanded climate monitoring procurement thresholds substantially.
- Research Institutions:Universities and national laboratories access subsidized academic licensing for methodological development. Barcelona Supercomputing Center and comparable facilities drive algorithm innovation that eventually commercializes.
- Private Enterprises:Agricultural conglomerates, insurance carriers, and commodity traders represent the fastest-expanding commercial segment. Subscription-based unlimited access contracts now displace per-image purchasing among large farming cooperatives.
- NGOs:Conservation organizations and humanitarian responders operate on constrained budgets favoring open data archives. Custom analytics partnerships with academic intermediaries stretch limited funding.
Government Agencies lead on scale; Private Enterprises lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's satellite imagery services sector exhibits regulatory-arbitrage dynamics as compliance costs and data governance requirements concentrate procurement authority in specific sub-regions. Public-sector buyers migrate toward jurisdictions with streamlined EU Copernicus integration and established ground infrastructure.
Andalusia
Olive oil cooperatives and citrus farming collectives drive commercial demand for precision agriculture subscriptions. The Junta de Andalucía's regional innovation fund subsidizes first-time satellite data adoption for irrigation optimization. Seville anchors a cluster of agritech intermediaries translating raw imagery into cooperative-facing yield analytics.
Catalonia
Barcelona's smart city pilot programs absorb municipal budgets for cadastral updating and informal settlement detection. The Catalan Data Protection Authority enforces GDPR-aligned handling protocols for geospatial datasets containing identifiable infrastructure. The Barcelona Supercomputing Center trains machine learning models that commercialize through local analytics vendors.
Madrid
National space strategy implementation and defense procurement concentrate in the capital region. Spain's National Institute for Aerospace Technology oversees licensing frameworks that shape operator market access. The Madrid metropolitan area hosts Hisdesat and Elecnor Deimos headquarters, anchoring government contracting relationships for classified imagery requirements.
Basque Country
Advanced manufacturing and maritime surveillance applications generate specialized radar imaging demand. The Basque Government's climate action plan funds coastal erosion monitoring through Earth observation service contracts. Bilbao's port authority procures all-weather vessel tracking capabilities that optical sensors cannot provide.
Valencia
Citrus export cooperatives and agricultural insurance underwriters represent emerging commercial adopters. The Valencian Institute of Business Competitiveness channels EU recovery funds toward precision farming technology adoption. Valencia's logistics corridor generates freight infrastructure monitoring demand from port operators and highway concessionaires.
Spain Satellite Imagery Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue component specialization and analytics layering. The vendor base stratifies across full-mission operators, payload developers, and ground segment integrators. Three archetypes dominate: government-anchored defense contractors, compact payload specialists supplying global constellations, and end-to-end mission control providers. Competitive dynamics center on strategic partnerships for launch access and portfolio diversification into carbon verification services.
Within the government-contractor archetype, Hisdesat exemplifies institutional relationship leverage for classified requirements. Satlantis occupies a position among compact payload developers exporting cameras to North American and Asia-Pacific constellation operators. Elecnor Deimos anchors the mission-control tier through ground segment integration capabilities that span full operational lifecycles.
| Leading Market Players |
|---|
| European Space Imaging (EUSI) GmbH |
| Hisdesat |
| Satlantis |
| Telespazio Iberica |
| Elecnor Deimos |
| Airbus SE |
| Satellite Imaging Corporation |
| GMV |
| Geocento |
| Others |
Pricing and Supply Chain Analysis
Captive ground segment integration by Spanish operators anchors both infrastructure control and pricing power in the satellite imagery value chain. Hisdesat and Elecnor Deimos leverage in-house mission control capabilities to bypass third-party ground station fees, compressing cost structures while preserving margin on premium analytics.
Pricing Analysis
Direct-to-cooperative subscriptions bypass intermediary agritech platforms that previously extracted 15-30% markups. Three-tier pricing structure across premium, standard, and economy levels stratifies by resolution grade and latency guarantee. Cost compression in the standard tier intensifies because EU Copernicus free data undercuts raw imagery resale. Agricultural cooperatives in Extremadura exhibit highest price sensitivity; defense and security buyers demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale constellation operator demand for compact optical payloads. Manufacturing concentrates in Spain, Germany, and the United States for precision optical components. Supply draws from gallium arsenide semiconductors, carbon fiber structures, and radiation-hardened electronics. Single-source vulnerability persists in synthetic aperture radar component supply. Distribution runs through ground station networks and cloud-based analytics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's satellite imagery market reads as a late-cycle quality story where cooperative buyers now mandate sub-meter resolution and predictive analytics as baseline procurement requirements.
For Market Incumbents: Anchor government contracting relationships through Hisdesat's institutional model while expanding carbon verification service portfolios. Threat from emerging smallsat constellation operators compressing revisit latency requires defensive investment in machine learning operations. Backward integration into compact payload manufacturing preserves margin on hardware exports to Asia-Pacific constellation builders. For New Entrants: Regional development agencies in Extremadura and Castilla-La Mancha represent the most penetrable channel partner type for first-mover positioning. White-space targets include subsidized precision agriculture adoption in lagging regions and radar-IoT fusion for predictive irrigation. Go-to-market through cooperative procurement pools aggregates fragmented farm-level demand. For Investors and Strategic Acquirers: Roll-up economics work for ground segment integrators because fragmented regional analytics vendors lack mission control capabilities. Long-term viability centers on 5-10 year subscription lock-in with agricultural cooperatives. Acquisition target archetype: agritech intermediaries with established cooperative relationships but no satellite tasking infrastructure. Signal to watch: EU Green Deal disclosure mandates accelerating carbon credit verifier procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Compact Payload Export Partnership | Spanish camera suppliers penetrate North American constellation architectures through component licensing. |
| Carbon Verification Service Launch | Agricultural insurance underwriters adopt satellite-based sequestration quantification for policy pricing. |
| Cooperative Subscription Aggregation | Andalusian olive collectives negotiate multi-year unlimited access contracts locking vendor relationships. |
| Ground Station Network Expansion | Elecnor Deimos extends mission control capabilities to Asia-Pacific constellation operators. |
| Radar-IoT Platform Integration | Basque maritime authorities procure all-weather vessel tracking fused with sensor network data. |
Research Methodology
Direct dialogue with satellite operators, agritech platform executives, cooperative procurement managers, and defense contracting officers grounded qualitative findings. Secondary validation drew from EU Copernicus program documentation, Spain's National Recovery and Resilience Plan allocations, INTA licensing frameworks, and customs records for optical component trade. Bottom-up and top-down triangulation reconciled subscription revenue estimates with regional agricultural output value.
Bottom-up modeling segmented by service type, sensor technology, industry vertical, and end-user category across the analysis window. Analytical framework incorporated precision agriculture adoption curves, defense procurement thresholds, and EU Green Deal compliance timelines. CAGRs derived from weighted average of segment growth trajectories and input cost elasticity assumptions.
Revisions become necessary when Ariane 6 schedule delays extend launch capacity constraints or when Spain's National Intelligence Centre tightens foreign operator imagery restrictions. Forecasts reflect assumptions on cooperative subscription renewal rates and carbon credit market liquidity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Electric Propulsion Satellite Market
Satellite
Global Dish Antennas Market
Satellite
Satellite Communication Subsystem Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
ASEAN Satellite-Based Earth Observation Market
Satellite
North America Satellite Launch Vehicle Market
Satellite
Russia Satellite Connectivity Market
Satellite
Italy Satellite Imagery Services Market
Satellite
North America Small Satellite Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Russia Satellite Imagery Services Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
UAE Satellite Communication Market