
 Global Artificial Intelligence and Analytics in Defense Market | 2026-2036
Global Artificial Intelligence and Analytics in Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence and Analytics in Defense Market Foresight
Software-defined predictive maintenance and algorithm subscription layers is rebalancing how defense agencies acquire AI capabilities, shifting capital expenditure toward recurring operational budgets. Lockheed Martin Corporation leverages its classified R&D infrastructure to anchor long-term analytics contracts with U.S. combatant commands. Palantir Technologies Inc. differentiates through hardened government cloud integrations that sustain multi-year intelligence community relationships. BAE Systems plc navigates transatlantic procurement requirements to occupy distinctive positions across British and allied defense ministries.
Artificial intelligence and analytics in defense encompasses machine learning platforms, computer vision systems, and natural language processing tools engineered to process multi-source intelligence at classification levels ranging from unclassified to TS/SCI, with latency requirements often below 100 milliseconds for tactical edge deployments. The primary purpose centers on accelerating operational decision cycles while reducing cognitive burden on command personnel under contested electromagnetic environments. Threat detection applications currently lead solution deployment, though autonomous systems represent the fastest-expanding category as unmanned platform swarming protocols mature. Hybrid deployment models capture expanding budget allocations as militaries reconcile data sovereignty requirements with cloud scalability.
The U.S. Department of Defense, the European Defence Agency, and NATO's AI Strategy implementation bodies collectively shape market access through ethical algorithm certification, cross-border data sharing protocols, and foreign ownership screening. These frameworks compel vendors to maintain segregated supply chains and audit trails that satisfy divergent national security classifications. Stakeholders must monitor how emerging sovereign AI requirements in allied nations fragment procurement standards and reshape partnership structures.
Market Dynamics
Defense procurement officers are abandoning perpetual software licenses in favor of algorithm-as-a-service subscriptions, compressing vendor cash cycles while embedding analytics deeper into operational workflows. This shift from capital to operational expenditure is restructuring contract terms, technical integration requirements, and supplier qualification criteria across NATO procurement frameworks.
Growth Catalysts
- Algorithm-as-a-Service Models:Subscription-based predictive maintenance platforms allow combatant commands to refresh machine learning models without hardware refresh cycles, accelerating capability iteration.
- EU AI Act Implementation:Mandatory conformity assessments for high-risk AI systems are creating certified vendor pools that reduce procurement friction for compliant solution providers.
- Multi-Domain Operations Doctrine:Joint force integration requirements across air, land, sea, space, and cyber domains are mandating unified data fabrics that only AI-enabled analytics can populate.
Market Restraints
- TS/SCI Clearance Bottlenecks:Personnel vetting backlogs at U.S. Defense Counterintelligence and Security Agency stretch 18-24 months, constraining vendor workforce scaling.
- Specialized Silicon Dependency:Custom AI accelerators from Taiwan Semiconductor Manufacturing Company and Samsung Foundry face export control uncertainty under U.S. Department of Commerce regulations.
- Data Sovereignty Fragmentation:Divergent national cloud certification requirements between U.S. FedRAMP, UK NCSC, and German BSI standards force redundant infrastructure investments.
Strategic Opportunities
- Swarm Autonomy Protocols:Unmanned aerial system swarming for electronic warfare applications remains underdeveloped, offering first-mover advantages in distributed kill chains.
- India Defense AI Roadmap:The Ministry of Defence's AI task force is channeling procurement toward indigenous-foreign joint ventures with technology transfer mandates.
- Synthetic Training Environments:Generative adversarial networks for synthetic intelligence generation are converging with virtual reality platforms to reduce live exercise costs.
Industry Challenges
- Adversarial ML Expertise Scarcity:Defense contractors face acute shortages of personnel skilled in robustness testing against adversarial attacks on neural networks.
- Cross-Domain Integration Complexity:Legacy command-and-control systems built on stovepiped architectures resist API-based interoperability with modern analytics stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence and Analytics in Defense Market |
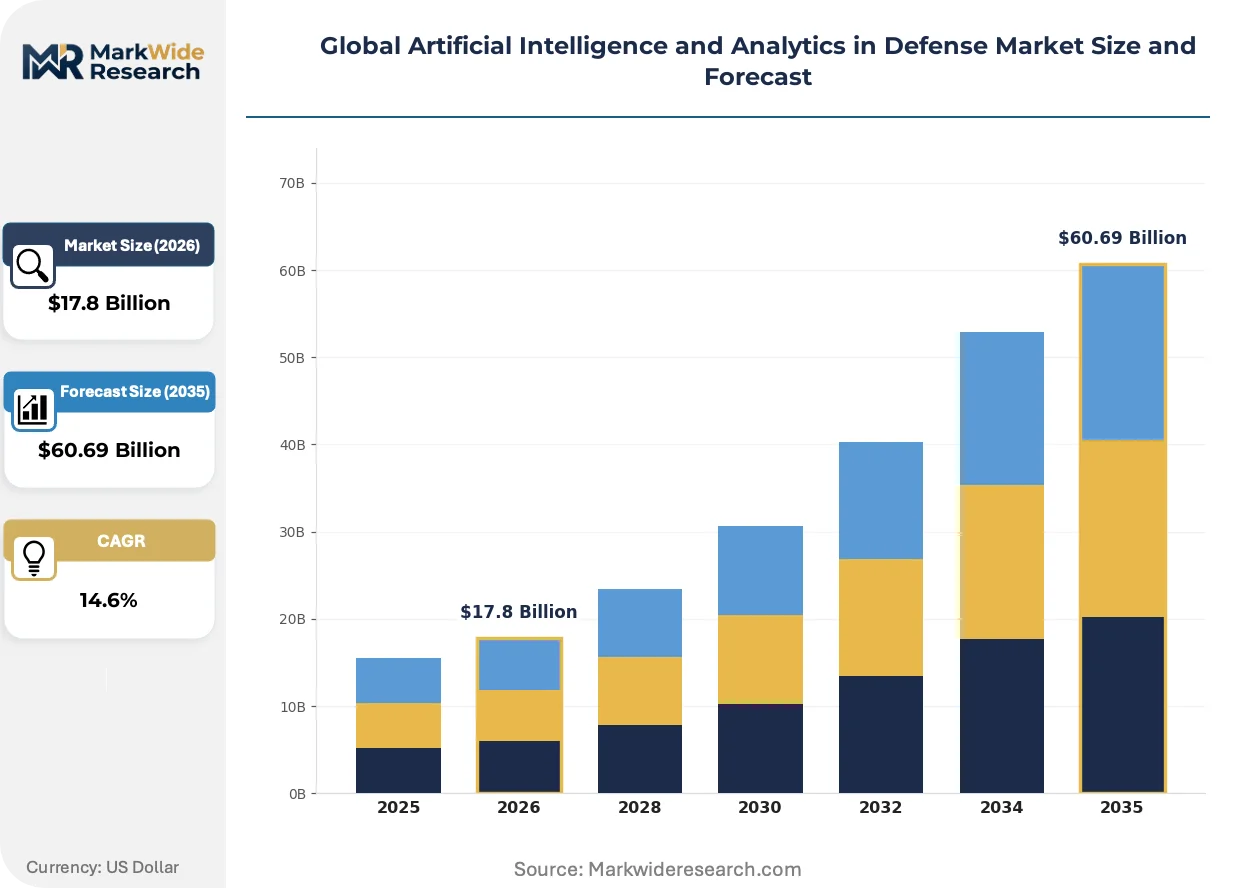
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $60.69 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Threat Detection, Autonomous Systems, Cybersecurity, Surveillance, Decision Support Solution Type: Predictive Analytics, Natural Language Processing, Computer Vision, Neural Networks, Machine Learning Platforms Deployment Model: On-premises, Cloud-based, Hybrid, Edge Computing, Distributed Networks End User: Military Command Centers, Defense Contractors, Intelligence Agencies, Homeland Security, Tactical Units |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation, BAE Systems plc, Thales Group, General Dynamics Corporation, L3Harris Technologies, Inc., Palantir Technologies Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence and Analytics in Defense Market Shifts & Advancements
Neuromorphic computing architectures are emerging from laboratory environments into field-test programs, promising orders-of-magnitude efficiency gains for edge-deployed inference. These hardware shifts are compressing the power-performance tradeoffs that have constrained tactical AI deployment.
Neuromorphic processors mimic biological neural structures through spiking neural networks, enabling sub-watt inference for target recognition workloads. DARPA's Microelectronics Exploration program and Israel's Directorate of Defense Research and Development are funding pilot integrations with unmanned ground vehicles. This hardware trajectory is electrifying competitive positioning around power-constrained platforms where traditional GPUs fail thermal envelopes.
The EU AI Act's high-risk system classification is mandating human-in-the-loop architectures for autonomous targeting systems, forcing algorithm redesigns across European defense procurement. French Direction Générale de l'Armement and German BAAINBw are embedding these requirements into forthcoming RfPs, compelling vendors to demonstrate interpretability by design. Affected suppliers are restructuring development pipelines to accommodate post-hoc explanation generation without latency penalties.
Defense ministries are unbundling software maintenance from platform acquisition, creating standalone analytics service contracts that outlive hardware lifecycles. British Army and Royal Australian Air Force pilot programs are separating data processing subscriptions from vehicle procurement, enabling capability refresh without airframe replacement. This purchasing behavior is most visible in intelligence-surveillance-reconnaissance platforms where sensor-agnostic analytics layers deliver mission flexibility.
Global Artificial Intelligence and Analytics in Defense Market Segmentation
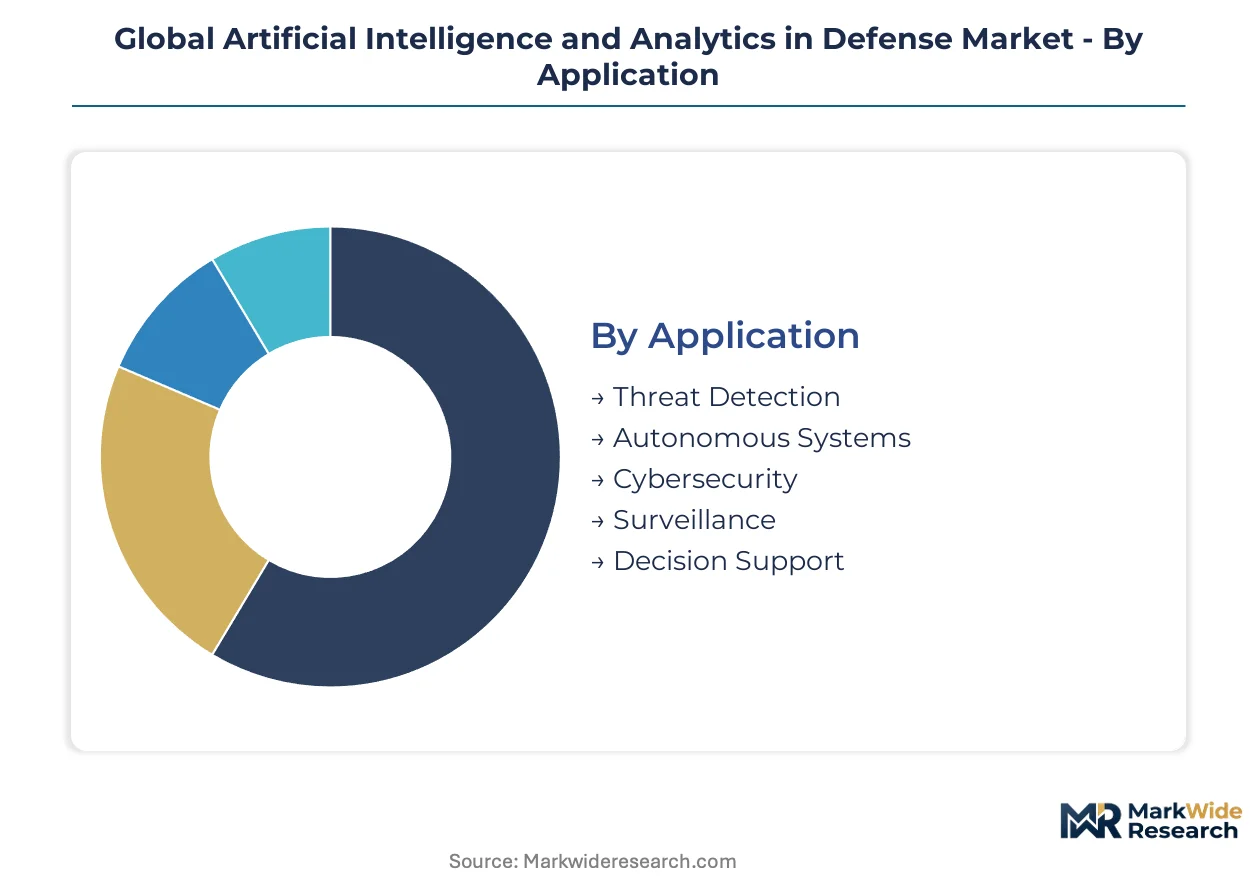
Defense procurement officers require granular segmentation to match clearance levels, latency constraints, and data sovereignty mandates against operational use cases. Each dimension below carries distinct certification pathways and vendor qualification requirements that determine contract accessibility.
Application:
Standardized threat detection protocols dominate current procurement volumes, while autonomous systems demand bespoke development cycles and extended security vetting.
- Threat Detection:Multi-source fusion algorithms process radar, signals intelligence, and imagery at sub-100-millisecond latency for tactical edge deployment. Military command centers across NATO member states prioritize these capabilities for contested electromagnetic environments where cognitive burden reduction proves critical.
- Autonomous Systems:Swarming protocols for unmanned platforms require distributed decision architectures that operate without persistent connectivity. Unmanned aerial system electronic warfare applications are climbing the fastest as kill chain distribution becomes operational priority.
- Cybersecurity:Adversarial machine learning defenses protect neural networks against data poisoning and evasion attacks.
- Surveillance:Persistent wide-area motion imagery analytics support border monitoring and force protection missions.
- Decision Support:Natural language interfaces accelerate command brief generation from classified document repositories.
Most installed capacity flows through Threat Detection. Expansion is steepest in Autonomous Systems.
Solution Type:
Cost tier separation reflects infrastructure intensity, with cloud-native platforms commanding premium subscriptions and on-premise neural networks requiring capital-intensive silicon.
- Predictive Analytics:Algorithm-as-a-service subscriptions for equipment failure forecasting compress maintenance windows across naval vessels and aircraft fleets. Defense agencies in the United States and United Kingdom are shifting capital expenditure toward these recurring operational budgets.
- Computer Vision:Real-time target recognition from electro-optical and infrared sensors demands specialized inference accelerators. Israeli defense innovation clusters lead field-test programs for power-constrained edge deployment.
- Natural Language Processing:Multi-lingual intelligence document triage supports human analyst prioritization.
- Neural Networks:Deep learning architectures for sensor fusion require extensive training data curation.
- Machine Learning Platforms:MLOps pipelines enable model versioning and audit trails for ethical AI compliance.
Predictive Analytics commands the largest share of recurring revenue. Computer Vision is gaining share fastest as sensor-agnostic deployment expands.
Deployment Model:
Volume concentration favors hybrid architectures that reconcile data sovereignty with burst compute scalability, while pure edge solutions serve disconnected tactical scenarios.
- Hybrid:Segregated data fabrics route sensitive processing through on-premise enclaves while leveraging commercial cloud for unclassified workloads. German BSI and UK NCSC certification requirements are driving redundant infrastructure investments across allied procurement frameworks.
- Edge Computing:Sub-watt neuromorphic processors enable inference on unmanned platforms where thermal and power budgets exclude traditional GPUs. DARPA's Microelectronics Exploration program funds pilot integrations with Israeli unmanned ground vehicle programs.
- On-premises:Air-gapped installations satisfy TS/SCI handling requirements for nuclear command-and-control systems.
- Cloud-based:FedRAMP-authorized government clouds support intelligence community analytics at scale.
- Distributed Networks:Mesh architectures for denied-area operations maintain functionality without centralized nodes.
Hybrid deployments absorb the majority of new budget allocation. Edge Computing shows the steepest expansion trajectory as tactical AI requirements harden.
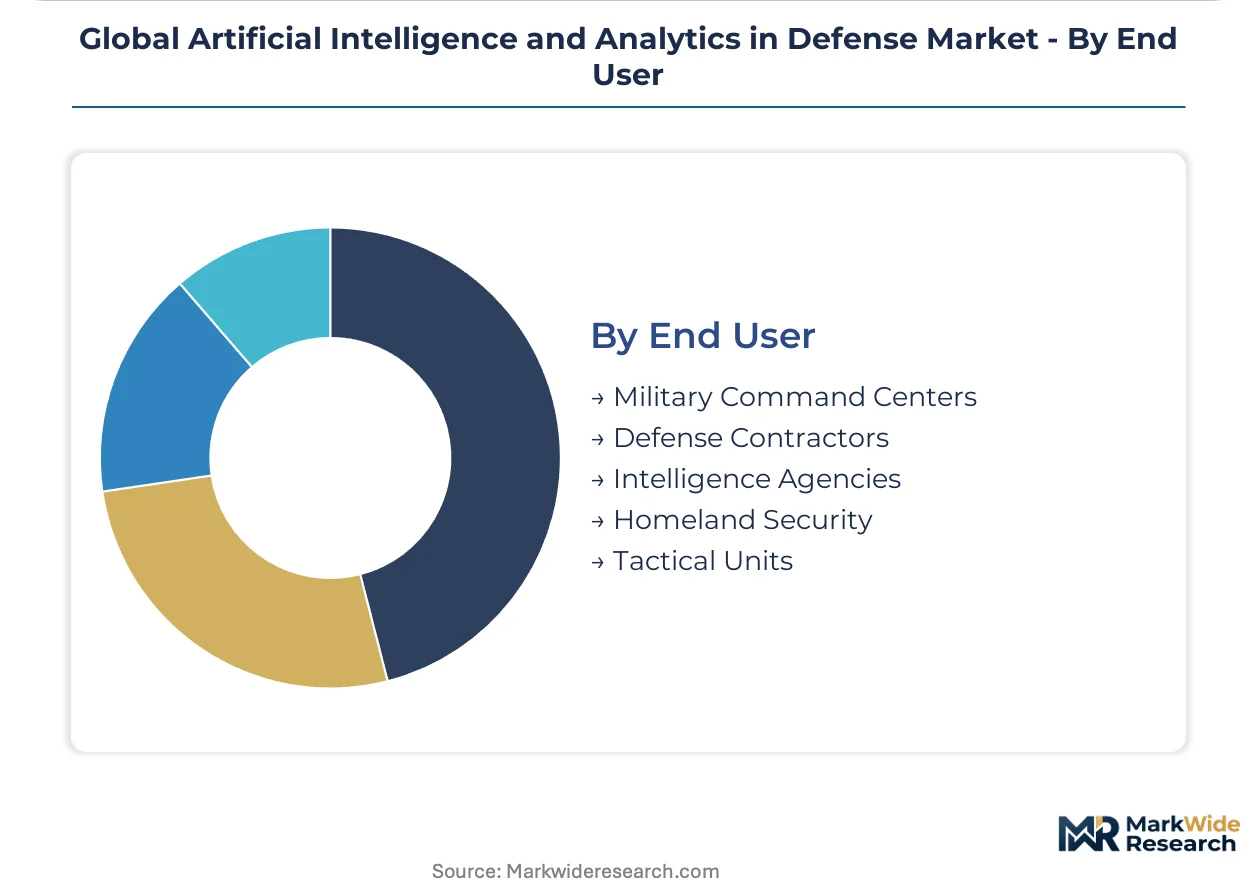
End User:
Customer type determines contract structure, with intelligence agencies mandating multi-year classified relationships and tactical units requiring rapid fielding cycles.
- Military Command Centers:Joint force integration across air, land, sea, space, and cyber domains demands unified data fabrics that only AI-enabled analytics can populate. U.S. combatant commands anchor long-term analytics contracts through classified R&D infrastructure access.
- Intelligence Agencies:Multi-source correlation platforms process human intelligence, signals intelligence, and geospatial data at scale. Hardened government cloud integrations sustain multi-year relationships with providers maintaining TS/SCI-cleared workforces.
- Defense Contractors:Prime systems integrators embed analytics layers into platform acquisition programs.
- Homeland Security:Border surveillance and critical infrastructure protection applications operate at lower classification levels.
- Tactical Units:Dismounted soldier systems require minimal training interfaces and resilient connectivity.
Military Command Centers concentrate the largest procurement volumes. Intelligence Agencies are expanding most quickly as all-source fusion requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel channels defense procurement through classified R&D ecosystems that rival the scale of U.S. combatant commands, while the United Kingdom structures transatlantic vendor qualification around dual-use technology screening.
United States
U.S. combatant commands anchor procurement through classified R&D infrastructure access and multi-year analytics contracts. The Department of Defense's Ethical AI Framework mandates audit trails and segregated supply chains for algorithm certification. Defense innovation clusters in Northern Virginia and Greater Boston concentrate vendor activity around intelligence community cloud integrations.
United Kingdom
British defense ministries prioritize hardened government cloud integrations that satisfy UK NCSC certification requirements alongside transatlantic procurement standards. The Ministry of Defence unbundles software maintenance from platform acquisition through standalone analytics service contracts. Bristol and Farnborough host prime systems integrators embedding AI layers into intelligence-surveillance-reconnaissance programs.
Israel
Israeli procurement channels through the Directorate of Defense Research and Development toward indigenous-foreign joint ventures with technology transfer mandates. DARPA-funded pilot programs integrate neuromorphic processors with unmanned ground vehicles for power-constrained edge deployment. Tel Aviv and Haifa defense innovation clusters lead field-test programs for sub-watt inference architectures.
Germany
German defense procurement navigates BSI cloud certification requirements and EU AI Act high-risk system classifications for autonomous targeting architectures. BAAINBw embeds human-in-the-loop interpretability mandates into forthcoming RfPs without latency penalties. Munich and Stuttgart industrial bases restructure development pipelines for post-hoc explanation generation.
India
India's Ministry of Defence AI task force channels procurement toward joint ventures with mandatory technology transfer provisions. The Defense Research and Development Organisation prioritizes indigenous algorithm development for multi-source intelligence fusion. Bangalore and Hyderabad defense corridors attract foreign vendors establishing local development centers for sensor-agnostic analytics layers.
Global Artificial Intelligence and Analytics in Defense Market Competitive Landscape
Top-tier vendors anchor long-term classified contracts, while mid-tier specialists compete through hardened cloud integrations and ethical AI certification pathways. The vendor base concentrates around three strategic archetypes: prime systems integrators with TS/SCI infrastructure, government cloud specialists with FedRAMP authorization, and boutique algorithm shops with neuromorphic hardware expertise. Competitive moves center on M&A for clearance-cleared workforces and strategic partnerships for cross-border data sharing compliance.
Within the prime integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions defined by classified R&D access and combatant command relationships. Palantir Technologies Inc. exemplifies the government cloud specialist archetype through hardened infrastructure sustaining intelligence community engagements. These three entities represent distinct competitive vectors: platform-centric integration, cloud-native analytics, and hybrid deployment architectures.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| RTX Corporation |
| BAE Systems plc |
| Thales Group |
| General Dynamics Corporation |
| L3Harris Technologies, Inc. |
| Palantir Technologies Inc. |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Algorithm-as-a-service procurement mandates from U.S. combatant commands and allied defense ministries are compressing vendor cash cycles and forcing supply chains toward recurring operational models rather than capital-intensive hardware refresh cycles.
Pricing Analysis
Capacity additions in Israeli neuromorphic processor development and U.S. government cloud infrastructure are reshaping price floors for tactical edge deployments. Three-tier pricing structure across classified, FVEY-cleared, and unclassified certification levels separates vendors by security clearance infrastructure investment. Pricing pressure stems from subscription model standardization as defense agencies shift capital expenditure to operational budgets. Intelligence agencies exhibit lowest price sensitivity due to mission-critical latency requirements, while homeland security applications face tighter procurement constraints.
Supply Chain Analysis
TS/SCI-cleared workforce availability in Northern Virginia and Greater Boston defense innovation clusters constrains vendor scaling velocity. Specialized silicon fabrication draws from Taiwan Semiconductor Manufacturing Company and Samsung Foundry, with custom AI accelerator design resting on U.S. and Israeli fabless semiconductor houses. Single-source vulnerability in advanced node manufacturing creates supply chain risk under U.S. Department of Commerce export control frameworks. Distribution runs through prime systems integrators with classified R&D infrastructure access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
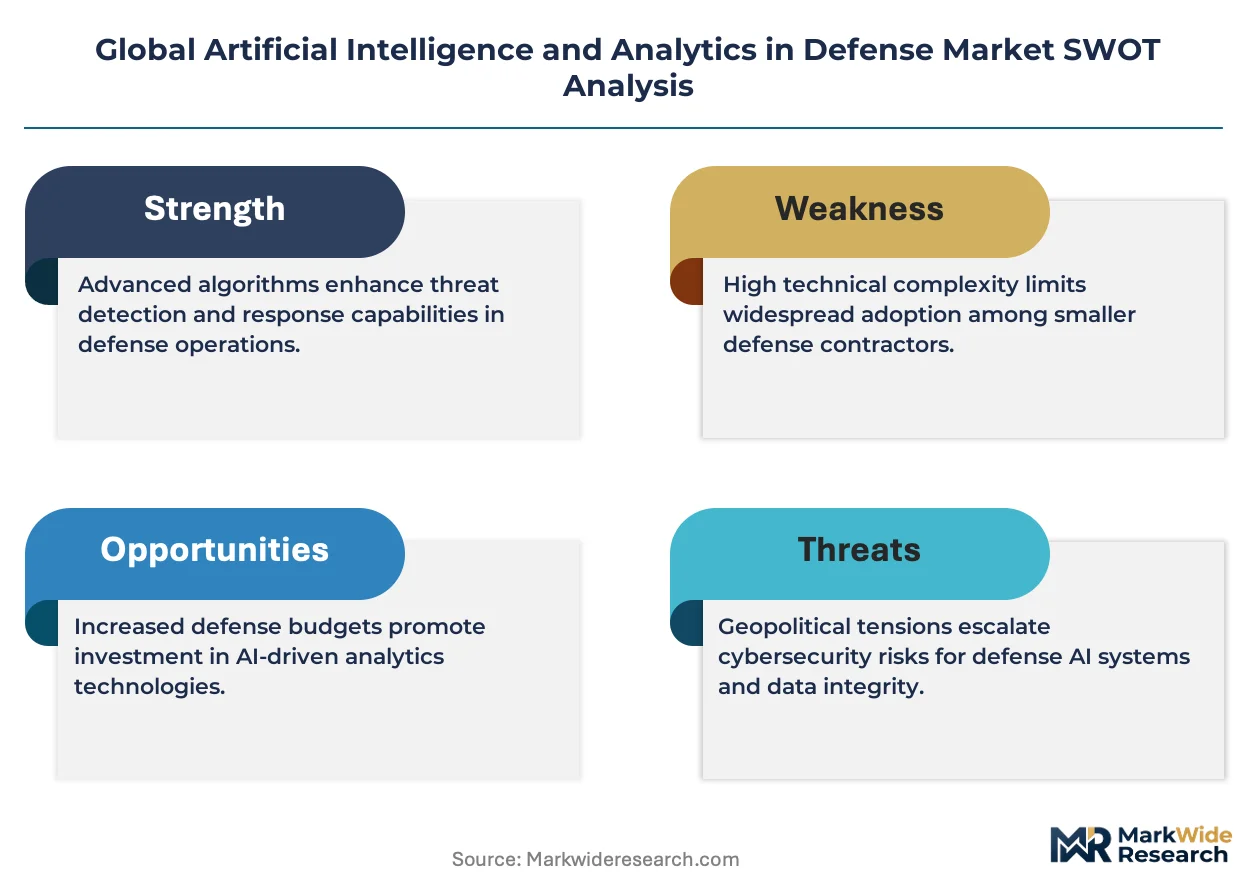
This market compounds regulatory complexity as the EU AI Act high-risk system classification mandates reshape algorithm procurement standards across allied defense frameworks.
For Market Incumbents: Deepen classified R&D infrastructure access through workforce clearance pipeline investments, countering TS/SCI vetting backlogs that constrain competitor scaling. Fortify government cloud integration capabilities to embed analytics deeper into operational workflows as subscription models displace perpetual licenses. For New Entrants and Emerging Players: Enter via neuromorphic hardware specialization for power-constrained unmanned platforms, where thermal envelope limitations exclude established GPU-centric vendors. Target Indian defense corridors through joint venture structures satisfying technology transfer mandates from the Ministry of Defence AI task force. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique algorithm shops possessing adversarial ML expertise and neuromorphic hardware co-design capabilities. Long-term viability hinges on ethical AI certification pathways that reduce procurement friction. Watch for fragmentation in sovereign cloud certification requirements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| TS/SCI-Cleared Workforce Expansion | Reduces 18-24 month vetting bottlenecks at U.S. Defense Counterintelligence and Security Agency. |
| Neuromorphic Processor Co-Development | Captures DARPA Microelectronics Exploration funding for sub-watt inference on unmanned platforms. |
| EU AI Act Conformity Assessment | Creates certified vendor pools reducing procurement friction for high-risk autonomous systems. |
| Hybrid Cloud Infrastructure Certification | Satisfies divergent German BSI and UK NCSC standards without redundant capital deployment. |
| Swarm Autonomy Protocol Development | Addresses underdeveloped electronic warfare applications in distributed kill chains. |
Research Methodology
Coverage spans the United States, United Kingdom, Israel, Germany, and India, with primary inputs from each defense procurement ecosystem. The analysis combines structured interviews with combatant command procurement officers, intelligence community cloud architects, prime systems integrator program managers, and defense ministry AI task force leads with secondary validation against U.S. Department of Defense budget justification materials, NATO AI Strategy implementation documents, EU AI Act regulatory filings, and national cloud certification standards from FedRAMP, UK NCSC, and German BSI. Bottom-up segment sizing triangulates against top-down defense expenditure allocation patterns.
Granularity extends to clearance level, latency tier, and deployment model for each application segment across the projection horizon. The analytical framework models threat detection, autonomous systems, cybersecurity, surveillance, and decision support applications separately, with cross-segment calibration for hybrid deployment architectures. CAGRs derive from defense budget trajectory analysis, procurement cycle timing, and technology readiness level progression for neuromorphic computing and swarm autonomy protocols.
Inputs from classified program budget documentation and vendor contract announcements were available through the study window; gaps in TS/SCI program specifics introduce uncertainty bands around intelligence community adoption timelines. Forecasts reflect assumptions regarding export control stability and allied data sharing protocol continuity. Material deviation in semiconductor manufacturing access or sovereign AI fragmentation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
AI in Military Market