
 Global HIV/AIDS Diagnostics Market | 2026-2036
Global HIV/AIDS Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global HIV/AIDS Diagnostics Market Foresight
Point-of-care testing demand from public health programs is hardening as ministries of health decentralize HIV services beyond centralized laboratories. Abbott Laboratories leverages its rapid test portfolio to anchor distribution across African national supply chains. Roche Diagnostics sustains technology leadership in nucleic acid amplification through instrument placement models that lock in revenue streams. Bio-Rad Laboratories specializes in quality control panels that laboratories require for assay validation.
HIV/AIDS diagnostics encompass assays, instruments, and consumables designed to detect viral antigens, antibodies, or nucleic acid in human specimens, with polymerase chain reaction achieving sensitivity thresholds below 20 copies per milliliter for viral load quantification. These products serve epidemiological surveillance, treatment monitoring, and blood safety screening functions across healthcare systems. Immunoassay platforms occupy the largest installed base due to lower capital requirements, while nucleic acid amplification captures the fastest expansion as countries transition to treat-all protocols demanding precise viral load thresholds. Public health programs generate the deepest volume pools, though diagnostic laboratories retain margin concentration through bundled service contracts.
WHO prequalification, FDA emergency use authorization, and EMA CE-IVD marking collectively determine market access eligibility and shape product development roadmaps for manufacturers. National regulators in South Africa and Kenya increasingly mandate local quality certification before tender participation, elevating compliance costs for new entrants. Stakeholders must monitor how point-of-care instrument connectivity standards evolve, as real-time data transmission becomes inseparable from funding eligibility in PEPFAR and Global Health Initiative frameworks.
Market Dynamics
Decentralization of HIV services from centralized laboratories to community health posts is restructuring procurement volumes and instrument specifications across public health systems.
Growth Catalysts
- WHO prequalification protocols:Ministries of health in Sub-Saharan Africa now mandate WHO-prequalified assays for national tenders, accelerating replacement of unapproved products.
- Nucleic acid amplification technology:Viral load monitoring platforms achieve sensitivity below 20 copies per milliliter, enabling treat-all protocols that demand precise quantification thresholds.
- Point-of-care instrument connectivity:Real-time data transmission capabilities are becoming prerequisites for PEPFAR and Global Health Initiative funding eligibility.
Market Restraints
- Reagent cold chain dependence:Nucleic acid amplification consumables require uninterrupted temperature control, limiting deployment to facilities with reliable infrastructure.
- Capital intensity of platform placement:Instrument leasing models lock laboratories into multi-year consumable commitments, constraining supplier switching.
- Specialized technician scarcity:Molecular diagnostics operation demands trained personnel that rural health posts cannot retain.
Strategic Opportunities
- Rural Kenya laboratory networks:County-level hub-and-spoke models are expanding viral load access beyond Nairobi and Mombasa corridors.
- Self-testing regulatory pathways:FDA emergency use authorization frameworks for over-the-counter HIV assays are opening direct-to-consumer channels.
- Integration with tuberculosis screening:Dual-disease diagnostic platforms are converging procurement budgets across integrated national programs.
Industry Challenges
- Quality control panel validation:Laboratories must demonstrate assay precision through external quality assessment schemes that lack standardization across national networks.
- Legacy immunoassay infrastructure:Existing rapid test installed bases create resistance to nucleic acid platform transitions despite superior sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HIV/AIDS Diagnostics Market |
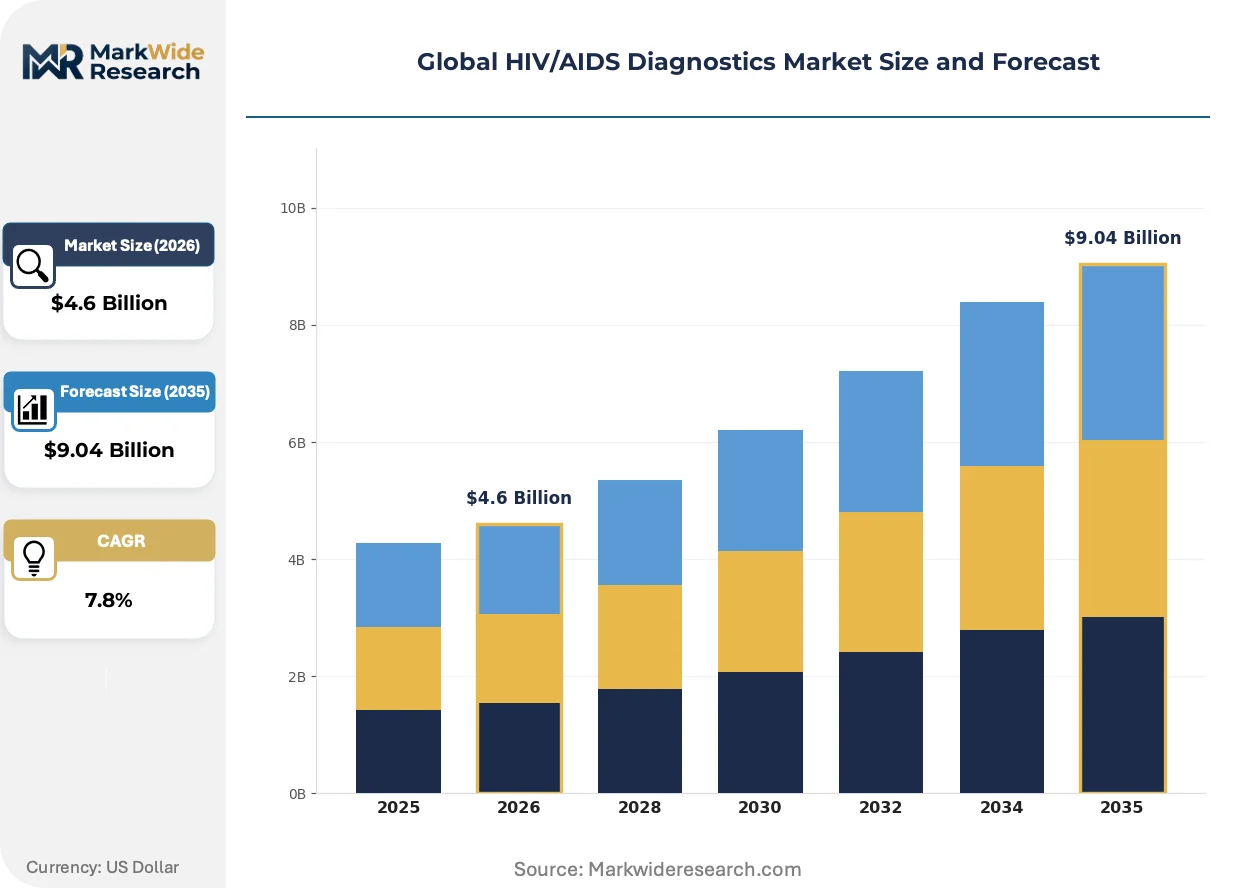
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $9.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Tests, ELISA Kits, Western Blot, PCR Assays, CD4 Count Kits Technology: Immunoassay, Nucleic Acid Amplification, Flow Cytometry, Chemiluminescence, Electrochemiluminescence Application: Early Detection, Viral Load Monitoring, Treatment Efficacy, Blood Screening, Epidemiological Surveillance End User: Diagnostic Laboratories, Blood Banks, Research Institutions, Non-Governmental Organizations, Public Health Programs |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Becton Dickinson, Bio-Rad Laboratories, Thermo Fisher Scientific, Danaher Corporation, OraSure Technologies, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HIV/AIDS Diagnostics Market Shifts & Advancements
Connectivity standards and sample-to-answer automation are compressing the skill gap required for molecular diagnostics deployment in resource-limited settings.
Isothermal amplification chemistry is converging with cartridge-based microfluidics to eliminate thermal cycler dependence. District hospitals in Nigeria and Uganda are adopting these platforms to process viral load samples without centralized laboratory referral. The technology is converging with cloud-based laboratory information systems to enable real-time epidemiological surveillance.
EMA CE-IVD marking requirements under the In Vitro Diagnostic Medical Devices Regulation are elevating clinical evidence standards for HIV assay approvals. Manufacturers must now submit expanded performance studies across diverse viral subtypes. African national regulators in South Africa and Kenya are adopting these standards into local tender specifications, compressing timelines for product registration.
Public health programs are consolidating procurement through framework agreements that bundle instruments, reagents, and service contracts into multi-year commitments. National supply chains in Ethiopia and Zambia are shifting from spot purchasing to these consolidated models. This concentration is favoring suppliers with established distribution infrastructure over niche technology innovators.
Global HIV/AIDS Diagnostics Market Segmentation
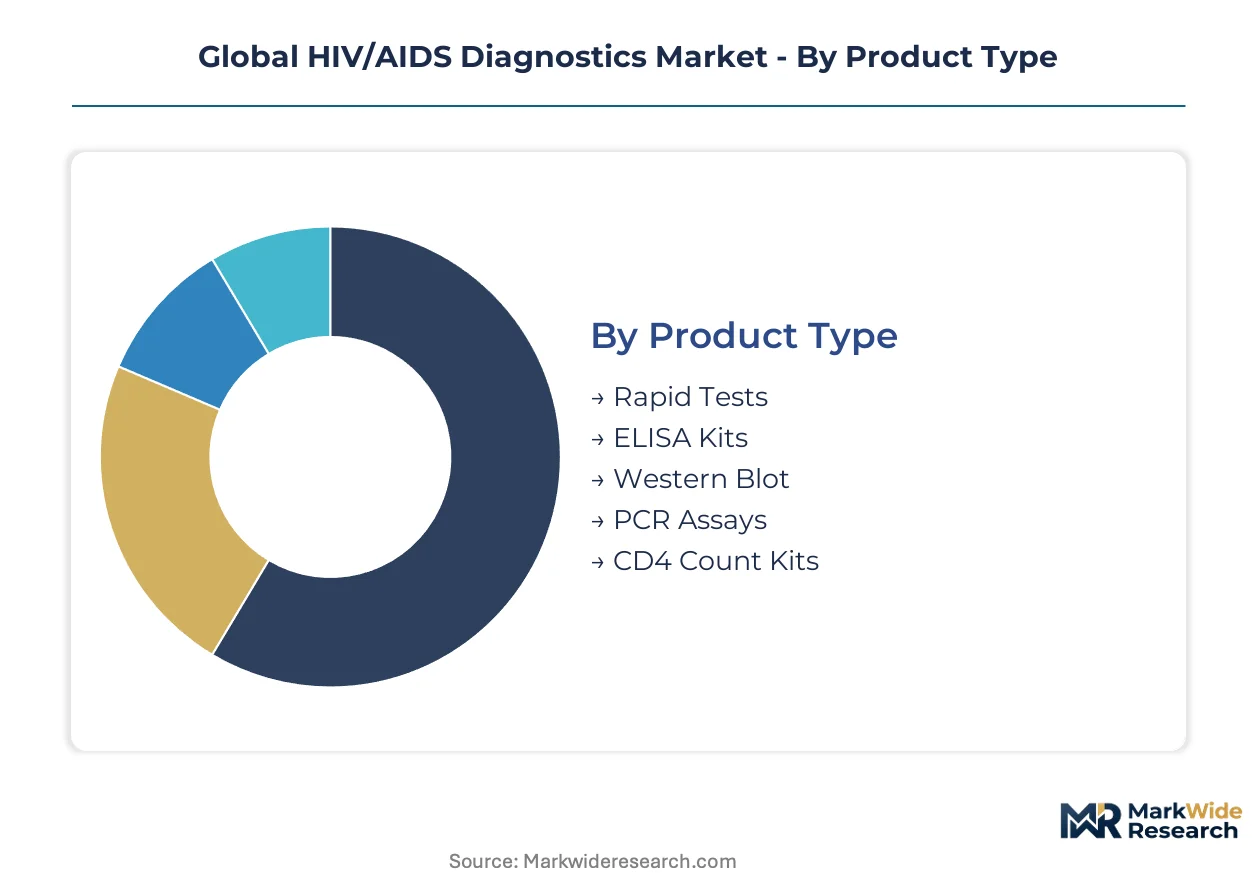
HIV/AIDS diagnostics segment across multiple axes that determine procurement patterns, regulatory pathways, and margin structures. Product type and technology classifications shape capital intensity and technician requirements. Application and end-user dimensions dictate funding sources and volume concentration.
Product Type:
Antigen-antibody detection formats vary in sensitivity thresholds, time-to-result, and infrastructure requirements.
- Rapid Tests:Lateral flow immunochromatographic strips detect HIV-1/2 antibodies in 15-20 minutes using whole blood, serum, or oral fluid. Demand concentrates in community health posts across Kenya and Nigeria where electricity access is unreliable and same-day result delivery is mandatory for linkage to care.
- PCR Assays:Quantitative nucleic acid amplification achieves detection below 20 copies per milliliter for viral load monitoring. Expansion is concentrated in South Africa's national laboratory network as treat-all protocols require precise threshold quantification for treatment switching decisions.
- ELISA Kits:Enzyme-linked immunosorbent assays remain the reference standard for blood bank screening in high-throughput settings.
- Western Blot:Confirmatory line immunoassays resolve discordant rapid test results in centralized reference laboratories.
- CD4 Count Kits:Flow cytometry-based enumeration supports immune status staging where viral load platforms are unavailable.
Mature deployment sits with Rapid Tests. Newer deployment is concentrated in PCR Assays.
Technology:
Detection chemistry determines platform cost, throughput capacity, and regulatory classification under WHO prequalification protocols.
- Immunoassay:Antibody and antigen capture methods dominate installed bases due to minimal capital requirements and ambient temperature stability. Procurement volumes from PEPFAR-funded programs in Ethiopia and Uganda sustain manufacturer revenue through high-frequency consumable purchasing.
- Nucleic Acid Amplification:Polymerase chain reaction and isothermal methods achieve molecular sensitivity for early infection detection and treatment monitoring. Adoption is climbing the fastest in district hospitals across Zambia and Malawi as cartridge-based platforms eliminate thermal cycler dependence.
- Flow Cytometry:Fluorescence-activated cell sorting enables CD4 T-cell enumeration for immunological staging.
- Chemiluminescence:High-sensitivity antibody detection supports automated high-throughput screening in centralized laboratories.
- Electrochemiluminescence:Meso Scale Discovery platforms offer multiplexing capability for research applications and quality control validation.
Volume concentration remains with Immunoassay. Margin expansion is shifting toward Nucleic Acid Amplification.
Application:
Clinical use case determines sensitivity requirements, turnaround time expectations, and reimbursement or funding mechanisms.
- Viral Load Monitoring:Quantitative RNA measurement tracks treatment response and detects virological failure before clinical progression. National programs in South Africa and Kenya mandate six-monthly testing for all patients on antiretroviral therapy, creating sustained reagent demand.
- Early Detection:Fourth-generation antigen-antibody combination assays shorten window periods to 14-18 days. Point-of-care deployment in Nigeria's antenatal clinics supports elimination of mother-to-child transmission targets.
- Treatment Efficacy:Resistance genotyping guides salvage regimen selection after first-line failure.
- Blood Screening:Serological and nucleic acid testing ensures transfusion safety in national blood services.
- Epidemiological Surveillance:Sentinel surveillance and population-based surveys track prevalence and incidence trends.
Programmatic funding anchors Viral Load Monitoring. Donor priorities are elevating Early Detection.
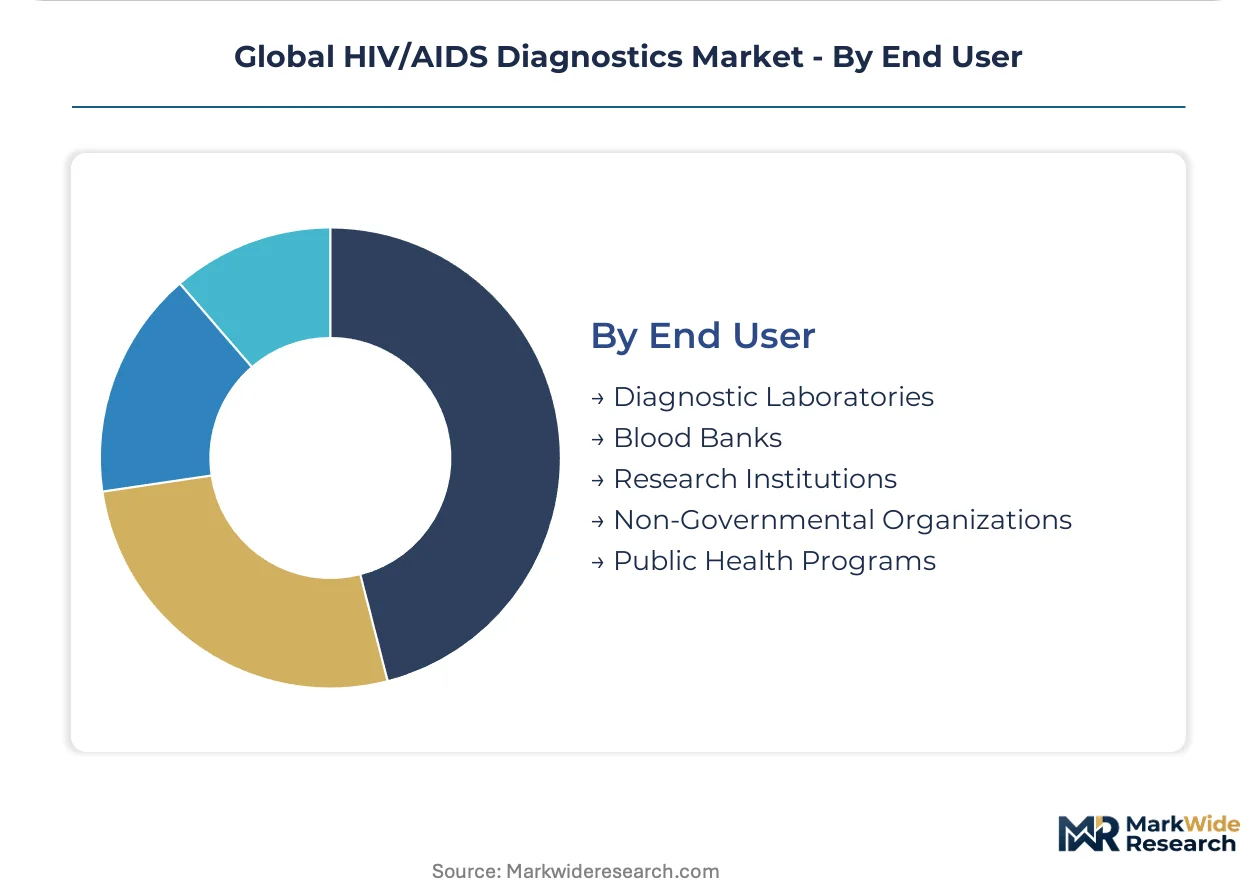
End User:
Institutional type shapes procurement modality, technical specification, and service contract structure.
- Public Health Programs:Ministry of health systems and Global Fund recipients generate the deepest volume pools through centralized tender processes. Framework agreements in Tanzania and Mozambique bundle instruments, reagents, and service into multi-year commitments that favor established distribution infrastructure.
- Diagnostic Laboratories:Private and hospital-based labs retain margin concentration through value-added services including result interpretation and clinician consultation.
- Blood Banks:National transfusion services operate under distinct regulatory frameworks with mandatory nucleic acid testing windows.
- Research Institutions:Academic and clinical trial sites drive demand for novel assay validation and subtype diversity panels.
- Non-Governmental Organizations:Community-based implementers prioritize portability and connectivity for remote service delivery.
Procurement scale sits with Public Health Programs. Margin capture is concentrating in Diagnostic Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic instrument manufacturing concentrates in the United States, Germany, and Switzerland, while testing volume consumption dominates Sub-Saharan Africa where national laboratory networks process millions of specimens annually.
South Africa
The National Health Laboratory Service operates Africa's largest viral load monitoring network, processing over 14 million tests annually across nine provinces. The South African Health Products Regulatory Authority mandates local quality certification for tender participation, elevating compliance barriers for new entrants. Johannesburg and Cape Town anchor the southern African diagnostics corridor where hub-and-spoke laboratory models distribute specimen processing from district hospitals.
Nigeria
Federal Ministry of Health decentralization programs are shifting HIV testing from centralized reference laboratories to 774 local government area clinics. The National Agency for Food and Drug Administration and Control enforces WHO prequalification standards for all assays procured through Global Fund mechanisms. Lagos and Abuja concentrate private diagnostic laboratory capacity while northern states rely on PEPFAR-supported community health posts for rapid test distribution.
Kenya
County-level devolution since 2013 has transferred diagnostic procurement authority to 47 county governments, fragmenting tender processes. The Pharmacy and Poisons Board aligns registration requirements with EMA CE-IVD marking under the In Vitro Diagnostic Medical Devices Regulation. Nairobi and Mombasa host centralized reference laboratories while western counties near Lake Victoria deploy point-of-care instruments for same-day result delivery.
United States
FDA emergency use authorization frameworks govern over-the-counter HIV self-test commercialization, with recent pathways opening direct-to-consumer channels. The Centers for Disease Control and Prevention funds domestic surveillance programs that sustain demand for fourth-generation antigen-antibody combination assays. Boston and San Diego concentrate molecular diagnostics R&D clusters where isothermal amplification chemistry converges with cartridge-based microfluidics development.
Germany
EMA headquarters in Amsterdam coordinates CE-IVD marking under the In Vitro Diagnostic Medical Devices Regulation, with German notified bodies conducting conformity assessments for HIV assay approvals. The Federal Institute for Drugs and Medical Devices requires expanded performance studies across diverse viral subtypes for registration. Munich and Mannheim anchor central European diagnostics manufacturing where automated high-throughput platforms serve blood bank screening networks.
Global HIV/AIDS Diagnostics Market Competitive Landscape
Top-tier vendors anchor instrument placement and reagent supply contracts, while mid-tier specialists compete on assay innovation and regional distribution reach. The vendor base stratifies across three tiers: multinational conglomerates with diagnostic divisions, pure-play molecular diagnostics firms, and regional distributors with tender expertise. Strategic archetypes include platform-locked consumable suppliers, quality control panel specialists, and rapid test commodity producers. Competitive moves concentrate on multi-year framework agreement pursuit and point-of-care connectivity certification.
Within the multinational conglomerate tier, Abbott Laboratories, Roche Diagnostics, and Siemens Healthineers exemplify platform-locked business models where instrument placement generates captive reagent revenue streams. Abbott represents the rapid test and point-of-care instrument archetype with African national supply chain anchoring. Roche occupies the nucleic acid amplification technology leadership position through viral load monitoring platform dominance. Siemens exemplifies the integrated diagnostics conglomerate structure spanning immunoassay, molecular, and blood gas portfolios.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Becton Dickinson |
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| Danaher Corporation |
| OraSure Technologies |
| bioMérieux |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up diagnostic distributors in Sub-Saharan Africa have consolidated procurement channels across Kenya, Nigeria, and South Africa, tightening pricing discipline on consumables while extracting volume rebates from manufacturers desperate for national tender access.
Pricing Analysis
Cost-down pressure on nucleic acid amplification reagents accelerates because PEPFAR procurement frameworks mandate connectivity-enabled platforms that bundle instruments, software, and consumables into indivisible contracts. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified assays from CE-IVD marked alternatives and unapproved rapid tests. Price differentiation rests on certification tier and after-sales service bundling. Public health programs exhibit acute price sensitivity, while research institutions tolerate premium positioning for subtype diversity panels.
Supply Chain Analysis
WHO prequalification and FDA emergency use authorization gating concentrate reagent manufacturing in the United States, Germany, and Switzerland, where notified bodies conduct conformity assessments. Supply chains draw from specialized polymer suppliers for cartridge microfluidics, enzyme manufacturers for reverse transcriptase, and fluorescence dye producers for detection chemistry. Single-source vulnerability pervades isothermal amplification enzyme supply. Distribution runs through national medical supply agencies in Ethiopia, Zambia, and Tanzania that aggregate county-level demand into framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
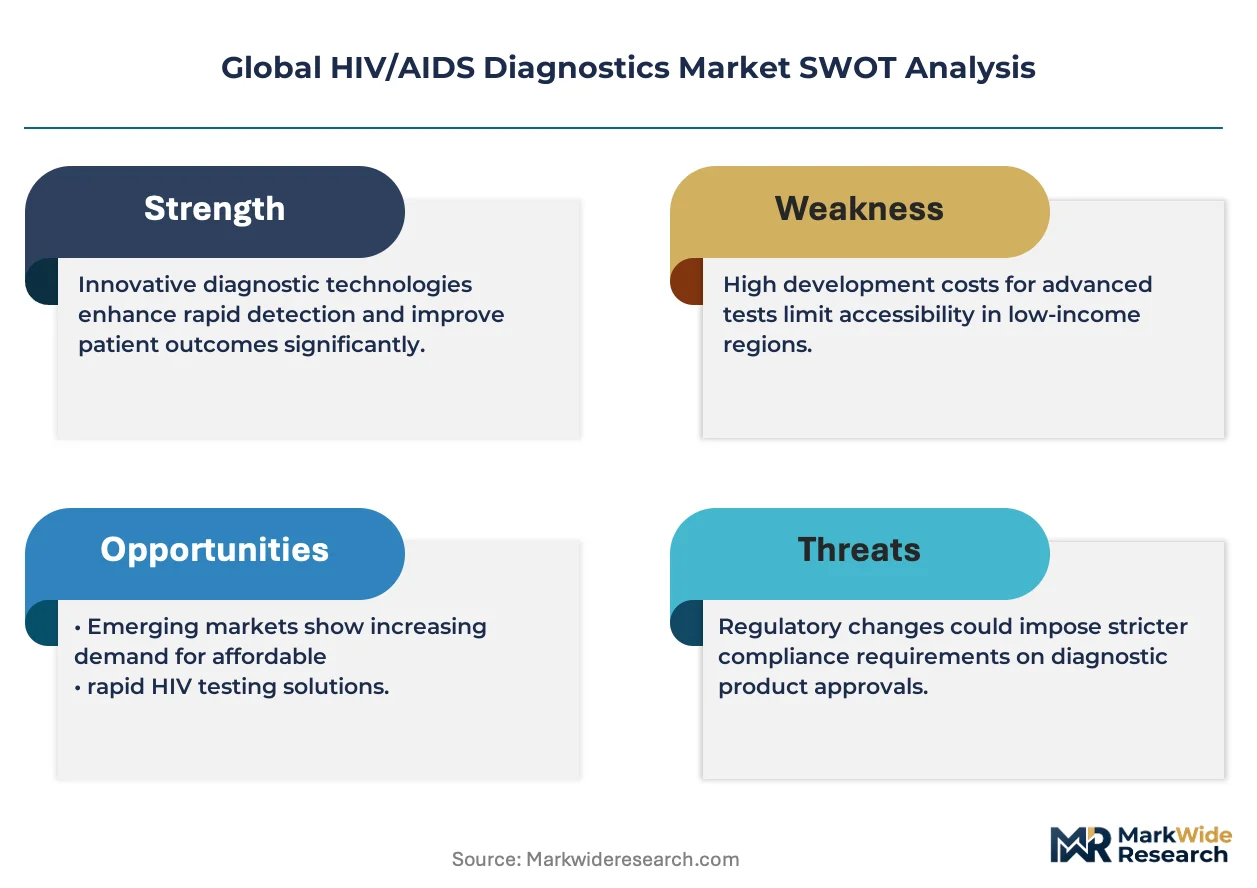
The Global HIV/AIDS Diagnostics Market sits in a technology-transition phase where nucleic acid amplification platforms displace legacy immunoassay infrastructure despite higher capital requirements and cold chain dependence.
For Market Incumbents: Lock in viral load monitoring platform placements through multi-year consumable commitments in South Africa's National Health Laboratory Service, defending against cartridge-based point-of-care entrants by accelerating instrument connectivity certification for PEPFAR eligibility. Prioritize backward integration into reagent enzyme production to insulate margins from supplier concentration.
For New Entrants and Emerging Players: Launch via county-level hub-and-spoke partnerships in rural Kenya, where devolved procurement authority fragments tender processes and creates white-space access beyond Nairobi-centered incumbents. Target isothermal amplification chemistry for district hospitals lacking thermal cycler infrastructure, using cloud-connected laboratory information systems as the go-to-market wedge.
For Investors and Strategic Acquirers: Distressed-cycle entries favor quality control panel specialists with WHO prequalification in South Africa, where regulatory elevation compresses timelines for product registration and strands undercapitalized competitors. Watch PEPFAR funding reauthorization negotiations as the inflection signal for platform connectivity standards and real-time data transmission mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Accelerates national tender eligibility across Sub-Saharan African ministry procurement systems. |
| Point-of-Care Connectivity Certification | Unlocks PEPFAR and Global Health Initiative funding streams requiring real-time data transmission. |
| County-Level Distribution Partnership | Captures devolved procurement authority in Kenya's 47 county governments beyond centralized channels. |
| Isothermal Amplification Platform Launch | Eliminates thermal cycler dependence for district hospitals in Nigeria and Uganda without laboratory infrastructure. |
| Multi-Year Framework Agreement Pursuit | Bundles instruments, reagents, and service into indivisible commitments that lock out competitor switching. |
Research Methodology
Multi-period observation of viral load testing volumes, instrument placement rates, and national tender award patterns anchored the trend analysis, supplemented by interviews with laboratory network directors, ministry of health procurement officers, biomedical engineers, and diagnostics distributor executives. Secondary validation drew from WHO prequalification listings, FDA emergency use authorization databases, Global Fund disbursement records, and national health accounts. Bottom-up testing volume estimates triangulated against top-down procurement expenditure data.
Input-output matrices mapped reagent consumption to instrument installed bases across product type, technology, application, and end-user segments over the projection horizon. CAGRs derived from logistic diffusion curves for nucleic acid amplification adoption and linear extrapolation for mature rapid test segments. Forecast inputs incorporated treat-all protocol expansion timelines and PEPFAR funding trajectory assumptions.
Regulatory approval delays, funding reauthorization volatility, and viral subtype diversity panel shortages are the dominant revision risks to testing volume projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
HDL Cholesterol Kits Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market