
 India in-Vitro Diagnostics Market | 2026-2036
India in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
India in-Vitro Diagnostics Market Foresight
The capital-intensity divergence between multinational instrument manufacturers and domestic reagent producers is unwinding as local firms scale automated platforms. Roche Diagnostics India Pvt Ltd leverages its global assay portfolio to anchor premium hospital contracts in metropolitan centers. Transasia Bio-Medicals Ltd sustains competitive positioning through integrated instrument-reagent bundles targeted at mid-tier laboratories. Dr. Lal PathLabs dominates consumer-facing diagnostics via dense collection center networks and direct-to-patient digital interfaces.
In-vitro diagnostics encompasses analytical testing performed on biological specimens outside the living organism, utilizing reagent-based chemical reactions, immunoassay binding affinities, or nucleic acid amplification with sensitivity thresholds reaching picogram concentrations to detect disease biomarkers, therapeutic drug levels, and physiological states. Reagents and consumables capture recurring revenue streams with higher margin stability than capital-intensive instrument placements, while infectious disease applications expand fastest amid residual tuberculosis burden and emerging antimicrobial resistance surveillance mandates. PCR technology leads molecular diagnostics volume, though ELISA retains cost advantages in high-throughput serology screening across public health programs.
CDSCO regulates in-vitro diagnostic medical devices under the Medical Device Rules, while BIS certification governs electrical safety and electromagnetic compatibility standards for imported analyzers, and the PLI scheme for medical devices shapes domestic manufacturing incentives that redirect procurement toward local production. The central drug regulator's risk-based classification system determines clinical trial requirements and import licensing burdens that differentiate market entry pathways for novel versus established test categories. Stakeholders must monitor evolving notified device status expansions and state-level procurement centralization that will determine channel economics for reagent suppliers and independent laboratory operators.
Market Dynamics
The PLI scheme for medical devices is compressing capital costs for domestic instrument manufacturers while Tier-II and Tier-III hospital expansion redistributes demand geography away from metropolitan laboratory networks. This dual movement is restructuring competitive economics for reagent suppliers and reference laboratory operators.
Growth Catalysts
- CDSCO risk-based classification:Streamlined import licensing for established IVD categories accelerates market entry for standardized reagent kits.
- Telangana diagnostic cluster expansion:Hyderabad's biotech corridor anchors reference laboratory consolidation, concentrating high-complexity testing demand.
- PCR platform automation:Nucleic acid amplification systems reduce technician-to-sample ratios in tuberculosis and antimicrobial resistance surveillance programs.
Market Restraints
- Optical component import dependency:Fluorescence detection modules and precision optics concentrate supply in East Asian manufacturing hubs, exposing margins to currency volatility.
- BIS electromagnetic compatibility certification:Electrical safety testing for automated analyzers extends equipment approval timelines by 4-6 months.
- Point-of-care lateral flow substitution:Rapid antigen tests displace laboratory-based serology in outpatient infectious disease screening.
Strategic Opportunities
- Karnataka Tier-III hospital penetration:District-level healthcare infrastructure expansion creates captive reagent demand outside Bengaluru's saturated diagnostic chain networks.
- Reagent rental instrument placement:Capital-light business models convert upfront equipment sales into recurring consumable revenue streams.
- AI-assisted pathology image analysis:Machine learning integration with digital microscopy platforms automates cytology screening workflows.
Industry Challenges
- Clinical laboratory scientist shortage:Molecular diagnostics and flow cytometry operations require specialized technicians scarce outside Maharashtra and Karnataka urban centers.
- LIS-HIS integration complexity:Laboratory information systems must interface with heterogeneous hospital management platforms across public and private provider networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India in-Vitro Diagnostics Market |
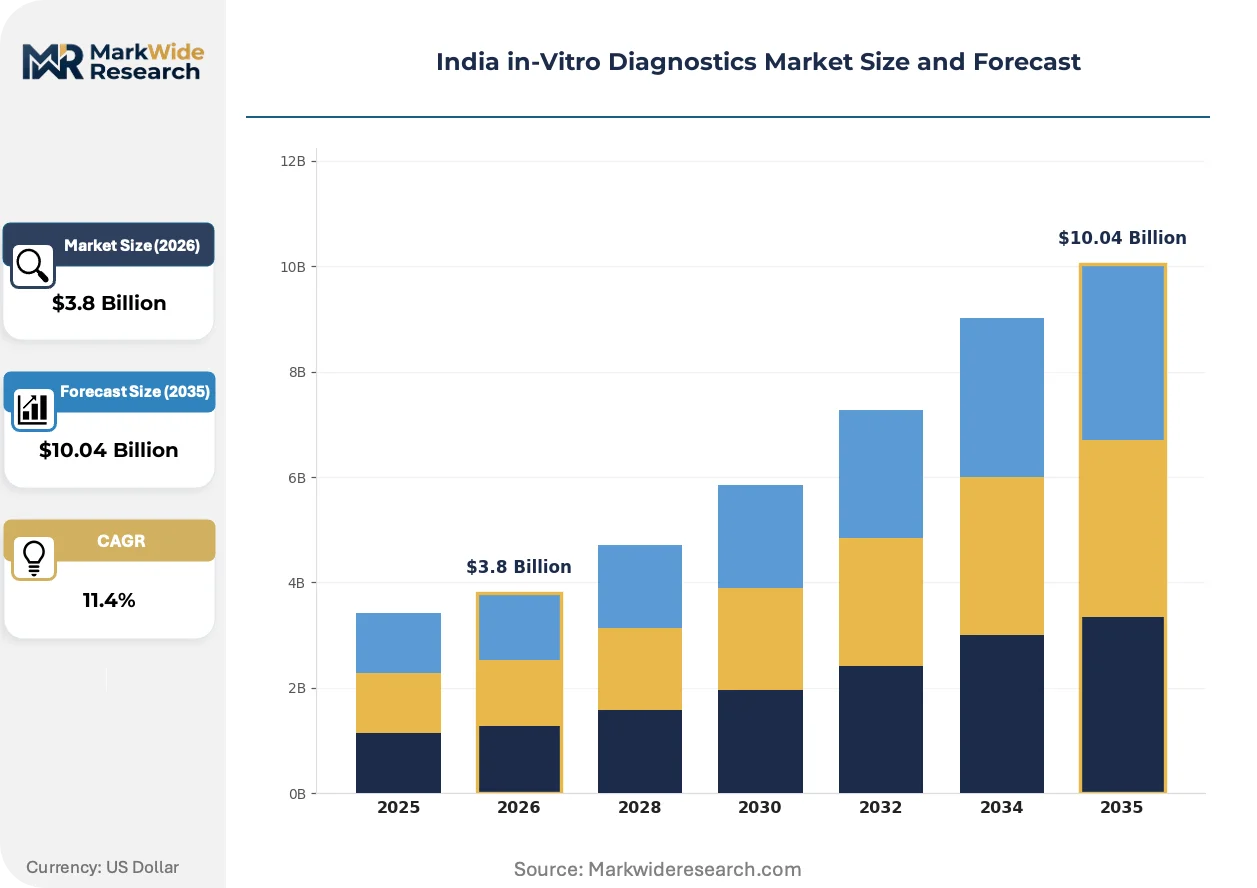
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Consumables, Software Application: Clinical Diagnostics, Research, Blood Testing, Infectious Disease End User: Hospitals, Laboratories, Home Care, PoC Testing Technology: PCR, Microarray, ELISA, Flow Cytometry |
| Companies Covered | Roche Diagnostics India Pvt Ltd, Abbott Healthcare Pvt Ltd, Siemens Healthineers India, Transasia Bio-Medicals Ltd, Beckman Coulter India, Dr. Lal PathLabs, SRL Diagnostics, Thyrocare, Agappe Diagnostics Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India in-Vitro Diagnostics Market Shifts & Advancements
Automation architectures and regulatory digitization are compressing operational economics for diagnostic service providers while procurement centralization redistributes buyer power across public and private channels.
Next-generation sequencing is bifurcating oncology companion diagnostics into high-throughput centralized laboratory services and targeted single-gene hospital-based assays. Tata Memorial Centre and AIIMS Delhi anchor the centralized tier, while mid-tier oncology units adopt focused NGS panels for EGFR and ALK mutation detection. This technology is bifurcating the market into premium complex testing and commoditized targeted screening segments with diverging margin structures.
CDSCO's Medical Device Rules notification expansion is reclassifying risk categories for novel biomarker assays, mandating clinical performance studies for Class C and D IVDs entering the Indian market. Manufacturers must submit analytical and clinical validation data to the central licensing authority before commercial distribution. Maharashtra and Gujarat-based reagent producers are responding by establishing in-house clinical affairs teams to manage regulatory dossier preparation.
Diagnostic chains are consolidating collection center networks into hub-and-spoke logistics models, replacing dispersed standalone laboratory relationships with integrated sample transport and centralized processing. Dr. Lal PathLabs and Metropolis Healthcare anchor this restructuring, capturing patient walk-in volume through digital appointment platforms. Karnataka and Telangana exhibit the densest collection center penetration, with rural-urban sample flow reversing traditional referral patterns.
India in-Vitro Diagnostics Market Segmentation
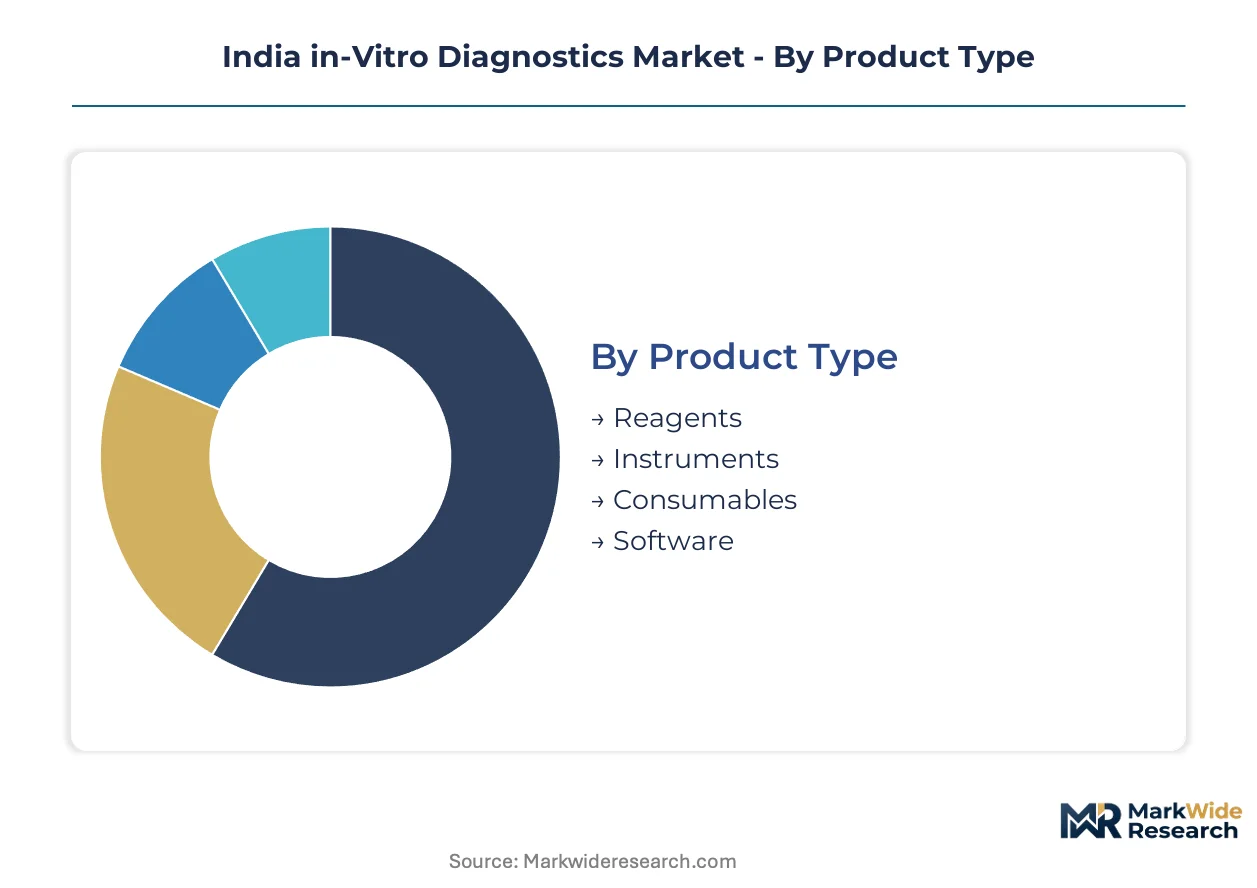
Segmentation in India's in-vitro diagnostics market reveals divergent margin structures and procurement pathways. Reagent suppliers, instrument manufacturers, and service operators face distinct competitive economics across product, application, end-user, and technology dimensions.
Product Type:
Domestic manufacturing concentrates in reagents and consumables, while instrument assembly relies heavily on imported optical and electronic subsystems.
- Reagents:Chemical and biological formulations drive recurring revenue with stable margins. Maharashtra and Telangana house the densest reagent production clusters, with PLI scheme incentives accelerating local enzyme and antibody manufacturing.
- Instruments:Automated analyzers, PCR platforms, and hematology systems require precision engineering. Karnataka's Bengaluru-Tumkur corridor anchors domestic assembly operations, though fluorescence detection modules remain import-dependent from East Asian suppliers.
- Consumables:Pipette tips, reaction vessels, and sample collection tubes constitute high-volume, low-unit-value procurement.
- Software:Laboratory information systems and AI-assisted diagnostic platforms command premium pricing in metropolitan hospital networks.
Reagents hold the largest share; momentum sits with software as diagnostic chains digitize patient interfaces.
Application:
Clinical utility and reimbursement pathways determine volume concentration across testing categories.
- Clinical Diagnostics:Routine biochemistry, immunoassay, and hematology panels form the revenue backbone. Tier-II and Tier-III hospital expansion in Karnataka and Telangana is redistributing demand away from metropolitan reference laboratories.
- Infectious Disease:Tuberculosis detection, antimicrobial resistance surveillance, and viral load monitoring expand fastest. CDSCO mandates clinical performance studies for novel infectious disease assays entering the Indian market.
- Blood Testing:Transfusion screening and donor pathogen detection operate under centralized procurement frameworks.
- Research:Academic and pharmaceutical R&D applications concentrate in Hyderabad's biotech corridor and Delhi-NCR institutional clusters.
Clinical diagnostics dominates current volume; infectious disease applications are climbing the fastest amid residual tuberculosis burden and emerging pathogen surveillance mandates.
End User:
Procurement centralization and capital availability fragment buyer power across institutional categories.
- Hospitals:Inpatient and outpatient testing demand anchors instrument placements. Tier-II and Tier-III facilities in Maharashtra and Karnataka are expanding test menus beyond basic biochemistry, creating captive reagent demand.
- Laboratories:Independent diagnostic chains and hospital-affiliated labs operate distinct logistics models. Dr. Lal PathLabs and Metropolis Healthcare consolidate collection center networks into hub-and-spoke configurations.
- PoC Testing:Physician office and clinic-based rapid diagnostics displace laboratory serology in outpatient infectious disease screening.
- Home Care:Direct-to-patient sample collection and digital result delivery expand in Bengaluru, Hyderabad, and Mumbai metropolitan regions.
Hospitals command the largest share; home care is gaining share fastest as digital platforms restructure patient access pathways.
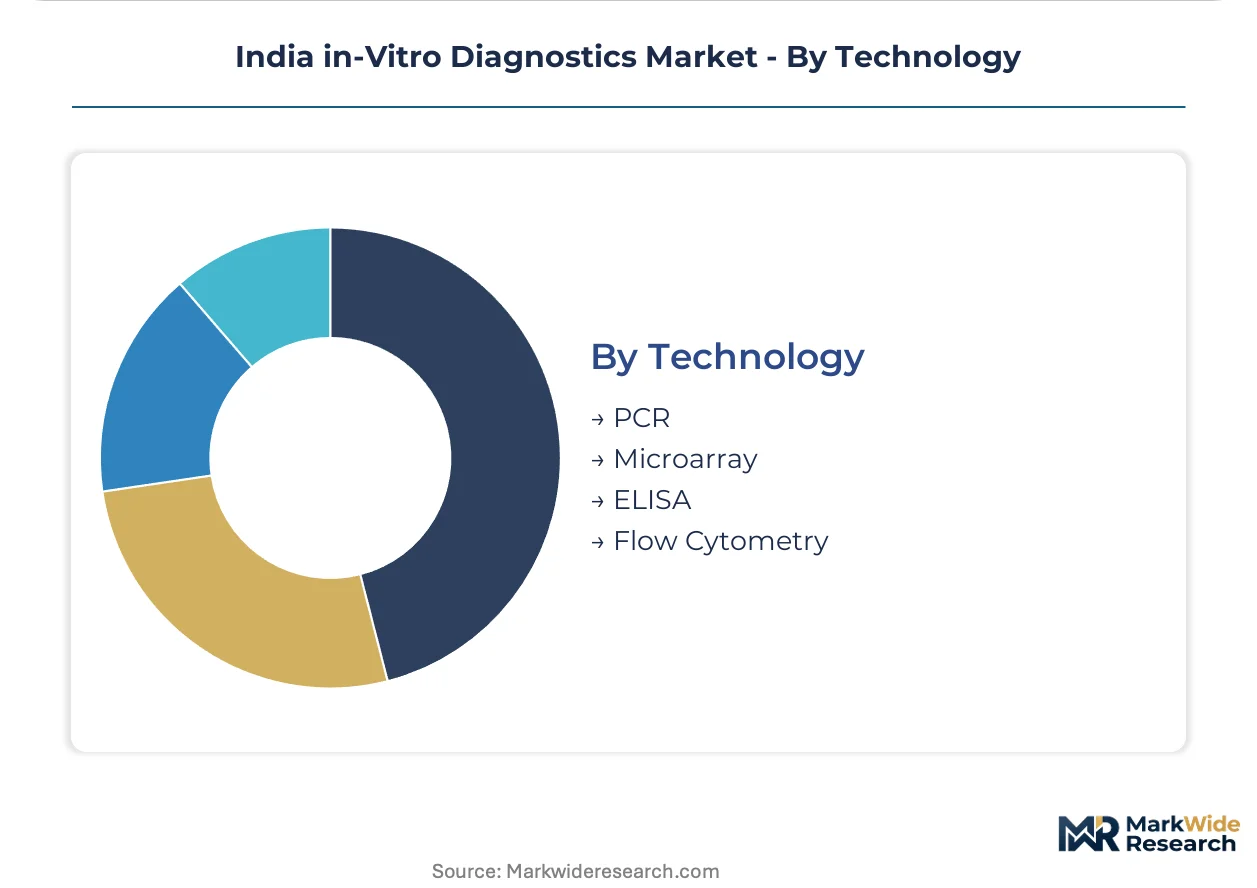
Technology:
Automation maturity and technician skill requirements differentiate adoption economics across method platforms.
- PCR:Nucleic acid amplification systems achieve picogram sensitivity for pathogen detection and genetic screening. Automated PCR platforms reduce technician-to-sample ratios in tuberculosis and antimicrobial resistance surveillance programs across Maharashtra public health networks.
- ELISA:Enzyme-linked immunosorbent assays retain cost advantages in high-throughput serology screening. National health programs deploy ELISA infrastructure for HIV and hepatitis B/C detection in district-level facilities.
- Flow Cytometry:Multi-parameter cell analysis requires specialized technicians scarce outside Karnataka and Maharashtra urban centers.
- Microarray:High-density nucleic acid probing supports oncology companion diagnostics and pharmacogenomic applications.
PCR holds the largest share; flow cytometry is expanding most quickly as hematology-oncology units upgrade analytical capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Indian states. Maharashtra and Karnataka laboratories absorb premium instrument placements with limited resistance. Tier-II and Tier-III facilities in Telangana and Gujarat demand aggressive reagent bundling and rental terms.
Maharashtra
Mumbai and Pune metropolitan laboratories anchor high-throughput molecular diagnostics demand. CDSCO's streamlined import licensing accelerates reagent kit market entry for established IVD categories. The Mumbai-Thane corridor concentrates reference laboratory networks where diagnostic chains consolidate processing capacity.
Karnataka
Bengaluru's biotech corridor drives oncology companion diagnostics and NGS panel adoption. BIS electromagnetic compatibility certification extends analyzer approval timelines by 4-6 months. The Bengaluru-Tumkur corridor anchors domestic instrument assembly operations alongside precision optics import dependencies.
Telangana
Hyderabad's diagnostic cluster expansion concentrates high-complexity testing demand in centralized facilities. The PLI scheme for medical devices compresses capital costs for domestic manufacturers. District-level hospital infrastructure creates captive reagent demand outside Hyderabad's saturated diagnostic networks.
Gujarat
Ahmedabad and Surat laboratories expand test menus amid pharmaceutical manufacturing adjacencies. CDSCO risk-based classification mandates clinical performance studies for novel biomarker assays entering the market. Reagent producers establish in-house clinical affairs teams to manage regulatory dossier preparation.
Delhi-NCR
AIIMS Delhi and Tata Memorial Centre anchor centralized oncology diagnostics with high-throughput NGS services. Public procurement centralization redistributes buyer power across government hospital networks. The Delhi-Gurgaon corridor exhibits densest point-of-care testing penetration in outpatient infectious disease screening.
India in-Vitro Diagnostics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across reagent production, instrument assembly, and diagnostic service delivery. The market structure concentrates in three archetypes: multinational instrument manufacturers with global assay portfolios, domestic reagent producers scaling automated platforms, and diagnostic service operators consolidating collection center networks. Dominant competitive moves include reagent rental instrument placements converting upfront equipment sales into recurring consumable revenue, and hub-and-spoke logistics models replacing dispersed standalone laboratory relationships.
Within the integrated multinational tier, Roche Diagnostics India Pvt Ltd and Abbott Healthcare Pvt Ltd exemplify premium positioning through global assay portfolios and metropolitan hospital anchoring. Among domestic specialists, Transasia Bio-Medicals Ltd occupies a position representing integrated instrument-reagent bundling targeted at mid-tier laboratories. Dr. Lal PathLabs sits within the diagnostic service operator archetype, exemplifying consumer-facing network consolidation through dense collection center penetration and direct-to-patient digital interfaces.
| Leading Market Players |
|---|
| Roche Diagnostics India Pvt Ltd |
| Abbott Healthcare Pvt Ltd |
| Siemens Healthineers India |
| Transasia Bio-Medicals Ltd |
| Beckman Coulter India |
| Dr. Lal PathLabs |
| SRL Diagnostics |
| Thyrocare |
| Agappe Diagnostics Ltd |
| Others |
Supply & Pricing Matrix
Reagent rental contracts with bundled instrument placements lock in multi-year consumable commitments while anchoring price visibility for diagnostic chains and hospital laboratories across Maharashtra and Karnataka procurement networks.
Pricing Analysis
After-sales consumable revenue streams drive lifetime value for instrument manufacturers operating in India. Reagent rental models convert upfront capital expenditure into recurring revenue with premium-mid-economy pricing differentiation based on test volume commitments and assay complexity tiers. Pricing pressure stems from CDSCO's streamlined import licensing for established IVD categories, which accelerates reagent kit market entry and intensifies competition. Tier-II and Tier-III hospitals in Telangana and Gujarat exhibit highest price sensitivity due to constrained capital budgets, while metropolitan reference laboratories in Mumbai and Bengaluru absorb premium placements with limited resistance.
Supply Chain Analysis
China and South Korea anchor fluorescence detection module and precision optics manufacturing for Indian IVD instrument assembly. Domestic reagent production clusters in Maharashtra and Telangana draw from imported enzyme and antibody raw materials, with PLI scheme incentives accelerating local manufacturing scale-up. Single-source vulnerability concentrates in East Asian optical component supply, exposing margins to currency volatility and logistics disruption. Distribution runs through diagnostic chain hub-and-spoke networks and direct hospital procurement channels, with consolidated collection center models replacing fragmented standalone laboratory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
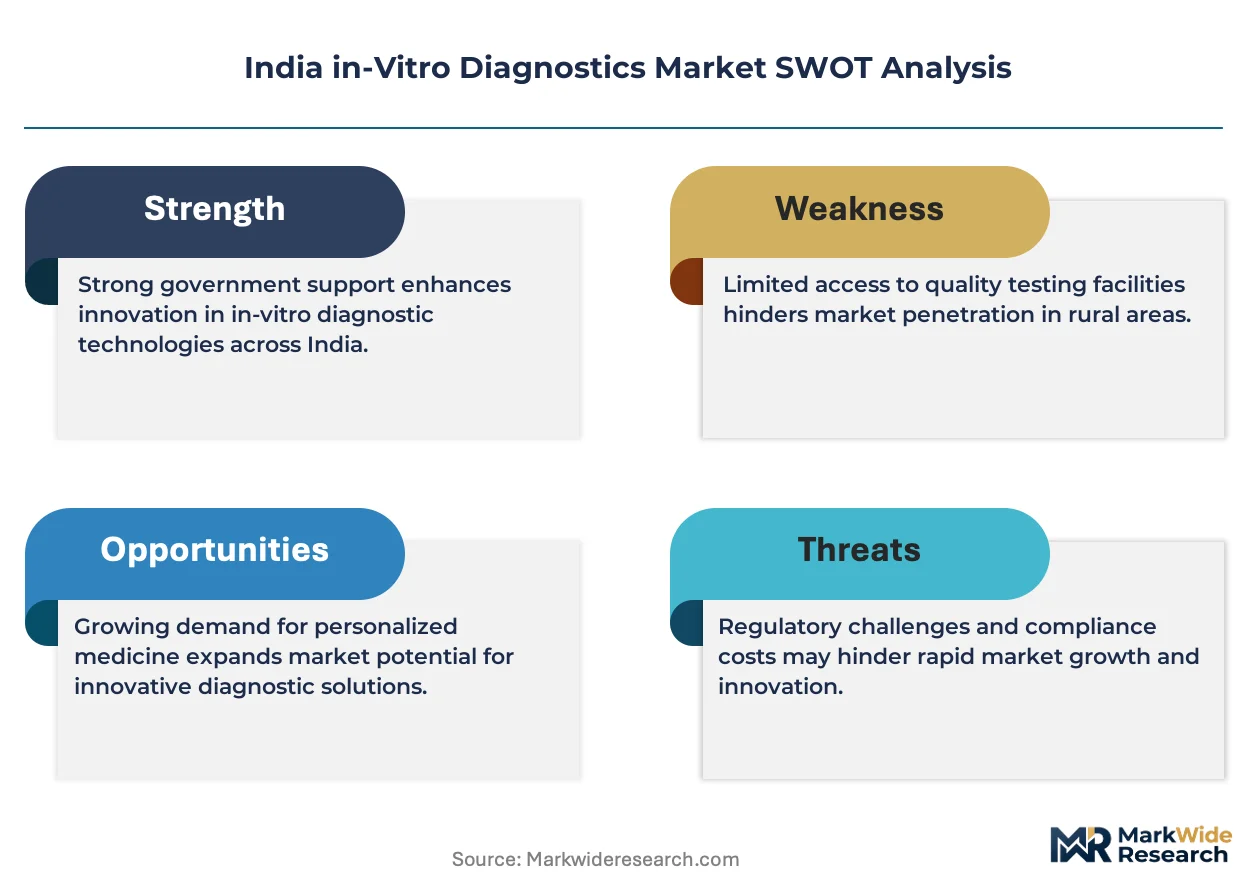
The India IVD market exhibits cyclical recovery characteristics as PLI scheme incentives and Tier-II hospital expansion create successive waves of instrument replacement and reagent demand acceleration.
For Market Incumbents: Compound defensive positioning through backward integration into domestic enzyme and antibody manufacturing, securing captive supply chains against import dependency risks. Deepen channel control via exclusive reagent rental contracts with Karnataka and Telangana diagnostic chains, locking out emerging competitors from high-volume reference laboratory networks. Prioritize CDSCO regulatory dossier investment for novel biomarker assays to maintain premium positioning amid classification expansion. For New Entrants and Emerging Players: Lead with AI-assisted pathology image analysis platforms targeting cytology screening workflows in district-level hospitals where technician scarcity constrains manual processing capacity. Penetrate Gujarat and Telangana Tier-III hospital segments through aggressive reagent bundling and rental terms, exploiting price sensitivity gaps left by multinational incumbents. Deploy capital-light software-as-a-service models to bypass capital-intensive instrument manufacturing barriers. For Investors and Strategic Acquirers: Capital is best deployed toward domestic reagent producers with automated platform scale-up trajectories and established CDSCO regulatory affairs capabilities. The five-to-ten year viability window favors acquisition targets with integrated instrument-reagent bundling expertise and dense collection center network penetration in Karnataka or Maharashtra. Monitor PLI scheme beneficiary announcements as inflection indicators for domestic manufacturing competitiveness shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Instrument Placement | Converts upfront equipment sales into recurring consumable revenue streams across Tier-II hospital networks. |
| CDSCO Regulatory Dossier Investment | Accelerates market entry for novel Class C and D IVD assays through streamlined risk-based classification pathways. |
| AI-Assisted Pathology Integration | Automates cytology screening workflows in laboratories facing clinical scientist shortages outside urban centers. |
| Hub-and-Spoke Logistics Consolidation | Replaces dispersed standalone laboratory relationships with integrated sample transport and centralized processing. |
| Backward Integration into Enzyme Manufacturing | Reduces import dependency for reagent raw materials under PLI scheme incentive structures. |
Research Methodology
Cross-validation between primary interviews with diagnostic chain procurement heads, hospital laboratory directors, biomedical engineers, and CDSCO regulatory affairs specialists and secondary validation through hospital procurement databases, GPO contracts, CDSCO Medical Device Rules notifications, and PLI scheme beneficiary disclosures anchors the qualitative findings. Bottom-up triangulation aggregates state-level test volume estimates across Maharashtra, Karnataka, Telangana, Gujarat, and Delhi-NCR, while top-down reconciliation cross-checks against national health program expenditure data and diagnostic chain revenue disclosures.
Sensitivity analysis around PLI scheme uptake rates, Tier-II hospital capital expenditure cycles, and CDSCO risk classification expansion timelines informs the analytical framework. Segmentation dimensions modeled include product type, application category, end-user archetype, and technology platform, with regional adoption patterns and regulatory cluster differentiation as cross-cutting variables. CAGRs derive from instrument placement trajectories, reagent consumption intensity per installed base unit, and test menu expansion rates across hospital tiers. Forecast inputs incorporate PCR platform automation adoption curves and NGS panel penetration in oncology companion diagnostics.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme extension, continued CDSCO regulatory streamlining, or stable East Asian optical component supply would require recalibration. Forecasts reflect documented assumptions regarding technician training pipeline expansion and diagnostic chain collection center network densification. Recalibration cycles align with material shifts in notified device status expansions and state-level procurement centralization policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Allergy Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Global Rapid Diagnostic Kits Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
Antigen Kit Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Global Saliva Collection and Diagnosis Market