
 Global Cardiovascular Disease Monitoring and Diagnostic Devices Market | 2026-2036
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market Foresight
Cardiac electrophysiology specialist labor is bifurcating the competitive landscape between premium device manufacturers and volume-driven suppliers. GE Healthcare leverages its imaging heritage to dominate integrated cath-lab ecosystems. Medtronic anchors its position through captive supply of implantable loop recorders and deep therapy-device linkages.
Cardiovascular disease monitoring and diagnostic devices encompass instruments that capture, process, and transmit hemodynamic, electrical, and structural cardiac data through specifications such as 12-lead ECG sampling rates exceeding 500 Hz and wireless telemetry ranges up to 30 meters. Their primary commercial purpose is enabling early arrhythmia detection and longitudinal heart failure management to reduce acute hospitalization incidence. Electrocardiogram devices and Holter monitors occupy mature, high-volume positions where margin pools have compressed toward service contracts and disposable electrode streams. Artificial intelligence analytics within the technology dimension represents the fastest-expanding margin pool, as cloud-based platforms shift pricing from capital expenditure toward per-patient subscription models.
FDA digital health pre-certification, EU MDR Class IIa/IIb conformity requirements, and Japan PMDA software-as-medical-device guidance collectively elevate validation costs while creating regulatory moats for established manufacturers. REACH and RoHS compliance in Europe further constrain material choices for wearable sensor housings and battery assemblies. Stakeholders must decide whether to build in-house regulatory intelligence across FDA, EMA, and PMDA jurisdictions or partner with specialized quality consulting firms as submission complexity escalates.
Market Dynamics
Cloud-based AI analytics platforms are compressing traditional hardware margins while elevating software-as-medical-device pathways through FDA pre-certification and EU MDR compliance requirements. This structural shift forces established manufacturers to rebuild pricing models around per-patient subscriptions rather than capital equipment sales.
Growth Catalysts
- FDA Digital Health Pre-Certification:The FDA's streamlined pathway for software-based cardiac diagnostics accelerates time-to-market for algorithm-driven arrhythmia detection platforms, reducing validation timelines for qualifying manufacturers.
- Integrated Cardiac Care Networks:Health systems in the United States, Germany, and Japan are consolidating procurement around single-vendor cath-lab ecosystems that bundle monitoring hardware with longitudinal data platforms.
- Remote Patient Monitoring:Wireless telemetry with 30-meter range specifications enables home-based heart failure management, shifting care delivery from hospital wards to ambulatory settings and expanding addressable patient populations.
Market Restraints
- EU MDR Class IIa/IIb Conformity Costs:Elevated clinical evidence requirements for wearable ECG devices and implantable loop recorders extend certification timelines and consume 15-20% of R&D budgets for mid-tier manufacturers.
- Electrode and Sensor Material Concentration:Silver-silver chloride electrode production concentrates in East Asian contract manufacturers, exposing device makers to input cost volatility and REACH/RoHS compliance complexity for European market access.
- Holter Monitor Saturation:Mature 12-lead ECG and 24-48 hour Holter segments face commoditization pressure as diagnostic accuracy thresholds plateau and service contracts become the primary margin source.
Strategic Opportunities
- Underpenetrated Ambulatory Surgery Centers:Cardiology clinics in India and Brazil lack integrated monitoring infrastructure, creating first-mover advantages for portable diagnostic platforms with simplified operator interfaces.
- AI-ECG Convergence:Machine learning algorithms trained on million-patient datasets enable predictive heart failure alerts by fusing electrical signals with implantable hemodynamic sensors, opening subscription revenue pools.
- Japan PMDA Software-as-Medical-Device Guidance:Explicit regulatory frameworks for cloud-based cardiac analytics reduce jurisdictional uncertainty and attract foreign developers to Asia-Pacific commercialization partnerships.
Industry Challenges
- Electrophysiologist Training Bottlenecks:Complex ablation mapping systems and AI-interpreted diagnostics require specialized operator certification that outpaces medical school pipeline output in most OECD markets.
- Legacy EMR Integration Friction:Hospital IT departments face 12-18 month implementation cycles to embed new cardiac monitoring data streams into existing electronic medical record architectures, delaying procurement decisions.
- Patent Thickets in Signal Processing:Dense intellectual property landscapes around QRS complex detection algorithms and noise-filtering methodologies force licensing negotiations or defensive R&D redirection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiovascular Disease Monitoring and Diagnostic Devices Market |
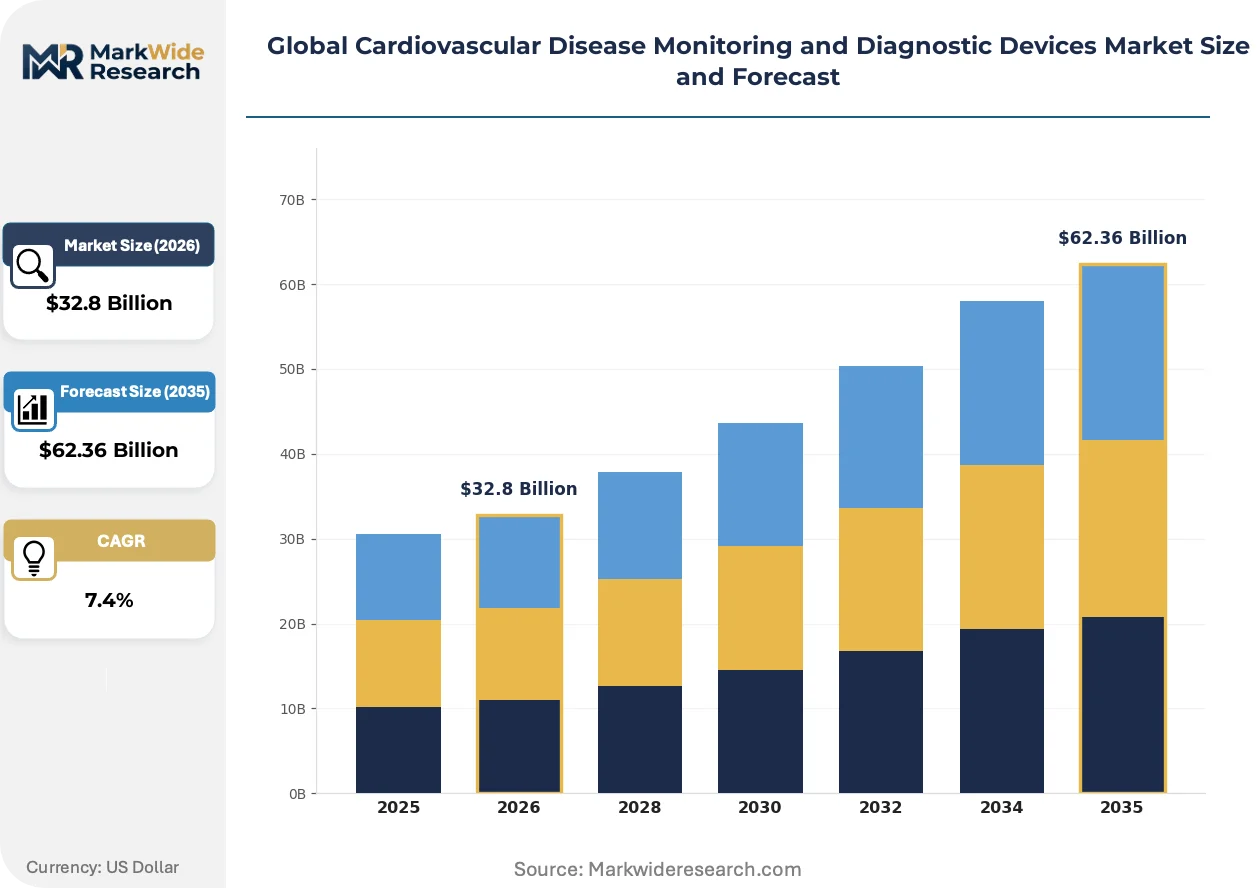
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $62.36 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrocardiogram Devices, Holter Monitors, Blood Pressure Monitors, Cardiac Event Recorders, Doppler Ultrasound, Implantable Loop Recorders Technology: Wearable Sensors, Wireless Monitoring, Optical Sensors, Telemetry Systems, Artificial Intelligence Analytics, Cloud-Based Platforms Application: Arrhythmia Detection, Heart Failure Management, Hypertension Monitoring, Ischemic Heart Disease Screening, Stroke Risk Assessment, Peripheral Artery Disease Evaluation End User: Cardiology Clinics, Diagnostic Laboratories, Primary Care Centers, Ambulatory Surgical Centers, Telehealth Providers, Specialized Cardiac Institutes |
| Companies Covered | GE Healthcare, Philips Healthcare, Medtronic, Abbott, Boston Scientific Corporation, Siemens Healthcare, Nihon Kohden Corporation, Schiller AG, Welch Allyn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market Shifts & Advancements
Algorithmic interpretation of cardiac electrical signals is restructuring competitive advantage away from hardware precision toward predictive clinical utility. Three convergent developments define this transformation.
Patch-based ambulatory monitors with solid-state electrodes are displacing traditional wired Holter systems in arrhythmia screening protocols. Cardiology clinics in the United States and Germany now prescribe adhesive patch devices for 7-14 day monitoring windows. This displacement collapses the distinction between diagnostic and monitoring modalities, compressing capital equipment refresh cycles toward 18-24 months.
EU MDR Class IIb requirements for active implantable devices now mandate post-market clinical follow-up studies for implantable loop recorders. Manufacturers must submit periodic safety updates to notified bodies, increasing regulatory staffing needs. The transcatheter electrophysiology segment absorbs the heaviest compliance burden, with smaller players exiting rather than absorbing validation costs.
Hospital procurement committees now unbundle hardware acquisition from algorithm licensing, creating separate vendor relationships for device supply and AI analytics. Academic medical centers in Japan and the Netherlands lead this bifurcation, signing direct contracts with cloud-platform developers. This purchasing pattern fragments supplier power and exposes hardware manufacturers to margin pressure on both ends of the value chain.
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market Segmentation
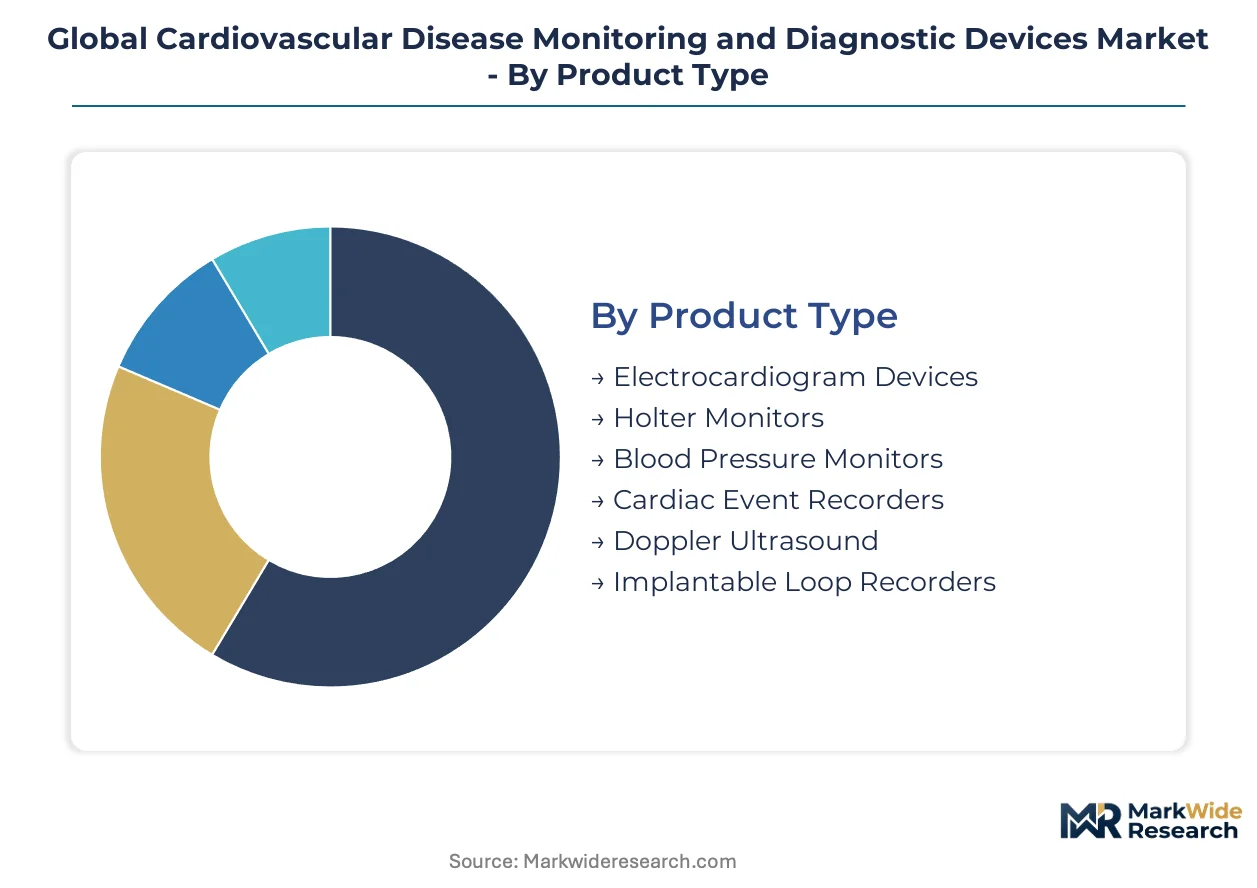
Segmentation in cardiovascular monitoring reveals how margin pools migrate from hardware commoditization toward software-enabled recurring revenue. Understanding these boundaries helps manufacturers allocate R&D budgets across device engineering, algorithm development, and platform integration.
Product Type:
Margin concentration in this category tilts toward implantable and patch-based systems that generate recurring service revenue, while traditional bedside equipment faces pricing compression.
- Electrocardiogram Devices:12-lead systems with sampling rates exceeding 500 Hz remain the diagnostic standard in hospital settings. Demand concentrates in Germany and Japan where integrated cardiac care networks require high-throughput screening capabilities, though procurement committees increasingly unbundle hardware from software licensing.
- Holter Monitors:24-48 hour wired recording systems dominate arrhythmia screening protocols in cardiology clinics. The United States absorbs the highest volume, yet adhesive patch alternatives are compressing refresh cycles toward 18-24 months and collapsing service contract margins.
- Blood Pressure Monitors:Oscillometric devices with wireless telemetry ranges up to 30 meters enable home-based hypertension management.
- Cardiac Event Recorders:Patient-activated and auto-triggered devices capture transient arrhythmias outside clinical settings.
- Doppler Ultrasound:Handheld and cart-based systems assess valvular function and hemodynamic parameters at point-of-care.
- Implantable Loop Recorders:Subcutaneous devices with multi-year battery life provide continuous monitoring for cryptogenic stroke evaluation, commanding premium pricing through deep therapy-device linkages.
The dominant share belongs to Electrocardiogram Devices, while Implantable Loop Recorders are closing the gap fastest through subscription-based remote monitoring contracts.
Technology:
Volume in this category clusters around established telemetry infrastructure, though fastest expansion occurs where AI analytics transform raw signals into predictive clinical alerts.
- Wearable Sensors:Solid-state electrode patches and photoplethysmography wristbands capture continuous cardiac data without clinical supervision. Demand concentrates in telehealth provider networks across the United States, where FDA digital health pre-certification accelerates algorithm-driven arrhythmia detection deployment.
- Wireless Monitoring:Bluetooth and proprietary radio protocols transmit hemodynamic data across 30-meter ranges for home-based heart failure management. Germany's integrated cardiac care networks drive adoption, shifting care delivery from hospital wards to ambulatory settings and expanding addressable patient populations.
- Optical Sensors:Green LED and infrared photodetectors enable pulse waveform analysis in consumer and medical-grade wearables.
- Telemetry Systems:Centralized monitoring stations aggregate multi-patient data streams in acute care environments.
- Artificial Intelligence Analytics:Machine learning algorithms trained on million-patient datasets enable predictive heart failure alerts by fusing electrical signals with implantable hemodynamic sensors.
- Cloud-Based Platforms:Per-patient subscription models replace capital expenditure pricing, elevating software-as-medical-device pathways through FDA pre-certification and EU MDR compliance requirements.
Wireless Monitoring holds the largest installed base, though Artificial Intelligence Analytics is expanding most quickly as cloud platforms shift vendor economics toward recurring revenue.
Application:
Commercial significance in this category follows the prevalence of chronic conditions requiring longitudinal management rather than episodic intervention.
- Arrhythmia Detection:Atrial fibrillation screening drives the highest device utilization rates across all monitoring modalities. Cardiology clinics in Japan and the United States prescribe adhesive patch devices for 7-14 day monitoring windows, displacing traditional wired Holter systems and compressing capital equipment refresh cycles.
- Heart Failure Management:Pulmonary artery pressure monitoring and implantable hemodynamic sensors enable proactive therapeutic adjustment. Academic medical centers in the Netherlands lead unbundled procurement patterns, signing direct contracts with cloud-platform developers separate from hardware vendors.
- Hypertension Monitoring:Ambulatory blood pressure tracking guides medication titration in primary care settings.
- Ischemic Heart Disease Screening:Stress testing and continuous monitoring detect silent ischemia in high-risk cohorts.
- Stroke Risk Assessment:Extended cardiac monitoring identifies paroxysmal atrial fibrillation in cryptogenic stroke patients.
- Peripheral Artery Disease Evaluation:Ankle-brachial index measurement and segmental pressure analysis guide revascularization decisions.
Arrhythmia Detection commands the greatest revenue concentration, while Heart Failure Management is gaining share fastest through value-based care contracts that reward hospitalization reduction.
End User:
Purchasing power in this category fragments across institutional buyers with divergent technical requirements and budget cycles.
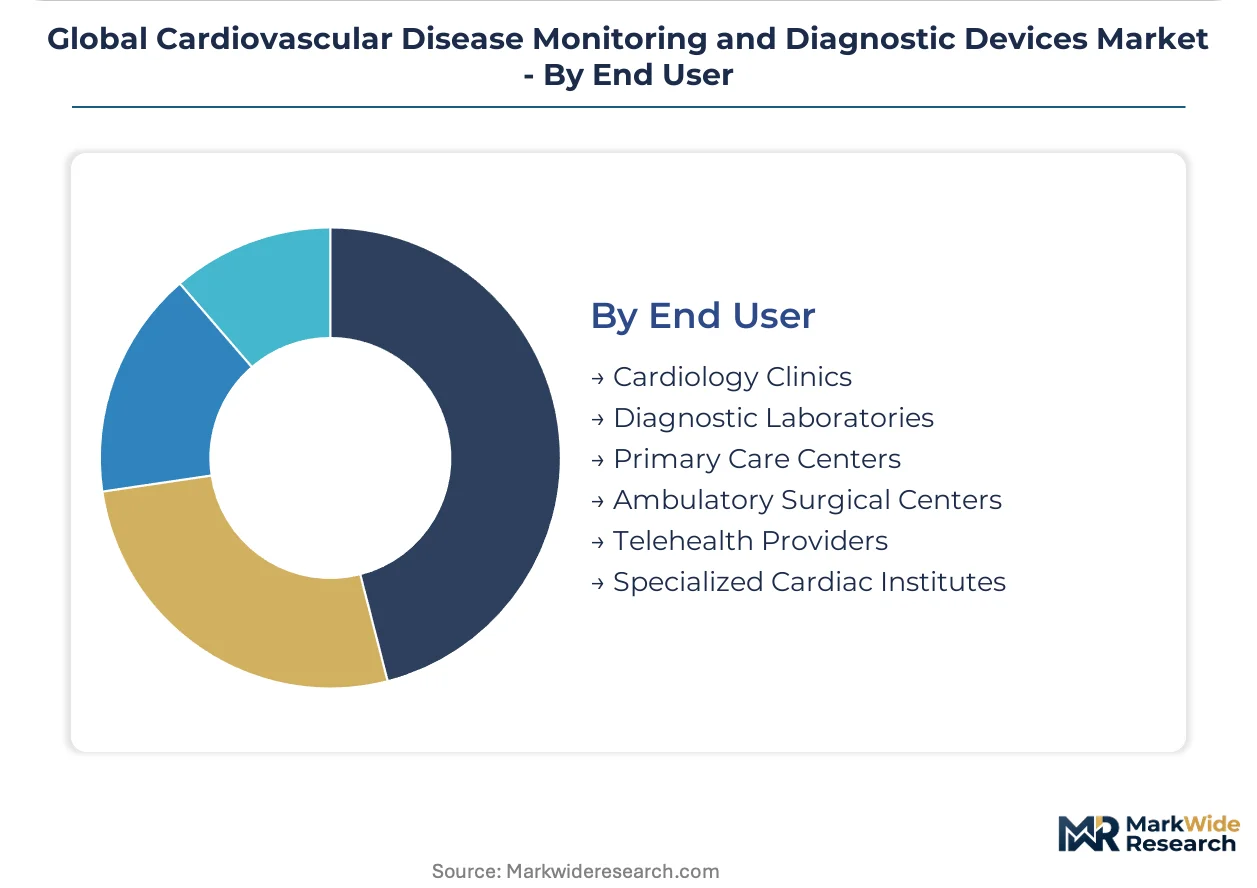
- Cardiology Clinics:Specialist practices demand integrated cath-lab ecosystems that bundle monitoring hardware with longitudinal data platforms. Procurement in the United States and Germany consolidates around single-vendor relationships, with GE Healthcare leveraging imaging heritage to dominate these workflows.
- Diagnostic Laboratories:High-throughput ECG interpretation services require automated analysis tools and regulatory-compliant reporting infrastructure.
- Primary Care Centers:Generalist physicians prioritize simplified operator interfaces and clear diagnostic outputs for initial cardiac assessment.
- Ambulatory Surgical Centers:Pre-operative screening and post-procedural monitoring create demand for portable diagnostic platforms in India and Brazil, where underpenetrated infrastructure offers first-mover advantages.
- Telehealth Providers:Remote patient monitoring programs require FDA-cleared devices with seamless data transmission to cloud platforms.
- Specialized Cardiac Institutes:Tertiary referral centers absorb complex ablation mapping systems and AI-interpreted diagnostics requiring specialized operator certification.
Cardiology Clinics retain the dominant procurement volume, though Telehealth Providers are climbing the fastest as reimbursement codes mature for remote physiological monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States prioritizes AI-integrated remote monitoring platforms, while Germany and Japan emphasize cath-lab ecosystem consolidation. China and India represent volume frontiers where simplified portable devices address infrastructure gaps.
United States
Cardiology clinics drive demand for adhesive patch monitors with 7-14 day recording windows. FDA digital health pre-certification accelerates algorithm-driven arrhythmia detection deployment. Academic medical centers in Boston and the Research Triangle lead unbundled procurement, separating hardware acquisition from cloud analytics licensing.
Germany
Integrated cardiac care networks mandate high-throughput 12-lead ECG systems with 500+ Hz sampling rates. EU MDR Class IIa/IIb conformity requirements elevate clinical evidence burdens for wearable device manufacturers. The Baden-Württemberg medical technology cluster around Stuttgart hosts concentrated cath-lab equipment engineering capabilities.
Japan
Specialized cardiac institutes absorb complex ablation mapping systems requiring electrophysiologist certification. PMDA software-as-medical-device guidance reduces regulatory uncertainty for foreign cloud-platform developers. The Kanto region around Tokyo anchors procurement for implantable loop recorders with multi-year battery specifications.
China
Domestic manufacturers scale production of oscillometric blood pressure monitors with 30-meter wireless telemetry. NMPA medical device registration timelines compress for Class II diagnostic equipment. The Yangtze River Delta manufacturing belt supplies solid-state electrode components to regional patch-monitor assemblers.
India
Ambulatory surgical centers in Maharashtra and Karnataka lack integrated monitoring infrastructure, creating demand for simplified operator interfaces. CDSCO medical device rules impose quality management system requirements on imported diagnostic equipment. Hyderabad's health technology corridor attracts first-mover portable platform deployments.
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. Premium device manufacturers leverage imaging heritage and therapy-device linkages to dominate cath-lab ecosystems, while volume-driven suppliers compete on electrode streams and service contract pricing. Two strategic archetypes predominate: integrated imaging-to-therapy platforms and focused diagnostic hardware specialists. Competitive dynamics center on M&A consolidation around AI analytics capabilities and strategic partnerships to embed cloud platforms within hospital IT architectures.
Within the integrated platform tier, GE Healthcare and Philips Healthcare exemplify diversified healthcare conglomerates leveraging cross-modal imaging dominance. Medtronic anchors the implantable device segment through captive supply relationships and deep therapy linkages. These three entities represent contrasting pathways—imaging heritage, diversified health technology portfolios, and therapy-centric integration—each occupying defensible positions against software-driven margin compression.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| Siemens Healthcare |
| Nihon Kohden Corporation |
| Schiller AG |
| Welch Allyn |
| Others |
Supply & Pricing Matrix
Capacity utilization at East Asian contract electrode manufacturers shapes margin floors across the cardiovascular device value chain, concentrating bargaining power with silver-silver chloride suppliers while forcing Western device makers to absorb input volatility or redesign sensor architectures around alternative conductive materials.
Pricing Analysis
Long-term service contracts dominate procurement relationships for implantable loop recorders and cath-lab ecosystems, while spot purchases govern disposable electrode streams and patch-based ambulatory monitors. Price differentiation rests on FDA pre-certification tier and integrated algorithm licensing depth, with premium tiers commanding subscription multiples over hardware-only vendors. Cost compression in the Holter monitor segment is intensifying because adhesive patch alternatives collapse refresh cycles toward 18-24 months. Cardiology clinics in Germany and Japan exhibit lowest price sensitivity due to integrated care network mandates, whereas ambulatory surgical centers in India and Brazil prioritize simplified operator interfaces over feature depth.
Supply Chain Analysis
Port congestion along the Shanghai-Ningbo corridor and container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for solid-state electrode components and lithium primary batteries destined for implantable device assembly. Manufacturing concentration in China, South Korea, and Malaysia feeds global demand for photoplethysmography sensors and wireless telemetry modules. Raw material dependencies center on silver-silver chloride electrode substrates, lithium manganese dioxide cells, and medical-grade silicone housings. Single-source vulnerability concentrates in East Asian contract manufacturers for electrode production. Distribution runs through cardiology clinic procurement committees in the United States and Germany, hospital system GPOs, and direct telehealth provider contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA digital health pre-certification and EU MDR Class IIb conformity requirements creates durable defensive moats for established manufacturers, as validation timelines and clinical evidence burdens deter rapid competitive entry.
For Market Incumbents: Secure algorithm licensing relationships with academic medical centers before procurement committees complete unbundling of hardware from cloud analytics. Deepen captive supply arrangements for silver-silver chloride electrodes to insulate against REACH and RoHS compliance volatility in European market access. Medtronic's therapy-device linkages and GE Healthcare's imaging heritage demonstrate how integrated ecosystem control resists margin compression from software-only entrants. For New Entrants and Emerging Players: FDA digital health pre-certification offers the fastest regulatory pathway for algorithm-driven arrhythmia detection platforms targeting telehealth provider networks. Ambulatory surgical centers in Maharashtra and Karnataka present the most penetrable geography, lacking integrated monitoring infrastructure and prioritizing portable diagnostic platforms with simplified operator interfaces over feature-rich hospital-grade systems. Direct cloud-platform developer contracts with academic medical centers in the Netherlands and Japan bypass hardware vendor relationships entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI analytics specialists with million-patient training datasets and established FDA pre-certification status over hardware manufacturers facing commoditization pressure. Long-term viability across the projection horizon rests on recurring revenue conversion and regulatory moat sustainability. Acquisition targets should demonstrate established cloud-platform deployments with per-patient subscription economics. The signal to monitor is hospital procurement committee unbundling velocity—accelerated separation of hardware acquisition from algorithm licensing indicates structural margin pressure on device-only manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerates algorithm-driven arrhythmia detection deployment for qualifying manufacturers through streamlined validation pathways. |
| CE Marking Pathway under EU MDR | Class IIa/IIb conformity requirements elevate clinical evidence burdens that favor established players with regulatory staffing scale. |
| Hospital System Partnership | Integrated cardiac care networks in Germany and Japan consolidate procurement around single-vendor cath-lab ecosystems. |
| Software Companion Development | Cloud-based platforms shift vendor economics from capital expenditure toward per-patient subscription recurring revenue. |
| Reimbursement Strategy | Value-based care contracts rewarding hospitalization reduction expand addressable populations for heart failure management platforms. |
Research Methodology
Operator-level perspectives from electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this cardiovascular device analysis. Primary interviews with cardiology clinic administrators and telehealth provider network directors combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation converged on segment-level estimates.
Sensitivity analysis across regulatory approval timelines, reimbursement code adoption curves, and electrode input cost scenarios framed the forecast uncertainty envelope. Segmentation dimensions modeled include product type, technology architecture, clinical application, and end-user procurement archetype across the analysis window. CAGRs derived from installed base evolution, replacement cycle compression, and subscription revenue conversion trajectories. Forecast inputs incorporated FDA pre-certification pipeline velocity and EU MDR transition completion rates.
Decision-makers should treat outputs as directional under assumptions of continued digital health regulatory streamlining and stable silver commodity pricing; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding algorithm adoption curves and hospital IT integration friction. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market