
 Thyroid Cancer Diagnostics Market | 2026-2036
Thyroid Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Thyroid Cancer Diagnostics Market Intelligence
A capital-intensity divergence between integrated platform vendors and point-of-care specialists is unwinding competitive stability across the diagnostics landscape. F. Hoffmann-La Roche Ltd leverages its centralized laboratory automation footprint to sustain high-throughput molecular testing workflows. Thermo Fisher Scientific, Inc. anchors its position through captive reagent supply chains and sequencing instrumentation ecosystems. Siemens Healthcare GmbH competes on imaging-to-pathology integration, controlling hardware-software bundles that span ultrasound through molecular confirmation.
Thyroid cancer diagnostics encompasses the detection, characterization, and monitoring of malignant neoplasms arising from follicular epithelial or parafollicular C cells through histopathological examination, serum biomarker quantification, and molecular profiling of BRAF, RAS, RET/PTC, and PAX8/PPARγ alterations. Imaging technology segments span ultrasound, CT scan, MRI, and PET scan modalities, with ultrasound dominating initial nodule evaluation due to cost efficiency and widespread availability while PET scan applications concentrate in recurrence monitoring and staging refinement. Molecular testing represents the fastest-expanding product category, driven by rising demand for preoperative risk stratification and targeted therapy selection, whereas blood tests remain mature with limited margin expansion outside specialized thyroid panel reference laboratories.
The FDA governs in vitro diagnostic approvals and clinical trial endpoints for companion assays, while the Clinical Laboratory Improvement Amendments framework shapes laboratory-developed test accessibility and quality benchmarks. EMA's In Vitro Diagnostic Regulation introduces stricter performance validation requirements that elevate compliance costs for European market entry. Stakeholders must monitor evolving payer coverage policies for liquid biopsy applications and decide between decentralized point-of-care investment versus centralized platform consolidation before reimbursement landscapes crystallize.
Market Dynamics
Centralized laboratory consolidation is compressing molecular testing margins while simultaneously elevating barriers for point-of-care entrants, creating a bifurcated competitive landscape where scale economics dominate high-throughput workflows.
Growth Catalysts
- Companion diagnostic guidelines:FDA's expanding framework for precision assay reimbursement is accelerating hospital laboratory investment in BRAF and RAS profiling platforms.
- Integrated health networks:United States-based hospital systems are consolidating reference laboratory contracts, driving volume concentration toward automated molecular platforms.
- Preoperative risk stratification:Surgical oncology departments now mandate molecular confirmation before thyroidectomy, embedding testing into standard care pathways.
Market Restraints
- Reagent supply concentration:Captive supply chains for sequencing chemistries concentrate among three dominant instrumentation vendors, creating procurement vulnerability.
- EMA IVDR compliance costs:Europe's stricter performance validation requirements elevate capital requirements for market entry, disadvantaging mid-scale laboratories.
- Ultrasound cost floor:Initial nodule evaluation relies on widely available imaging with minimal margin expansion potential, capping revenue per diagnostic episode.
Strategic Opportunities
- Liquid biopsy reimbursement:Payer coverage expansion for circulating tumor DNA monitoring in recurrence surveillance creates new service line potential.
- Imaging-to-pathology integration:Hardware-software bundles spanning ultrasound through molecular confirmation offer bundled pricing power against standalone vendors.
- Decentralized point-of-care:Community oncology clinics in underserved United States regions present volume capture potential before reimbursement landscapes crystallize.
Industry Challenges
- Molecular pathologist scarcity:Interpretation of RET/PTC and PAX8/PPARγ alterations requires specialized training that academic medical centers struggle to staff.
- Laboratory Information System integration:Legacy hospital IT infrastructure creates friction when connecting new molecular platforms to electronic health record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyroid Cancer Diagnostics Market |
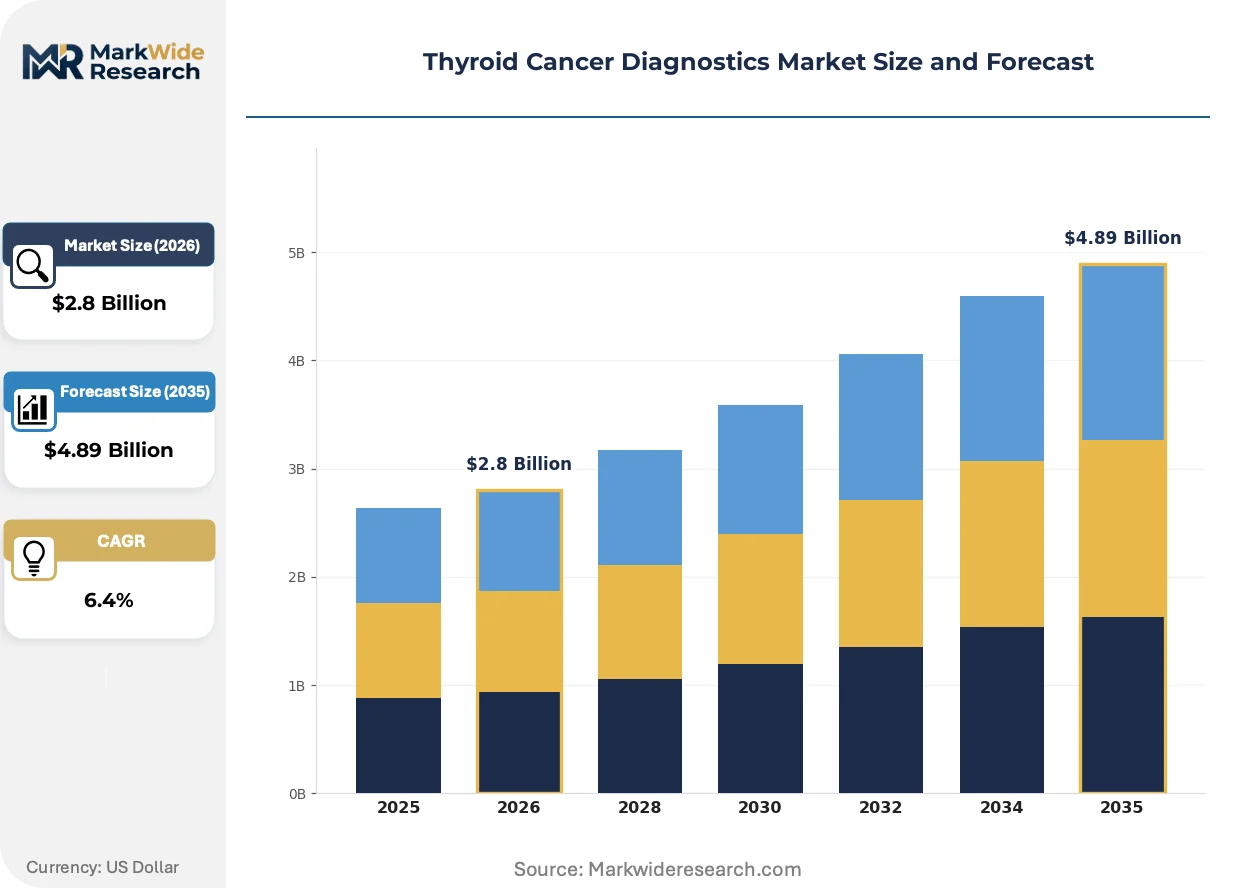
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Imaging, Blood Tests, Molecular Testing Technology: Ultrasound, CT Scan, MRI, PET Scan End User: Hospitals, Diagnostic Centers, Research Laboratories, Clinics Application: Screening, Staging, Monitoring, Prognosis |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott, Thermo Fisher Scientific, Inc., Siemens Healthcare GmbH, GE HealthCare, Bio-Rad Laboratories, Inc., Agilent Technologies, Inc., Illumina, Inc., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyroid Cancer Diagnostics Market Strategic Shifts & Innovations
Next-generation sequencing workflows are compressing turnaround times for mutational profiling while regulatory frameworks simultaneously tighten performance validation requirements. These forces are reshaping vendor competitive positions and buyer procurement criteria.
Multi-gene panel testing is displacing single-analyte BRAF assays in preoperative risk stratification. Academic medical centers and large integrated delivery networks now mandate comprehensive mutational profiling before surgical intervention. This shift is displacing lower-complexity immunohistochemistry workflows and compressing margins for standalone FISH laboratories.
EMA's In Vitro Diagnostic Regulation introduces post-market surveillance obligations and clinical evidence requirements that exceed predecessor directives. European reference laboratories must now maintain quality management systems comparable to pharmaceutical manufacturing standards. Small and mid-scale diagnostic providers are responding through partnership arrangements with multinational platform vendors rather than independent compliance investment.
Hospital procurement departments now unbundle after-sales service contracts from capital equipment purchases, negotiating multi-vendor maintenance agreements. This behavior disrupts traditional captive reagent-supply economics that instrumentation vendors relied upon for margin protection. The United States exhibits the most pronounced shift, where group purchasing organizations aggregate laboratory capital expenditure across health system networks.
Thyroid Cancer Diagnostics Market Segmentation
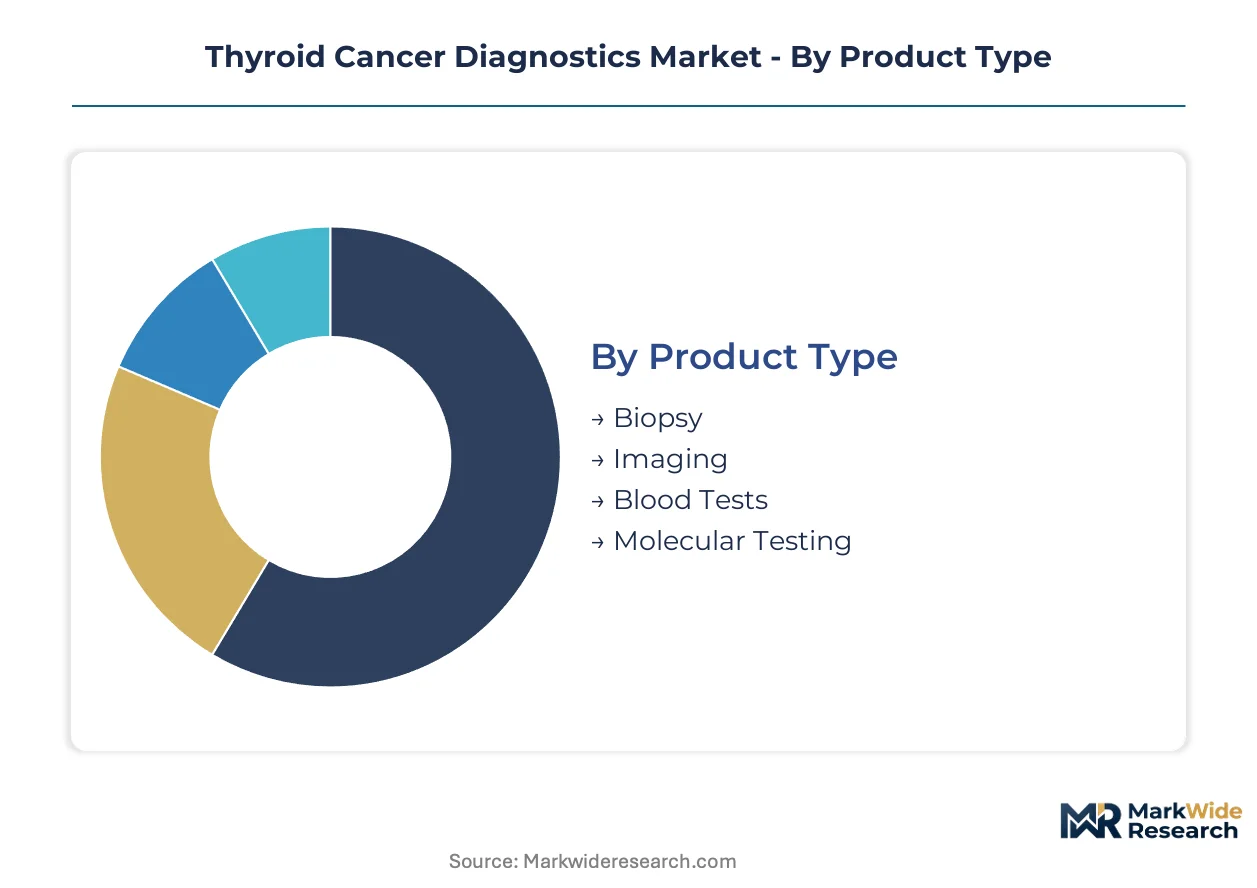
Segmentation in thyroid cancer diagnostics reveals how clinical workflow integration and reimbursement pathways shape purchasing decisions across hospital systems. Product type and technology segments exhibit divergent margin profiles, while end-user concentration determines platform scalability requirements.
Product Type:
Molecular testing platforms command premium pricing in domestic United States markets, whereas imaging modalities sustain volume through export-led equipment sales to Asia-Pacific hospital networks.
- Molecular Testing:Multi-gene panels profile BRAF, RAS, RET/PTC, and PAX8/PPARγ alterations for preoperative risk stratification. United States academic medical centers now mandate comprehensive profiling before thyroidectomy, embedding these assays into standard surgical oncology pathways.
- Imaging:Ultrasound dominates initial nodule evaluation due to cost efficiency and widespread availability, while PET scan applications concentrate in recurrence monitoring and staging refinement. German and Japanese hospital systems drive premium imaging equipment demand through centralized procurement.
- Biopsy:Fine-needle aspiration procedures generate recurring consumable revenue for pathology laboratories.
- Blood Tests:Thyroid panel reference laboratories in the United States and United Kingdom maintain mature service lines with limited margin expansion.
Molecular testing holds the largest share; momentum sits with imaging-to-pathology integration bundles.
Technology:
Cost tier stratification separates premium PET-CT installations from standard ultrasound deployments, with mid-tier MRI occupying hospital capital budgets in secondary markets.
- Ultrasound:High-frequency transducers enable real-time nodule characterization with elastography and Doppler assessment. Community hospitals in India and Brazil deploy these systems for initial triage before referral to tertiary centers.
- PET Scan:Fluorodeoxyglucose imaging identifies metastatic recurrence and guides radioactive iodine therapy decisions. South Korean and Australian oncology networks prioritize PET-CT procurement for surveillance protocols.
- CT Scan:Cross-sectional anatomy evaluation supports surgical planning and extrathyroidal extension assessment.
- MRI:Soft tissue contrast resolution aids recurrent laryngeal nerve mapping in complex reoperations.
Ultrasound holds the largest share; momentum sits with PET scan surveillance applications.
End User:
Customer type concentration favors integrated delivery networks consolidating reference laboratory contracts, while standalone diagnostic centers compete on turnaround time in fragmented metropolitan markets.
- Hospitals:Hospital-based oncology departments drive rising adoption of automated molecular testing platforms. United States health systems including Mayo Clinic and Cleveland Clinic anchor high-throughput workflows through centralized laboratory consolidation.
- Diagnostic Centers:Independent facilities compete on biopsy turnaround and cytopathology interpretation speed. Commercial laboratories in Texas and Florida capture outpatient volume through physician office partnerships.
- Research Laboratories:Academic medical centers validate novel biomarker assays under FDA investigational device exemption frameworks.
- Clinics:Community endocrinology practices in underserved United States regions present point-of-care volume capture potential.
Hospitals hold the largest share; momentum sits with diagnostic center consolidation.
Application:
Volume distribution across the care continuum shows screening dominating incident cases while monitoring generates recurring revenue per patient.
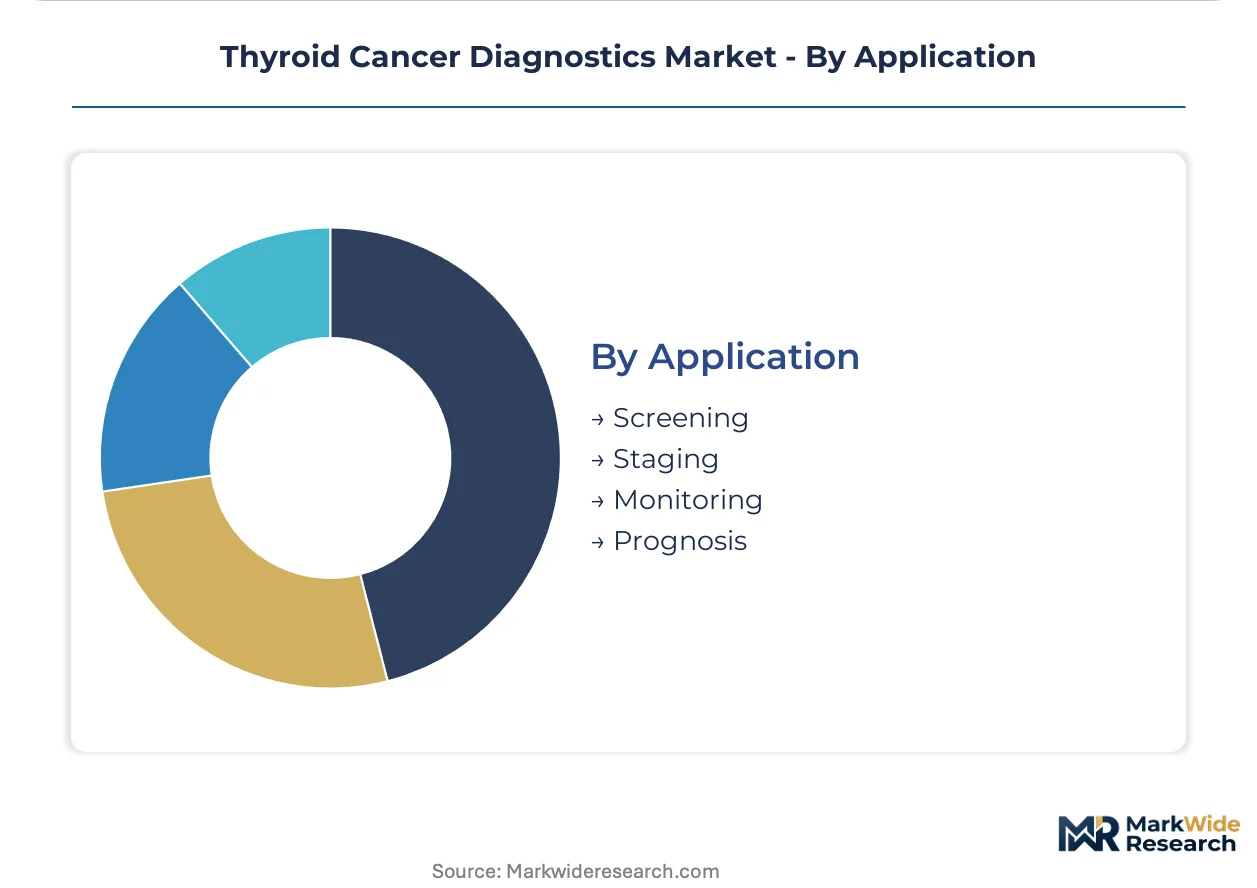
- Screening:Incidental nodule detection during unrelated imaging studies drives downstream diagnostic cascade. United States radiology practices flag thyroid abnormalities on CT chest and carotid ultrasound examinations.
- Monitoring:Circulating thyroglobulin and anti-thyroglobulin antibody quantification tracks recurrence after total thyroidectomy. German and French endocrinology societies mandate structured surveillance protocols.
- Staging:TNM classification integrates molecular risk signatures with anatomic extent assessment.
- Prognosis:Multivariate risk calculators incorporate histologic grade and mutational profile for survival estimation.
Screening holds the largest share; momentum sits with monitoring service line expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a diagnostics trade surplus in molecular platforms, while Germany and Japan import imaging instrumentation components from specialized Asian suppliers. South Korea and Australia concentrate PET-CT procurement for surveillance protocols, creating regional demand clusters that diverge from North American purchasing patterns.
United States
Hospital-based oncology departments at Mayo Clinic and Cleveland Clinic anchor high-throughput molecular testing workflows through centralized laboratory consolidation. FDA companion diagnostic guidelines reshape reimbursement pathways for precision assays, accelerating BRAF and RAS profiling platform investment. Texas and Florida commercial laboratories capture outpatient volume through physician office partnerships in fragmented metropolitan markets.
Germany
German hospital systems drive premium imaging equipment demand through centralized procurement of ultrasound and PET-CT systems for nodule evaluation. EMA In Vitro Diagnostic Regulation introduces stricter performance validation requirements that elevate compliance costs for European market entry. Bavarian reference laboratories maintain quality management systems comparable to pharmaceutical manufacturing standards under post-market surveillance obligations.
Japan
Japanese oncology networks prioritize PET-CT procurement for structured recurrence surveillance protocols mandated by national endocrinology societies. METI industrial policy supports domestic imaging equipment manufacturers competing on hardware-software integration. Tokyo and Osaka academic medical centers validate novel biomarker assays under PMDA investigational device exemption frameworks.
South Korea
South Korean health technology assessment processes accelerate adoption of next-generation sequencing workflows for preoperative risk stratification. MFDS regulatory pathways streamline approvals for multi-gene panel testing platforms in tertiary hospital networks. Seoul-based integrated delivery networks consolidate reference laboratory contracts toward automated molecular platforms.
Australia
Australian oncology networks emphasize PET scan applications in recurrence monitoring and staging refinement for thyroid cancer patients. TGA oversight governs in vitro diagnostic approvals with alignment to international harmonization frameworks. Sydney and Melbourne diagnostic centers compete on biopsy turnaround speed against hospital-based pathology departments.
Thyroid Cancer Diagnostics Market Key Industry Players
Concentration sits with multinational instrumentation vendors controlling captive reagent supply chains and sequencing chemistry ecosystems. Three dominant platform providers anchor high-throughput molecular workflows through centralized laboratory automation footprints. Competitive moves center on imaging-to-pathology hardware-software bundling and multi-vendor maintenance agreement negotiations that disrupt traditional after-sales service economics.
Among Swiss and German-based diversified healthcare conglomerates, F. Hoffmann-La Roche Ltd and Siemens Healthcare GmbH occupy positions spanning diagnostics through therapeutic areas. Thermo Fisher Scientific, Inc. represents the captive supply chain archetype through sequencing instrumentation ecosystems. These three entities exemplify the scale-driven tier where automated platform consolidation determines procurement outcomes.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott |
| Thermo Fisher Scientific, Inc. |
| Siemens Healthcare GmbH |
| GE HealthCare |
| Bio-Rad Laboratories, Inc. |
| Agilent Technologies, Inc. |
| Illumina, Inc. |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
High-throughput molecular platform scale economies at United States academic medical centers compress per-test costs while simultaneously elevating price floors for mid-scale laboratories lacking automation density. This concentration dynamic bifurcates procurement outcomes: integrated health networks extract volume discounts from captive reagent suppliers, while standalone diagnostic centers absorb premium pricing for decentralized point-of-care assays.
Pricing Analysis
Hospital laboratory procurement committees anchor contract-based long-term offtake pricing for multi-gene panel platforms, with differentiation driven by FDA companion diagnostic certification tier and after-sales service bundling. Cost compression in standard ultrasound imaging intensifies because equipment vendors compete on hardware-software integration rather than standalone modality sales. Community endocrinology clinics exhibit highest price sensitivity due to limited capital budgets, whereas Mayo Clinic and Cleveland Clinic anchor premium tier negotiations through centralized volume concentration.
Supply Chain Analysis
Port congestion at Los Angeles and Long Beach elevates inbound logistics costs for sequencing instrumentation components sourced from Japanese and German precision manufacturers. Reagent supply chains draw from United States, Germany, and South Korea for sequencing chemistries and molecular assay consumables. Single-source vulnerability concentrates in Illumina sequencing cartridge production, with distribution running through group purchasing organization contracts to hospital network consolidated laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thyroid cancer diagnostics market sits in post-pandemic cyclical recovery as deferred surgical oncology procedures return to baseline scheduling and hospital capital expenditure resumes for molecular platform upgrades.
For Market Incumbents: Fortify automated platform consolidation through backward integration into sequencing chemistry production, countering procurement vulnerability from captive reagent suppliers. Defend high-throughput molecular workflow margins by embedding BRAF and RAS profiling into standard preoperative pathways before point-of-care entrants capture community clinic volume. For New Entrants and Emerging Players: FDA Breakthrough Device designation fast-tracks reimbursement pathway establishment for liquid biopsy surveillance assays, opening white-space in recurrence monitoring service lines. Target underserved United States community oncology regions in Texas and Florida where diagnostic center fragmentation persists, deploying rapid-turnaround cytopathology partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors imaging-to-pathology integration specialists with hardware-software bundling capabilities over standalone modality vendors. Long-term viability across the analysis window hinges on reimbursement landscape crystallization for circulating tumor DNA applications. Watch liquid biopsy coverage determinations from CMS and major commercial payers as the inflection indicator for service line expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Pathway Alignment | FDA reimbursement guidelines reshape hospital laboratory investment priorities for precision assay platforms. |
| Imaging-to-Pathology Integration | Siemens Healthcare GmbH controls bundled hardware-software contracts spanning ultrasound through molecular confirmation. |
| Decentralized Point-of-Care Deployment | Community clinic volume capture in underserved United States regions precedes reimbursement landscape crystallization. |
| Liquid Biopsy Reimbursement Strategy | Payer coverage expansion for circulating tumor DNA monitoring creates new service line potential in surveillance. |
| Multi-Gene Panel Standardization | Academic medical centers now mandate comprehensive BRAF, RAS, RET/PTC profiling before thyroidectomy procedures. |
Research Approach
Initial hypotheses were tested against primary input from molecular pathologists, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads at sequencing platform vendors and refined through secondary validation. Sources included FDA 510(k) filings and companion diagnostic approval databases, CMS Medicare coverage determinations, hospital procurement contract disclosures, and EMA IVDR implementation guidance documents. Bottom-up test volume modeling and top-down health system expenditure analysis were triangulated against manufacturer shipment data.
Variance decomposition across the projection horizon isolates volume drivers by product type, technology tier, end-user concentration, and application stage within the care continuum. CAGRs were derived from segmented growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated molecular pathologist staffing ratios, integrated delivery network consolidation trajectories, and evolving payer coverage policies for liquid biopsy applications.
Decision-makers should treat outputs as directional under stable FDA regulatory frameworks and continued hospital laboratory consolidation; material deviation in reimbursement landscape timing would warrant model refresh. Recalibration cycles align with material shifts in companion diagnostic guideline expansions and liquid biopsy coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Rapid Plasma Reagin Test Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
Fertility Test Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Self-Administered HPV Test Market