
 Tuberculosis (TB) Diagnostics Market | 2026-2036
Tuberculosis (TB) Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Tuberculosis (TB) Diagnostics Market Analytics
Leasing and instrument-rental programs for molecular diagnostic platforms is narrowing the capital barrier for mid-sized laboratories in high-burden countries. Danaher (Cepheid) leverages its GeneXpert installed base to sustain recurring cartridge revenue across Africa and South Asia. bioMérieux SA anchors European reference laboratory demand with specialized mycobacterial culture systems. F. Hoffmann-La Roche Ltd. competes through integrated workflow automation that reduces manual sample handling.
Tuberculosis diagnostics encompasses laboratory and point-of-care methods for detecting Mycobacterium tuberculosis complex through nucleic acid amplification, antigen detection, or culture-based isolation, with GeneXpert MTB/RIF delivering results within two hours from unprocessed sputum. Molecular diagnostics leads installed capacity due to WHO endorsement and standardized performance, while serology occupies a restricted role following policy withdrawal. Drug resistance testing represents the fastest-growing application segment as rifampicin and multidrug-resistant strains expand. Diagnostic laboratories capture the dominant end-user volume, though clinics represent an emerging channel for decentralized screening.
WHO prequalification and the International Standards for TB Care govern product eligibility in donor-funded procurement, while FDA and EMA pathways shape commercial access in developed markets. National regulators in India and South Africa enforce local licensing requirements that delay market entry for unproven platforms. Stakeholders must monitor evolving WHO policy guidance on novel assays and prequalification timelines to align R&D investment with procurement eligibility.
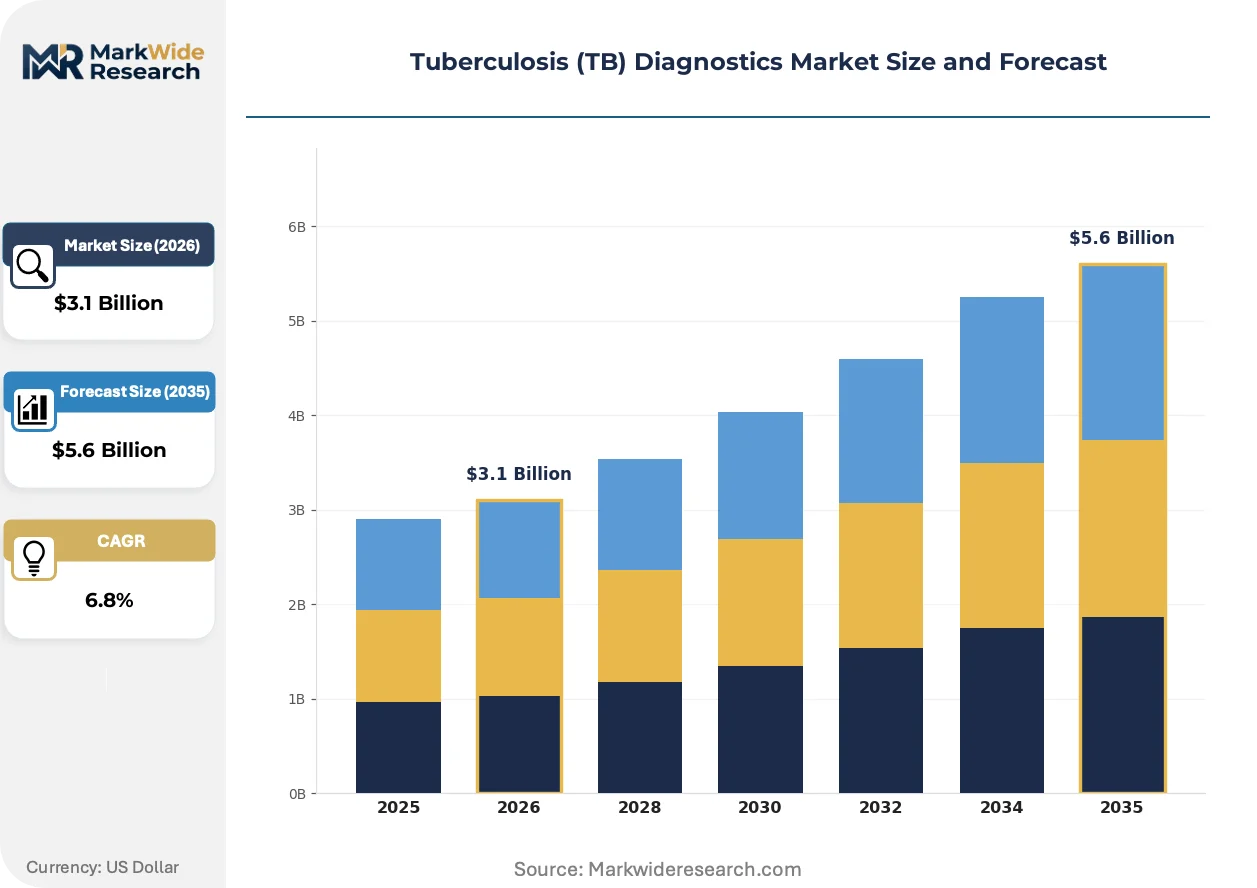
Market Dynamics
Instrument-rental programs for molecular platforms are compressing capital barriers for mid-sized laboratories across high-burden countries, redirecting procurement from outright purchase toward operational expenditure models that favor cartridge-based recurring revenue.
Growth Catalysts
- WHO Prequalification Pathway:The WHO prequalification program accelerates market access for nucleic acid amplification tests in donor-funded procurement, creating eligibility for Global Fund and PEPFAR tenders across African and South Asian national programs.
- Rifampicin Resistance Expansion:The spreading geographic footprint of multidrug-resistant TB strains pulls demand for second-line drug susceptibility testing into peripheral laboratories previously limited to smear microscopy.
- Decentralized Screening Infrastructure:Point-of-care molecular platforms enable same-day diagnosis at primary health centers in Indonesia and South Africa, bypassing centralized laboratory bottlenecks that delay treatment initiation.
Market Restraints
- Reagent Cold-Chain Dependency:Temperature-sensitive cartridges require uninterrupted refrigeration from manufacturing through last-mile delivery, elevating logistics costs and spoilage risk in tropical climates with unreliable electricity.
- Specialized Technical Labor Scarcity:Molecular platform operation demands trained laboratory technicians capable of troubleshooting nucleic acid extraction failures, a skill concentration limited to urban tertiary facilities in low-income settings.
- Serology Policy Withdrawal:The WHO's 2011 recommendation against antibody-based TB tests eliminated a low-cost diagnostic tier, forcing health systems toward more expensive molecular alternatives without intermediate options.
Strategic Opportunities
- Artificial Intelligence-Assisted Microscopy:Machine learning algorithms applied to sputum smear imaging promise automated bacilli counting without molecular infrastructure, converging digital pathology with legacy screening methods.
- India's Private Laboratory Network:Underpenetrated urban diagnostic chains and corporate health screening programs represent a commercial channel distinct from public procurement, with pricing flexibility unavailable in donor-funded segments.
- Next-Generation Sequencing Integration:Whole-genome sequencing for outbreak investigation and resistance profiling is migrating from research institutes into routine reference laboratory workflows, enabled by declining per-sample costs.
Industry Challenges
- Platform Proprietary Lock-In:Closed cartridge systems tether laboratories to single manufacturers, complicating multi-vendor procurement strategies and limiting price negotiation leverage for ministry of health buyers.
- Sample-Referral Network Fragmentation:Specimen transport from peripheral clinics to centralized testing hubs suffers from weak courier infrastructure, introducing pre-analytical delays that degrade molecular test sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuberculosis (TB) Diagnostics Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RT-PCR, Blood Test, Sputum Test, Culture Test Technology: Molecular Diagnostics, Serology, X-ray, GeneXpert End User: Hospitals, Diagnostic Laboratories, Research Institutes, Clinics Application: Active TB Detection, Latent TB Infection Screening, Drug Resistance Testing, Epidemiological Studies |
| Companies Covered | F. Hoffmann-La Roche Ltd., QIAGEN, Abbott Laboratories, Becton Dickinson & Co, Thermo Fisher Scientific Inc., Danaher (Cepheid), Hologic Inc., bioMérieux SA, Oxford Immunotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuberculosis (TB) Diagnostics Market Evolving Landscape
Digital health integration and assay miniaturization are compressing the physical and temporal distance between specimen collection and result delivery, reconfiguring where diagnostic value is captured in the patient pathway.
Ultra-portable nucleic acid amplification devices are collapsing the infrastructure requirements for molecular TB diagnosis. These battery-operated platforms process sputum through automated sample preparation, eliminating dependence on continuous electricity and pipetting skill. District hospitals in Uganda and Bangladesh are adopting these systems for same-day rifampicin resistance detection. The technology is collapsing the traditional tiered laboratory hierarchy that concentrated molecular capacity at national reference centers.
The European Union's In Vitro Diagnostic Regulation (IVDR) is tightening clinical evidence requirements for TB assays seeking CE marking, mandating expanded analytical and clinical validation studies beyond previous Directive 98/79/EC standards. Manufacturers must now demonstrate traceable performance across diverse epidemiological settings, elevating regulatory compliance costs. High-complexity mycobacterial culture systems face the steepest documentation burden, delaying market entry for novel automated platforms.
Health ministries are unbundling instrument placement from reagent procurement, separating capital decisions from consumable supply through rental and leasing arrangements. This financing innovation transfers equipment risk to vendors while locking laboratories into multi-year cartridge commitments. The model is displacing traditional tender-based bulk purchasing in South Africa's provincial laboratory services and Kenya's national referral network.
Tuberculosis (TB) Diagnostics Market Segmentation
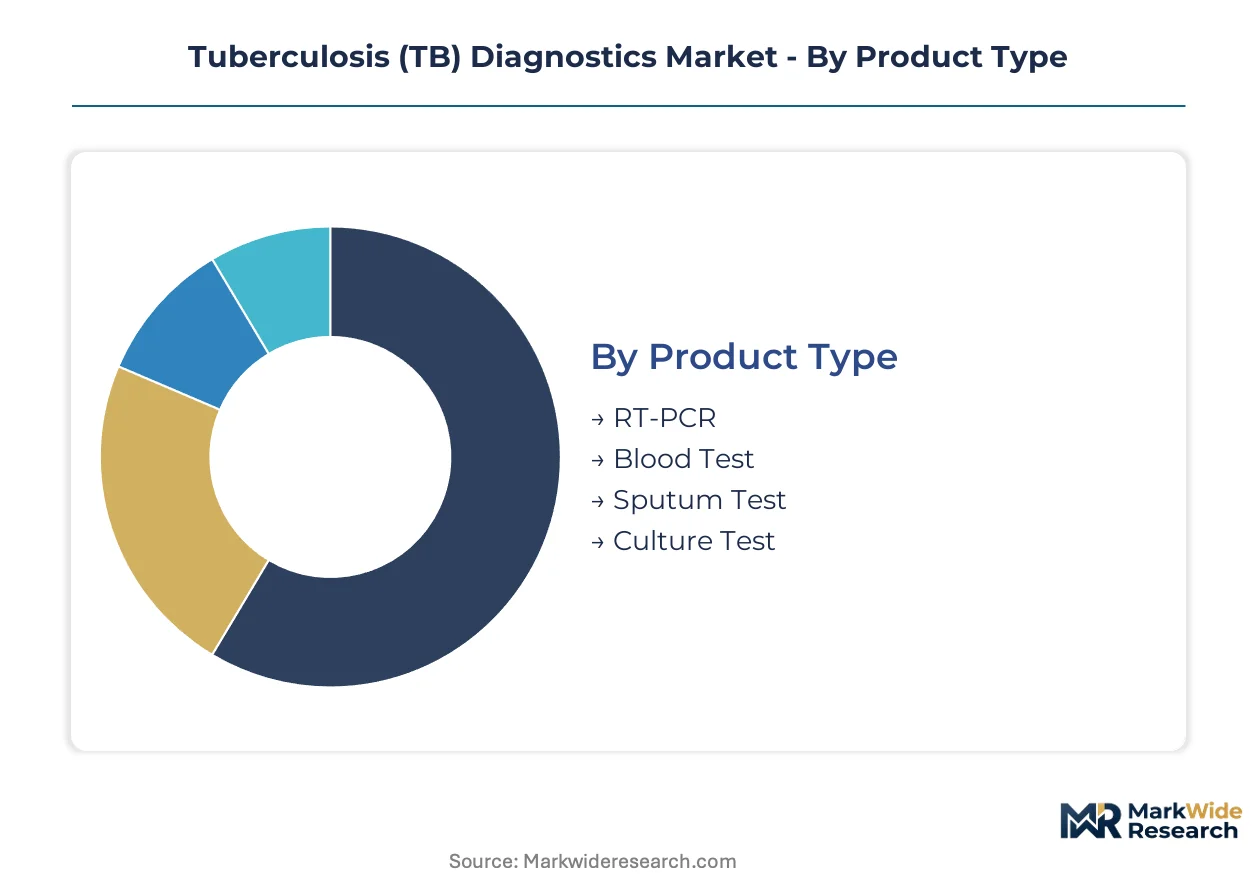
TB diagnostics segmentation reveals distinct procurement patterns across public health systems, private laboratory chains, and research institutions. Each category carries specific technical requirements, reimbursement pathways, and regulatory constraints that shape vendor positioning and pricing power.
Product Type:
Mature reference methods anchor hospital procurement while emerging rapid platforms reshape peripheral laboratory adoption.
- RT-PCR:Nucleic acid amplification platforms detect Mycobacterium tuberculosis complex DNA with high analytical sensitivity, typically processing sputum specimens within 2-4 hours. Demand concentrates in India's national reference laboratories and South Africa's NHLS network, driven by WHO prequalification requirements for donor-funded procurement.
- Sputum Test:Direct microscopy of acid-fast bacilli remains the most widely deployed screening method, requiring minimal infrastructure and delivering same-day results. Peripheral clinics in Indonesia and Bangladesh rely on this tier for initial case detection, constrained by variable technician proficiency and lower sensitivity in HIV-coinfected patients.
- Culture Test:Solid and liquid mycobacterial culture systems provide definitive diagnosis and drug susceptibility profiling.
- Blood Test:Interferon-gamma release assays and serological methods serve latent infection screening in occupational health settings.
RT-PCR retains volume leadership in high-burden countries; Sputum Test holds the steepest expansion curve in decentralized screening programs.
Technology:
Cost tier stratification separates capital-intensive molecular platforms from imaging and legacy immunological methods.
- Molecular Diagnostics:Automated nucleic acid amplification systems integrate sample preparation, amplification, and detection in closed cartridges. India's CDSCO and South Africa's SAHPRA enforce local validation requirements that delay market entry, favoring established platforms with existing regulatory dossiers.
- GeneXpert:Cepheid's cartridge-based platform delivers rifampicin resistance detection from unprocessed sputum within 90 minutes. Uganda's national TB program and Kenya's Ministry of Health have adopted this system through instrument-rental arrangements that convert capital expenditure to operational budgets.
- X-ray:Chest radiography supports triage and screening in high-volume settings where molecular capacity is limited.
- Serology:Antibody-based detection methods occupy a restricted role following WHO policy withdrawal.
GeneXpert captures dominant installed base in African and South Asian procurement; Molecular Diagnostics is gaining share fastest in reference laboratory automation.
End User:
Customer type determines reimbursement pathway, with public tenders, private insurance, and research grants creating divergent pricing environments.
- Diagnostic Laboratories:High-throughput facilities process centralized testing for national TB programs and private health networks. India's Lal PathLabs and South Africa's Ampath operate multi-site networks requiring standardized workflows and electronic result reporting to health ministries.
- Hospitals:Tertiary medical centers manage multidrug-resistant TB cases requiring comprehensive drug susceptibility testing.
- Clinics:Primary health centers in Indonesia's JKN program and South Africa's PHC system deploy point-of-care molecular platforms.
- Research Institutes:Academic and government research centers conduct epidemiological surveillance and assay validation studies.
Diagnostic Laboratories retain volume leadership in absolute test throughput; Clinics are expanding most quickly in point-of-care deployment.
Application:
Application segmentation follows the patient care cascade from screening through treatment monitoring, with each stage carrying distinct technical and regulatory requirements.
- Drug Resistance Testing:Second-line drug susceptibility testing for rifampicin, isoniazid, and fluoroquinolone resistance guides therapeutic selection in MDR-TB cases. India's National TB Elimination Programme and South Africa's KwaZulu-Natal provincial laboratories have expanded molecular resistance testing to district hospital level.
- Active TB Detection:Symptom-based screening and diagnostic confirmation in presumptive TB cases represents the largest application volume.
- Latent TB Infection Screening:Interferon-gamma release assays and tuberculin skin testing target high-risk populations including healthcare workers and immunocompromised patients.
- Epidemiological Studies:Population-level surveillance and outbreak investigation support public health policy formulation.
Active TB Detection retains volume leadership in absolute test numbers; Drug Resistance Testing commands the steepest expansion trajectory as MDR-TB surveillance scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TB diagnostics trade flows reflect divergent procurement models across high-burden and donor-funded markets. India and South Africa import molecular platforms while exporting reference laboratory expertise to neighboring countries. European manufacturers supply cartridge-based systems through instrument-rental arrangements that convert capital expenditure into recurring operational budgets.
India
The National TB Elimination Programme drives demand for GeneXpert and Truenat platforms across district hospitals and medical colleges. CDSCO enforces local validation requirements for novel assays, delaying market entry for unproven molecular systems. Mumbai's public hospital network and Bengaluru's private diagnostic chains anchor installed capacity for drug susceptibility testing.
South Africa
The National Health Laboratory Service operates Africa's largest centralized molecular TB testing infrastructure, processing samples from neighboring Botswana and Namibia. SAHPRA maintains stringent prequalification standards aligned with WHO guidelines. KwaZulu-Natal's provincial laboratories have decentralized rifampicin resistance testing to 47 district sites.
Indonesia
Jaminan Kesehatan Nasional reimbursement expansion pulls molecular diagnostics into primary health centers across Java and Sumatra. The national pharmaceutical regulator requires local clinical trials for platform registration, extending time-to-market for new entrants. Jakarta's referral hospitals and Surabaya's provincial laboratories concentrate advanced culture and sequencing capacity.
Uganda
Global Fund and PEPFAR procurement channels dominate platform placement through ministry of health tenders. The country's national drug authority coordinates with WHO prequalification to accelerate assay approval. Kampala's Makerere University teaching hospitals and regional referral centers in Mbarara and Gulu anchor the specimen transport network.
Bangladesh
BRAC's community health workers extend screening reach into rural areas where laboratory infrastructure remains sparse. The Directorate General of Drug Administration harmonizes registration with WHO policy guidance. Dhaka's infectious disease hospitals and Chittagong's port city medical complexes house the national reference laboratory capacity.
Tuberculosis (TB) Diagnostics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying reagents and consumables to closed cartridge ecosystems. The market structure concentrates around three to five multinational conglomerates with prequalified molecular platforms, while regional distributors and service providers occupy fragmented downstream positions. Two strategic archetypes dominate: integrated diagnostics conglomerates with installed-base leverage, and specialized mycobacterial culture system manufacturers serving reference laboratories. Competitive moves center on instrument-rental financing innovations and multi-year cartridge supply contracts that lock ministries of health into exclusive procurement relationships.
Within the integrated platform tier, Danaher (Cepheid) and F. Hoffmann-La Roche Ltd. exemplify divergent approaches to molecular workflow automation. Cepheid's GeneXpert installed base across African and South Asian national programs represents the archetype of cartridge-driven recurring revenue. Roche occupies a position emphasizing laboratory automation and integrated sample-to-result workflows. bioMérieux SA anchors the specialized culture system segment, serving European reference laboratories and research institutes with mycobacterial identification platforms. These three entities collectively represent the competitive spectrum from point-of-care decentralization to high-complexity centralized diagnostics.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| QIAGEN |
| Abbott Laboratories |
| Becton Dickinson & Co |
| Thermo Fisher Scientific Inc. |
| Danaher (Cepheid) |
| Hologic Inc. |
| bioMérieux SA |
| Oxford Immunotec |
| Others |
Value Network & Pricing Analysis
Dubai-to-Mumbai air freight corridors carry temperature-sensitive molecular cartridges at premium rates, concentrating supply-side leverage among three multinational manufacturers while forcing price stratification between cold-chain-dependent premium platforms and ambient-stable legacy methods. Ministries of health in high-burden countries absorb elevated logistics costs through instrument-rental arrangements that embed freight premiums into per-test pricing.
Pricing Analysis
Public procurement buyers anchor a contract-based long-term offtake structure, with WHO prequalification tier and cold-chain reliability grade serving as the primary price differentiation drivers. Cost compression in peripheral clinic tiers is intensifying because donor-funded programs negotiate cartridge volume commitments that squeeze manufacturer margins. National reference laboratories exhibit the least price sensitivity due to consolidated purchasing power, while district hospitals in Indonesia and Bangladesh face acute budget constraints.
Supply Chain Analysis
Polymerase feedstocks and specialized plastic cartridge resins draw from Germany, Singapore, and the United States, with nucleic acid extraction reagents resting on enzymatic precursor supply from Swiss and Danish fermentation facilities. Single-source vulnerability concentrates in Cepheid's proprietary cartridge molding operations. Distribution runs through national laboratory service hubs in South Africa and India's state medical college networks, with last-mile delivery to primary health centers handled by regional cold-chain logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation across decentralized screening tiers creates acquisition opportunities, as Indonesia's JKN reimbursement expansion and South Africa's district laboratory scale-up generate demand niches underserved by centralized molecular vendors.
For Market Incumbents: Entrench installed-base leverage through multi-year cartridge supply contracts that lock Kenya's Ministry of Health and Uganda's national TB program into exclusive procurement relationships. Deepen backward integration into cold-chain logistics to defend margin position against emerging battery-operated platform competitors. Prioritize CDSCO and SAHPRA certification maintenance to delay market entry for novel assay developers. For New Entrants and Emerging Players: Build out AI-assisted microscopy capabilities for India's private diagnostic chains, where pricing flexibility exceeds donor-funded segments. Target Bangladesh's BRAC community health worker network with ultra-portable nucleic acid devices that bypass cold-chain infrastructure requirements. Pursue hospital system partnerships in Mumbai and Bengaluru as the primary go-to-market angle. For Investors and Strategic Acquirers: EU IVDR implementation reshapes the acquisition landscape by elevating compliance costs for CE-marked assay developers. Five-to-ten year viability favors specialized mycobacterial culture system manufacturers with established European reference laboratory relationships. Signal to watch: WHO prequalification timeline acceleration for novel resistance profiling platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Instrument-Rental Program Expansion | Converts capital expenditure to operational budgets for Kenya's national referral network. |
| AI-Assisted Microscopy Development | Automates bacilli counting without molecular infrastructure in Bangladesh peripheral clinics. |
| EU IVDR Compliance Investment | Mandates expanded clinical validation for bioMérieux culture systems seeking CE marking. |
| Next-Generation Sequencing Integration | Migrates outbreak investigation from research institutes into South Africa's NHLS workflows. |
| Private Laboratory Network Partnership | Captures pricing flexibility in India's Lal PathLabs and Ampath corporate screening programs. |
Research Methodology
Operator-level perspectives from laboratory directors at India's National TB Elimination Programme, South Africa's NHLS procurement managers, and WHO prequalification officers anchored the qualitative base. Secondary validation drew from Global Fund tender documents, CDSCO registration filings, PEPFAR procurement databases, and WHO policy guidance releases. Bottom-up test volume modeling triangulated against top-down expenditure flows from national health accounts.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific milestones. Segmentation dimensions included product type, technology platform, end-user tier, and application stage within the patient care cascade. CAGRs derived from instrument placement trajectories, cartridge consumption curves, and assay menu expansion timelines. Resistance surveillance scale-up in KwaZulu-Natal and India's district hospital decentralization served as volume anchors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-operated platform developers or AI-microscopy specialists would shift outcomes. Regulatory delays at SAHPRA or CDSCO, cold-chain infrastructure failures, or WHO policy reversals on serology alternatives could revise trajectory. Cross-checking against Global Fund disbursement schedules and national health budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fertility Testing Devices Market
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
In Vitro Diagnostic (IVD) Reagent Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Fungal Antigens Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
LDL Test Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
Veterinary Diagnostic Services Market