
 Human Immunodeficiency Virus Rapid Test Kit Market | 2026-2036
Human Immunodeficiency Virus Rapid Test Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Human Immunodeficiency Virus Rapid Test Kit Market Insights
Procurement of HIV rapid test kits is broadening from traditional hospital laboratory networks toward community-based organizations and at-home users. Abbott leverages extensive distribution infrastructure across endemic regions to sustain volume leadership in high-burden markets. OraSure Technologies anchors the oral-fluid self-testing segment with differentiated sample-collection technology that reduces healthcare worker dependence. Bio-Rad Laboratories competes through specialized quality-control and confirmatory testing systems that integrate with rapid screening workflows.
HIV rapid test kits are point-of-care diagnostic devices that detect viral antigens, antibodies, or nucleic acids within minutes using immunochromatographic strips or lateral-flow cassettes, typically requiring capillary blood, oral fluid, or serum samples without laboratory equipment. These devices serve commercial and public-health purposes by enabling same-result clinical decisions, epidemiological surveillance, and decentralized screening in resource-limited settings. Antibody tests occupy the mature volume base of the market, while combo tests that simultaneously detect HIV-1/2 antibodies and p24 antigen represent the fastest-expanding segment due to earlier infection detection and reduced window-period false negatives. Lateral-flow technology dominates manufacturing scale and unit economics, though PCR-based nucleic acid platforms command premium positioning in confirmatory and early-infant-diagnosis applications where sensitivity thresholds are non-negotiable.
FDA Emergency Use Authorization and WHO prequalification frameworks govern market access for novel HIV rapid diagnostics, with CE marking under the EU In Vitro Diagnostic Regulation creating additional compliance layers for European distribution. The EPA and OSHA regulate waste-stream management and healthcare worker safety protocols associated with test-kit disposal and bloodborne-pathogen exposure. Stakeholders must monitor evolving prequalification criteria and decentralized procurement shifts to align manufacturing capacity with changing demand patterns.
Market Dynamics
Decentralization of HIV testing infrastructure is compressing procurement timelines and fragmenting buyer concentration across community health programs, home-based screening initiatives, and mobile clinic networks. WHO prequalification pathways and FDA Emergency Use Authorization frameworks are accelerating product commercialization while reshaping competitive entry barriers.
Growth Catalysts
- WHO Prequalification Program:Streamlined assessment pathways for HIV rapid diagnostics enable faster market entry in sub-Saharan African countries with expanding national testing campaigns.
- Oral-fluid self-testing technology:Sample-collection methods that eliminate healthcare worker dependence unlock home-based screening demand and reduce facility infrastructure requirements.
- Community health worker deployment:Task-shifting policies in Kenya, South Africa, and Nigeria extend testing reach into rural populations previously excluded from centralized laboratory networks.
Market Restraints
- Reagent supply concentration:Specialized immunochromatographic membrane production clusters in East Asian manufacturing hubs create input vulnerability for lateral-flow cassette assembly.
- Confirmatory testing infrastructure gaps:Limited nucleic acid testing capacity in resource-limited settings generates diagnostic delay and undermines rapid test utility.
- Window-period sensitivity limitations:Antibody-only detection formats miss acute infection phases, necessitating parallel p24 antigen or nucleic acid platforms with higher unit costs.
Strategic Opportunities
- Dual HIV-syphilis combo test expansion:Integrated detection platforms address co-infection screening needs in antenatal care programs across high-burden African markets.
- Digital result reporting integration:Bluetooth-connected readers and smartphone-based result capture enable real-time surveillance data transmission to national health information systems.
- Pharmacy channel penetration:Over-the-counter distribution through retail pharmacy networks in South Africa and Kenya bypasses traditional clinic-based access barriers.
Industry Challenges
- Quality assurance workforce scarcity:Trained personnel for lot-release testing and in-country verification are concentrated in national reference laboratories with limited surge capacity.
- Cold chain fragmentation:Temperature-sensitive reagent stability requirements conflict with last-mile distribution networks lacking controlled storage infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Immunodeficiency Virus Rapid Test Kit Market |
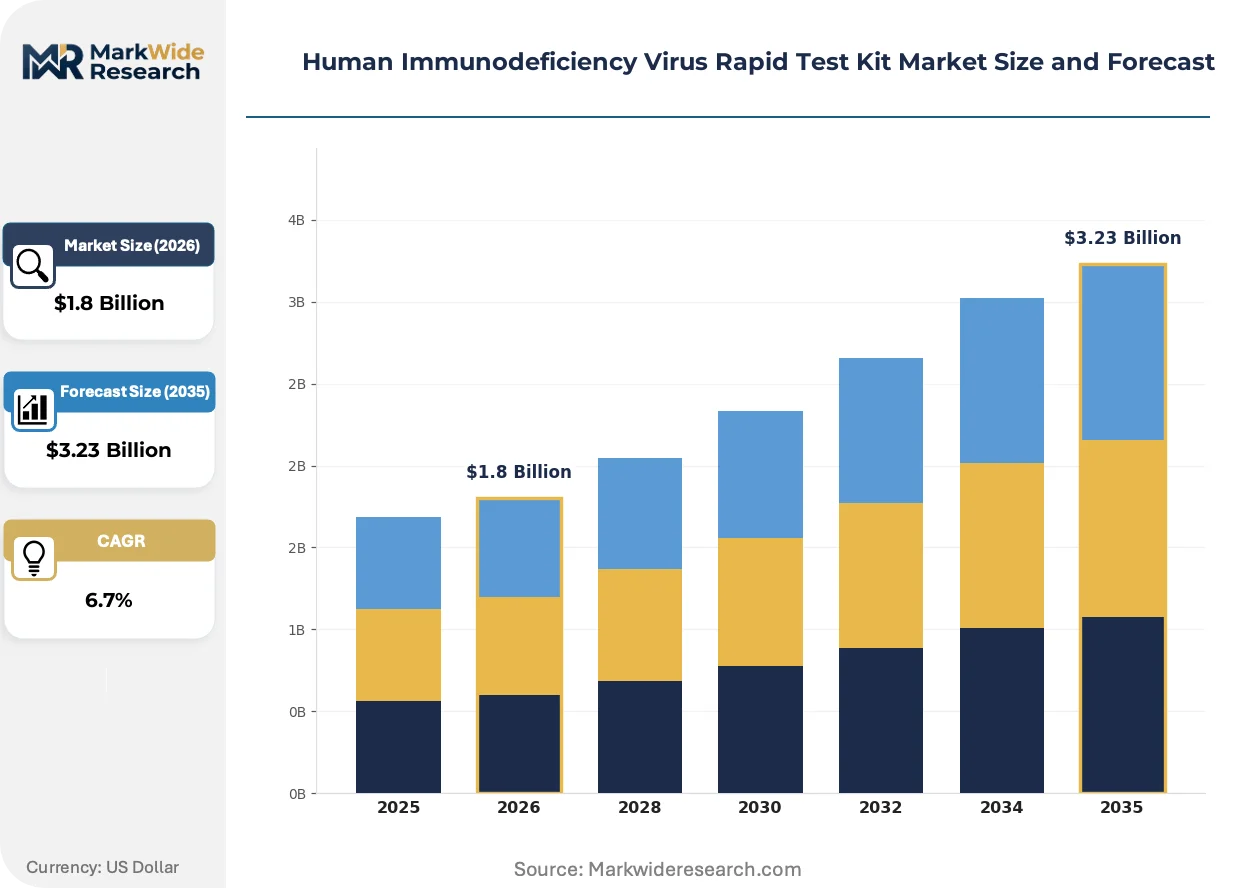
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antigen Tests, Antibody Tests, Nucleic Acid Tests, Combo Tests Technology: Immunochromatography, Lateral Flow, ELISA, PCR End User: Hospitals, Clinics, Laboratories, Home Care Distribution Channel: Online Sales, Pharmacies, Direct Sales, Wholesalers |
| Companies Covered | Abbott, OraSure Technologies, Bio-Rad Laboratories, Chembio Diagnostics, bioMérieux, Siemens Healthineers, Becton, Dickinson and Company, Atomo Diagnostics, bioLytical Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Immunodeficiency Virus Rapid Test Kit Market Trends and Innovations
Diagnostic platform convergence with digital health infrastructure is reconfiguring how HIV rapid test results flow into treatment cascades and epidemiological surveillance systems. Three developments are restructuring competitive positioning.
Nucleic acid amplification technology is expanding into point-of-care formats previously dominated by immunochromatographic methods. Early-infant-diagnosis programs and acute infection screening in South African and Kenyan referral networks are adopting cartridge-based PCR platforms. This shift compresses the confirmatory testing timeline from centralized laboratory turnaround to same-visit result delivery.
CE marking under the EU In Vitro Diagnostic Regulation imposes strengthened clinical evidence and post-market surveillance obligations on manufacturers seeking European distribution. The MDR transition forces restructuring of technical documentation and quality management systems. Mid-tier diagnostic firms are responding by concentrating resources on WHO prequalification pathways for African and Asian markets where volume concentration outweighs European premium positioning.
Self-testing kit procurement through e-commerce channels and direct-to-consumer platforms is displacing traditional clinic-based distribution in urban South African and Nigerian markets. Pharmacy retailers and telehealth providers are capturing margin previously allocated to public health supply chains. This channel rotation is most visible in metropolitan districts where smartphone penetration and delivery logistics infrastructure enable discreet product access.
Human Immunodeficiency Virus Rapid Test Kit Market Segmentation
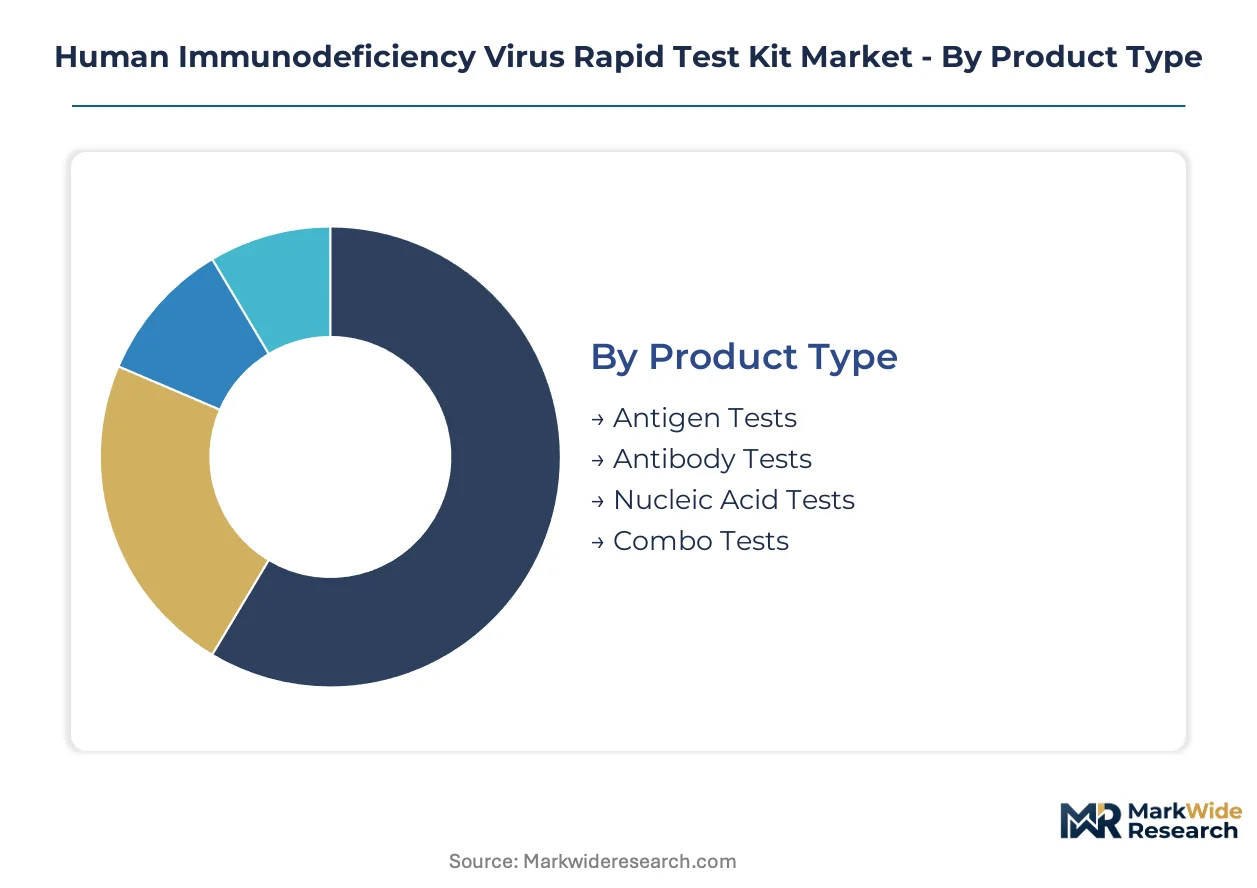
Product architecture in HIV rapid diagnostics determines regulatory pathway complexity, manufacturing scale economics, and procurement channel access. Segment boundaries shift as point-of-care platforms absorb laboratory functions and self-testing protocols reshape end-user definitions.
Product Type:
Procurement priorities diverge between public health programs optimizing for cost-per-test and clinical settings demanding diagnostic certainty.
- Antigen Tests:p24 capsid protein detection compresses the serological window period to 14-21 days post-exposure. Kenyan and South African antenatal screening programs prioritize these for acute infection capture in high-turnover testing environments.
- Antibody Tests:Mature immunochromatographic platforms detecting HIV-1/2 antibodies dominate volume procurement through WHO prequalified supplier lists. Uganda and Nigeria distribute these through community health worker networks where cold chain infrastructure remains limited.
- Nucleic Acid Tests:Cartridge-based RNA amplification for early infant diagnosis commands premium positioning in South African referral networks.
- Combo Tests:Simultaneous antibody and p24 antigen detection platforms represent the fastest-growing trajectory as national programs consolidate testing algorithms.
Volume sits with Antibody Tests; growth tilts toward Combo Tests.
Technology:
Manufacturing concentration and sensitivity thresholds shape competitive moats across platform generations.
- Immunochromatography:Colloidal gold and enzyme-labeled antibody visualization on nitrocellulose membranes enables ambient-temperature stability. This platform anchors donor screening in Indian blood bank networks where equipment minimization drives protocol design.
- Lateral Flow:Capillary-driven fluid transport through porous matrices delivers sub-20-minute turnaround without power requirements. Sub-Saharan African ministries of health specify these for rural clinic deployment where electricity access is intermittent.
- ELISA:Enzyme-linked immunosorbent assays retain centralized laboratory positioning for high-throughput screening in Brazilian public health reference centers.
- PCR:Polymerase chain reaction platforms are gaining share fastest in point-of-care formats as cartridge miniaturization reduces thermal cycling complexity.
Unit economics favor Lateral Flow; margin expansion concentrates in PCR.
End User:
Facility infrastructure requirements and result confidentiality needs segment buyer behavior sharply.
- Hospitals:Integrated laboratory networks in Thailand and Vietnam deploy rapid tests for emergency department triage and surgical screening protocols where same-shift result delivery is mandatory.
- Clinics:Primary care facilities in Mozambique and Zambia conduct the majority of national testing volume through task-shifted nurse cadres using oral-fluid platforms.
- Laboratories:National reference centers in Ghana and Cameroon maintain confirmatory capacity with nucleic acid platforms.
- Home Care:Self-testing procurement through South African pharmacy retail and Nigerian e-commerce channels is expanding most quickly as discreet access preferences reshape distribution.
Testing volume concentrates in Clinics; channel innovation centers on Home Care.
Distribution Channel:
Regulatory authorization scope and buyer procurement sophistication determine channel viability.
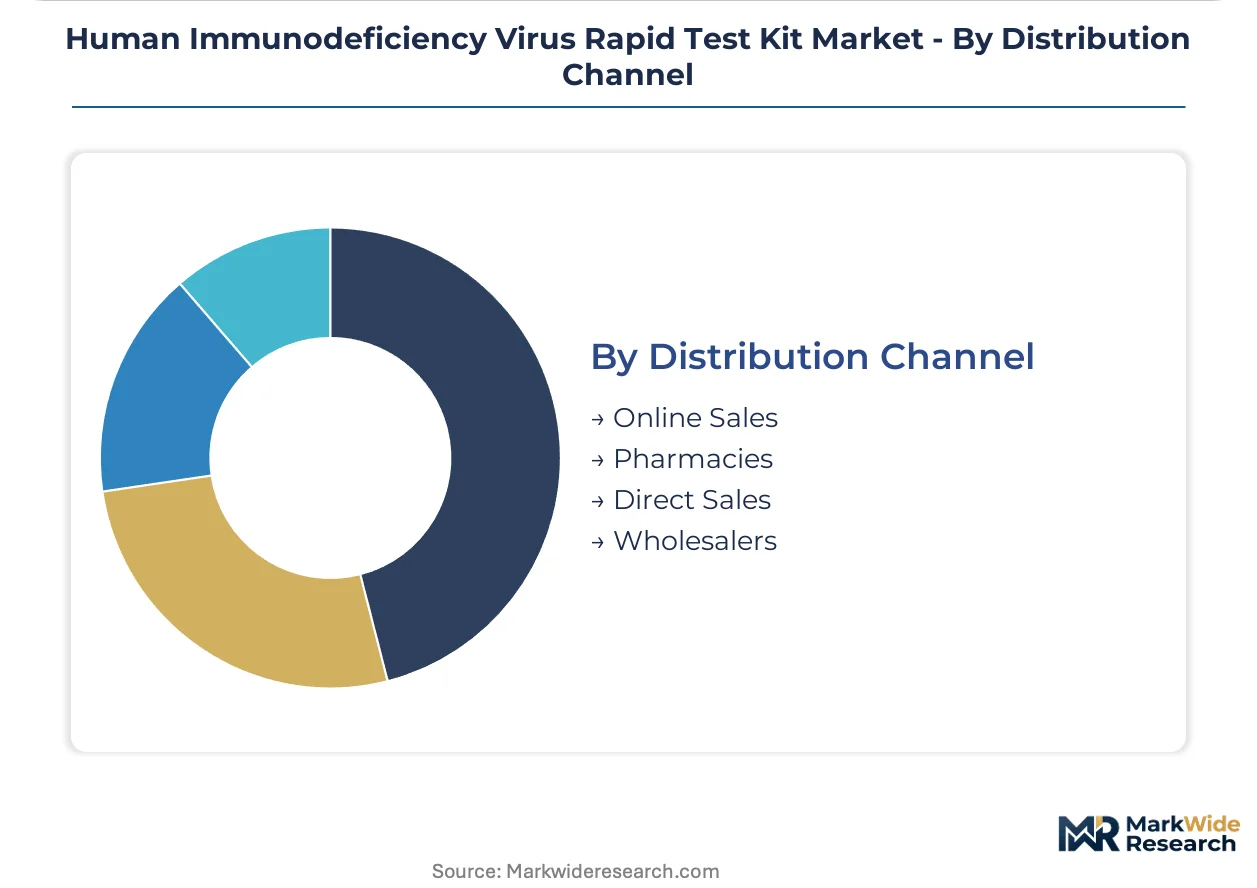
- Online Sales:Direct-to-consumer platforms in urban South Africa and Kenya bypass clinic stigma barriers for self-testing kit delivery.
- Pharmacies:Over-the-counter availability through Clicks and Dis-Chem networks in South Africa enables same-day access without appointment infrastructure.
- Direct Sales:Manufacturer relationships with national AIDS control programs in Ethiopia and Tanzania secure multi-year tender volumes through centralized procurement.
- Wholesalers:Medical supply distributors across West Africa aggregate fragmented clinic demand into order sizes that justify import logistics.
Public volume flows through Direct Sales; retail expansion is accelerating fastest in Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for HIV rapid test kits concentrates in sub-Saharan African countries with high prevalence rates and expanding national screening programs. Public health procurement drives volume, while decentralized testing infrastructure reshapes distribution patterns across endemic regions.
South Africa
National testing campaigns and antenatal screening protocols consume substantial kit volumes through public health supply chains. The South African Health Products Regulatory Authority governs market authorization for point-of-care diagnostics. Johannesburg and Cape Town anchor distribution networks serving both clinic-based and pharmacy retail channels.
Kenya
Community health worker deployment extends testing reach into rural populations previously excluded from laboratory networks. Kenya's Pharmacy and Poisons Board regulates importation and quality standards for rapid diagnostic devices. Nairobi concentrates procurement coordination for Ministry of Health tenders and NGO supply programs.
Nigeria
E-commerce and direct-to-consumer platforms are displacing traditional clinic-based distribution in Lagos and Abuja metropolitan areas. The National Agency for Food and Drug Administration and Control oversees product registration and post-market surveillance. Pharmacy retail networks in southwestern states enable over-the-counter access without appointment infrastructure.
Uganda
Community health worker networks distribute antibody-only platforms where cold chain infrastructure remains limited. The National Drug Authority manages prequalification alignment with WHO standards for donor-funded procurement. Kampala serves as the logistics hub for last-mile distribution to peripheral health centers.
United States
FDA Emergency Use Authorization pathways accelerate commercialization timelines for novel diagnostic platforms targeting home-based screening segments. The CDC and HRSA coordinate procurement for safety-net clinics and Ryan White program beneficiaries. California and New York metropolitan areas concentrate telehealth-integrated self-testing demand through pharmacy and online channels.
Human Immunodeficiency Virus Rapid Test Kit Market Competitive Landscape
United States-based multinationals anchor one tier through established regulatory relationships and distribution infrastructure; European and Australian specialists hold differentiated positions in oral-fluid and quality-control segments. Market structure tilts toward consolidation among prequalified suppliers with WHO-approved manufacturing sites, though mid-tier regional assemblers compete on price in tender-driven African markets. Three archetypes dominate: vertically integrated diagnostics conglomerates with blood-banking heritage, oral-fluid technology specialists with consumer-health positioning, and nucleic acid platform innovators targeting early-infant-diagnosis workflows. Competitive moves center on WHO prequalification pursuit for African market access and digital connectivity integration for surveillance data capture.
Among United States-based manufacturers, Abbott and OraSure Technologies exemplify contrasting strategic positions within the point-of-care tier. Abbott represents the scale-driven archetype with extensive distribution infrastructure across endemic regions, while OraSure Technologies occupies the consumer-access segment through differentiated sample-collection technology. Bio-Rad Laboratories, also United States-based, anchors the quality-control and confirmatory testing tier with specialized systems that integrate with rapid screening workflows. These three companies collectively illustrate how regulatory authorization breadth, sample-technology differentiation, and laboratory-integration capability define competitive positioning in this market.
| Leading Market Players |
|---|
| Abbott |
| OraSure Technologies |
| Bio-Rad Laboratories |
| Chembio Diagnostics |
| bioMérieux |
| Siemens Healthineers |
| Becton, Dickinson and Company |
| Atomo Diagnostics |
| bioLytical Laboratories |
| Others |
Pricing and Supply Chain Analysis
Specialized quality-assurance technicians concentrated in East Asian manufacturing hubs command wage premiums that compress margin spreads between economy-grade antibody strips and premium nucleic acid cartridges. Labor-cost differentials between automated membrane production lines in China and manual assembly operations in Southeast Asian contract facilities directly determine pricing-tier spreads across WHO-prequalified and non-prequalified supplier categories.
Pricing Analysis
Volume concentrates in antibody-only lateral-flow strips procured through national tender programs, while margin expansion centers on combo tests and PCR-based platforms for early-infant-diagnosis applications. Three-tier pricing structure across premium, standard, and economy levels reflects WHO prequalification status, cold-chain stability specifications, and bundled training support. Pricing pressure stems from donor-funded procurement consolidation in sub-Saharan African markets where Ministries of Health consolidate supplier lists. Public health programs exhibit extreme price sensitivity, while private pharmacy retail channels in South Africa and Nigeria tolerate modest premiums for discreet packaging and digital result integration.
Supply Chain Analysis
Domestic-content mandates in India and Brazil are reshaping sourcing patterns for nitrocellulose membrane substrates and colloidal gold conjugates, forcing manufacturers to qualify secondary suppliers outside traditional East Asian clusters. Immunochromatographic membrane production concentrates in China, South Korea, and Japan, while lateral-flow cassette assembly draws from Vietnam, Malaysia, and Mexico facilities. Raw material dependencies span specialized porous polymers, enzyme-labeled antibodies, and desiccant packaging systems. Single-source vulnerability in p24 antigen reagent supply creates disruption risk for combo test manufacturers. Distribution runs through WHO-prequalified procurement hubs in Geneva and Amsterdam, with last-mile fragmentation across African national medical stores and NGO logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where WHO prequalification investment creates a barrier-to-entry moat that protects incumbent margin structures against price-competitive regional assemblers.
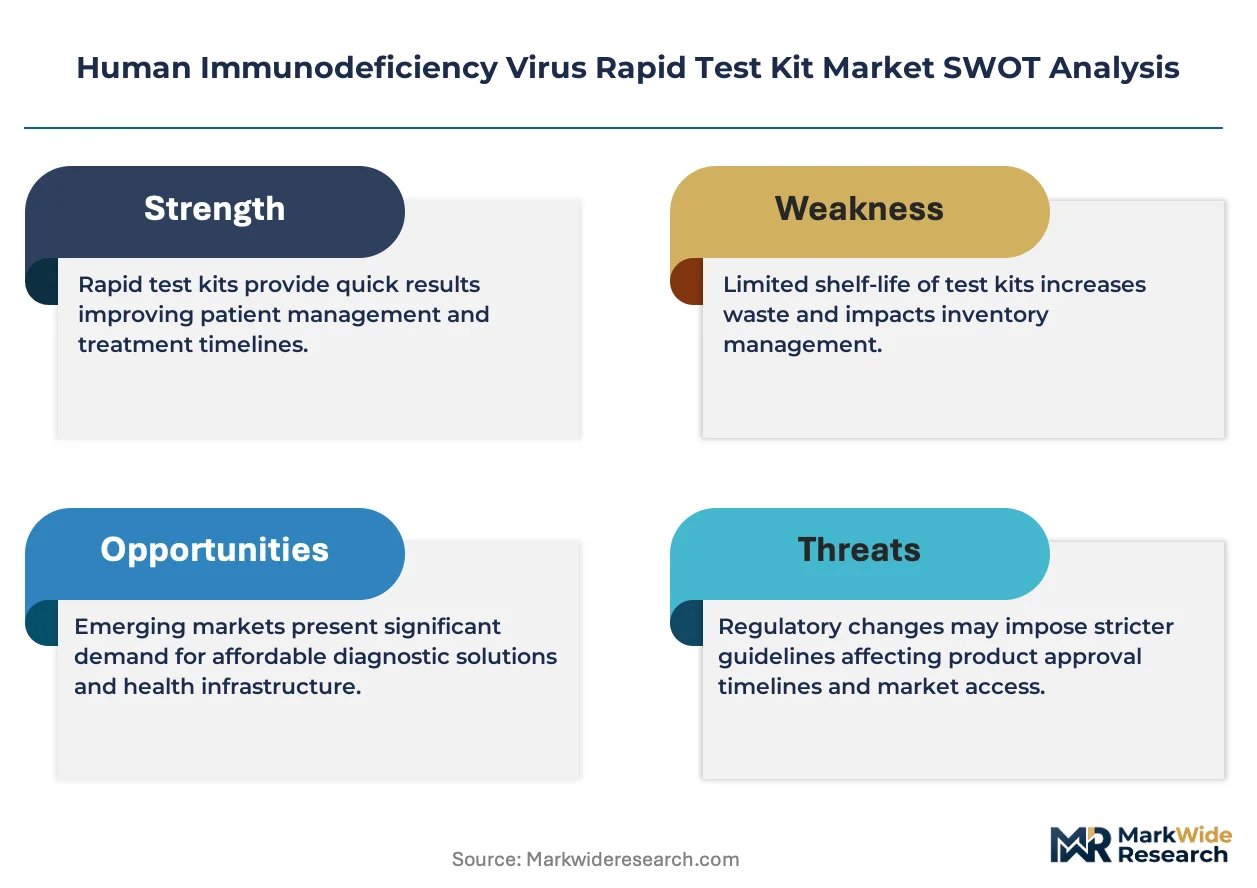
For Market Incumbents: Anticipate margin compression from cartridge-based PCR platforms displacing immunochromatographic methods in South African and Kenyan referral networks. Defensive consolidation through backward integration into nitrocellulose membrane production reduces input vulnerability from East Asian supply concentration. Channel control investments in digital result-reporting infrastructure lock in Ministry of Health surveillance contracts against oral-fluid self-testing entrants. For New Entrants and Emerging Players: Pharmacy retail chains in Nigeria and South Africa represent the most penetrable channel for oral-fluid self-testing kits bypassing clinic stigma barriers. White-space targets include e-commerce direct-to-consumer distribution in Lagos and Abuja metropolitan areas, and dual HIV-syphilis combo test development for antenatal care programs in Uganda and Tanzania. Go-to-market execution should anchor on telehealth provider partnerships for result linkage to care. For Investors and Strategic Acquirers: The window for entry favors nucleic acid platform innovators with cartridge miniaturization capabilities and WHO prequalification track records. Long-term viability hinges on diagnostic convergence with national health information systems and early-infant-diagnosis workflow integration. Watch for inflection signals in FDA Emergency Use Authorization timelines for novel sample-collection technologies that reduce healthcare worker dependence.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks multi-year tender access in Ethiopian and Tanzanian national AIDS control programs. |
| Digital Connectivity Integration | Bluetooth-connected readers enable real-time surveillance data transmission to Kenyan health information systems. |
| Dual HIV-Syphilis Combo Development | Integrated detection platforms address co-infection screening needs in Ugandan antenatal care workflows. |
| Pharmacy Channel Penetration | Over-the-counter distribution through Clicks and Dis-Chem networks bypasses clinic access barriers. |
| Cold Chain Infrastructure Investment | Temperature-stable reagent formulations extend reach into Ugandan community health worker networks. |
Research Methodology
WHO prequalification databases, FDA Emergency Use Authorization filings, and national procurement tender records formed the secondary backbone of this analysis. Primary interviews with diagnostic manufacturing executives, Ministry of Health procurement officers, and NGO supply chain managers were cross-referenced against GPO contract databases and hospital procurement systems. Bottom-up unit demand estimates from 15 endemic countries were triangulated with top-down manufacturer shipment data.
Historical trendline analysis of testing volume expansion across Kenyan community health worker programs and South African pharmacy retail channels established baseline growth parameters. Segmentation modeling incorporated product type, technology platform, end-user facility tier, and distribution channel sophistication across the projection horizon. CAGRs were derived from epidemiological surveillance data, national testing campaign targets, and diagnostic algorithm shifts toward combo and nucleic acid platforms.
Caveats apply where regulatory prequalification delays, donor funding volatility, or cold chain infrastructure gaps could materially shift the outlook. Forecasts reflect assumptions about WHO policy continuity and national program decentralization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Fertility Test Market
Diagnostics
United Kingdom in-Vitro Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Rapid Plasma Reagin Test Market
Diagnostics
Sweden in-Vitro Diagnostics Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market