
 Antigen Skin Test Market | 2026-2036
Antigen Skin Test Market Size, Share, and Industry Trends Forecast 2026-2036
Antigen Skin Test Market Analysis
ISO 13485 certification is unwinding competitive access for manufacturers lacking established quality management systems. Becton, Dickinson and Company leverages its integrated diagnostics portfolio to sustain hospital contracts across multiple continents. Thermo Fisher Scientific anchors its position through captive supply of reagents and instrumentation for laboratory-developed tests. Abbott Laboratories differentiates via point-of-care connectivity features that streamline clinic workflows.
An antigen skin test introduces purified allergen extracts or pathogen-derived antigens into the epidermis or dermis to elicit localized immune responses, with wheal diameter or erythema intensity measured at 15–20 minutes serving as the primary functional readout. Intradermal tests command premium positioning in allergy diagnosis due to superior sensitivity for drug and venom hypersensitivity, while lateral flow assay technology captures expanding volume in resource-limited settings where laboratory infrastructure remains scarce. Hospitals dominate end-user demand through bundled procurement of allergen panels and associated immunotherapy protocols.
The FDA regulates antigen skin tests as Class II medical devices requiring 510(k) premarket notification, while the European Medical Device Regulation imposes stricter clinical evidence requirements for post-market surveillance. These frameworks elevate barriers for new entrants and reward incumbents with established regulatory dossiers. Stakeholders must monitor evolving equivalence standards for microneedle-based delivery platforms as agencies reassess biocompatibility expectations for novel intradermal technologies.
Market Dynamics
Hospital consolidation across the United States is compressing vendor counts and centralizing assay platform procurement, forcing manufacturers to defend contract renewals through integrated reagent-instrument bundles rather than standalone test sales.
Growth Catalysts
- MDR Clinical Evidence Requirements:The European Medical Device Regulation mandates enhanced post-market surveillance, rewarding incumbent manufacturers with established dossiers and accelerating replacement cycles for legacy systems in Germany and France.
- Point-of-Care Connectivity:Cloud-enabled result reporting and EMR integration streamline clinic workflows, driving preference for platforms that eliminate manual transcription in high-volume allergy practices.
- India Diagnostic Laboratory Expansion:Private laboratory chains in Mumbai and Delhi are adding allergen panels to capture rising affluent demand for precision immunotherapy protocols.
Market Restraints
- Purified Allergen Extract Volatility:Biologic raw material sourcing concentrates among European suppliers, exposing manufacturers to batch-to-batch potency variation and cold chain cost escalation.
- 510(k) Equivalence Standards:FDA premarket notification requirements for novel microneedle delivery platforms create protracted review timelines that delay commercialization by 18-24 months relative to conventional intradermal devices.
- Lateral Flow Substitution:Capillary blood-based serological assays eliminate skin prick discomfort and reduce technician training requirements in pediatric and geriatric populations.
Strategic Opportunities
- Brazil ANVISA Harmonization:Regulatory alignment with FDA 510(k) pathways reduces redundant clinical trials for manufacturers seeking access to Latin America's largest diagnostic market.
- Microneedle Array Convergence:Solid-state microprojection technology combined with stabilized dry allergen coatings eliminates cold chain dependency and enables pharmacy-based administration.
- Direct-to-Consumer Distribution:Telehealth-integrated home testing kits bypass traditional clinic channels, capturing allergy-susceptible populations in suburban and rural geographies.
Industry Challenges
- ISO 13485 Certification Timeline:Quality management system implementation demands 12-18 month lead times, excluding emerging manufacturers from hospital tender processes.
- Legacy LIS Integration Complexity:Hospital information system interoperability requirements force redundant software development for each major EMR platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antigen Skin Test Market |
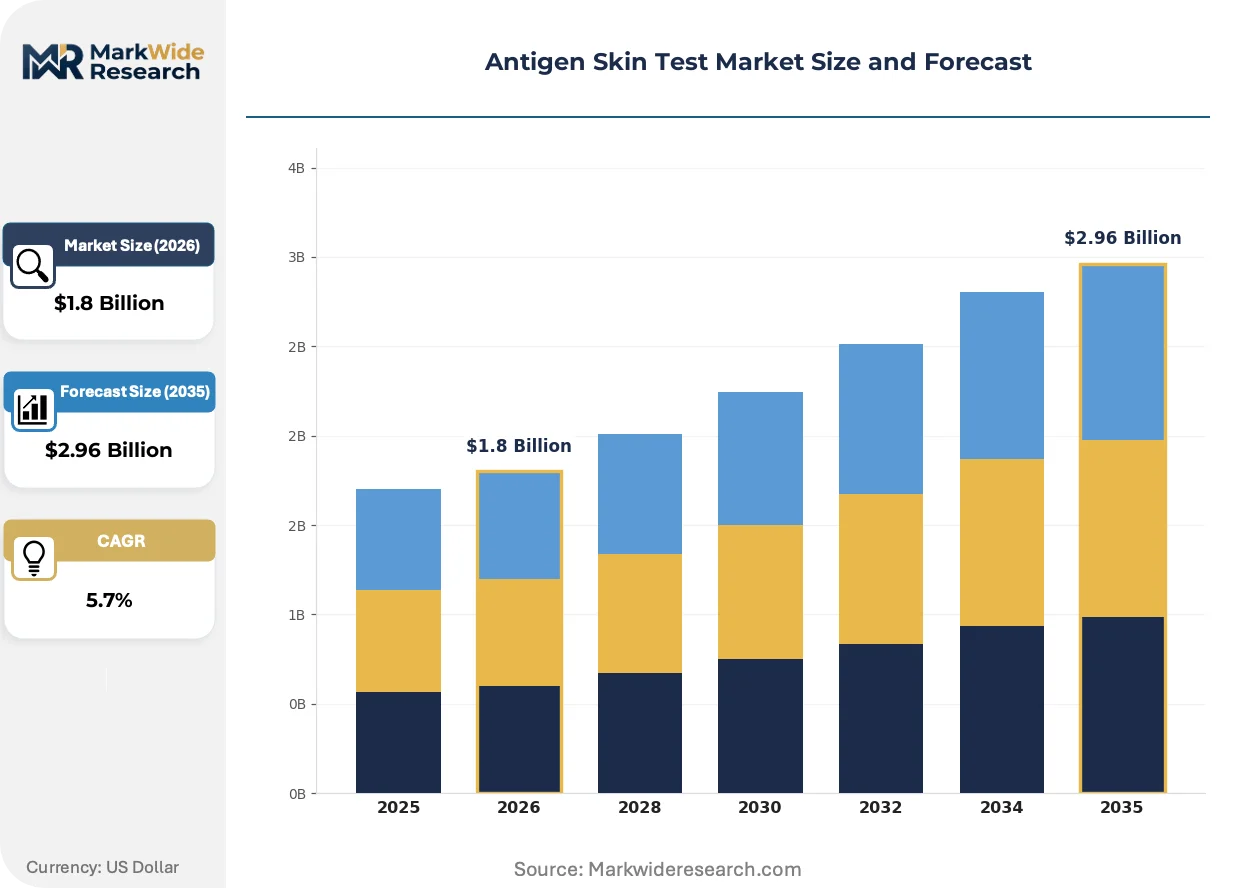
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intradermal Test, Patch Test, Scratch Test, Microneedle Test Technology: ELISA, Immunofluorescence, Lateral Flow Assay, Radioallergosorbent Test End User: Hospitals, Diagnostic Laboratories, Research Institutions, Private Clinics Application: Allergy Diagnosis, Immunology Research, Infectious Disease Detection, Vaccine Development |
| Companies Covered | Abbott Laboratories, Becton, Dickinson and Company, Thermo Fisher Scientific, Inc., Stallergenes Greer, ALK-Abelló, QIAGEN N.V., Siemens Healthineers, DiaSorin S.p.A., BioMérieux SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antigen Skin Test Market Emerging Trajectories
Antigen skin test technology is fragmenting into two distinct performance tiers, with premium intradermal systems defending hospital laboratory share against simplified point-of-care formats penetrating retail and pharmacy channels.
Microneedle array technology is bifurcating test administration between clinical and non-clinical settings. Solid-state microprojections deliver allergen to dermal dendritic cells with reduced variability versus liquid intradermal injection. Pharmacy chains and occupational health clinics are adopting disposable microneedle patches to eliminate technician training requirements. This format is compressing reimbursement differentiation between specialist-administered and self-administered testing protocols.
MDR Article 10 clinical evidence requirements are elevating post-market surveillance burdens for Class IIa devices. Manufacturers must now maintain proactive safety monitoring systems equivalent to pharmaceutical pharmacovigilance. German notified bodies are demanding real-world performance data from German and Austrian clinical sites. Incumbents with established European quality infrastructures are absorbing compliance costs while smaller competitors withdraw from CE marking pursuits.
Allergist procurement patterns are consolidating around bundled reagent-instrument contracts that lock in multi-year exclusive supply agreements. Independent allergy practices and small clinic chains are losing negotiating leverage as hospital-owned ambulatory networks centralize purchasing decisions. This concentration is most visible in the United States, where integrated delivery networks in Texas and Florida have eliminated standalone vendor relationships in favor of sole-source diagnostics partnerships.
Antigen Skin Test Market Segmentation
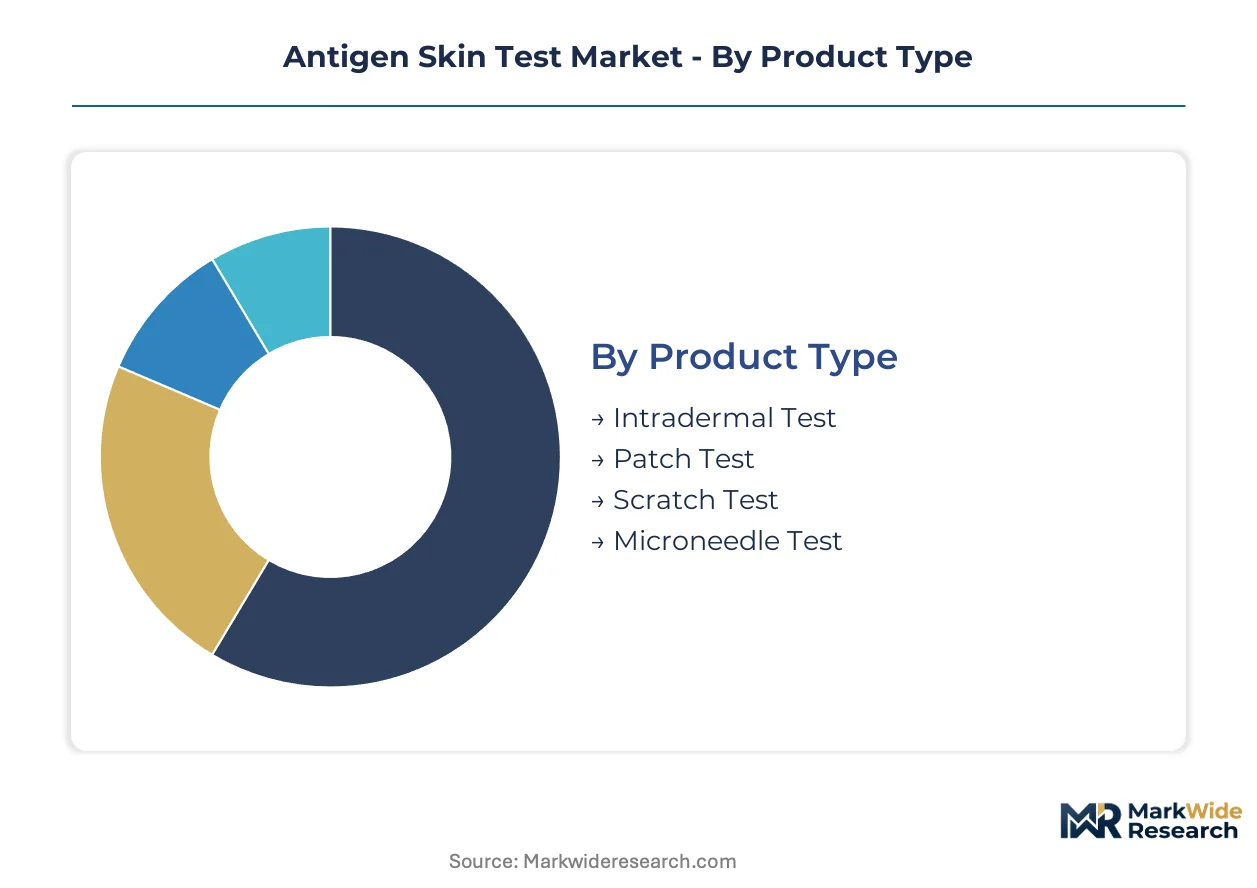
Antigen skin test segmentation reveals how clinical workflow requirements and regulatory pathways fragment purchasing decisions across healthcare settings. Manufacturers must align product portfolios with distinct performance tiers rather than pursuing universal platform strategies.
Product Type:
Margins concentrate in intradermal formats where sensitivity specifications command premium pricing in hospital laboratories, while simplified formats compete on volume throughput in decentralized settings.
- Intradermal Test:Liquid allergen injection into the dermis produces measurable wheal-and-flare responses with superior sensitivity for drug and venom hypersensitivity. United States hospital laboratories dominate procurement through bundled reagent-instrument contracts that lock in multi-year exclusive supply agreements for high-complexity allergy panels.
- Microneedle Test:Solid-state microprojection arrays deliver stabilized dry allergen coatings to dermal dendritic cells with reduced administration variability. Pharmacy chains in suburban United States geographies are adopting disposable patches to eliminate cold chain dependency and technician training requirements.
- Patch Test:Occlusive allergen application for delayed hypersensitivity assessment, primarily utilized in dermatology clinics for contact allergy screening.
- Scratch Test:Epidermal abrasion technique with lower sensitivity, concentrated in pediatric settings where patient compliance limits invasive procedures.
The dominant share belongs to Intradermal Test, while Microneedle Test is closing the gap fastest.
Technology:
Technology selection tracks laboratory infrastructure maturity, with automated platforms defending share in consolidated health systems and simplified formats penetrating resource-limited environments.
- Lateral Flow Assay:Capillary-driven immunochromatographic strips eliminate equipment requirements and reduce technician training burdens. Diagnostic laboratories in India are adding lateral flow allergen panels to capture rising affluent demand for precision immunotherapy protocols in Mumbai and Delhi.
- ELISA:Enzyme-linked immunosorbent assay delivers quantitative IgE measurements with established standardization protocols. Hospital consolidation across the United States compresses vendor counts and centralizes assay platform procurement around ELISA workstations with integrated reagent supply.
- Immunofluorescence:Fluorophore-labeled antibody detection for research-grade specificity, concentrated in academic medical centers with dedicated microscopy infrastructure.
- Radioallergosorbent Test:Radiolabeled IgE quantification method with declining utilization due to waste disposal requirements and regulatory complexity.
ELISA maintains installed base leadership, though Lateral Flow Assay is expanding most quickly in emerging market laboratory chains.
End User:
Customer concentration patterns diverge sharply between consolidated purchasing in health systems and fragmented procurement in independent practice settings.
- Hospitals:Integrated delivery networks in Texas and Florida have eliminated standalone vendor relationships in favor of sole-source diagnostics partnerships bundling allergen panels with immunotherapy protocols.
- Diagnostic Laboratories:Private chains are expanding test menus for allergic conditions, with ISO 13485 certification requirements excluding emerging manufacturers from tender processes.
- Private Clinics:Independent allergy practices are losing negotiating leverage as hospital-owned ambulatory networks centralize purchasing decisions.
- Research Institutions:Academic centers drive protocol development for novel allergen extracts, though volume remains limited compared to clinical diagnostics.
Hospitals capture the largest volume share, while Diagnostic Laboratories are gaining share fastest through menu expansion strategies.
Application:
Application demand correlates with reimbursement stability and protocol standardization, with established indications defending share against emerging therapeutic areas.
- Allergy Diagnosis:Standardized allergen panels for IgE-mediated hypersensitivity represent the foundational use case. Cloud-enabled result reporting and EMR integration streamline clinic workflows in high-volume United States allergy practices.
- Infectious Disease Detection:Tuberculosis and fungal antigen skin tests maintain public health utility despite serological substitution trends. Lateral flow assays are eliminating skin prick discomfort in pediatric and geriatric populations where technician training requirements constrain traditional methods.
- Immunology Research:Mechanistic studies of cellular immune responses support therapeutic development pipelines.
- Vaccine Development:Adjuvant and formulation testing for dermal delivery routes, concentrated in contract research organizations.
Allergy Diagnosis holds the dominant position, though Infectious Disease Detection is climbing the fastest through point-of-care format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) premarket notification pathways and MDR Article 10 clinical evidence mandates are reshaping qualification timelines across major diagnostic markets. Hospital consolidation and laboratory chain expansion are concentrating procurement decisions in integrated health networks.
United States
Integrated delivery networks in Texas and Florida have eliminated standalone vendor relationships in favor of sole-source diagnostics partnerships. The FDA's evolving in vitro diagnostic regulations compress review timelines for established 510(k) predicates while delaying novel microneedle platforms. Allergen panel procurement concentrates in hospital-owned ambulatory networks across the Southeast and Southwest.
Germany
German notified bodies under MDR Article 10 are demanding real-world performance data from German and Austrian clinical sites for Class IIa device recertification. The country's quality infrastructure rewards incumbents with established ISO 13485 systems while accelerating replacement cycles for legacy allergy diagnostic platforms in Bavaria and North Rhine-Westphalia.
India
Private laboratory chains in Mumbai and Delhi are expanding allergen panel menus to capture affluent demand for precision immunotherapy protocols. CDSCO medical device regulations are harmonizing with international standards for in vitro diagnostics. Diagnostic infrastructure investment concentrates in Maharashtra and Karnataka where hospital networks centralize purchasing decisions.
Brazil
ANVISA regulatory alignment with FDA 510(k) pathways reduces redundant clinical trials for manufacturers accessing Latin America's largest diagnostic market. Hospital consolidation in São Paulo and Rio de Janeiro drives centralized procurement of validated assay platforms. The country's diagnostic laboratory expansion targets allergy and infectious disease testing capacity.
Japan
PMDA quality management system requirements for in vitro diagnostics elevate barriers for emerging manufacturers lacking established regulatory dossiers. Hospital procurement in the Kanto and Kansai regions favors bundled reagent-instrument contracts with multi-year exclusive supply agreements. Allergy diagnostic demand concentrates in Tokyo and Osaka metropolitan medical centers.
Antigen Skin Test Market Vendor Landscape
Listed leaders compete with private specialists across regulatory qualification capabilities, with publicly traded diagnostics conglomerates leveraging integrated portfolios against focused allergen extract suppliers. The vendor base stratifies into three tiers: multinational conglomerates with captive reagent supply, mid-cap specialists with regional regulatory dossiers, and emerging manufacturers seeking ISO 13485 certification. Consolidation pressures favor archetypes with established FDA and MDR quality infrastructures. Dominant competitive moves include strategic partnerships for microneedle technology licensing and backward integration into stabilized allergen extract production.
Within the multinational conglomerate tier, Thermo Fisher Scientific, Inc. and Becton, Dickinson and Company exemplify scale-driven positioning through integrated diagnostics portfolios. Abbott Laboratories occupies a distinct point-of-care connectivity position. Among European specialists, ALK-Abelló and Stallergenes Greer represent allergen-focused archetypes with established immunotherapy protocol relationships. Siemens Healthineers and QIAGEN N.V. anchor the instrumentation-reagent bundling strategy in hospital laboratory settings.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific, Inc. |
| Stallergenes Greer |
| ALK-Abelló |
| QIAGEN N.V. |
| Siemens Healthineers |
| DiaSorin S.p.A. |
| BioMérieux SA |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates both supplier qualification and price tier placement, compressing margins for uncertified manufacturers while rewarding incumbents with premium positioning in hospital tender processes. Certification status separates reagent-instrument bundles commanding multi-year exclusivity from commodity test sales facing downward pressure.
Pricing Analysis
Certification level creates the primary spread between premium hospital contracts and economy point-of-care formats. Pricing stratifies across FDA-cleared intradermal systems, CE-marked laboratory platforms, and unbundled lateral flow strips. Cost compression in the standard tier intensifies because hospital consolidation centralizes purchasing around sole-source partnerships. Independent clinics exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
European suppliers anchor purified allergen extract production, with Denmark and France hosting established immunotherapy-grade manufacturing. Batch-to-batch potency variation and cold chain requirements tether production to qualified biologic facilities. Single-source vulnerability concentrates in stabilized dry allergen coatings for microneedle arrays. Distribution runs through diagnostic distributors serving hospital networks and direct contracts with laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate serological assay substitution threatening skin test volume in pediatric and geriatric populations, defending clinical utility through sensitivity advantages in drug and venom hypersensitivity.
For Market Incumbents: Shield hospital contract renewals through captive reagent supply and integrated instrument platforms that raise switching costs. Backward integration into stabilized allergen extract production secures raw material consistency against European supplier concentration. Defend against lateral flow substitution by emphasizing intradermal sensitivity specifications in high-stakes diagnostic scenarios.
For New Entrants and Emerging Players: Anchor in pharmacy-based microneedle distribution bypassing ISO 13485 certification timelines that exclude hospital tenders. Target suburban United States geographies where telehealth-integrated home testing kits capture allergy-susceptible populations outside clinic networks. Pursue ANVISA harmonization pathways to access Latin American laboratory expansion with reduced clinical trial burdens.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates divesting non-core allergy diagnostic divisions. Five-to-ten year viability hinges on microneedle platform adoption compressing reimbursement differentiation between clinical and self-administered protocols. Watch FDA equivalence standard evolution for novel delivery technologies as inflection indicator for competitive entry timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 10 compliance unlocks German and French hospital laboratory procurement. |
| Hospital System Partnership | Sole-source diagnostics agreements in Texas and Florida lock in multi-year reagent supply. |
| Software Companion Development | Cloud-enabled EMR integration eliminates manual transcription in high-volume allergy practices. |
| Backward Integration | In-house stabilized allergen production reduces European supplier dependency and cold chain costs. |
| Reimbursement Strategy | Microneedle patch coding alignment defends pharmacy channel margin against clinic-based competitors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with allergy clinic administrators, hospital purchasing committee members, diagnostic laboratory directors, and biomedical engineers at integrated delivery networks. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and GPO contract repositories. Bottom-up test volume modeling and top-down market sizing triangulated across the analysis window.
Across the projection horizon, forecasts segmented by product type, technology platform, end-user concentration, and application indication. CAGRs derived from installed base erosion rates and replacement cycle acceleration in regulated markets. Modeled inputs included allergen panel expansion trajectories, microneedle regulatory pathway timelines, and laboratory chain consolidation patterns.
Material uncertainties — purified extract supply disruptions, MDR equivalence standard revisions, and lateral flow assay reimbursement shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization progress and hospital purchasing centralization. Recalibration cycles align with material shifts in notified body interpretation and integrated delivery network tender outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Sweden in-Vitro Diagnostics Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Rapid Diagnostics Market