
 HIV Diagnostics Market | 2026-2036
HIV Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
HIV Diagnostics Market Analysis
Platform licensing revenue is tilting toward integrated molecular diagnostics systems over discrete immunoassay reagents. F. Hoffmann-La Roche Ltd leverages its automated cobas platforms to anchor high-throughput laboratory workflows across developed markets. Abbott Laboratories competes through its point-of-care Alinity portfolio, while bioMérieux SA specializes in syndromic panel approaches that bundle HIV detection with co-infection screening.
HIV diagnostics encompasses assays, instruments, and consumables designed to detect viral antigens, antibodies, or nucleic acids in human specimens, with sensitivity thresholds typically reaching 20-40 copies per milliliter for quantitative PCR methods. The primary commercial purpose centers on enabling clinical staging, treatment monitoring, and prevention of mother-to-child transmission. Immunoassays still occupy the largest installed base in centralized laboratories, though nucleic acid testing captures the fastest expansion as countries adopt test-and-treat protocols requiring viral load quantification. Self-testing kits are emerging as a margin-accretive segment through retail pharmacy and online retail channels, while laboratory based tests sustain the bulk revenue in blood donation centers and reference labs.
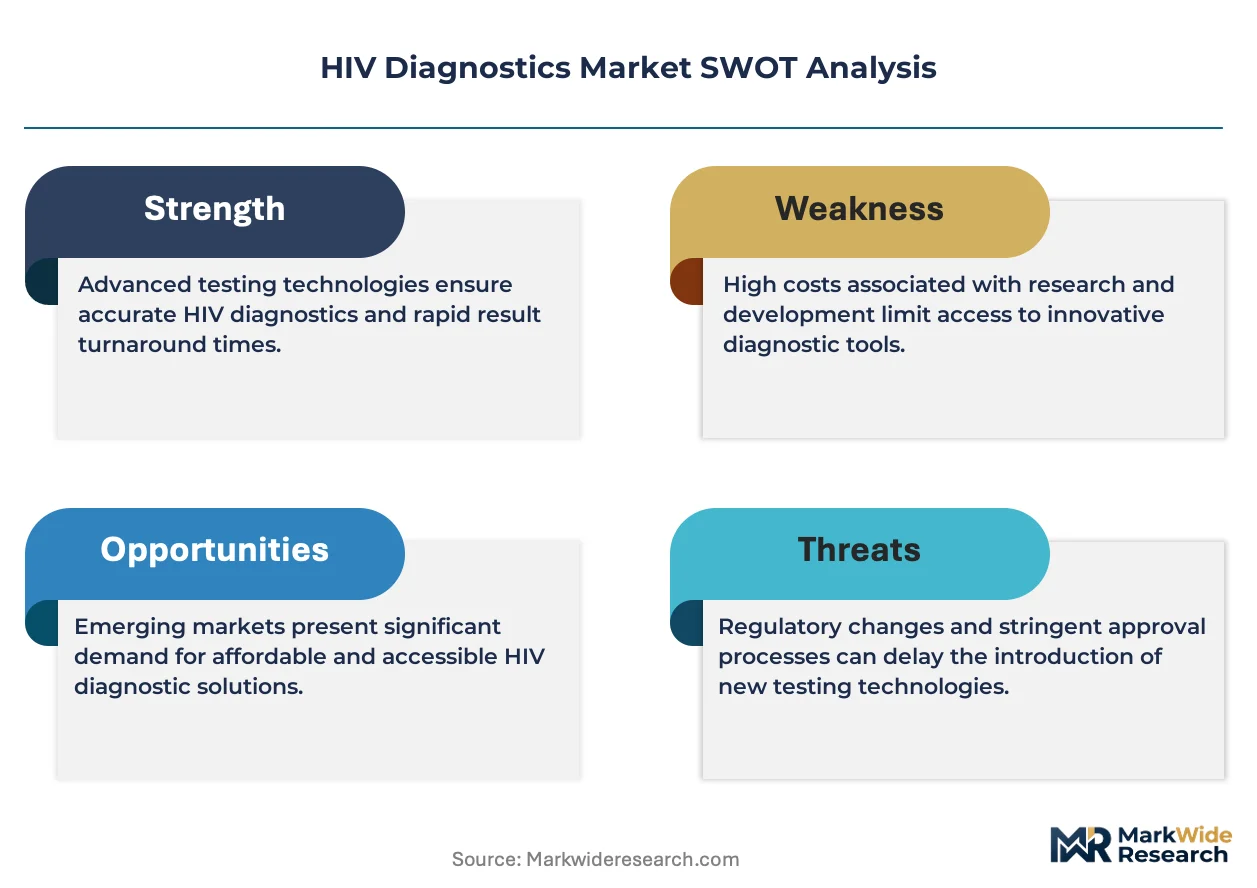
FDA premarket review and WHO prequalification jointly determine which manufacturers access procurement pipelines for low- and middle-income countries, effectively filtering market participants by clinical validation standards. The EU In Vitro Diagnostic Regulation imposes stricter post-market surveillance and performance documentation requirements that favor established players with regulatory infrastructure. Stakeholders must monitor how decentralized testing policies reshape channel economics between direct sales to ministries of health and retail pharmacy distribution.
Market Dynamics
Decentralized testing policies are compressing channel margins and forcing manufacturers to reconfigure distribution networks between ministry procurement and retail pharmacy channels. This structural shift is reshaping how diagnostic platforms reach end-users across high-burden and developed markets alike.
Growth Catalysts
- WHO Prequalification Program:The WHO prequalification pathway accelerates market access for manufacturers targeting donor-funded procurement pools in sub-Saharan Africa. This regulatory mechanism filters participants by clinical validation standards.
- Test-and-Treat Protocols:National HIV programs adopting test-and-treat guidelines require viral load quantification capabilities. Nucleic acid testing platforms capture expanded procurement volumes from ministries of health.
- Point-of-Care Platforms:Community health clinics in Kenya, South Africa, and Malawi deploy portable diagnostic instruments. These decentralized sites accelerate screening coverage beyond centralized laboratory capacity.
Market Restraints
- Reagent Supply Concentration:Polymerase chain reaction consumables depend on specialized enzyme suppliers concentrated in North America and Western Europe. Geographic concentration creates vulnerability to export restrictions.
- EU MDR Compliance Burden:The EU In Vitro Diagnostic Regulation imposes stricter post-market surveillance and performance documentation requirements. Established players with regulatory infrastructure absorb compliance costs more readily than emerging competitors.
- Antigen Test Sensitivity Limitations:Rapid immunoassays detect antibodies during later infection stages. Early acute infection windows require nucleic acid confirmation, limiting standalone diagnostic utility.
Strategic Opportunities
- Self-Testing Retail Channels:Oral-fluid self-test kits penetrate pharmacy and e-commerce distribution in South Africa and Kenya. These channels offer margin accretion beyond institutional procurement.
- Syndromic Panel Integration:Multiplex platforms combining HIV detection with tuberculosis and hepatitis screening address co-infection prevalence. Integrated panels reduce per-test operational costs for reference laboratories.
- Digital Connectivity Mandates:National health information systems in Rwanda and Zambia require test result reporting integration. Manufacturers embedding connectivity modules capture preferred vendor status.
Industry Challenges
- Cold Chain Distribution Complexity:Nucleic acid test reagents require temperature-controlled logistics across tropical climates. Supply chain reconfiguration demands capital investment in regional distribution hubs.
- Multi-Site Quality Harmonization:Decentralized testing networks spanning urban hospitals and rural clinics struggle with inter-laboratory standardization. Proficiency testing programs impose ongoing operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HIV Diagnostics Market |
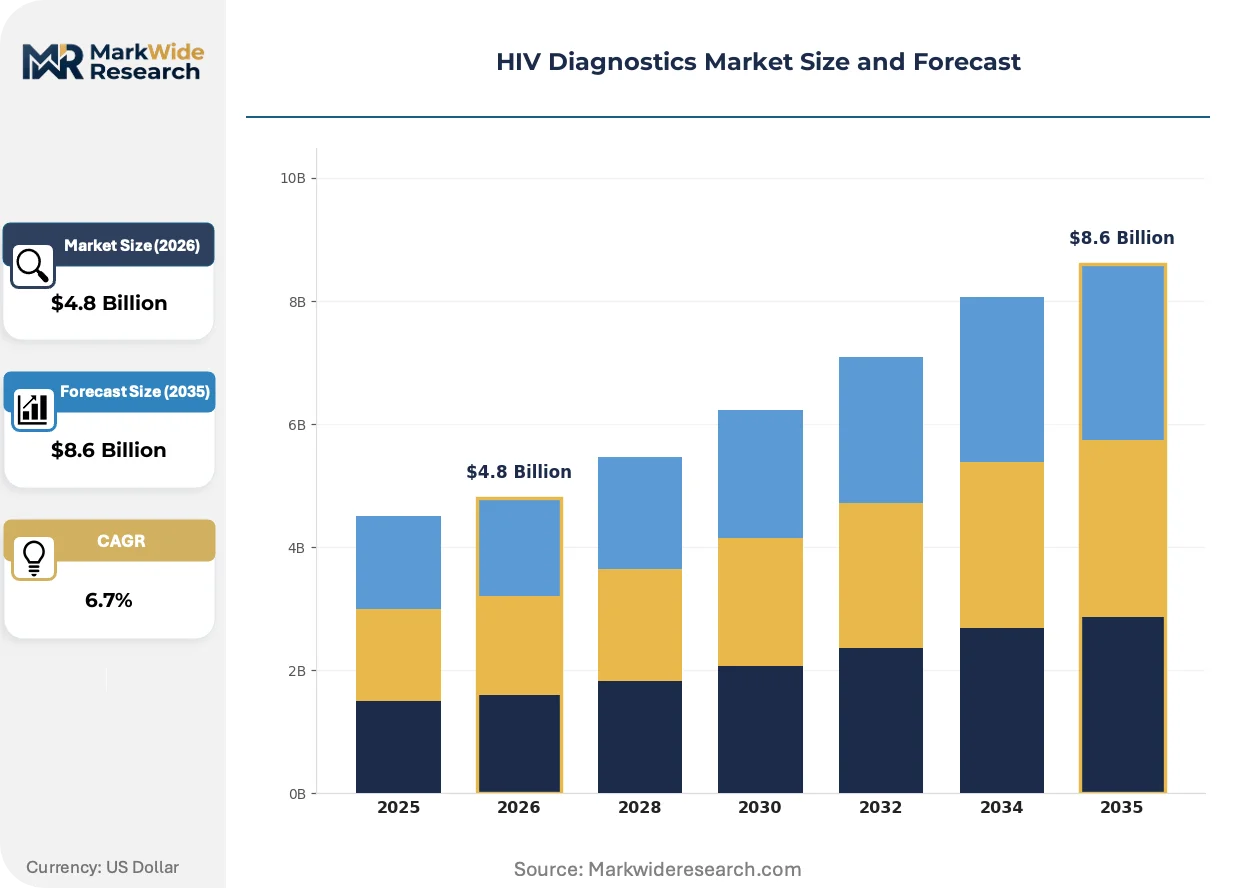
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, Laboratory Based Tests, Self-Testing Kits, PCR Tests Technology: Immunoassays, Nucleic Acid Testing, Microfluidics, Electronic Test Devices End User: Hospitals, Diagnostic Laboratories, Home Care, Blood Donation Centers Distribution Channel: Retail Pharmacies, Online Retail, Direct Sales, Wholesale Distributors |
| Companies Covered | Thermo Fisher Scientific Inc., Becton, Dickinson and Company, Siemens Healthineers, Bio-Rad Laboratories, Inc., bioMérieux SA, F. Hoffmann-La Roche Ltd, Danaher Corporation, QIAGEN, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HIV Diagnostics Market Emerging Trajectories
Diagnostic workflows are converging around connected platforms that integrate sample-to-answer automation with real-time data transmission. This convergence is compressing turnaround times and enabling new service delivery models.
Near-patient molecular diagnostics is digitizing result reporting pathways. Automated cartridge-based systems perform nucleic acid extraction and amplification without laboratory infrastructure. Ministries of health in Uganda and Zimbabwe deploy these platforms in district hospitals. The technology is digitizing the link between testing and treatment initiation by eliminating batch-processing delays.
FDA emergency use authorization pathways for novel assays compress premarket review timelines for manufacturers addressing emerging variants. The accelerated pathway reduces validation documentation requirements for well-characterized platform modifications. Viral load quantification assays benefit most from this flexibility, with manufacturers submitting supplementary data packages rather than complete new submissions.
Community-based screening programs are displacing facility-dependent testing models. Lay health workers in Mozambique and Malawi administer oral-fluid rapid tests during home visits. Retail pharmacy distribution in urban Nigeria captures asymptomatic individuals avoiding clinic stigma. Sub-Saharan Africa exhibits the most pronounced channel fragmentation, with procurement splitting between national programs, donor consortia, and private out-of-pocket purchases.
HIV Diagnostics Market Segmentation
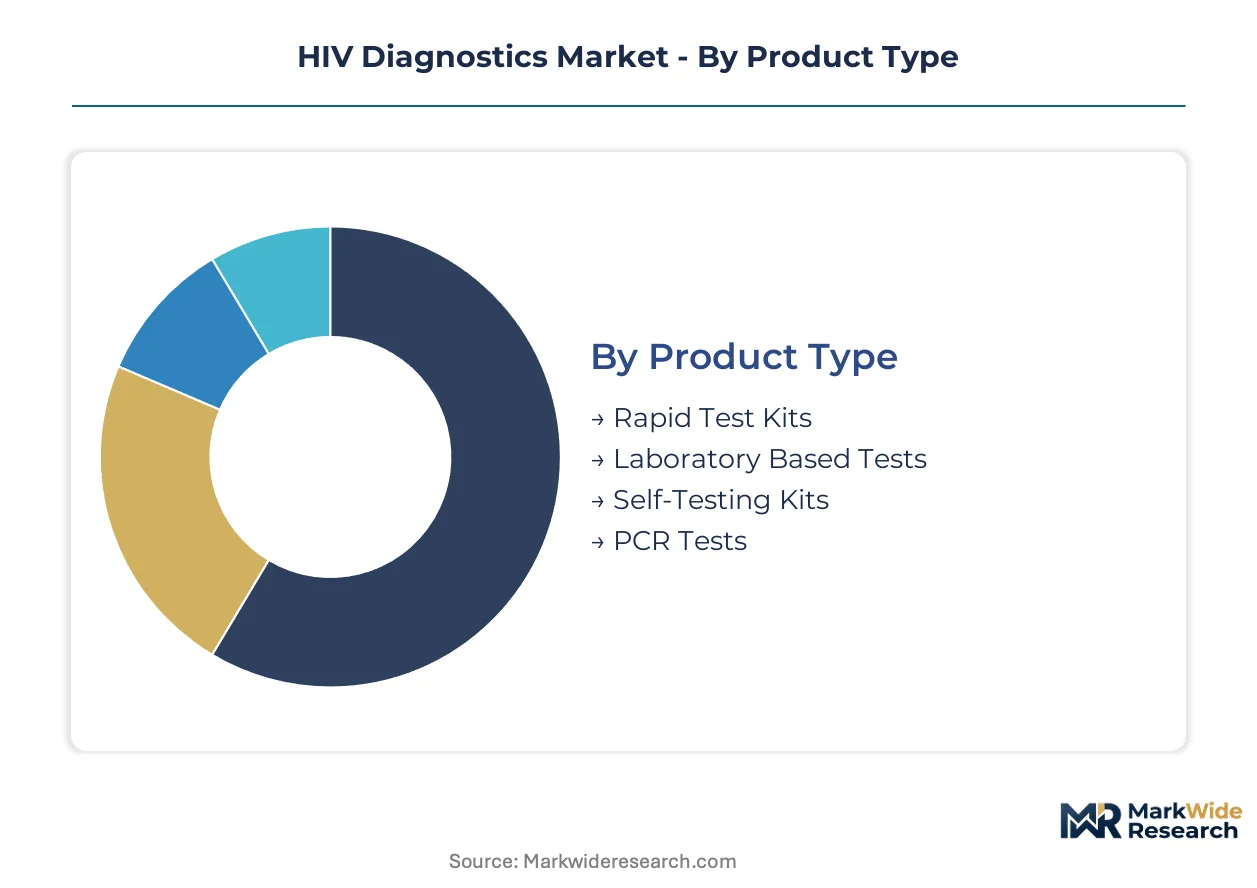
Diagnostic procurement splits sharply between institutional tenders and retail pharmacy channels. Manufacturers must configure platform portfolios across four distinct category axes to capture volume in both centralized laboratories and decentralized community settings.
Product Type:
Mature laboratory formats dominate revenue concentration while emerging formats reshape access models.
- Laboratory Based Tests:High-throughput immunoassay analyzers process serum and plasma specimens in centralized reference facilities. Blood donation centers across Kenya, South Africa, and Malawi deploy these systems for serological screening of donor pools, with procurement flowing through ministry tenders and WHO prequalification pathways.
- PCR Tests:Quantitative nucleic acid platforms detect viral RNA at 20-40 copies per milliliter sensitivity thresholds, enabling viral load monitoring for test-and-treat protocols. District hospitals in Uganda and Zimbabwe adopt cartridge-based systems that eliminate batch-processing delays and digitize result reporting to national health information systems.
- Rapid Test Kits:Lateral flow immunoassays deliver antibody detection in 15-20 minutes without laboratory infrastructure.
- Self-Testing Kits:Oral-fluid devices penetrate retail pharmacy and e-commerce channels in urban Nigeria and South Africa.
Laboratory Based Tests handle the majority of throughput; Self-Testing Kits are expanding most quickly on share.
Technology:
Cost tier stratification separates high-sensitivity molecular methods from affordable rapid screening formats.
- Nucleic Acid Testing:Real-time PCR and isothermal amplification methods target viral RNA with quantitative precision. Ministries of health in Rwanda and Zambia mandate connectivity modules for these platforms to integrate with national surveillance databases, creating preferred vendor criteria for manufacturers embedding digital transmission capabilities.
- Immunoassays:Enzyme-linked and chemiluminescent antibody detection methods retain the largest installed base in developed market reference laboratories. The EU MDR imposes stricter post-market surveillance documentation that favors established players with regulatory infrastructure over emerging competitors.
- Microfluidics:Lab-on-chip architectures miniaturize sample preparation and detection into disposable cartridges.
- Electronic Test Devices:Smartphone-connected readers and portable analyzers digitize result interpretation.
Immunoassays handle the majority of throughput; Nucleic Acid Testing is climbing the fastest on share.
End User:
Customer type fragmentation demands distinct platform configurations across facility-based and community-based delivery models.
- Diagnostic Laboratories:Centralized reference facilities and hospital-based labs perform confirmatory testing and viral load quantification. These sites prioritize automated sample-to-answer systems that reduce technician labor and standardize turnaround times across high-throughput workflows.
- Home Care:Lay health workers in Mozambique and Malawi administer oral-fluid rapid tests during household visits, capturing asymptomatic individuals who avoid clinic-based screening due to stigma concerns. This channel requires portable devices with minimal training requirements.
- Hospitals:Acute care facilities integrate HIV testing into emergency department and antenatal workflows.
- Blood Donation Centers:Transfusion services mandate serological screening of donor units with documented traceability.
Diagnostic Laboratories handle the majority of throughput; Home Care is gaining share fastest.
Distribution Channel:
Supply concentration in ministry procurement contrasts with margin-accretive retail fragmentation.
- Direct Sales:Manufacturers negotiate framework agreements with ministries of health and donor consortia in sub-Saharan Africa. These contracts specify volume commitments, cold chain requirements, and service level agreements for nucleic acid test reagents requiring temperature-controlled logistics.
- Retail Pharmacies:Urban pharmacy chains in Nigeria and Kenya stock oral-fluid self-test kits for out-of-pocket purchase. This channel captures asymptomatic screening demand outside national program eligibility criteria and offers price premiums above institutional tender rates.
- Online Retail:E-commerce platforms expand geographic reach for self-testing products.
- Wholesale Distributors:Regional logistics partners aggregate procurement for private laboratory networks.
Direct Sales handles the majority of throughput; Retail Pharmacies is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for HIV diagnostics diverges sharply across geographies. Sub-Saharan African ministries of health negotiate volume tenders with extreme price sensitivity, while private pharmacy channels in middle-income markets absorb modest premiums for self-testing convenience.
South Africa
The national HIV screening program and PEPFAR-funded procurement anchor regional volume. The South African Health Products Regulatory Authority enforces WHO prequalification alignment for public sector entry. Johannesburg and Cape Town house reference laboratory networks processing viral load quantification for test-and-treat protocols.
United States
Commercial insurers and CDC prevention programs sustain demand for fourth-generation immunoassays and nucleic acid confirmation. FDA emergency use authorization pathways compress timelines for viral load assay modifications. The Research Triangle Park cluster in North Carolina concentrates molecular diagnostics development activity.
Uganda
District hospital networks deploy cartridge-based molecular platforms under Ministry of Health decentralization policies. The Uganda National Drug Authority regulates importation through prequalification documentation requirements. Kampala anchors the national reference laboratory system while regional hubs in Mbarara and Gulu process decentralized testing volumes.
Germany
Blood donation centers and clinical reference laboratories sustain high-throughput analyzer demand. The EU In Vitro Diagnostic Regulation imposes post-market surveillance documentation that filters market participants. The Rhine-Main metropolitan region around Frankfurt concentrates diagnostics manufacturing and regulatory affairs infrastructure.
India
State-level AIDS control societies procure rapid test kits through centralized tenders with extreme price competition. The Central Drugs Standard Control Organization regulates HIV diagnostics under the Medical Devices Rules framework. The Mumbai-Pune corridor houses contract manufacturers supplying reagents to African procurement programs.
HIV Diagnostics Market Vendor Landscape
Integrated platform specialists and point-of-care innovators split the market into distinct competitive spheres. Consolidation around automated laboratory systems contrasts with fragmentation in rapid test manufacturing. Three archetypes dominate: multinational conglomerates with diagnostic divisions, pure-play molecular diagnostics specialists, and regional rapid test producers. Competitive moves center on WHO prequalification attainment and cold chain distribution partnerships in tropical markets.
Among the integrated laboratory platform providers, F. Hoffmann-La Roche Ltd and Abbott Laboratories exemplify the high-throughput automation archetype, while bioMérieux SA represents the syndromic panel specialization vector. These entities anchor competitive positioning through regulatory infrastructure depth and prequalification portfolio breadth rather than price-based rivalry alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Becton, Dickinson and Company |
| Siemens Healthineers |
| Bio-Rad Laboratories, Inc. |
| bioMérieux SA |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| QIAGEN |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Specialized enzyme suppliers concentrated in North America and Western Europe anchor margin capture for PCR consumables, while downstream pricing power fragments across ministry tenders and retail pharmacy channels. Reagent manufacturers extract premium returns from nucleic acid test kits, forcing instrument OEMs to compete on service contract bundling rather than hardware margins alone.
Pricing Analysis
Service contract revenue and reagent rental agreements drive lifetime value for platform manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified systems from non-certified alternatives and retail self-test kits. Cost compression in rapid immunoassays is intensifying because state-level AIDS control societies in India and African ministries negotiate extreme volume discounts. National procurement programs exhibit highest price sensitivity; private pharmacy channels in urban Nigeria and South Africa absorb modest premiums for convenience.
Supply Chain Analysis
Export-control regimes on nucleic acid amplification technologies limit flows to certain end-use destinations, constraining supplier flexibility. Manufacturing concentrates in Germany, the United States, and India for instruments; reagent production draws from Switzerland, Singapore, and the Netherlands. Reverse transcriptase enzymes and fluorescent probe chemistries remain vulnerable to single-source concentration. Distribution runs through cold-chain logistics partners with tropical climate expertise, feeding both direct ministry tenders and wholesale pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HIV diagnostics demand follows cyclical donor funding cycles, with PEPFAR replenishment and Global Fund allocation rounds driving procurement waves. Manufacturers must align capacity planning to these predictable funding pulses.
For Market Incumbents: Harden regulatory moats by accelerating WHO prequalification for cartridge-based molecular platforms before EU MDR documentation burdens escalate. Deepen backward integration into proprietary enzyme supply to offset geographic concentration risk from North American suppliers. Lock in multi-year service contracts with ministries of health in Uganda and Zimbabwe to secure viral load monitoring revenue streams against point-of-care displacement. For New Entrants and Emerging Players: Establish a beachhead in oral-fluid self-testing retail channels across Kenyan and South African pharmacy chains, where out-of-pocket purchase avoids tender price compression. Target connectivity-embedded platforms for Rwanda and Zambia national health information system integration, as digital mandates create preferred vendor barriers. Pursue white-label manufacturing partnerships with Mumbai-Pune corridor contract manufacturers to access African procurement pipelines without direct regulatory investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rapid test manufacturers facing margin pressure from Indian state tender competition. Five-to-ten year viability hinges on molecular diagnostics transition capabilities and cold chain distribution infrastructure in tropical markets. Monitor FDA emergency use authorization submission volumes for viral load assay modifications as inflection signal for platform technology refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks donor-funded procurement pools in sub-Saharan African ministry tenders. |
| Cartridge-Based Platform Launch | Eliminates batch-processing delays for Uganda district hospital networks. |
| Digital Connectivity Integration | Captures preferred vendor status under Rwanda national health information mandates. |
| Cold Chain Distribution Partnership | Enables reagent supply security across tropical climates with temperature-controlled logistics. |
| Syndromic Panel Development | Reduces per-test costs for reference laboratories screening HIV-tuberculosis co-infections. |
Methodological Framework
Desk research of WHO prequalification databases, FDA 510(k) and emergency use authorization filings, and national ministry tender records preceded structured interviews with diagnostic platform product managers, regulatory affairs specialists at IVD manufacturers, procurement officers at Global Fund implementing partners, and laboratory directors at Uganda district hospitals. Secondary validation drew from EMA documentation, ClinicalTrials.gov assay studies, and customs trade data on reagent imports. Bottom-up instrument installation tracking and top-down procurement budget analysis were triangulated against reported manufacturer revenue.
Assumptions held donor funding commitments stable across the analysis window while viral load testing coverage expansion and self-testing regulatory approvals were treated as scenario variables. Segmentation modeling spanned product format, technology tier, end-user facility type, and distribution channel structure. CAGRs were derived from fitted curves on historical procurement volumes and projected test-and-treat protocol adoption timelines. Forecast inputs included national HIV prevalence surveillance data and ministry decentralization policy implementation rates.
Sensitivities concentrate around PEPFAR funding renewal levels, EU MDR transition timeline delays, and nucleic acid test reagent export restriction escalations. Forecasts reflect these documented assumptions and prevailing regulatory frameworks. Material shifts in WHO prequalification criteria or major donor consortium procurement consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Extraction Kits Market
Diagnostics
Global Saliva Collection and Diagnosis Market