
 Companion Animal Arthritis Market | 2026-2036
Companion Animal Arthritis Market Size, Share, and Industry Trends Forecast 2026-2036
Companion Animal Arthritis Market Intelligence
The EU Green Deal's sustainability mandates for pharmaceutical supply chains is shifting procurement criteria across European veterinary distributors. Zoetis, Inc. leverages its biologics manufacturing scale to supply monoclonal antibody therapies for canine osteoarthritis. Boehringer Ingelheim International GmbH anchors its position through R&D intensity in metabolics and pain management pipelines. Dechra Pharmaceuticals plc specializes in topical and transdermal formulations that address compliance challenges in feline patients.
Companion animal arthritis encompasses degenerative joint disease management through pharmacological and nutraceutical interventions, including NSAIDs, polysulfated glycosaminoglycans, and anti-nerve growth factor antibodies administered via subcutaneous or oral routes to restore mobility and reduce nociceptive signaling in synovial joints. Prescription medications capture the dominant margin pool due to patent-protected biologics and mandatory veterinary oversight, while nutraceuticals compete on accessibility through direct-to-consumer channels. The injectable administration route leads in clinical settings for rapid bioavailability, though oral formulations sustain broader household compliance among aging pet populations.
The FDA Center for Veterinary Medicine governs approval pathways for novel arthritis therapeutics in the United States, while the EMA coordinates centralized marketing authorizations across EU member states for cross-border veterinary product distribution. The USDA Animal and Plant Health Inspection Service regulates certain biologic manufacturing facilities, creating layered compliance requirements that shape market access timelines. Stakeholders must monitor evolving pharmacovigilance reporting obligations and anticipate how tightening environmental impact assessments for pharmaceutical manufacturing will reshape supplier qualification criteria.
Market Dynamics
The FDA Center for Veterinary Medicine's tightened manufacturing standards for monoclonal antibody therapies is forcing supply chain requalification across biologics manufacturers, compressing timelines for new entrants while consolidating advantage among scaled producers.
Growth Catalysts
- Aging pet demographics:The United States hosts over 50 million dogs aged seven or older, creating sustained demand for disease-modifying osteoarthritis interventions.
- EU Green Deal sustainability mandates:Pharmaceutical supply chain procurement criteria now prioritize environmental impact assessments, rewarding early-adopter veterinary distributors with preferred supplier status.
- Anti-nerve growth factor antibodies:This therapeutic class delivers superior pain modulation compared to traditional NSAIDs, accelerating veterinary protocol adoption in specialty practices.
Market Restraints
- Biologics manufacturing concentration:Monoclonal antibody production capacity clusters among a limited cohort of contract manufacturing organizations, creating single-source vulnerability.
- Cold chain infrastructure gaps:Injectable arthritis therapeutics require uninterrupted temperature control, limiting distribution reach into rural veterinary markets.
- Extended FDA approval timelines:Novel veterinary biologics face 24-36 month review cycles, delaying revenue realization for development-stage assets.
Strategic Opportunities
- Feline formulation white space:Transdermal and topical delivery systems address compliance challenges in cats, an underpenetrated species segment relative to canine markets.
- Direct-to-consumer nutraceutical channels:Pet owners increasingly bypass veterinary intermediaries for glucosamine and chondroitin purchases, opening margin capture opportunities for branded ingredient suppliers.
- USDA APHIS facility certification:Biologic manufacturing sites achieving dual FDA-USDA compliance gain preferential access to federally regulated research and commercial channels.
Industry Challenges
- Veterinary specialist shortages:Board-certified veterinary surgeons and rehabilitation therapists remain concentrated in metropolitan corridors, constraining therapeutic adoption outside urban centers.
- Legacy practice management system integration:Electronic health record platforms in general veterinary practices lack specialized arthritis monitoring modules, fragmenting patient data across care episodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Companion Animal Arthritis Market |
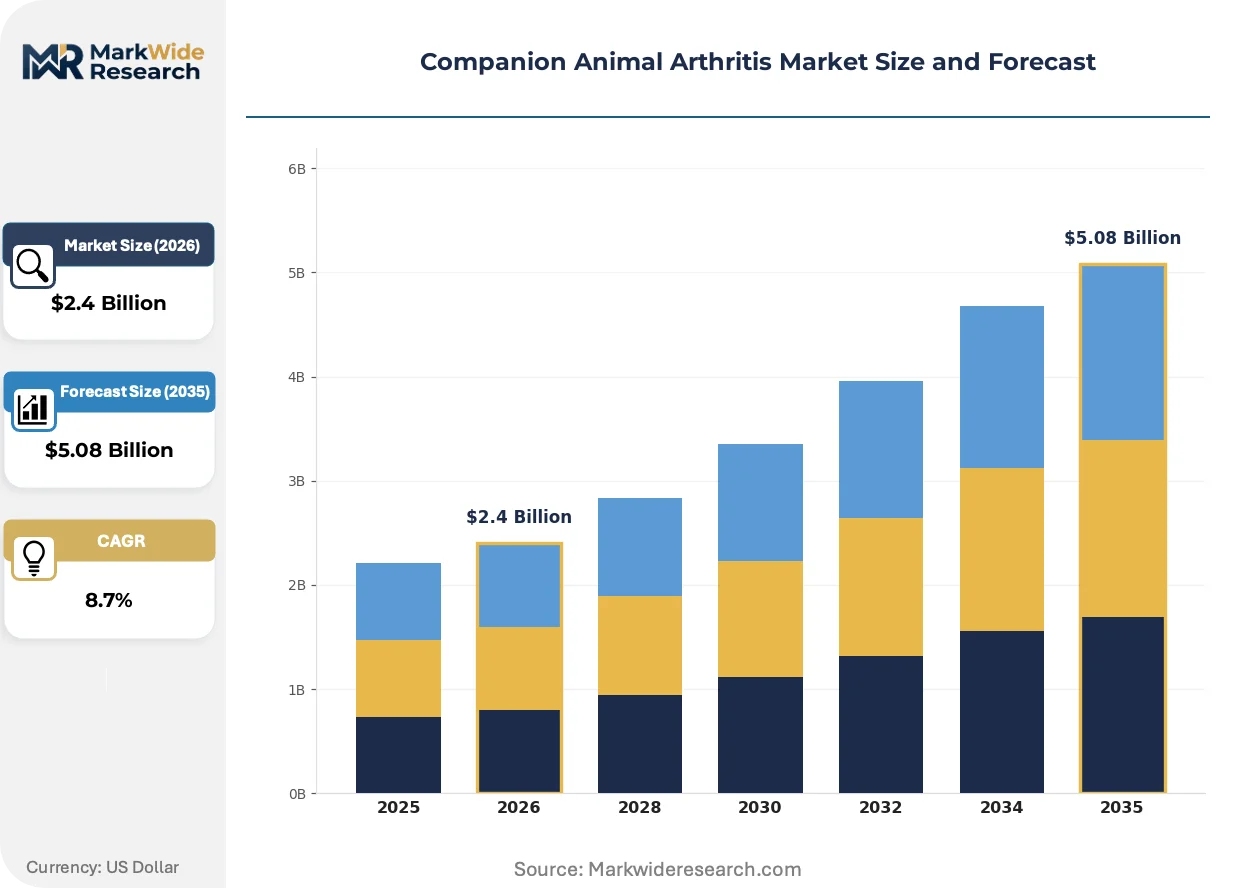
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, Nutraceuticals, Injections, Topical Treatments Administration Route: Oral, Injectable, Transdermal, Intravenous Animal Type: Dogs, Cats, Rabbits, Horses Distribution Channel: Veterinary Clinics, Online Retail, Pet Stores, Pharmacies |
| Companies Covered | Zoetis, Inc., Boehringer Ingelheim International GmbH, Elanco Animal Health Incorporated, Virbac, CEVA Santé Animale, Dechra Pharmaceuticals plc, Vetoquinol SA, American Regent, Inc., Nutramax Laboratories Veterinary Sciences, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Companion Animal Arthritis Market Strategic Shifts & Innovations
Biologics manufacturing scale and regulatory stringency are compressing competitive margins while opening differentiation pathways through species-specific formulation science and channel accessibility.
Anti-nerve growth factor monoclonal antibodies deliver targeted nociceptive pathway inhibition with reduced gastrointestinal toxicity versus COX-2 inhibitors. Specialty veterinary practices in the United States and Western Europe have adopted these agents as first-line therapy for moderate-to-severe canine osteoarthritis. Injectable biologics is overtaking oral NSAID prescriptions in metropolitan specialty referral networks, compressing the addressable market for small-molecule analgesics.
The EU Green Deal's pharmaceutical supply chain sustainability requirements mandate carbon footprint disclosure and waste reduction targets for veterinary product distributors. European procurement departments now embed environmental scoring into supplier qualification matrices, disadvantaging manufacturers without verified lifecycle assessments. Biologics producers with ISO 14001-certified facilities capture preferential contract terms across German, French, and Benelux veterinary purchasing cooperatives.
Pet owner purchasing behavior has shifted toward subscription-based wellness plans that bundle preventive diagnostics with chronic disease management. General veterinary practices in the United States are responding by unbundling arthritis monitoring from acute intervention, creating recurring revenue streams through telehealth follow-up and home delivery of maintenance therapeutics. This model concentrates most visibly in California, Texas, and Florida markets where practice management software vendors have deployed integrated e-commerce modules.
Companion Animal Arthritis Market Segmentation
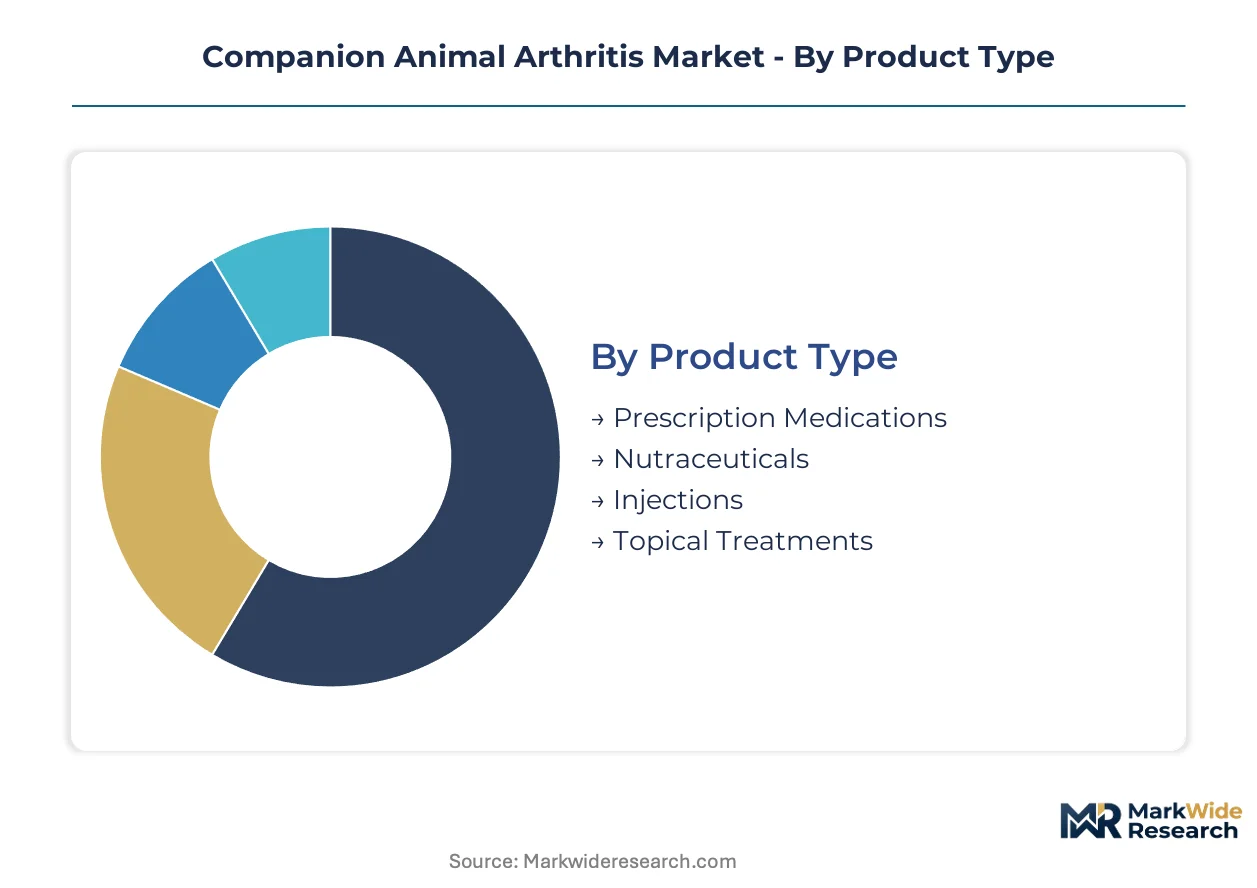
Companion animal arthritis therapeutics fragment across four intersecting dimensions that determine margin capture, regulatory pathway, and channel strategy. Product type and administration route govern manufacturing complexity and veterinary oversight requirements. Animal species and distribution channel shape pricing power and customer acquisition economics.
Product Type:
Prescription medications command premium pricing through patent protection and mandatory veterinary diagnosis, while nutraceuticals compete on accessibility through direct-to-consumer channels. Volume concentrates in mass-market formulations despite lower per-unit margins.
- Prescription Medications:Patent-protected biologics including monoclonal antibodies and polysulfated glycosaminoglycans require FDA Center for Veterinary Medicine approval and specialist administration. Demand clusters in United States metropolitan specialty practices where pet owners seek disease-modifying therapies for aging dogs.
- Nutraceuticals:Glucosamine, chondroitin sulfate, and omega-3 formulations fall outside prescription frameworks, enabling direct-to-consumer sales. California, Texas, and Florida households drive volume through subscription wellness plans bundled with telehealth follow-up.
- Injections:Injectable biologics deliver rapid bioavailability for acute flare management. Cold chain requirements limit rural veterinary market penetration.
- Topical Treatments:Transdermal NSAIDs and lidocaine patches address localized joint pain with reduced systemic exposure. Feline compliance challenges sustain niche positioning.
Mature deployment sits with prescription medications. Newer deployment is concentrated in nutraceuticals.
Administration Route:
Injectable routes dominate clinical settings for bioavailability and dosing precision, while oral and transdermal formats expand household compliance among aging pet populations. Cost tier stratification follows convenience and veterinary supervision intensity.
- Oral:Chewable tablets and liquid suspensions sustain chronic maintenance therapy in home environments. United States general veterinary practices prescribe oral NSAIDs as first-line intervention for mild-to-moderate osteoarthritis in suburban markets.
- Injectable:Subcutaneous and intra-articular administration delivers therapeutic concentrations for moderate-to-severe cases. Specialty referral networks in Germany and France prefer injectable biologics for rapid pain modulation.
- Transdermal:Gel and patch formulations bypass gastrointestinal metabolism and first-pass hepatic effects. Feline patients in Japanese urban households show highest compliance rates for transdermal methimidine alternatives adapted for arthritis.
- Intravenous:Hospital-administered polysulfated glycosaminoglycans address acute synovitis in equine and large-breed canine patients. United States university veterinary teaching hospitals concentrate IV therapy utilization.
Injectable administration anchors hospital revenue. Oral administration is expanding most quickly through retail veterinary chains.
Animal Type:
Canine applications generate dominant revenue share due to aging demographics and owner willingness-to-pay, while feline and exotic segments present formulation compliance challenges. Species-specific physiology dictates dosing regimens and palatability engineering.
- Dogs:Over 50 million United States dogs aged seven or older create sustained demand for disease-modifying interventions. Large-breed predisposition to hip dysplasia and elbow osteoarthritis concentrates therapeutic investment in retrievers, shepherds, and mastiff variants.
- Cats:Masking of pain behaviors delays diagnosis, compressing addressable market relative to canine populations. Transdermal formulations addressing feline compliance challenges command premium positioning in Benelux and United Kingdom markets.
- Rabbits:Exotic veterinary specialists manage arthritis in aging companion rabbits through compounded meloxicam and physical therapy. United States exotic animal practices in California and New York drive segment volume.
- Horses:Equine athletes and aging pleasure horses receive intra-articular corticosteroids and hyaluronic acid injections. Kentucky and Florida equine veterinary clinics concentrate therapeutic administration.
Canine applications dominate therapeutic development pipelines. Feline formulations represent the steepest expansion trajectory as compliance technologies mature.
Distribution Channel:
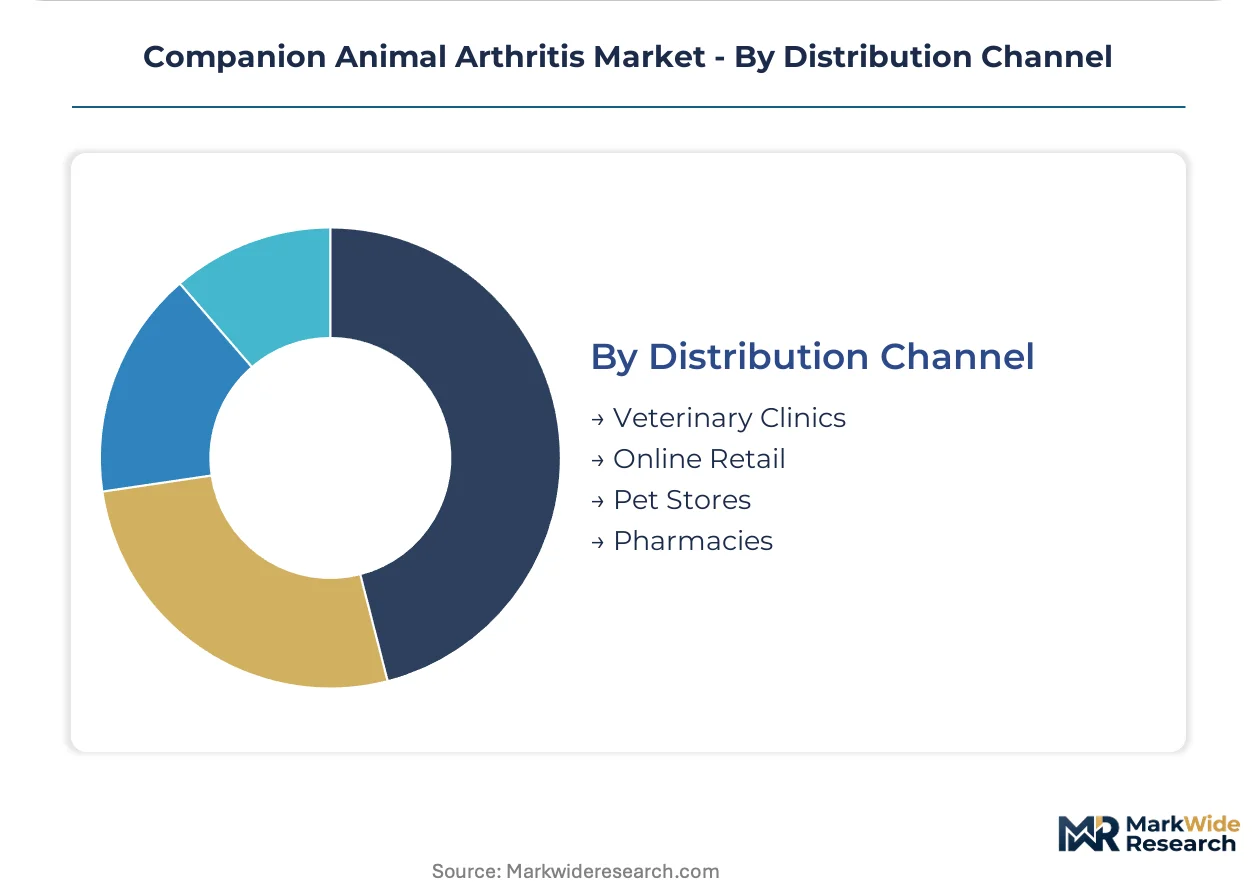
Veterinary clinics retain prescription medication gatekeeper status, while online retail and pet stores capture nutraceutical volume through convenience positioning. Channel margin structures diverge sharply based on regulatory oversight requirements.
- Veterinary Clinics:General and specialty practices control prescription medication dispensing through in-house pharmacies and mandated examination protocols. United States corporate veterinary groups consolidate purchasing power through centralized procurement.
- Online Retail:Direct-to-consumer platforms bypass veterinary intermediaries for nutraceutical and OTC topical sales. German and French pet owners demonstrate highest e-commerce penetration for glucosamine subscriptions.
- Pet Stores:Mass-market retailers stock limited-spectrum nutraceuticals with lower active ingredient concentrations. Big-box chains in Texas and Florida markets experiment with veterinary telehealth kiosks to extend prescription access.
- Pharmacies:Human pharmacy chains compound veterinary formulations where specialty manufacturing capacity exists. United States independent pharmacies in rural markets fill gaps where veterinary practice density is insufficient.
Veterinary clinics retain prescription dominance. Online retail is gaining share fastest in nutraceutical categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing concentrates in the United States and Germany while consumption spreads across aging pet populations in Western Europe and Japan. Veterinary pharmaceutical production clusters near FDA and EMA regulatory hubs, creating geographic friction between supply capacity and demand centers.
United States
Over 50 million dogs aged seven or older drive sustained demand for disease-modifying osteoarthritis interventions. The FDA Center for Veterinary Medicine governs approval pathways for novel monoclonal antibody therapies, tightening manufacturing standards that compress timelines for new entrants. Specialty veterinary practices proliferate in California, Texas, and Florida metropolitan corridors where pet owners seek advanced biologic treatments.
Germany
Large-breed canine populations and high veterinary expenditure sustain robust demand for injectable arthritis therapeutics. The EU Green Deal mandates carbon footprint disclosure and waste reduction targets across pharmaceutical supply chains, embedding environmental scoring into distributor procurement matrices. Biologics producers with ISO 14001-certified facilities in Bavaria and North Rhine-Westphalia capture preferential contract terms across veterinary purchasing cooperatives.
France
Specialty referral networks in Paris and Lyon prefer injectable biologics for rapid pain modulation in moderate-to-severe osteoarthritis cases. EMA centralized marketing authorizations coordinate cross-border veterinary product distribution across EU member states. Benelux markets adjacent to northeastern France demonstrate highest penetration rates for transdermal feline formulations addressing compliance challenges.
United Kingdom
Aging companion animal demographics and elevated pet insurance penetration support premium therapeutic adoption. The Veterinary Medicines Directorate enforces pharmacovigilance reporting obligations that shape post-market surveillance requirements. Dechra Pharmaceuticals plc anchors manufacturing and R&D operations in Shropshire, specializing in topical and transdermal formulations for feline patients.
Japan
Urban households demonstrate highest compliance rates for transdermal methimidine alternatives adapted for feline arthritis management. The PMDA regulates veterinary pharmaceutical approvals with timelines that generally parallel EMA processes. Tokyo and Osaka metropolitan veterinary clinics concentrate adoption of advanced biologic therapies among aging small-breed canine populations.
Companion Animal Arthritis Market Key Industry Players
The competitive structure tilts toward scaled biologics manufacturers with regulatory compliance depth. Patent-protected monoclonal antibodies and mandatory veterinary oversight create barriers that favor established pharmaceutical players with integrated manufacturing and distribution infrastructure. Three archetypes dominate: diversified human-animal health conglomerates, pure-play veterinary pharmaceutical specialists, and contract manufacturing organizations serving branded innovators. Consolidation through acquisition of niche formulation capabilities and strategic partnerships for cold chain distribution represent the dominant competitive moves reshaping market access.
Among diversified pharmaceutical conglomerates, Zoetis, Inc. and Boehringer Ingelheim International GmbH occupy positions reflecting scale advantages in biologics manufacturing and metabolics R&D intensity. Dechra Pharmaceuticals plc exemplifies the veterinary pure-play archetype, anchoring its competitive position through species-specific formulation science rather than broad therapeutic diversification. These three entities collectively represent the tiered structure where manufacturing scale, regulatory compliance depth, and species-specific expertise determine margin capture and market access velocity.
| Leading Market Players |
|---|
| Zoetis, Inc. |
| Boehringer Ingelheim International GmbH |
| Elanco Animal Health Incorporated |
| Virbac |
| CEVA Santé Animale |
| Dechra Pharmaceuticals plc |
| Vetoquinol SA |
| American Regent, Inc. |
| Nutramax Laboratories Veterinary Sciences, Inc |
| Others |
Cost & Logistics Intelligence
Veterinary biologics manufacturing specialists concentrated in Bavaria and North Rhine-Westphalia command wage premiums that propagate through three-tier pricing spreads across European and United States markets. Labor-cost differentials between ISO 14001-certified facilities and standard manufacturing sites translate directly into premium positioning for cold-chain biologics versus commodity nutraceuticals.
Pricing Analysis
Price erosion across injectable monoclonal antibodies traces to manufacturing scale advantages held by scaled producers with dual FDA-USDA compliance. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected biologics from authorized generics and direct-to-consumer nutraceuticals. ISO certification tier and cold-chain reliability drive price differentiation within the biologics tier. Cost-down pressure on oral NSAIDs accelerates because retail veterinary chains consolidate purchasing power through centralized procurement. General veterinary practices in suburban United States markets demonstrate highest price sensitivity, while specialty referral networks in metropolitan corridors absorb premium pricing for rapid-onset injectables.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Chicago, and Tokyo operate hub-and-spoke patterns that aggregate cold-chain biologics before last-mile veterinary clinic delivery. Manufacturing concentration clusters in the United States, Germany, and Switzerland for monoclonal antibody production. Active pharmaceutical ingredients and polysulfated glycosaminoglycans draw from specialized fermentation and mammalian cell culture facilities. Single-source vulnerability pervades contract manufacturing organization networks for fill-finish operations. Distribution runs through veterinary purchasing cooperatives in Europe and corporate veterinary group procurement in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion animal arthritis therapeutics reward players securing captive supply of biologics manufacturing capacity or direct-to-consumer channel control. Backward integration into cold-chain distribution infrastructure separates margin leaders from commodity-positioned competitors.
For Market Incumbents: To counter FDA manufacturing standard tightening that compresses new entrant timelines, deepen ISO 14001 certification coverage across European facilities and acquire feline formulation specialists in Benelux. Channel control through corporate veterinary group procurement contracts anchors volume retention against direct-to-consumer nutraceutical erosion. For New Entrants and Emerging Players: Enter via transdermal feline delivery systems where compliance technologies remain underdeveloped relative to canine markets. Target United States exotic animal practices in California and New York for compounded meloxicam positioning. Go-to-market leverage rests on telehealth-integrated subscription wellness plans bundling diagnostics with maintenance therapeutics. For Investors and Strategic Acquirers: The window for entry favors veterinary pure-plays with species-specific formulation science over diversified pharmaceutical conglomerates. Long-term viability centers on acquisition of transdermal delivery platform capabilities and cold-chain logistics networks. Watch anti-nerve growth factor antibody adoption rates in Japanese metropolitan clinics as inflection indicator for biologics displacement of oral NSAIDs.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Dual FDA-USDA facility certification unlocks federally regulated research and commercial channels for biologics producers. |
| Species-Specific Formulation Development | Transdermal feline delivery systems command premium positioning in Benelux and United Kingdom markets. |
| Direct-to-Consumer Channel Launch | Subscription wellness plans bundling telehealth with home delivery capture recurring revenue in California, Texas, and Florida. |
| Regulatory Compliance Investment | ISO 14001 certification embeds environmental scoring into German, French, and Benelux veterinary purchasing cooperatives. |
| Strategic Partnership | Cold-chain distribution agreements with regional hub operators extend biologics reach into rural veterinary markets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this companion animal arthritis therapeutics analysis. Primary interviews with veterinary pharmaceutical executives, regulatory affairs specialists at the FDA Center for Veterinary Medicine and EMA, specialty practice procurement directors, and corporate veterinary group supply chain managers combined with secondary validation from FDA 510(k) submissions, EMA centralized marketing authorization databases, and USDA APHIS facility inspection records. Bottom-up patient population modeling and top-down pharmaceutical expenditure triangulation cross-verified volume estimates.
Segmentation granularity modeled administration route, product type, animal species, and distribution channel at the country level across the analysis window. CAGRs derived from therapeutic class adoption curves, pricing trajectory assumptions, and veterinary practice consolidation rates. Forecast inputs incorporated anti-nerve growth factor antibody protocol penetration in specialty referral networks and direct-to-consumer nutraceutical channel shift velocities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA approval timeline extensions or EU Green Deal supply chain sustainability mandate acceleration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Software Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Veterinary Excipients Market
Veterinary
Pet DNA Testing Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Foot and Mouth Disease (FMD) Vaccine Market
Veterinary
Bovine Mastitis Market
Veterinary
Veterinary Lasers Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Spain Veterinary Healthcare Market