
 Allergy Diagnostics Market | 2026-2036
Allergy Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Allergy Diagnostics Market Intelligence
The divide between high-throughput, automated systems for central labs and single-use, point-of-care tests for clinics is restructuring the competitive landscape for allergy diagnostics. Thermo Fisher Scientific Inc. leverages its extensive scale in immunoassay platforms to serve large reference laboratories. Siemens Healthineers AG competes with integrated diagnostic solutions for hospital networks, while bioMérieux SA specializes in advanced molecular and microbiological diagnostics for complex cases.
Allergy diagnostics encompass the in vivo and in vitro methods used to identify specific allergens responsible for Type I hypersensitivity reactions. These tests function by detecting the presence and quantity of allergen-specific Immunoglobulin E (IgE) antibodies in a patient's serum or through skin reactivity. Serum Specific IgE Tests represent the dominant product category due to their safety profile and convenience. Within applications, food allergy detection is a significant and expanding segment, driven by rising prevalence and public health concerns.
Regulatory bodies including the US FDA, the European Medicines Agency (EMA), and China's NMPA mandate stringent validation for test accuracy and clinical performance claims. These clearance processes directly impact market entry timelines and the required evidence for new diagnostic products. The key decision for providers now revolves around the strategic investment in component-resolved diagnostics versus traditional whole-allergen testing methods to improve specificity.
Market Dynamics
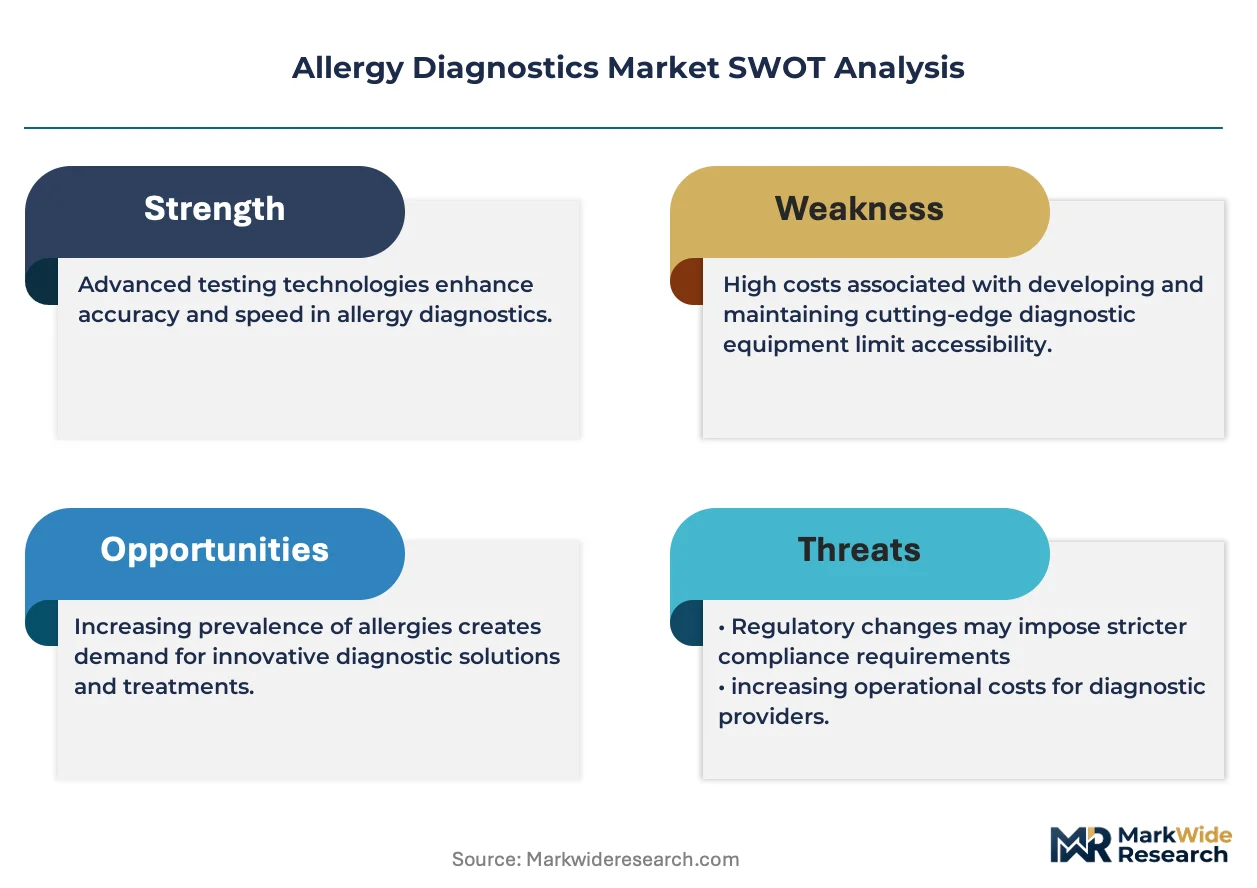
The allergy diagnostics market is shaped by the strategic divergence between high-throughput, automated systems for large central laboratories and single-use, point-of-care tests designed for clinics. This bifurcation influences investment decisions, competitive positioning, and channel strategies across the vendor landscape.
Growth Catalysts
- Stricter Labeling Mandates:New food allergen labeling regulations from bodies like the US FDA and the European Union's EMA are compelling more thorough screening by food manufacturers, directly increasing test volume.
- Laboratory Automation:The expansion of automated immunoassay platforms within large-scale diagnostic laboratories enables higher throughput and broader test menus, making allergy panels more accessible and cost-effective for healthcare providers.
- Developed Economy Demand:High public awareness, established healthcare infrastructure, and significant healthcare expenditure in countries such as Germany and Japan sustain strong, consistent demand for advanced diagnostic services.
Market Restraints
- High Test Costs:The elevated cost of advanced methods like component-resolved diagnostics restricts their widespread use to specialized centers, limiting adoption in routine clinical practice, particularly in price-sensitive healthcare systems.
- Reimbursement Variability:Inconsistent and often inadequate reimbursement policies for newer, more specific allergy tests across different national healthcare systems create financial uncertainty for both laboratories and manufacturers.
- Technical Limitations:The potential for cross-reactivity in traditional whole-allergen IgE tests can produce false-positive results, necessitating additional confirmatory testing which adds complexity and cost to the diagnostic process.
Strategic Opportunities
- Emerging Market Penetration:Untapped demand in Latin American and Southeast Asian countries, where allergy prevalence is rising alongside disposable incomes, presents a significant geographic expansion opportunity for test manufacturers.
- Point-of-Care Expansion:Developing and commercializing CLIA-waived, rapid point-of-care tests for common allergens allows for diagnostic decentralization into primary care clinics, pharmacies, and pediatric offices.
- Digital Health Integration:Integrating diagnostic results with AI-powered software platforms can provide predictive insights into allergy development and severity, offering a value-added service beyond a simple test result.
Industry Challenges
- Diagnostic Standardization:A lack of global consensus on allergen component nomenclature and result reporting standards complicates the ability of clinicians to compare data from different test systems, hindering the development of universal treatment guidelines.
- Data Management Complexity:Integrating allergy test results from multiple diagnostic platforms into a unified patient view within electronic health record systems poses a significant technical and interoperability challenge for hospital IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergy Diagnostics Market |
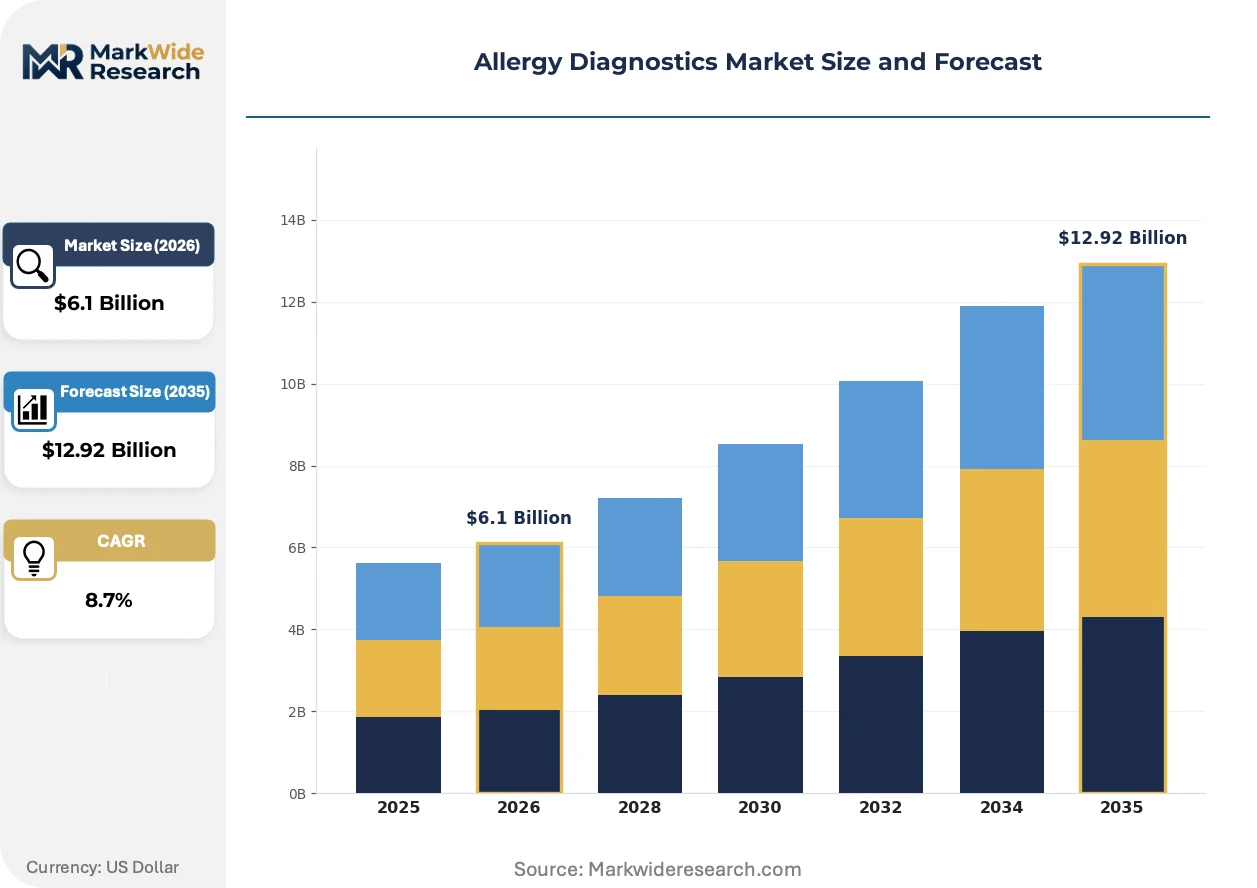
| Market Size in 2026 | $6.1 Billion |
| Market Size in 2035 | $12.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Prick Test, Serum Specific IgE Test, Patch Test, Blood Component Testing, Radioallergosorbent Test Application: Food Allergy Detection, Respiratory Allergies Identification, Drug Hypersensitivity, Insect Sting Allergy Evaluation, Environmental Allergy Analysis End User: Diagnostic Laboratories, Allergy Clinics, Research Institutes, Academic Hospitals, Specialized Healthcare Centers Technology: Enzyme-Linked Immunosorbent Assay, Chemiluminescent Immunoassay, ImmunoCAP, Microarray, Fluorescence Immunoassay |
| Companies Covered | bioMérieux SA, STALLergenes Greer, Thermo Fisher Scientific Inc., Minaris Medical America, Inc., HYCOR Biomedical, Siemens Healthineers AG, Omega Diagnostics Group PLC, EUROIMMUN MEDIZINISCHE LABORDIAGNOSTIKA AG, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergy Diagnostics Market Strategic Shifts & Innovations
The evolution of allergy diagnostics is driven by twin imperatives: enhancing diagnostic specificity to improve patient outcomes and broadening access to testing outside of specialized centers. This dynamic fosters innovation in both testing methodologies and service delivery models.
Component-resolved diagnostics (CRD) identifies patient sensitization to specific allergenic molecules rather than whole allergen extracts. Allergy specialists and large reference laboratories are adopting this technology to clarify complex cases involving multiple sensitizations or cross-reactivity. CRD is rewriting clinical management by enabling more precise risk stratification for severe reactions and informing tailored patient avoidance strategies.
Regulatory frameworks, such as the European Union's In Vitro Diagnostic Regulation (IVDR), are imposing more rigorous requirements for clinical evidence and post-market surveillance. This directly increases the time and cost associated with bringing new allergy tests to market. Manufacturers of both new and legacy diagnostic products are most affected, as they must invest heavily in performance studies to achieve or maintain CE marking.
Consumer demand for convenience and proactive health management is spurring a shift toward at-home sample collection models for allergy screening. This channel innovation often bypasses traditional primary care gatekeepers, with consumers purchasing kits online and sending samples directly to a partner laboratory for analysis. This trend is particularly visible in the United States, altering the initial patient entry point into the diagnostic pathway.
Allergy Diagnostics Market Segmentation
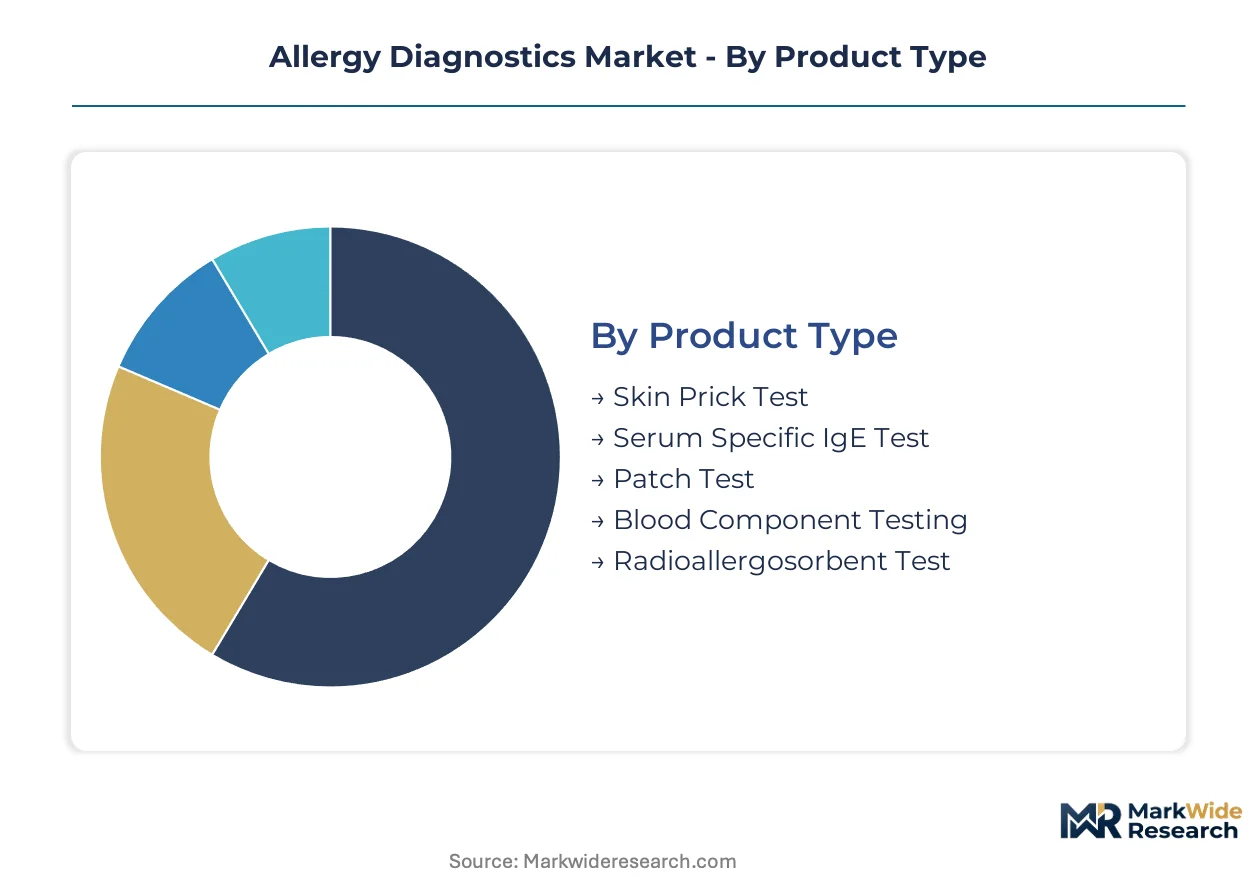
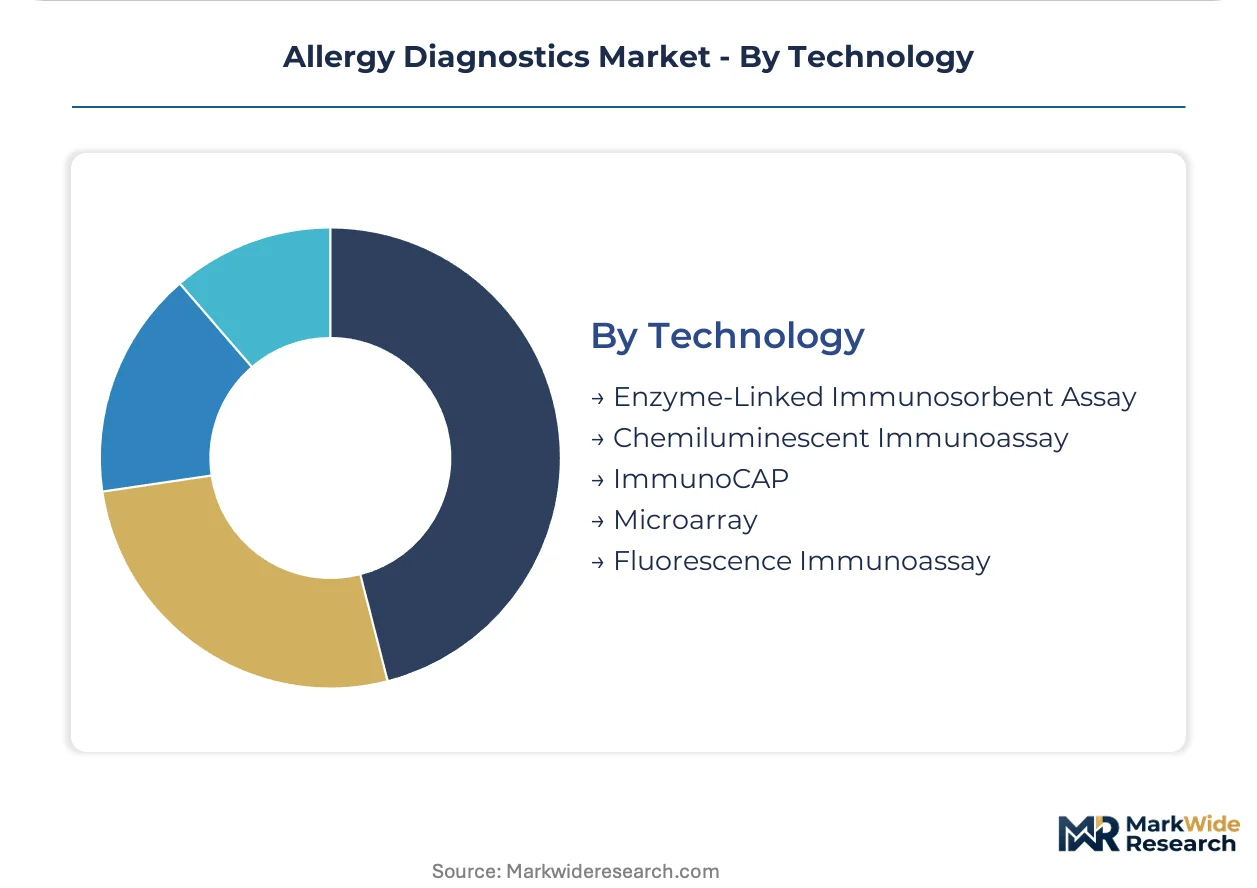
The allergy diagnostics market segments based on the diverse methods, applications, and end-user requirements that define testing pathways. Understanding these distinct categories provides clarity on where investment and innovation are concentrating across the diagnostic landscape. This analysis highlights the different operational models and technological preferences shaping market demand.
Product Type:
Buyers in the product type segment prioritize either convenience for initial screening or diagnostic depth for complex allergy cases.
- Serum Specific IgE Test:This in vitro method measures allergen-specific IgE antibodies in a patient's blood sample, offering a safe and convenient alternative to skin testing. Demand concentrates in developed economies like Germany due to high public awareness and established healthcare infrastructure supporting laboratory-based diagnostics.
- Blood Component Testing:This advanced method, including component-resolved diagnostics (CRD), identifies specific allergenic molecules within a blood sample, providing precise risk stratification for severe reactions. Allergy specialists and large reference laboratories in Japan are increasingly adopting CRD to clarify complex cases involving multiple sensitizations.
- Skin Prick Test:This in vivo method involves introducing small amounts of allergens into the skin to observe localized reactions, serving as a primary screening tool.
- Patch Test:Used primarily for contact dermatitis, this test involves applying allergen patches to the skin for a prolonged period to detect delayed hypersensitivity reactions.
- Radioallergosorbent Test:An older in vitro method, RAST measures allergen-specific IgE antibodies in serum, though largely superseded by newer immunoassay technologies.
Serum Specific IgE Test leads volumes today; Blood Component Testing is gaining share fastest.
Application:
The application segment highlights the diverse clinical needs addressed by allergy diagnostics, from common food sensitivities to rare drug reactions.
- Food Allergy Detection:This segment identifies immune responses to specific food proteins, driven by rising prevalence and stricter food allergen labeling regulations from bodies like the US FDA and the European Union's EMA. Demand is expanding significantly as public health concerns increase globally.
- Respiratory Allergies Identification:This application focuses on detecting allergens responsible for conditions like asthma and allergic rhinitis, which are widespread and impact a large patient population. Testing for common environmental allergens like pollen and dust mites remains a high-volume activity in countries with seasonal allergy burdens.
- Drug Hypersensitivity:This application identifies adverse immune reactions to pharmaceutical agents, crucial for patient safety and personalized medicine.
- Insect Sting Allergy Evaluation:This segment diagnoses allergic reactions to insect venom, guiding treatment strategies for potentially life-threatening anaphylaxis.
- Environmental Allergy Analysis:This application covers a broad range of outdoor and indoor environmental allergens, helping patients manage chronic allergic conditions.
Food Allergy Detection generates significant revenue, while Drug Hypersensitivity testing shows strong expansion.
End User:
End users in the allergy diagnostics market vary significantly by their operational scale and patient volume, influencing their technology adoption patterns.
- Diagnostic Laboratories:These facilities, often large-scale and centralized, leverage automated immunoassay platforms for high-throughput processing of allergy panels. They benefit from economies of scale and serve a broad referral base from various healthcare providers.
- Allergy Clinics:Specialized clinics focus on comprehensive allergy management, utilizing both in vivo and in vitro tests, including advanced component-resolved diagnostics, to provide tailored patient care. These clinics prioritize detailed diagnostic insights for their patient populations.
- Research Institutes:These entities conduct studies on allergy mechanisms, biomarker discovery, and novel diagnostic assay development, contributing to scientific advancement.
- Academic Hospitals:These large medical centers combine patient care with medical education and research, integrating allergy diagnostics into complex clinical pathways and training programs.
- Specialized Healthcare Centers:These centers offer focused services for specific allergic conditions, often adopting advanced diagnostic tools to cater to niche patient needs.
Diagnostic Laboratories account for the largest share of test volumes, with Specialized Healthcare Centers exhibiting steady patient growth.
Technology:
Technological advancements drive specificity and throughput across the allergy diagnostics landscape, enabling more precise and efficient testing.
- Enzyme-Linked Immunosorbent Assay (ELISA):This widely used immunoassay technology detects and quantifies allergen-specific IgE antibodies through an enzyme-substrate reaction, providing a robust and cost-effective method. ELISA platforms are prevalent in diagnostic laboratories for routine allergy screening due to their established reliability.
- Chemiluminescent Immunoassay (CLIA):This highly sensitive immunoassay technology uses a chemiluminescent label to detect specific IgE antibodies, offering excellent analytical performance and broad automation capabilities. CLIA systems are favored by large central laboratories for their high throughput and precision in detecting low antibody concentrations.
- ImmunoCAP:A specific brand of fluorescence enzyme immunoassay, ImmunoCAP is recognized for its high sensitivity and quantitative results for allergen-specific IgE, often considered a gold standard.
- Microarray:This multiplex technology allows for simultaneous detection of multiple allergen-specific IgE antibodies from a single blood sample, providing comprehensive profiles for complex cases.
- Fluorescence Immunoassay:This method uses fluorescent labels to detect and quantify IgE antibodies, offering high sensitivity and adaptability for various diagnostic platforms.
ELISA remains a foundational technology, while microarray platforms enable high-plex testing for complex cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentrations in life sciences and medical technology sectors anchor demand for advanced allergy diagnostics across key global regions. These hubs foster innovation and ensure rapid adoption of new testing methodologies. Healthcare infrastructure readiness and regulatory support also influence market penetration and growth trajectories.
United States
Stricter food allergen labeling rules from the US FDA drive demand for comprehensive screening and diagnostic testing. Consumers increasingly utilize at-home sample collection models for initial allergy screening. Biotech hubs like Boston and San Francisco continue to drive diagnostic innovation and product development.
Germany
High public awareness and established healthcare infrastructure sustain consistent demand for allergy diagnostics. The European Union's IVDR imposes rigorous requirements for clinical evidence, influencing market entry. Munich's life sciences sector sees significant investment in advanced diagnostic platforms for central laboratories.
Japan
High healthcare expenditure and a focus on precision medicine support the increasing adoption of component-resolved diagnostics. The PMDA ensures stringent test accuracy and clinical performance claims for new products. Tokyo's medical technology firms focus on integrating advanced molecular diagnostics into hospital networks.
China
Rising allergy prevalence and expanding healthcare access are driving increased test volumes across the country. China's NMPA mandates stringent validation for market entry of diagnostic products. Shanghai's diagnostic industry benefits from government support for localized production and technology transfer.
Brazil
Rising allergy prevalence and increasing disposable incomes present a significant geographic expansion opportunity for test manufacturers. ANVISA regulates medical devices and diagnostics, impacting market access and product clearances. São Paulo's medical technology sector is a hub for new diagnostic product launches targeting a growing patient base.
Allergy Diagnostics Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in allergy diagnostics. The market structure is tiered, with a few dominant integrated diagnostic solution providers and numerous specialized assay developers. Key archetypes include large-scale immunoassay platform manufacturers, advanced molecular diagnostics firms, and rapid point-of-care test developers. Market participants pursue portfolio diversification and strategic partnerships to expand their global footprint.
At the scale-driven end, Thermo Fisher Scientific Inc. and Siemens Healthineers AG offer extensive immunoassay platforms and integrated diagnostic solutions for large reference laboratories and hospital networks. bioMérieux SA, a European company, occupies a position specializing in advanced molecular and microbiological diagnostics for complex allergy cases. These firms represent the established players shaping the competitive dynamics.
| Leading Market Players |
|---|
| bioMérieux SA |
| STALLergenes Greer |
| Thermo Fisher Scientific Inc. |
| Minaris Medical America, Inc. |
| HYCOR Biomedical |
| Siemens Healthineers AG |
| Omega Diagnostics Group PLC |
| EUROIMMUN MEDIZINISCHE LABORDIAGNOSTIKA AG |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Vertical integration into diagnostic platform manufacturing anchors pricing power for large players like Thermo Fisher Scientific. This strategic choice dictates both supply control and the ability to offer comprehensive testing solutions.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing in allergy diagnostics. Integrated diagnostic solutions for hospital networks often command premium, contract-based pricing, reflecting comprehensive support and platform integration. Per-unit transactional pricing dominates for single-use point-of-care tests, catering to clinic-level convenience. Pricing pressure stems from the elevated cost of advanced methods like component-resolved diagnostics, limiting adoption in price-sensitive healthcare systems.
Supply Chain Analysis
Local content mandates, such as those implied by China's NMPA for localized production, reshape sourcing strategies for diagnostic components and reagents. Key manufacturing and innovation hubs concentrate in the United States, Germany, and Japan, anchoring global supply. The market relies on specialized biochemical reagents and immunoassay platform components. Regulatory restrictions, including stringent validation processes from bodies like the European Union's IVDR, represent a structural risk. Distribution runs through direct sales channels to diagnostic laboratories and specialized clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allergy diagnostics market functions as a stable compounder, driven by the sustained expansion of automated testing menus within large diagnostic laboratories. This consistent demand underpins predictable, long-term growth across the analysis window.
For Market Incumbents: Anticipate continued investment in component-resolved diagnostics to counter the technical limitations of traditional whole-allergen testing. Expanding automated immunoassay platforms in emerging markets presents a key lever for incumbents like Thermo Fisher Scientific. Reinforce relationships with large reference laboratories to maintain channel control against rapid point-of-care test developers. Regulatory bodies like the US FDA increasingly demand stringent validation, requiring ongoing R&D investment.
For New Entrants and Emerging Players: Capture underserved demand in Latin American and Southeast Asian countries, where allergy prevalence is rising. Developing CLIA-waived, rapid point-of-care tests for primary care clinics offers a significant white-space opportunity. Integrating diagnostic results with AI-powered software platforms provides a value-added service beyond simple test results. At-home sample collection models, particularly in the United States, allow direct patient engagement.
For Investors and Strategic Acquirers: Roll-up economics work for specialized assay developers because diagnostic standardization remains a challenge, creating niche opportunities. Long-term viability is secured by high public awareness and established healthcare infrastructure in developed economies. Acquisition targets include advanced molecular diagnostics firms specializing in component-resolved diagnostics. The increasing rigor of regulatory frameworks, such as the European Union's IVDR, serves as a signal to watch for market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Automated Immunoassay Platforms | Siemens Healthineers AG can enhance throughput for large diagnostic laboratories. |
| Invest in Component-Resolved Diagnostics R&D | bioMérieux SA can improve specificity for complex allergy cases and reduce false positives. |
| Develop CLIA-Waived Point-of-Care Tests | New entrants can decentralize testing into primary care clinics and pharmacies. |
| Integrate Digital Health Solutions | Providers can offer predictive insights into allergy development and severity for patients. |
| Pursue Emerging Market Penetration | Manufacturers can tap into rising allergy prevalence in Latin American countries. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. This included discussions with diagnostic laboratory directors, allergy clinic specialists, and regulatory affairs managers. Secondary data sources comprised US FDA clearance databases, European Medicines Agency guidelines, and academic research on allergy prevalence. Bottom-up and top-down triangulation ensured data consistency.
Segment-weighting formed the core of the analytical framework, disaggregating the market by product type, application, end-user, and technology. CAGRs were derived from historical growth trends and projected market dynamics over the projection horizon. Key forecast inputs included evolving allergy prevalence rates and new food allergen labeling regulations from bodies like the US FDA. Regional healthcare expenditure also informed market projections.
Reimbursement policy changes, unforeseen technological breakthroughs, and global health crises are the dominant revision risks for these forecasts. The projections reflect assumptions about healthcare expenditure and regulatory stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Semen Analysis Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Global Respiratory Diagnostics Market