
 Neurodegenerative Disease Market | 2026-2036
Neurodegenerative Disease Market Size, Share, and Industry Trends Forecast 2026-2036
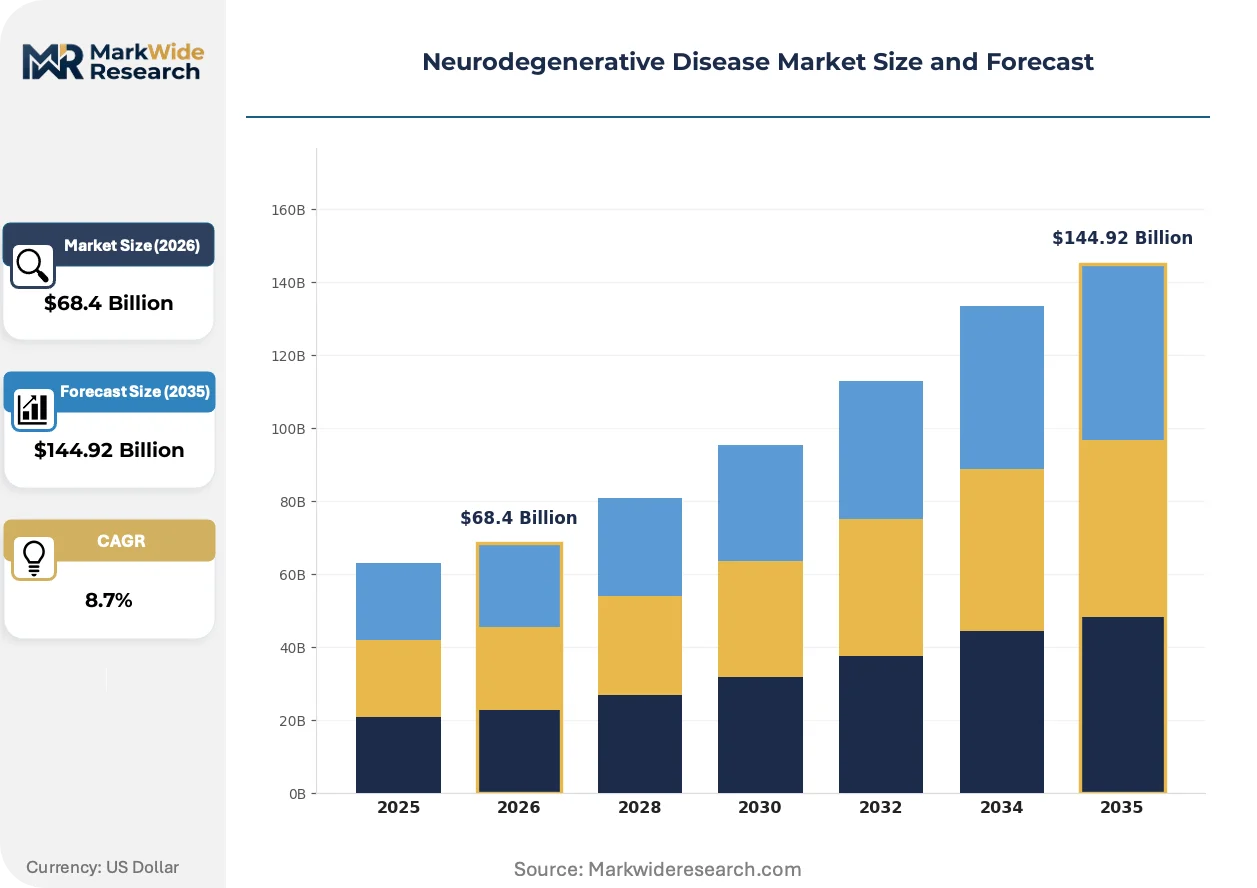
Neurodegenerative Disease Market Outlook
Buyer concentration among hospital networks and integrated delivery systems is hardening as large health systems consolidate purchasing decisions for high-cost biologics. Biogen Inc. sustains its position through deep specialization in amyloid-targeting platforms, while F. Hoffmann-La Roche Ltd anchors global diagnostics capacity with cerebrospinal fluid biomarker assays. Pfizer Inc. leverages manufacturing scale to compete on infusion-based therapies across major therapeutic areas.
Neurodegenerative diseases constitute a class of progressive disorders characterized by selective neuronal loss, protein misfolding pathology, and declining cognitive or motor function, with diagnosis relying on biomarker confirmation through PET imaging or fluid-based assays. The primary commercial purpose centers on slowing disease progression and managing symptomatic burden across Alzheimer's and Parkinson's patient populations. Pharmaceuticals dominates current revenue as small-molecule symptomatic treatments retain broad prescribing base, while biologics represents the fastest-expanding margin pool driven by monoclonal antibody development. Alzheimer's Disease application commands the largest addressable patient base, though Parkinson's Disease shows intensifying pipeline competition as disease-modifying targets advance.
FDA breakthrough therapy designation and EMA PRIME eligibility frameworks compress development timelines and reshape how sponsors allocate clinical trial investment across geographies. The FDA's accelerated approval pathway, contingent on biomarker endpoints, creates regulatory complexity requiring confirmatory trial commitments that influence portfolio risk calculations. Stakeholders must monitor how CMS coverage determination processes for novel biologics will structure reimbursement access and shape commercial launch sequencing across patient segments.
Market Dynamics
FDA's accelerated approval pathway contingent on biomarker endpoints is compressing development timelines while forcing sponsors into confirmatory trial commitments that reshape portfolio risk allocation across amyloid-targeting and tau-focused programs.
Growth Catalysts
- Breakthrough Therapy Designation:FDA's compressed review timelines pull investment toward disease-modifying candidates with surrogate endpoint strategies. Developers prioritize assets eligible for rolling submission protocols.
- Integrated Delivery Networks:Hospital system consolidation concentrates purchasing power for high-cost biologics. Neurology units within these networks streamline infusion capacity and patient access pathways.
- PET Imaging Infrastructure:Amyloid and tau tracer availability expands diagnostic confirmation capacity. Academic medical centers deploy hybrid PET-MRI systems to support trial enrollment and treatment monitoring.
Market Restraints
- Biomarker Assay Concentration:Cerebrospinal fluid collection and analysis capacity clusters at specialized academic centers. Community neurology practices face equipment and training barriers to adoption.
- Confirmatory Trial Burden:Accelerated approval mandates create sunk cost exposure if surrogate endpoints fail to translate into clinical benefit. Sponsors carry dual trial execution risk.
- Infusion Capacity Scarcity:Monoclonal antibody administration requires monitored settings with adverse event response protocols. Outpatient infusion center availability constrains patient throughput.
Strategic Opportunities
- Blood-Based Biomarker Validation:Plasma p-tau and neurofilament light assays promise diagnostic access expansion. Community-based screening protocols could reshape patient identification geography.
- Parkinson's Disease-Modifying Pipeline:Alpha-synuclein targeting programs advance behind Alzheimer's precedent. GBA and LRRK2 pathway investments concentrate at specialized biotech platforms.
- Japan's Sakigake Designation:PMDA's priority review framework offers early market access for innovative neurology assets. Sponsors sequence regulatory submissions to capture reimbursement precedent.
Industry Challenges
- Specialized Trial Site Scarcity:Cognitive assessment rater certification and MRI standardization requirements limit qualified investigator networks. Recruitment bottlenecks extend enrollment timelines.
- Legacy Diagnostic Coding:ICD-10 classification lag behind biomarker-defined disease staging complicates payer coverage determination. Reimbursement ambiguity delays treatment initiation.
- Supply Chain Cold-Chain Integrity:Biologic stability requirements demand continuous temperature monitoring from manufacturing through infusion. Distribution network qualification consumes qualification resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurodegenerative Disease Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biologics, Diagnostics, Therapies Application: Alzheimer's Disease, Parkinson's Disease, Huntington's Disease, Amyotrophic Lateral Sclerosis End User: Hospitals, Clinics, Home Care, Research Institutions Delivery Mode: Oral, Injectable, Infusion, Transdermal |
| Companies Covered | Pfizer Inc., Biogen Inc., F. Hoffmann-La Roche Ltd, Novartis AG, AbbVie Inc., Sanofi S.A., Eli Lilly and Company, Merck & Co. Inc., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurodegenerative Disease Market Strategic Shifts
Biomarker-driven trial design is collapsing traditional phase boundaries while digital health technologies capture real-world efficacy data outside controlled clinical settings.
Multimodal biomarker platforms combining plasma assays, digital cognitive assessments, and wearable motor sensors are unifying patient stratification across Alzheimer's and Parkinson's trials. Contract research organizations deploy these integrated panels to reduce screen failure rates and accelerate enrollment. The technology is unifying previously siloed diagnostic workflows into continuous monitoring protocols that compress trial duration.
EMA's PRIME eligibility framework is compressing scientific advice timelines and accelerating access to centralized procedural assistance for neurodegenerative disease sponsors. The policy consequence shifts regulatory strategy investment toward European trial footprint expansion ahead of US filing. Small and mid-cap developers most affected are restructuring clinical operations to capture priority medicines status.
Hospital-at-home infusion models are displacing traditional outpatient center dependence for stable biologic administration. Medicare Advantage plans in the United States pilot remote monitoring protocols that substitute in-person observation with telemedicine oversight. The shift is most visible in Florida and Arizona retirement corridors where patient mobility constraints and facility distance create access inequities.
Neurodegenerative Disease Market Segmentation
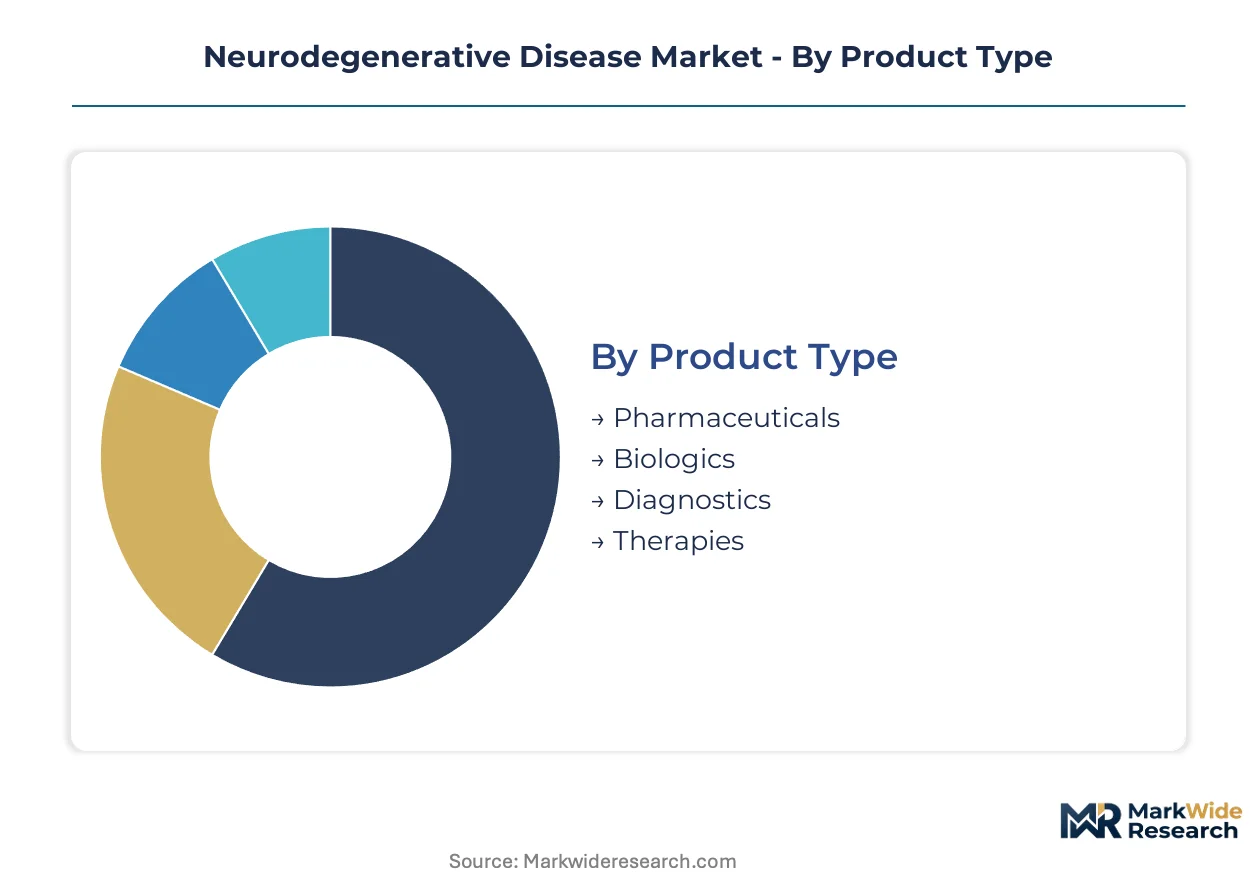
Neurodegenerative disease treatment markets fragment across therapeutic modality, disease pathology, and care setting. Each segmentation axis reveals distinct margin structures, regulatory pathways, and capacity constraints that reshape competitive positioning.
Product Type:
Volume concentration sits with established small-molecule formulations, while premium pricing power clusters around biologic platforms requiring cold-chain infrastructure and specialized administration.
- Pharmaceuticals:Small-molecule symptomatic agents including cholinesterase inhibitors and dopamine precursors retain the broadest prescriber base. Medicare Part D formularies in the United States drive volume through tiered copay structures, though generic erosion compresses margins across mature assets.
- Biologics:Monoclonal antibodies targeting amyloid-beta and emerging anti-tau constructs command infusion-based reimbursement at academic medical centers. FDA accelerated approval contingent on biomarker endpoints forces sponsors into parallel confirmatory trial commitments that reshape portfolio risk allocation.
- Diagnostics:PET amyloid and tau tracers plus cerebrospinal fluid assay platforms enable disease confirmation and trial stratification.
- Therapies:Non-pharmacological interventions including deep brain stimulation and focused ultrasound ablation address motor symptom subsets.
Today's leader: Pharmaceuticals. Tomorrow's challenger: Biologics.
Application:
Disease-specific investment correlates with addressable patient base size and biomarker validation maturity, creating divergent competitive intensity across pathology types.
- Alzheimer's Disease:Amyloid-targeting approvals have validated surrogate endpoint strategies for cognitive decline modification. The FDA's contingent approval framework for lecanemab and donanemab establishes regulatory precedent that pipeline sponsors now replicate.
- Parkinson's Disease:Alpha-synuclein imaging tracers and GBA pathway modulators are advancing through Phase II, with Roche's prasinezumab and Biogen's BIIB122 competing for disease-modifying positioning ahead of motor symptom progression.
- Huntington's Disease:CAG repeat expansion diagnostics enable genetic stratification, though therapeutic options remain predominantly symptomatic.
- Amyotrophic Lateral Sclerosis:Riluzole and edaravone establish modest survival extension benchmarks, with antisense oligonucleotide trials targeting SOD1 and C9orf72 mutations.
Alzheimer's commands current investment density. Parkinson's is climbing the fastest as biomarker infrastructure matures.
End User:
Care setting determines reimbursement pathway complexity and patient throughput capacity, with hospital consolidation reshaping purchasing leverage for high-cost modalities.
- Hospitals:Integrated delivery networks concentrate infusion capacity for monoclonal antibodies and deep brain stimulation procedures. Academic medical centers anchor trial enrollment through specialized neurology units with PET-MRI hybrid systems.
- Clinics:Community neurology practices face equipment barriers to biomarker assay adoption, creating diagnostic access gaps that blood-based screening protocols could eventually bridge.
- Home Care:Medicare Advantage pilots in Florida and Arizona retirement corridors are testing remote monitoring substitutes for in-person infusion observation.
- Research Institutions:Cognitive assessment rater certification and MRI standardization requirements limit qualified investigator networks, extending enrollment timelines for pivotal trials.
Hospitals dominate biologic revenue capture. Home care represents the steepest expansion trajectory as hospital-at-home models displace traditional outpatient dependence.
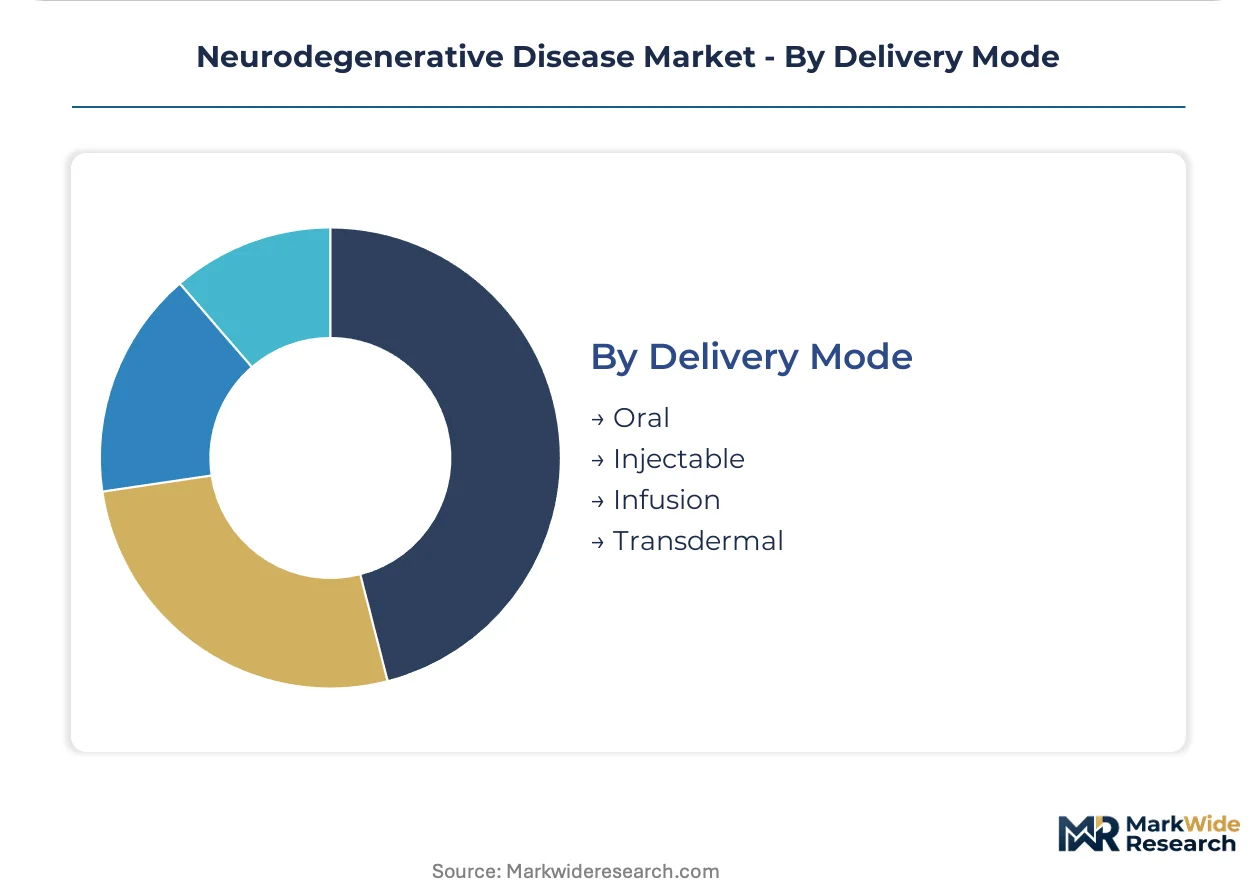
Delivery Mode:
Administration route dictates site-of-care requirements, cold-chain burden, and adverse event response infrastructure, segmenting addressable patient populations by mobility and geographic access.
- Oral:Small-molecule symptomatic treatments including donepezil and rivastigmine enable broad prescriber access without specialized administration infrastructure.
- Injectable:Subcutaneous formulations reduce site-of-care constraints compared to infusion, though adverse event monitoring requirements vary by agent.
- Infusion:Monoclonal antibodies require monitored settings with amyloid-related imaging abnormarity response protocols, constraining patient throughput.
- Transdermal:Rivastigmine patches address caregiver administration burden and gastrointestinal tolerability limitations of oral cholinesterase inhibitors.
Oral formulations retain volume leadership. Infusion is gaining share fastest as disease-modifying biologics reshape therapeutic standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement policies diverge sharply from Japan's priority review frameworks, creating divergent commercial launch sequencing for disease-modifying therapies across these two leading markets.
United States
Medicare Part D formularies and CMS coverage determinations structure access for high-cost biologics, with hospital system consolidation concentrating infusion capacity at academic medical centers. FDA's accelerated approval pathway for amyloid-targeting antibodies establishes regulatory precedent that sponsors now replicate. Massachusetts and California anchor specialized neurology trial networks with PET-MRI hybrid systems.
Japan
PMDA's Sakigake designation compresses review timelines for innovative neurology assets, pulling regulatory submission sequencing toward early Japanese market entry. The country's aging demographic concentrates demand for Alzheimer's and Parkinson's interventions. Tokyo and Osaka metropolitan areas host the majority of cerebrospinal fluid biomarker assay capacity.
Germany
EMA centralized procedures and Germany's statutory health insurance system create predictable reimbursement pathways for disease-modifying therapies. The country's diagnostic infrastructure supports broad PET tracer availability for amyloid confirmation. Munich and Heidelberg academic clusters drive Phase II-III trial enrollment across tau-focused programs.
Switzerland
Swissmedic's alignment with EMA scientific advice streamlines market access for biologics targeting progressive supranuclear palsy and multiple system atrophy. The country's precision medicine infrastructure supports biomarker-defined patient stratification. Basel and Zurich anchor pharmaceutical R&D concentration with specialized neurology units.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning frameworks determine access to infusion-based therapies for Alzheimer's disease. The UK's dementia research strategy prioritizes blood-based biomarker validation for community screening expansion. London and Cambridge academic medical centers lead digital cognitive assessment platform deployment.
Neurodegenerative Disease Market Competitive Environment
United States-based developers anchor the disease-modifying biologics tier; Swiss and German specialists hold established positions in diagnostics and small-molecule symptomatic agents. The market structure concentrates around three to five integrated pharmaceutical groups with neurology-specific R&D infrastructure, supplemented by mid-cap biotechnology platforms focused on single-pathway modulation. Strategic archetypes include amyloid-targeting antibody specialists, tau-focused platform companies, and diagnostic-assay integrators. Competitive moves center on biomarker assay acquisition and confirmatory trial partnership structures.
Among the integrated pharmaceutical tier, Pfizer Inc. and Biogen Inc. occupy positions representing manufacturing scale and deep specialization respectively, while F. Hoffmann-La Roche Ltd exemplifies the diagnostic-therapeutic convergence archetype through cerebrospinal fluid biomarker infrastructure. These three entities anchor distinct competitive vectors within the broader market structure.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Biogen Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| AbbVie Inc. |
| Sanofi S.A. |
| Eli Lilly and Company |
| Merck & Co. Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Cold-chain biologics manufacturing scale-up across Switzerland and Massachusetts is compressing per-unit production costs while concentrating supply leverage among integrated pharmaceutical groups with captive fill-finish capacity. This technological transition simultaneously expands margin headroom for disease-modifying therapies and hardens barriers for developers lacking manufacturing infrastructure.
Pricing Analysis
Capacity additions in Switzerland and Massachusetts are reshaping price floors for monoclonal antibody infusions as manufacturing scale economies offset cold-chain logistics burdens. Three-tier pricing structure across premium amyloid-targeting biologics, standard small-molecule symptomatic agents, and economy generic cholinesterase inhibitors stratifies the market by treatment modality and administration setting. Price differentiation hinges on FDA breakthrough therapy designation status and biomarker confirmation requirements. Cost compression in the small-molecule tier is intensifying because generic erosion of donepezil and rivastigmine formulations accelerates formulary tier shifts. Community neurology practices demonstrate highest price sensitivity due to Medicare Part D copay burden on fixed-margin operations, while academic medical centers with bundled payment contracts exhibit lowest sensitivity.
Supply Chain Analysis
Return flows of temperature-exposed biologics and refurbishment of infusion equipment create reverse-logistics complexity distinct from traditional pharmaceutical distribution. Active pharmaceutical ingredient synthesis concentrates in Switzerland, Ireland, and Singapore, with fill-finish operations clustering in Massachusetts and North Carolina. Cold-chain integrity rests on continuous temperature monitoring from manufacturing through patient administration, drawing from specialized logistics providers with validated thermal packaging. Single-source vulnerability in amyloid-beta precursor protein supply creates concentration risk for antibody developers. Distribution runs through specialty pharmacy channels with direct-to-site delivery protocols for hospital infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in neurodegenerative disease therapies stems from blood-based biomarker cost-down trajectories that promise diagnostic access democratization and patient identification at earlier disease stages.
For Market Incumbents: Acquire blood-based diagnostic assay platforms to anchor patient identification infrastructure ahead of biomarker validation completion. Secure infusion capacity commitments at academic medical centers through preferred provider arrangements that lock out pipeline competitors. Vertical integration into cerebrospinal fluid collection networks defends against community-based screening displacement. For New Entrants and Emerging Players: Community neurology practices in Florida and Arizona retirement corridors represent an underserved buyer archetype with unmet diagnostic access needs and Medicare Advantage reimbursement flexibility. White-space concentration sits with Parkinson's disease-modifying candidates where biomarker infrastructure lags Alzheimer's precedent. Direct-to-clinic sampling partnerships bypass hospital system consolidation barriers. For Investors and Strategic Acquirers: Roll-up economics work for specialized neurology CROs because trial site scarcity and cognitive assessment rater certification bottlenecks create durable competitive moats. Platform consolidation across biomarker assay developers and digital cognitive assessment tools offers five-to-ten year viability as regulatory frameworks harden around surrogate endpoint strategies. Watch FDA confirmatory trial readouts as inflection indicators for portfolio risk recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Assay Acquisition | PET tracer and CSF platform control secures trial stratification leverage against competitors. |
| Confirmatory Trial Partnership | Shared execution risk with academic medical centers reduces sunk cost exposure from surrogate endpoint failure. |
| Infusion Capacity Expansion | Hospital-at-home pilot scaling in Medicare Advantage corridors addresses throughput constraints. |
| Regulatory Submission Sequencing | PMDA Sakigake priority review capture precedes CMS coverage determination complexity. |
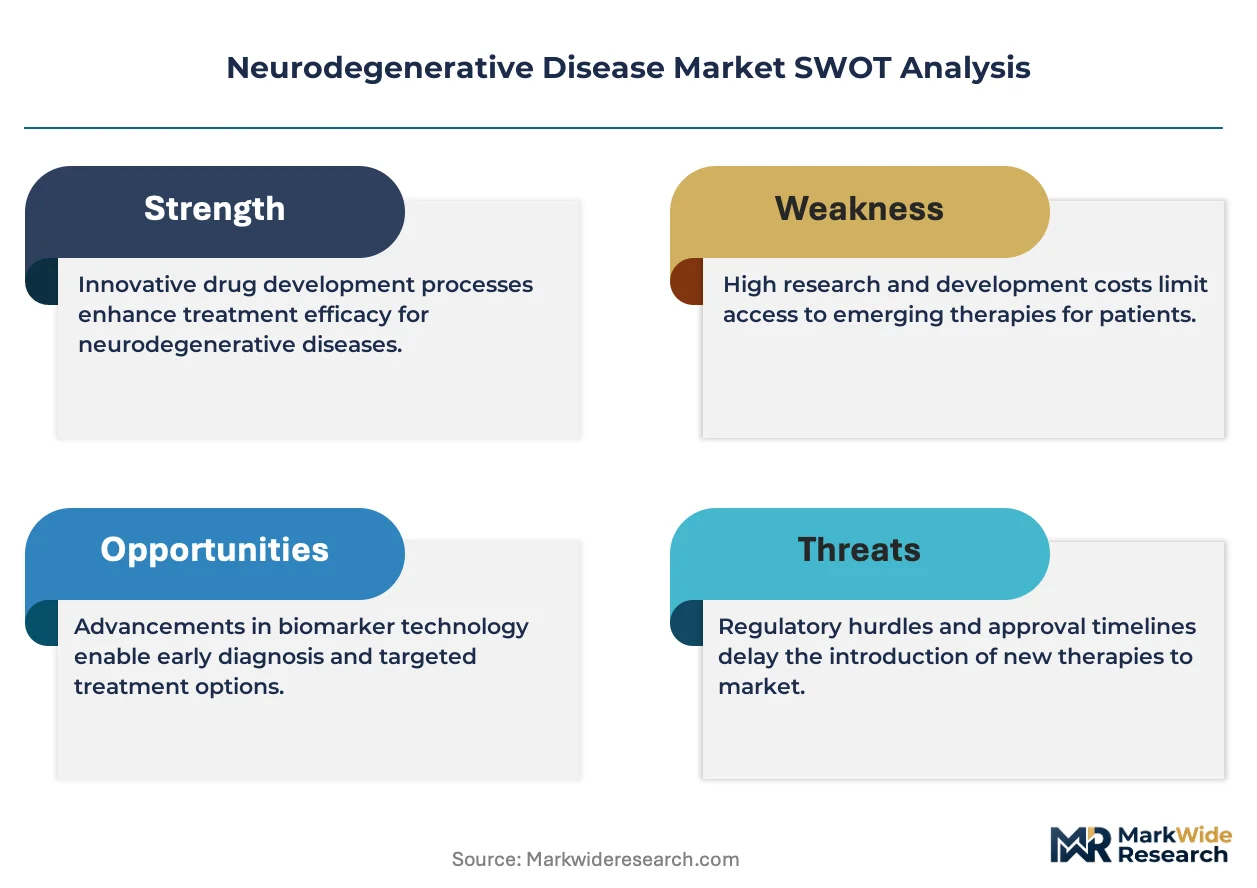
| Pipeline Diversification | Alpha-synuclein and tau pathway investments hedge against amyloid-targeting clinical benefit uncertainty. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down pharmaceutical manufacturing tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare claims data. Triangulation across these sources addresses reporting bias in pipeline disclosure and commercial volume estimates.
Input-output matrices map treatment modality demand against manufacturing capacity constraints across the projection horizon. Segmentation dimensions modeled include therapeutic modality, disease pathology, care setting, administration route, and regional regulatory cluster. CAGRs derive from patient population epidemiology, biomarker adoption curves, and reimbursement access trajectories. Forecast inputs incorporate infusion center capacity buildout rates and blood-based assay validation timelines.
Underlying measurement precision varies by segment; Alzheimer's disease prevalence estimates carry tighter precision than Huntington's disease due to diagnostic coding standardization differences. Forecasts reflect assumptions about FDA accelerated approval pathway continuity and CMS coverage determination timelines. Practitioners should monitor confirmatory trial readouts, biomarker assay regulatory clearances, and Medicare Advantage policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market