
 Cardiac Surgery Instruments Market | 2026-2036
Cardiac Surgery Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Surgery Instruments Market Analysis
Preventive maintenance and software-defined calibration layers is consolidating around instrument fleets, shifting vendor relationships from transactional sales to lifecycle partnerships. Medtronic plc leverages its integrated service networks to lock in multi-year hospital contracts. Stryker Corporation sustains competitive positioning through specialized cardiac instrument portfolios and dedicated field engineering teams. Abbott Laboratories anchors its presence in valve repair instrument lines with precision-manufactured delivery systems.
Cardiac surgery instruments encompass precision-engineered handheld and powered tools—typically manufactured from surgical-grade stainless steel or titanium alloys with tolerances measured in micrometers—designed to incise, grasp, suture, or manipulate cardiac tissue during thoracic procedures. Forceps and scalpels command the largest share of current product type demand, reflecting their ubiquity across all cardiac surgical approaches. Robotic delivery mode adoption is expanding fastest among delivery categories, driven by da Vinci system integration and surgeon training program maturation. Open heart surgery application segments retain the deepest margin pools due to instrument intensity and procedure complexity, though coronary bypass volumes sustain the highest absolute unit demand.
FDA premarket clearance pathways and ISO 13485 quality management standards govern instrument design validation and manufacturing consistency across the United States market. The EU Medical Device Regulation imposes enhanced clinical evidence requirements and Unique Device Identification mandates that reshape export strategies for manufacturers serving European hospitals. Stakeholders must monitor reimbursement code revisions for robotic-assisted cardiac procedures and positioning for service-contract revenue as capital equipment sales face pricing pressure from hospital group purchasing consolidation.
Market Dynamics
Robotic-assisted surgical platforms are compressing instrument replacement cycles and forcing manufacturers to embed connectivity layers into legacy handheld tools, fundamentally altering how hospitals evaluate total cost of ownership across instrument fleets.
Growth Catalysts
- Aging surgical populations:Rising prevalence of valvular heart disease and coronary artery disease in patients over 65 is expanding addressable procedure volumes across tertiary cardiac centers.
- FDA breakthrough device designation:Expedited review pathways for novel cardiac repair instruments are compressing time-to-market for sutureless valve technologies and enabling faster clinical adoption.
- Titanium alloy adoption:Advanced metallurgy with enhanced fatigue resistance is extending instrument lifespan and reducing per-procedure depreciation costs for high-volume cardiac surgery departments.
Market Restraints
- Surgical-grade stainless steel price volatility:Fluctuations in nickel and chromium feedstock costs are compressing margin stability for precision-forged instrument manufacturers.
- Single-supplier dependence for robotic instrument arms:Concentrated sourcing of da Vinci-compatible proprietary attachments creates vulnerability to supply interruptions and pricing leverage.
- ISO 13485 certification timelines:Extended quality management system audits and corrective action cycles are delaying product launches and freezing working capital in regulatory compliance.
Strategic Opportunities
- India's cardiac surgery infrastructure expansion:Government-funded medical cities and public-private hospital partnerships are creating instrument demand in tier-2 cities previously underserved by advanced thoracic surgery capabilities.
- Hybrid operating room integration:Convergence of intraoperative imaging systems with precision instrument tracking is opening revenue streams for instrument-software bundled offerings.
- EU MDR Unique Device Identification mandate:Regulatory traceability requirements are creating service-contract opportunities for instrument fleet management and automated sterilization cycle logging.
Industry Challenges
- Robotic surgery credentialing bottlenecks:Protracted training program completion and proctoring requirements are constraining surgeon throughput and delaying instrument utilization ramp.
- Legacy sterilization infrastructure incompatibility:Integration of advanced polymer-coated instruments with existing autoclave protocols requires capital-intensive reprocessing workflow redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Surgery Instruments Market |
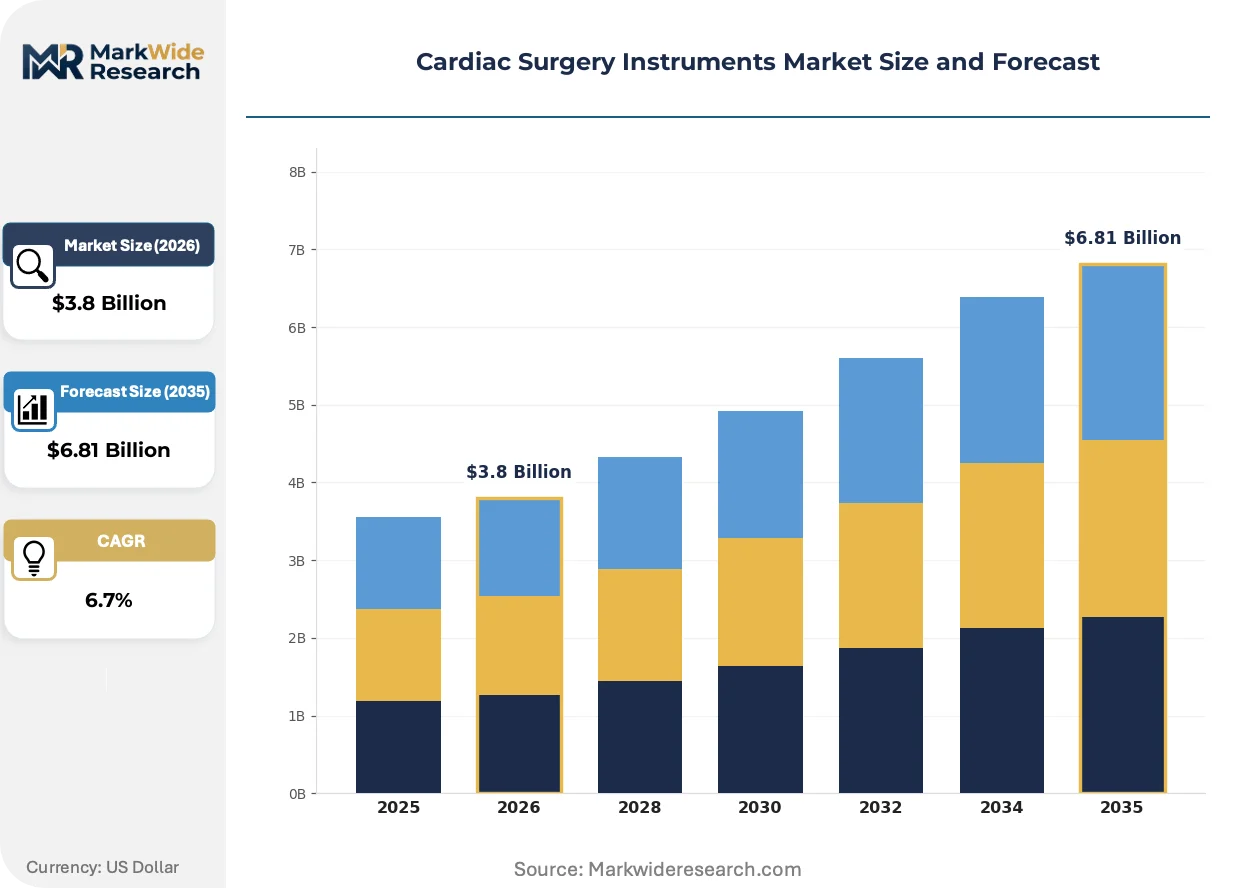
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Sutures Delivery Mode: Manual, Robotic, Electromechanical, Disposable End User: Hospitals, Surgical Centers, Research Institutes, Emergency Services Application: Open Heart Surgery, Coronary Bypass, Valve Repair, Aneurysm Repair |
| Companies Covered | Edwards Lifesciences Corporation, Stryker Corporation, Medtronic plc, B. Braun Melsungen AG, Terumo Corporation, Johnson & Johnson, Getinge AB, Teleflex Incorporated, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Surgery Instruments Market Emerging Trajectories
Digital instrument tracking and predictive maintenance algorithms are embedding intelligence directly into surgical tool supply chains, compressing equipment downtime and shifting vendor relationships toward continuous service models rather than episodic replacement sales.
Smart instrument handles with embedded RFID and usage sensors are modularizing how cardiac surgery departments manage their fleets. High-volume hospitals in the United States are deploying these connected tools to automate sterilization cycle counting and trigger just-in-time replacement orders. This connectivity layer is modularizing the traditional capital procurement model into subscription-based instrument availability guarantees.
The EU Medical Device Regulation's enhanced clinical evidence requirements are forcing manufacturers to rebuild technical documentation for legacy instrument portfolios. Class II surgical devices now require systematic post-market surveillance data that many established product lines lack. European notified bodies are extending review timelines, prompting manufacturers to prioritize MDR-compliant submissions for their highest-margin cardiac valve repair instrument sets.
Hospital group purchasing organizations are consolidating cardiac surgery instrument sourcing decisions across multi-hospital systems. This buyer concentration is compressing vendor margins and demanding standardized instrument configurations across divergent surgeon preferences. The United States exhibits the most pronounced consolidation, with regional GPOs negotiating enterprise-wide contracts that bundle instruments with robotic system service agreements.
Cardiac Surgery Instruments Market Segmentation
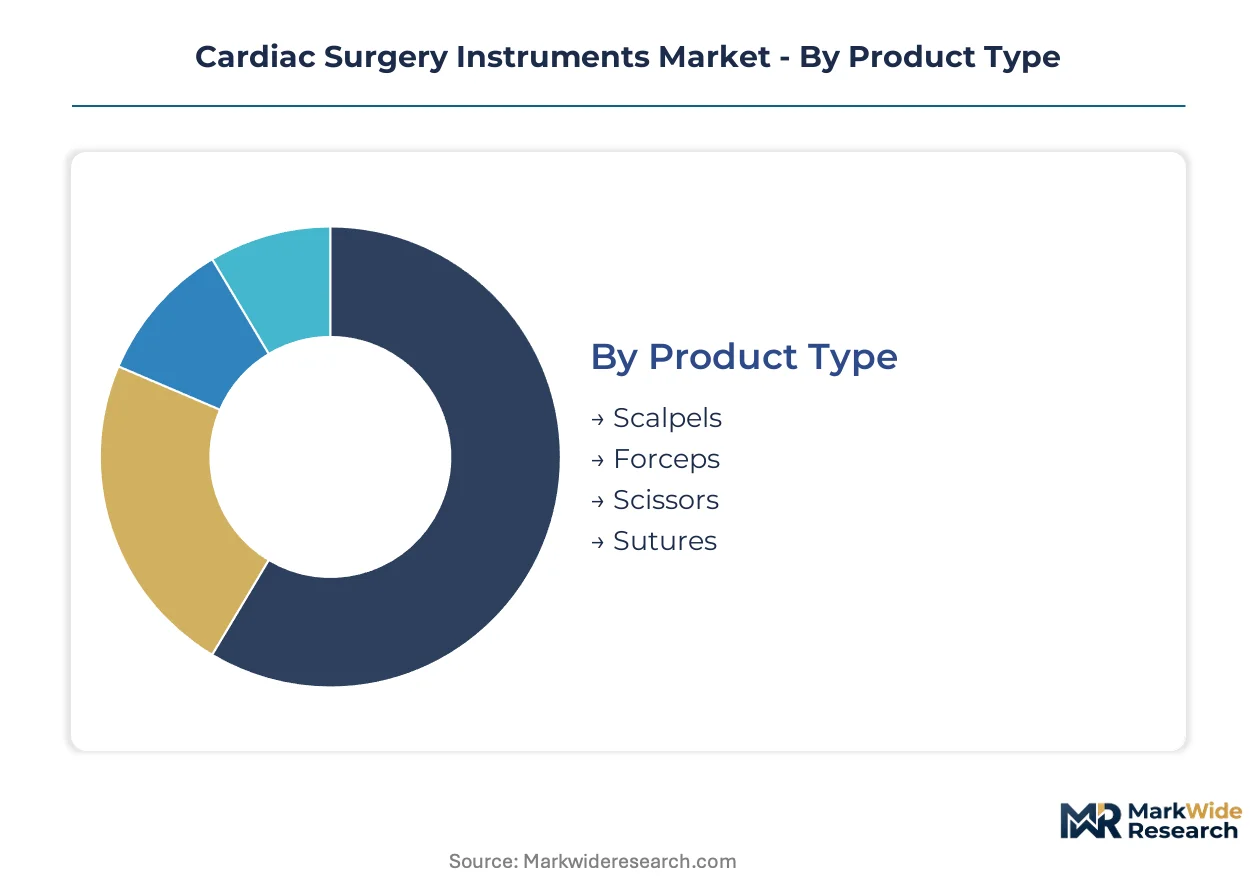
Cardiac surgery instruments fragment across four critical dimensions that determine procurement patterns and margin structures. Product type and delivery mode classifications shape hospital capital allocation, while end-user and application segments dictate instrument intensity and replacement cycles.
Product Type:
Forceps and scalpels anchor volume procurement through ubiquity across all thoracic procedures, while premium margins concentrate in specialized suture technologies.
- Scalpels:Precision-ground surgical blades manufactured from martensitic stainless steel with Rockwell hardness exceeding 55 HRC. Demand clusters in United States tertiary cardiac centers performing complex redo sternotomies where blade retention and edge durability reduce per-procedure costs.
- Forceps:Tungsten carbide-inserted grasping instruments with micro-serrated jaw patterns for atraumatic tissue handling. German cardiac surgery departments drive specification standards for DeBakey-pattern designs, influencing procurement requirements across European hospital networks.
- Scissors:Supercut and standard configurations for dissecting cardiac tissue and prosthetic graft materials.
- Sutures:Absorbable and non-absorbable configurations with pledgeted and continuous variants for valve annuloplasty and vascular anastomosis.
Today's leader: Forceps. Tomorrow's challenger: Sutures.
Delivery Mode:
Manual instruments dominate current fleet value, though connectivity requirements and robotic system integration are restructuring replacement economics.
- Manual:Handheld stainless steel and titanium instruments requiring surgeon tactile feedback for tissue manipulation. Japanese cardiac centers sustain premium positioning for handmade Japanese steel forceps, preserving artisanal manufacturing clusters in Seki and Sakai.
- Robotic:Proprietary instrument arms and end-effectors compatible with da Vinci surgical systems. South Korean hospital systems are expanding fastest in robotic cardiac program deployment, compressing training timelines through government-funded surgeon certification initiatives.
- Electromechanical:Powered staplers and clip appliers with battery or line power for tissue approximation.
- Disposable:Single-use instruments eliminating reprocessing costs and cross-contamination risk in emergency settings.
Manual instruments retain installed base dominance. Robotic delivery is expanding most quickly through system-level hospital commitments.
End User:
Hospital procurement concentration determines pricing leverage, while ambulatory migration creates instrument specification divergence.
- Hospitals:Integrated delivery networks with centralized sterile processing departments and capital equipment budgets. United States academic medical centers anchor demand for instrument-software bundles with predictive maintenance contracts.
- Surgical Centers:Focused cardiac facilities emphasizing same-day discharge and streamlined instrument workflows. Indian metro surgical centers are adopting disposable instrument strategies to bypass capital-intensive autoclave infrastructure.
- Research Institutes:Preclinical and translational research facilities requiring specialized microsurgical instruments for cardiac model development.
- Emergency Services:Field and transport settings demanding compact, sterilizable instrument sets for trauma-induced cardiac injury.
Hospitals command procurement volume. Surgical centers are gaining specification influence through volume growth.
Application:
Procedure complexity tiers separate premium instrument sets from standard configurations, with coronary volumes sustaining replacement demand.
- Open Heart Surgery:Full median sternotomy procedures requiring comprehensive instrument arrays including retractors, cannulae, and cardioplegia delivery systems. German cardiac surgery volumes in this category exceed European peers, sustaining specialized instrument manufacturer presence in Tuttlingen.
- Coronary Bypass:Revascularization procedures representing highest absolute annual case counts across all cardiac surgery applications. United States hospital systems perform these at scale, driving forceps and needle holder standardization through group purchasing organization consolidation.
- Valve Repair:Preservative procedures demanding precision annuloplasty band sizing instruments and chordal replacement tools.
- Aneurysm Repair:Aortic arch and thoracoabdominal interventions requiring deep hypothermic circulatory arrest instrument protocols.
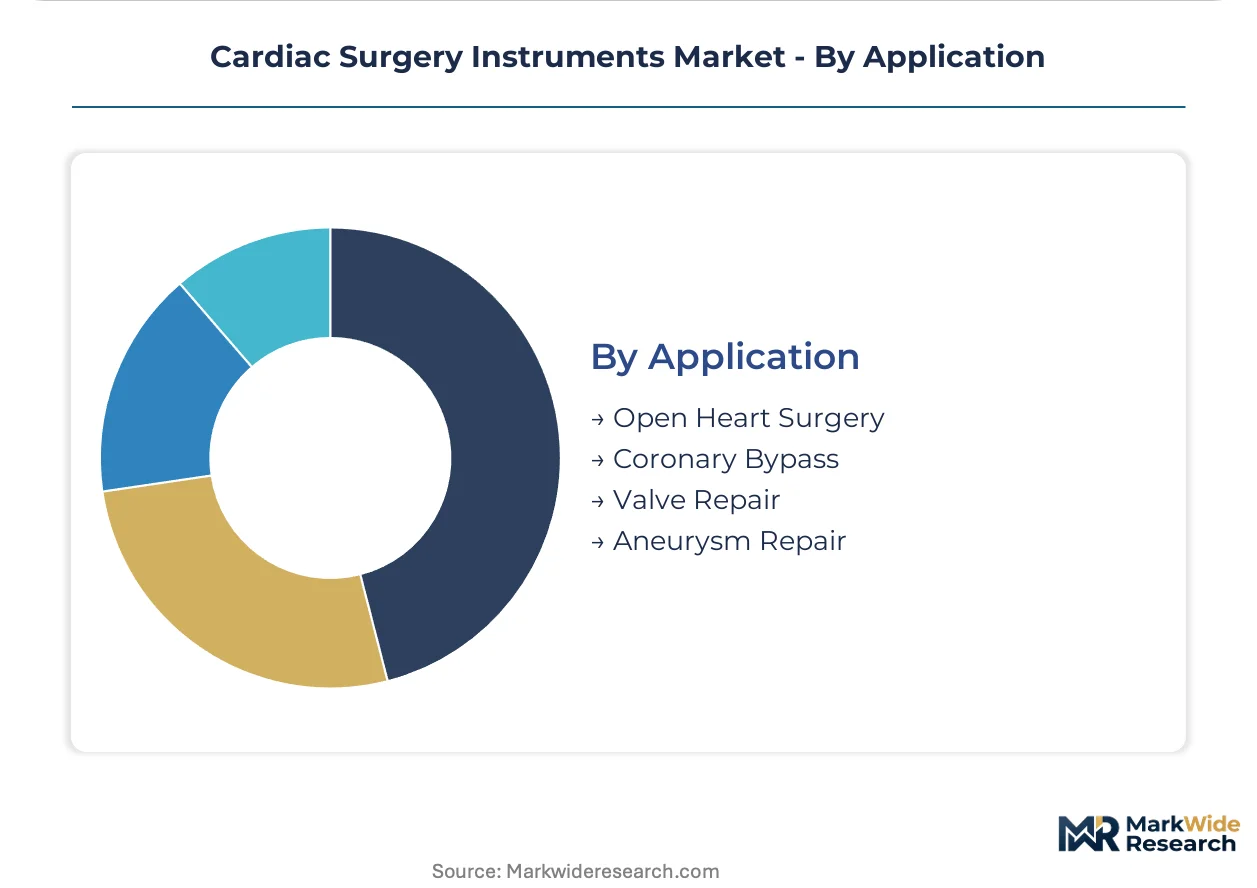
Coronary bypass sustains volume leadership. Valve repair is climbing the fastest through structural heart program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany performs cardiac procedures at higher per-capita rates than Japan, yet Japanese hospitals sustain premium pricing for artisanal steel instruments that German manufacturers struggle to replicate.
United States
Academic medical centers in Boston and Houston drive demand for instrument-software bundles with predictive maintenance contracts. FDA premarket notification requirements for Class II surgical devices shape product development timelines and compliance costs. The Cleveland Clinic anchors procurement standardization through its multi-hospital network, forcing vendors into enterprise-wide service agreements.
Germany
Tertiary cardiac centers in Berlin and Munich sustain specialized instrument manufacturer presence in Tuttlingen. EU Medical Device Regulation imposes enhanced clinical evidence requirements and Unique Device Identification mandates that reshape export strategies. The Baden-Württemberg cluster concentrates precision-forged instrument production for valve repair procedures.
Japan
Cardiac centers in Tokyo and Osaka preserve artisanal manufacturing clusters in Seki and Sakai for handmade steel forceps. PMDA regulatory pathways maintain stringent quality benchmarks that limit foreign vendor penetration. Kanto region hospitals emphasize surgeon tactile feedback preferences, sustaining manual instrument dominance against robotic alternatives.
India
Government-funded medical cities in Hyderabad and Chennai create instrument demand in tier-2 cities previously underserved by advanced thoracic surgery capabilities. CDSCO medical device regulations are tightening quality management system requirements for imported surgical tools. Maharashtra's public-private hospital partnerships are expanding cardiac surgery infrastructure faster than sterile processing capacity.
South Korea
Hospital systems in Seoul are expanding robotic cardiac program deployment fastest among Asian peers. MFDS expedited review pathways compress regulatory timelines for novel surgical instruments. Government-funded surgeon certification initiatives in the capital region are compressing training timelines and accelerating instrument utilization ramp.
Cardiac Surgery Instruments Market Vendor Landscape
Top-tier vendors anchor multi-hospital service contracts, while mid-tier specialists compete on instrument customization and regional responsiveness. The vendor base stratifies across integrated medtech conglomerates with robotic system portfolios, precision-forged instrument specialists with metallurgical expertise, and disposable instrument manufacturers targeting cost-sensitive surgical centers. Dominant competitive moves include strategic partnerships for hybrid operating room integration and geographic expansion into India's tier-2 cardiac surgery infrastructure.
Among diversified medtech conglomerates, Medtronic plc and Stryker Corporation exemplify the integrated service network archetype, leveraging multi-year hospital contracts to lock in instrument fleet management revenue. Abbott Laboratories occupies a position within the precision-delivery-system tier, anchoring presence in valve repair instrument lines. B. Braun Melsungen AG represents the European precision-manufacturing archetype, sustaining competitive positioning through specialized cardiac instrument portfolios.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Stryker Corporation |
| Medtronic plc |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Johnson & Johnson |
| Getinge AB |
| Teleflex Incorporated |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Hospital group purchasing organization consolidation across United States multi-hospital networks is compressing vendor margins and forcing manufacturers to restructure pricing models around multi-year service contracts rather than per-unit transactional sales.
Pricing Analysis
Capacity additions in South Korea and India are reshaping price floors for electromechanical and disposable instrument tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared titanium alloy instruments from ISO-certified stainless steel configurations and unbranded generic alternatives. Cost compression in the standard tier is intensifying because GPOs demand standardized instrument sets across divergent surgeon preferences. Ambulatory surgical centers in India exhibit the highest price sensitivity, while academic medical centers in Boston and Houston prioritize predictive maintenance bundling over per-unit cost.
Supply Chain Analysis
Ocean freight cost volatility between German manufacturing clusters in Tuttlingen and Asian cardiac centers is forcing inventory positioning shifts. Supply concentrates in Germany for precision-forged valve repair instruments, Japan for artisanal steel forceps from Seki and Sakai, and the United States for robotic-compatible instrument arms. Raw material dependencies include surgical-grade stainless steel with nickel and chromium feedstocks, titanium alloys with vanadium and aluminum additives, and tungsten carbide for micro-serrated jaw inserts. Single-source vulnerability for da Vinci-compatible proprietary attachments creates supply interruption exposure. Distribution runs through hospital group purchasing organizations and regional medical device distributors with sterile processing integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cardiac surgery instruments hinges on titanium alloy adoption extending instrument lifespan and reducing per-procedure depreciation costs for high-volume departments.
For Market Incumbents: Anticipate robotic surgery credentialing bottlenecks constraining surgeon throughput by embedding training support into service contracts. Defensive consolidation moves include acquiring specialized suture technology portfolios to anchor valve repair instrument lines and building captive titanium alloy forging capacity to offset feedstock price volatility. Vertical integration into precision metallurgy preserves margin stability against nickel and chromium cost swings. For New Entrants and Emerging Players: Tier-2 cardiac surgery departments in Indian medical cities represent an underserved buyer archetype with instrument demand outpacing sterile processing infrastructure. White-space targets include disposable instrument strategies bypassing capital-intensive autoclave requirements and electromechanical staplers for coronary bypass procedures. Go-to-market through public-private hospital partnerships in Maharashtra and Telangana accelerates credentialing without legacy field engineering investments. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-forged instrument specialists with metallurgical expertise and MDR-compliant technical documentation for legacy portfolios. Long-term viability over a multi-year horizon favors manufacturers with ISO 13485 certification infrastructure and European notified body relationships. Acquisition target archetypes include mid-tier German instrument manufacturers in Baden-Württemberg with valve repair specialization. The signal to watch is EU MDR Unique Device Identification mandate compliance timelines as a gate for European market access.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year service contracts with Cleveland Clinic anchor procurement standardization across integrated networks. |
| CE Marking Pathway | MDR-compliant submissions for valve repair instrument sets unlock European hospital access amid extended notified body timelines. |
| Software Companion Development | Predictive maintenance algorithms embedded in smart instrument handles automate sterilization cycle counting for United States academic centers. |
| Backward Integration | Captive titanium alloy forging capacity insulates margin stability from nickel and chromium feedstock volatility. |
| Reimbursement Strategy | Positioning for robotic-assisted cardiac procedure code revisions captures premium pricing as training programs mature. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and South Korea, with primary inputs from each market informing demand-side validation. The analysis combines structured interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, CDSCO medical device registrations, PMDA quality benchmarks, and hospital procurement databases. Bottom-up instrument unit demand modeling triangulates against top-down market value estimates from trade data and manufacturer revenue disclosures.
Segmentation granularity extends to product type, delivery mode, end user, and application dimensions across the projection horizon. CAGRs derive from procedure volume trajectories, instrument replacement cycle compression from robotic platform adoption, and titanium alloy penetration rates. Industry-specific forecast inputs include da Vinci system installation counts by hospital system and EU MDR technical documentation rebuild timelines for legacy portfolios.
Underlying measurement precision varies by segment; robotic delivery mode and open heart surgery application carry tighter precision than emerging disposable instrument categories. Forecasts reflect assumptions around surgeon training program completion rates, GPO contract renewal patterns, and sterile processing infrastructure buildout in Indian tier-2 cities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Iris Retractors Market