
 Global Liver Disease Diagnostics Market | 2026-2036
Global Liver Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liver Disease Diagnostics Market Foresight
Hospital procurement channels is reconfiguring as integrated delivery networks consolidate diagnostic purchasing across multi-site systems. Siemens Healthcare GmbH leverages its imaging portfolio to anchor long-term service contracts with large health systems. Abbott competes through point-of-care platforms that reduce laboratory turnaround times for hepatitis panels. Thermo Fisher Scientific Inc. specializes in molecular assay development, sustaining R&D partnerships with academic medical centers.
Liver disease diagnostics encompasses biochemical, imaging, and molecular modalities that detect fibrosis, inflammation, viral infection, and neoplastic transformation in hepatic tissue. Enzyme-linked immunosorbent assay platforms quantify serum biomarkers such as ALT, AST, and AFP with sensitivity thresholds reaching picogram-per-milliliter concentrations, enabling early-stage intervention before irreversible cirrhosis develops. Molecular diagnostics represents the fastest-expanding technology segment as polymerase chain reaction-based hepatitis viral load testing displaces slower culture methods in high-throughput laboratories. Imaging systems, particularly ultrasound and elastography equipment, command durable margin pools through recurring calibration and maintenance revenues.
The FDA regulates in vitro diagnostic devices through premarket notification and de novo pathways, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for CE-marked liver biomarker kits. ISO 13485 quality management standards govern manufacturing consistency across multinational supply chains, shaping vendor qualification criteria for diagnostic laboratories. Stakeholders must monitor evolving reimbursement codes for non-invasive fibrosis scoring algorithms as payors reassess coverage for alternatives to liver biopsy.
Market Dynamics
The transition from invasive liver biopsy to non-invasive biomarker testing and elastography imaging is compressing diagnostic timelines and redistributing revenue across laboratory and radiology service lines. This modality shift favors vendors with integrated platform portfolios over standalone assay suppliers.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review timelines for novel fibrosis biomarker panels accelerate commercialization of blood-based alternatives to histopathology, shortening the pathway from clinical validation to reimbursement.
- Germany's Specialist Center Model:Concentrated hepatology expertise at university hospitals drives standardized elastography protocols and bulk equipment procurement, creating anchor demand for imaging vendors.
- PCR Viral Load Testing:Molecular diagnostics laboratories are replacing culture-based hepatitis confirmation with automated nucleic acid amplification platforms, expanding throughput capacity for screening programs.
Market Restraints
- Reagent Supply Concentration:Polymerase and fluorescent probe manufacturing clusters in Germany and the United States create vulnerability to regional logistics disruptions affecting molecular assay production.
- EMA IVDR Clinical Evidence Requirements:Stricter post-market surveillance and performance study obligations for CE-marked liver biomarker kits extend regulatory timelines and inflate documentation costs for European market entry.
- Biopsy Pathology Infrastructure:Established histopathology laboratories with sunk investments in tissue processing equipment resist full conversion to non-invasive alternatives, slowing modality substitution.
Strategic Opportunities
- India's Underserved Tier-2 Cities:Hepatitis B and C prevalence in secondary urban centers exceeds diagnostic capacity, creating demand for portable point-of-care platforms deployable outside metropolitan hospital networks.
- Artificial Intelligence-Enhanced Elastography:Machine learning algorithms applied to ultrasound shear wave imaging improve fibrosis staging accuracy, enabling algorithm-as-a-service revenue models atop hardware installations.
- Japan's National Screening Mandates:METI-backed hepatitis elimination targets drive government-funded testing programs, opening procurement channels for high-throughput automated platforms in prefectural health centers.
Industry Challenges
- Interoperability with Legacy LIS:New biomarker reporting platforms require custom HL7 interface development to integrate with entrenched laboratory information systems, extending implementation timelines.
- ISO 13485 Audit Burden:Multinational manufacturers face overlapping quality management system audits across notified bodies, diverting engineering resources from product development cycles.
- Reimbursement Code Lag:Novel non-invasive fibrosis scoring algorithms await Category III CPT code assignments, creating temporary coverage uncertainty that delays hospital capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liver Disease Diagnostics Market |
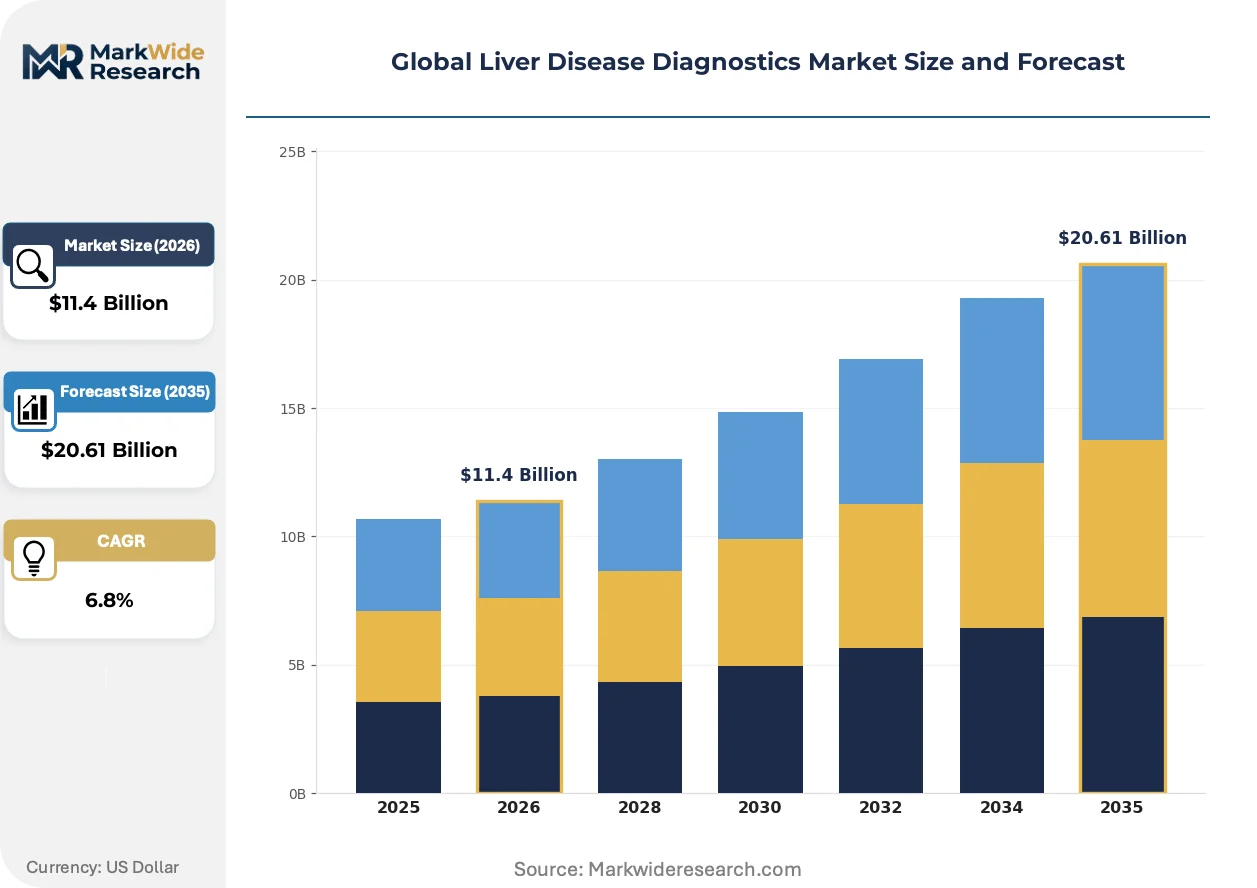
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Biochemical Tests, Molecular Diagnostics, Liver Biopsy Kits Technology: Ultrasound, Elastography, Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay Application: Hepatitis Screening, Cirrhosis Detection, Fatty Liver Evaluation, Liver Cancer Monitoring End User: Diagnostic Laboratories, Specialty Clinics, Research Institutes, Healthcare Providers |
| Companies Covered | Siemens Healthcare GmbH, Abbott, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., Randox Laboratories Ltd., Boston Scientific Corporation, Laboratory Corporation of America Holdings, Fujifilm Corporation, Horiba Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liver Disease Diagnostics Market Shifts & Advancements
Artificial intelligence integration, regulatory pathway evolution, and procurement centralization are simultaneously reshaping technology development priorities and commercial access strategies across the diagnostics value chain.
Magnetic resonance elastography is rendering obsolete conventional ultrasound-based stiffness measurement for indeterminate fibrosis cases. Academic medical centers in the United States and Germany are adopting MR elastography protocols for non-alcoholic steatohepatitis staging, compressing the addressable market for intermediate-accuracy imaging modalities and elevating premium-tier system requirements.
Europe's In Vitro Diagnostic Regulation imposes systematic clinical performance documentation obligations that exceed predecessor directive standards. Liver biomarker kit manufacturers must maintain post-market performance registries, which favors larger diagnostics firms with dedicated regulatory affairs infrastructure over mid-sized specialty assay developers seeking CE marking.
Integrated delivery networks in the United States are consolidating hepatitis panel purchasing across multi-hospital systems, displacing site-specific laboratory procurement autonomy. This concentration shifts negotiating leverage toward vendors offering enterprise-wide service contracts with standardized reagent pricing and remote instrument monitoring capabilities, most visible in Texas and California health system alliances.
Global Liver Disease Diagnostics Market Segmentation
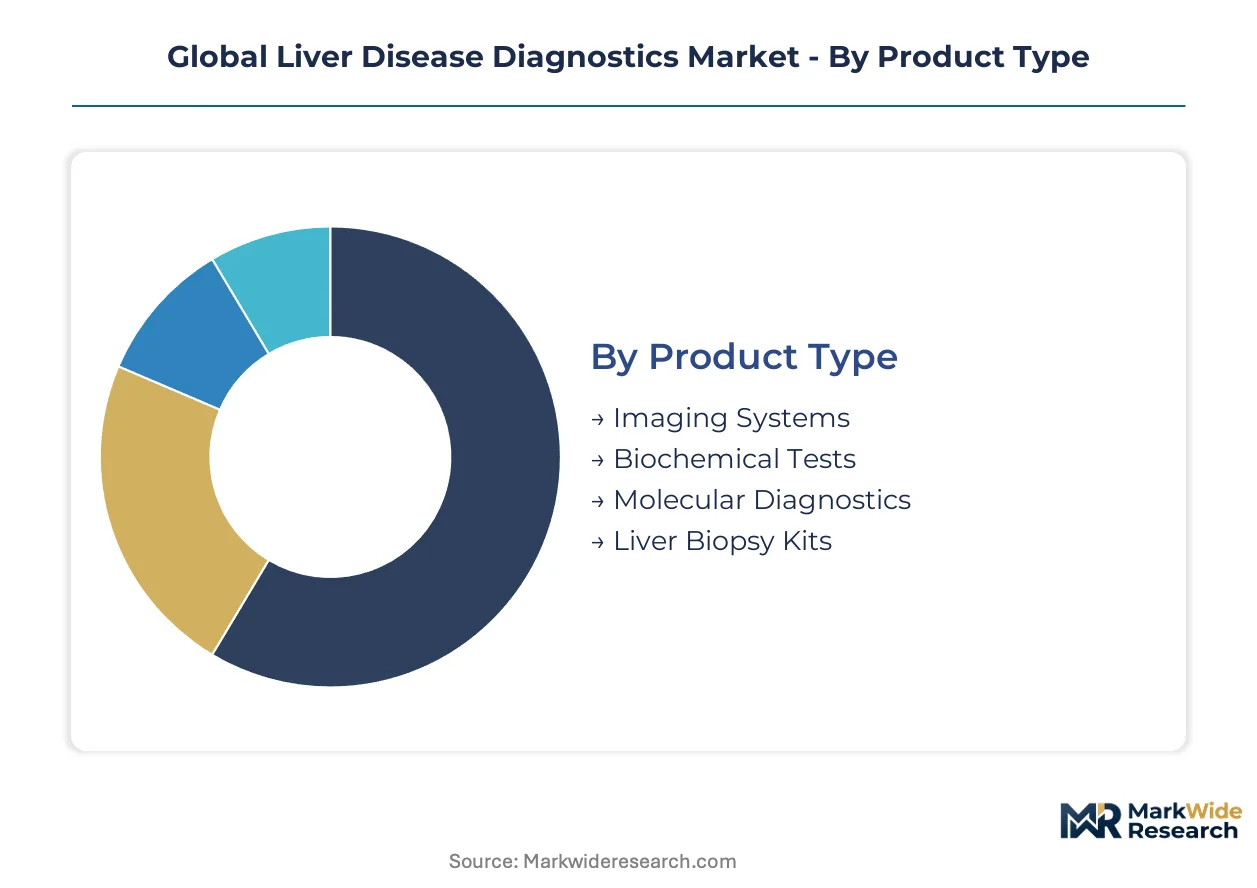
Diagnostic modality selection in liver disease hinges on disease stage, resource availability, and reimbursement pathways. Segmentation reveals how technology maturity and clinical utility distribute value across biochemical, imaging, and molecular platforms.
Product Type:
Mature biochemical platforms coexist with emerging molecular assays as laboratories balance throughput against diagnostic depth.
- Imaging Systems:Ultrasound and elastography equipment generate recurring service revenues through calibration contracts and software upgrades. Demand concentrates at university hospitals in Germany and the United States where hepatology centers standardize fibrosis staging protocols.
- Molecular Diagnostics:Polymerase chain reaction platforms detect hepatitis viral loads with sensitivity exceeding culture methods. Procurement is accelerating in Japan's prefectural health centers following METI-backed elimination targets.
- Biochemical Tests:Serum enzyme assays for ALT, AST, and AFP remain the workhorse for initial screening in high-volume hospital laboratories.
- Liver Biopsy Kits:Tissue acquisition devices face declining utilization as non-invasive alternatives capture share in cirrhosis evaluation workflows.
Biochemical tests handle the majority of throughput; molecular diagnostics is the fastest mover on share.
Technology:
Cost tier stratification separates premium imaging modalities from accessible point-of-care alternatives.
- Elastography:Shear wave imaging quantifies liver stiffness without invasive sampling. Specialist centers in Germany drive standardized adoption through bulk equipment procurement and protocol harmonization.
- Polymerase Chain Reaction:Automated nucleic acid amplification replaces slower culture confirmation in hepatitis screening programs. Supply concentration for polymerase reagents in Germany and the United States creates logistics vulnerability.
- Ultrasound:Conventional B-mode imaging serves as the entry-level modality for fatty liver evaluation in resource-constrained settings.
- Enzyme-Linked Immunosorbent Assay:ELISA platforms deliver cost-effective serological screening for hepatitis antigens and antibodies at scale.
Elastography commands premium pricing; PCR platforms are expanding most quickly in viral load quantification.
Application:
Volume distribution follows disease prevalence patterns and screening program mandates across healthcare systems.
- Hepatitis Screening:Population-scale testing programs target B and C virus elimination. Japan's national mandates and India's tier-2 city prevalence create divergent demand profiles for high-throughput versus portable platforms.
- Cirrhosis Detection:Fibrosis staging determines intervention timing before decompensation. Non-invasive biomarker panels and elastography displace biopsy in United States and German hepatology centers.
- Fatty Liver Evaluation:Non-alcoholic steatohepatitis monitoring expands with metabolic disease burden in diagnostic laboratories.
- Liver Cancer Monitoring:AFP surveillance and imaging protocols track hepatocellular carcinoma risk in cirrhotic patients.
Hepatitis screening handles the majority of throughput; fatty liver evaluation is climbing the fastest as metabolic disease prevalence rises.
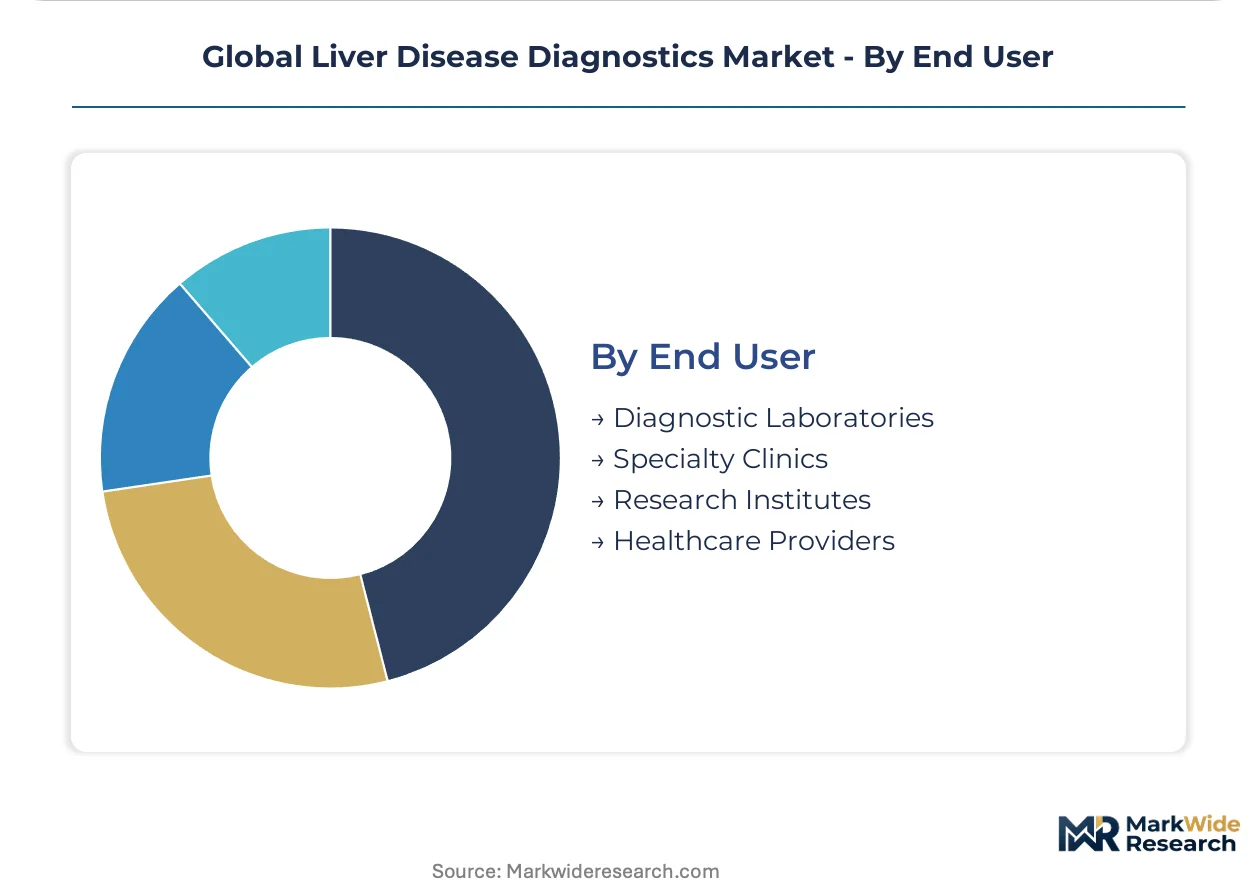
End User:
Customer type determines equipment specifications, service contract structures, and regulatory compliance requirements.
- Diagnostic Laboratories:High-throughput facilities integrate automated platforms with laboratory information systems. HL7 interface development challenges slow implementation timelines for novel biomarker reporting.
- Healthcare Providers:Hospital systems consolidate procurement across integrated delivery networks in Texas and California, shifting leverage toward vendors offering enterprise-wide service contracts.
- Specialty Clinics:Hepatology-focused practices prioritize elastography accuracy and point-of-care turnaround for patient retention.
- Research Institutes:Academic medical centers in the United States and Germany drive MR elastography adoption for NASH staging protocols.
Diagnostic laboratories handle the majority of throughput; healthcare providers are gaining share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations anchor United States market momentum, while EMA IVDR compliance reshapes European vendor economics. Japan's METI-backed elimination targets and India's tier-2 diagnostic gaps create divergent procurement profiles across major geographies.
United States
Hospital laboratories automate hepatitis screening workflows at scale. FDA premarket notification pathways compress approval timelines for novel fibrosis biomarker panels. Texas and California integrated delivery networks consolidate multi-site procurement, shifting leverage toward vendors with enterprise service contracts.
Germany
Specialist hepatology centers at university hospitals drive standardized elastography protocols. EMA In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for CE-marked liver biomarker kits. Munich and Heidelberg clusters anchor bulk imaging equipment procurement through harmonized fibrosis staging workflows.
Japan
METI hepatitis elimination targets fund national testing programs at prefectural health centers. PMDA regulatory frameworks govern molecular assay approvals for viral load quantification. Tokyo and Osaka metropolitan laboratories deploy high-throughput automated nucleic acid amplification platforms.
India
Hepatitis B and C prevalence in tier-2 cities exceeds diagnostic infrastructure capacity. CDSCO regulates in vitro diagnostic device imports and local manufacturing licensure. Maharashtra and Gujarat secondary urban centers generate demand for portable point-of-care platforms deployable outside metropolitan hospital networks.
China
NMPA oversees premarket approval for liver biomarker kits and imaging systems in the world's largest hepatitis patient population. Yangtze River Delta academic medical centers pilot artificial intelligence-enhanced elastography protocols. Shanghai and Hangzhou clusters concentrate molecular diagnostics manufacturing for domestic and export markets.
Global Liver Disease Diagnostics Market Competitive Landscape
Integrated imaging vendors and molecular assay specialists split the market between platform consolidation and test innovation. Siemens Healthcare GmbH anchors long-term service contracts with large health systems through imaging portfolio bundling. Abbott competes via point-of-care platforms that compress laboratory turnaround times. Thermo Fisher Scientific Inc. sustains R&D partnerships with academic medical centers for molecular assay development. Two competitive moves dominate: procurement consolidation across integrated delivery networks and regulatory pathway optimization for breakthrough device designations.
Among Germany-based healthcare conglomerates, Siemens Healthcare GmbH exemplifies the integrated-platform archetype through imaging and service contract bundling. Abbott and Thermo Fisher Scientific Inc. represent the specialized-diagnostics tier, with the former occupying point-of-care positioning and the latter anchoring molecular assay development partnerships. These three companies collectively illustrate how vendor strategy diverges between hardware-service integration and test-menu specialization.
| Leading Market Players |
|---|
| Siemens Healthcare GmbH |
| Abbott |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| Randox Laboratories Ltd. |
| Boston Scientific Corporation |
| Laboratory Corporation of America Holdings |
| Fujifilm Corporation |
| Horiba Medical |
| Others |
Supply & Pricing Matrix
Munich and Heidelberg imaging equipment clusters anchor global elastography manufacturing capacity, concentrating polymerase reagent production in German and United States hubs. This geographic clustering grants incumbent vendors pricing power over hospital procurement committees negotiating enterprise service contracts, while reagent supply bottlenecks compress margins for molecular assay developers dependent on cross-border logistics.
Pricing Analysis
Price spreads between German university hospital contracts and Indian tier-2 city deployments exceed threefold for comparable elastography systems. Three-tier pricing structure across premium, standard, and economy levels separates MRI-anchored academic centers from portable ultrasound clinics. Cost compression in point-of-care hepatitis panels is intensifying because Abbott and Siemens Healthcare GmbH compete for integrated delivery network volume commitments. Public health programs in Japan exhibit lowest price sensitivity; Indian diagnostic laboratories face acute budget constraints.
Supply Chain Analysis
Tariff exposure between Germany and United States polymerase reagent flows dominates supply chain risk assessment for hepatitis viral load assay manufacturers. Production concentrates in Germany, United States, and China for imaging systems, molecular platforms, and biochemical reagents respectively. Fluorescent probes, specialized optical components, and PCR enzymes draw from concentrated chemical synthesis clusters. Single-source vulnerability for elastography transducer arrays threatens equipment delivery timelines. Distribution runs through integrated delivery network procurement offices in Texas and California, GPO contracts for hospital laboratories, and CDSCO-licensed importers for Indian tier-2 markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across diagnostic modality selection—biochemical screening, elastography staging, molecular confirmation—creates niche specialization opportunities as hepatology centers resist one-size-fits-all platform consolidation.
For Market Incumbents: Pre-empt modality substitution by bundling imaging hardware with algorithm-as-a-service contracts for AI-enhanced fibrosis scoring. Anchor long-term reagent supply agreements with integrated delivery networks before PCR viral load testing commoditizes. Siemens Healthcare GmbH's service contract model with Texas health systems exemplifies the defensive playbook; Abbott's point-of-care turnaround advantage threatens laboratory-centric incumbents. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 hepatitis screening gap through portable ELISA platforms deployable outside metropolitan hospital networks. METI-funded Japanese prefectural health centers offer secondary penetration for high-throughput automated nucleic acid amplification systems. CDSCO import licensure partnerships with Maharashtra distributors provide the critical go-to-market angle for molecular assay newcomers. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-sized European assay developers struggling with EMA IVDR post-market surveillance documentation burdens. Five-to-ten year viability hinges on regulatory affairs infrastructure scale rather than test-menu breadth alone. The signal to watch is FDA breakthrough device designation velocity for blood-based fibrosis alternatives, which accelerates reimbursement code assignments and hospital capital allocation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Siemens Healthcare GmbH anchors multi-site service contracts through imaging portfolio bundling in Texas and California. |
| FDA Breakthrough Device Submission | Blood-based fibrosis biomarker panels compress approval timelines and accelerate Category III CPT code coverage. |
| Software Companion Development | AI-enhanced elastography algorithms enable recurring revenue atop hardware through machine learning fibrosis staging. |
| CE Marking Pathway Optimization | EMA IVDR clinical performance registries favor larger firms with dedicated regulatory infrastructure over mid-sized developers. |
| Reimbursement Strategy | Novel non-invasive scoring algorithms require proactive payer engagement before hospital procurement committees commit capital. |
Research Methodology
A standing panel of hepatology laboratory directors, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against operating reality. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement contract registries. Bottom-up instrument shipment tracking and top-down healthcare expenditure modeling were triangulated to anchor volume estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning diagnostic modality, technology tier, disease application, and end-user facility type. CAGRs were derived from fitted growth curves applied to instrument install bases and reagent consumption patterns. Forecast inputs incorporated METI elimination target funding trajectories, EMA IVDR implementation timelines, and integrated delivery network consolidation velocity in United States hospital systems.
Stress conditions across reagent supply disruptions, reimbursement code assignment delays, and modality substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway efficiency and procurement centralization momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Home Diagnostics Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Extraction Kits Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Global Urinalysis Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market