
 Complement C3 ELISA Kits Market | 2026-2036
Complement C3 ELISA Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Complement C3 ELISA Kits Market Insights
CE marking under the EU In Vitro Diagnostic Regulation is collapsing the supplier base for European distribution, forcing smaller distributors to consolidate or exit. Thermo Fisher leverages its pre-existing notified body relationships to sustain broad kit registration across member states. Abcam anchors its competitive position through specialized antibody portfolios that differentiate its C3 detection sensitivity from commoditized alternatives. Novus Biologicals competes by controlling direct-to-laboratory channels in North American academic medical centers.
Complement C3 ELISA Kits are quantitative immunoassay systems that detect human complement component C3 protein in serum, plasma, or other biological fluids using enzyme-linked immunosorbent methodology, typically achieving detection thresholds in the nanogram-per-milliliter range with colorimetric or chemiluminescent readout. These assays serve primarily as diagnostic and research tools for monitoring complement activation in autoimmune, infectious, and inflammatory conditions. Sandwich ELISA Kits occupy the dominant revenue position due to superior specificity for intact C3 versus cleavage products, while Chemiluminescent Assays represent the fastest-expanding technology segment as laboratories replace legacy colorimetric workflows for higher throughput and wider dynamic range. Research Institutions constitute a mature, price-sensitive end-user channel, whereas Clinical Laboratories concentrate margin pools through contracted volume commitments and integrated analyzer compatibility requirements.
The FDA's 21 CFR Part 820 quality system regulation and the EU IVDR's performance evaluation requirements shape kit validation burdens, with notified body backlogs currently extending conformity assessment timelines for mid-tier manufacturers. China's NMPA has tightened import registration for foreign IVD products, compelling overseas suppliers to establish local clinical evidence or partner with domestic license holders. Japan's PMDA maintains distinct reagent classification rules that segment market access between general laboratory use and clinical diagnostic claims. Stakeholders must monitor how divergent post-market surveillance obligations across these jurisdictions reshape localization investment priorities and partnership structures.
Market Dynamics
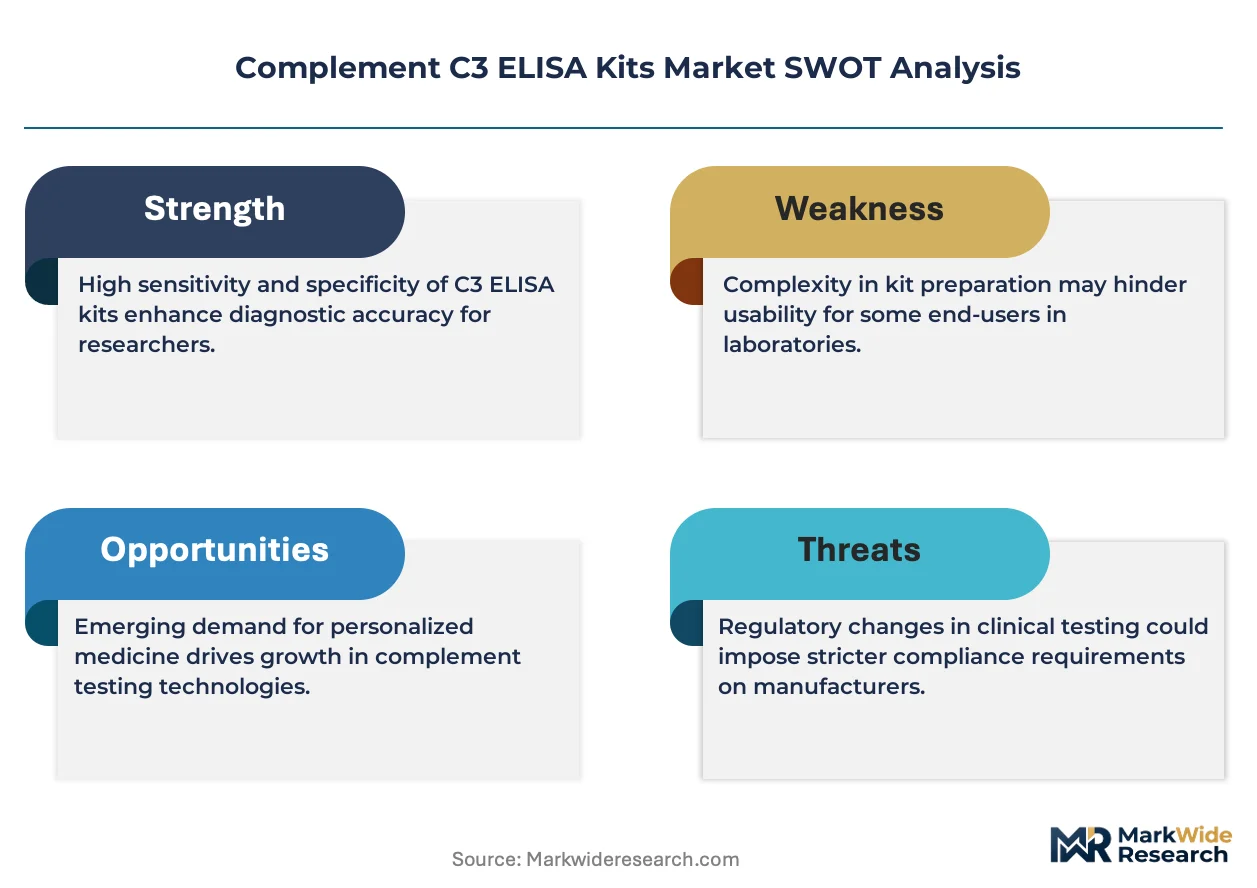
The Complement C3 ELISA Kits market is experiencing structural pressure from regulatory fragmentation as the EU IVDR transition and FDA quality system updates simultaneously reshape qualification requirements for immunoassay manufacturers.
Growth Catalysts
- Autoimmune disorder diagnostics expansion:Clinical laboratories in the United States and Germany are scaling C3 testing volumes for lupus and rheumatoid arthritis monitoring, creating sustained kit demand.
- EU IVDR compliance mandates:The European Union's In Vitro Diagnostic Regulation is accelerating replacement of legacy assays with certified alternatives, forcing laboratory equipment refresh cycles.
- Chemiluminescent detection adoption:Academic medical centers are replacing colorimetric workflows with higher-throughput chemiluminescent platforms, expanding addressable kit volumes.
Market Restraints
- Notified body capacity constraints:EU IVDR conformity assessment backlogs are extending certification timelines for mid-tier manufacturers, compressing revenue recognition windows.
- Antibody raw material concentration:Specialized C3 antibody supply concentrates among a limited set of hybridoma facilities, creating input cost volatility and qualification risk.
- Serum-based assay substitution:Multiplex protein array platforms are displacing single-analyte ELISA workflows in high-volume research settings, constraining price elasticity.
Strategic Opportunities
- China NMPA localization:Foreign manufacturers partnering with domestic license holders can access hospital procurement networks previously restricted by import registration barriers.
- Point-of-care C3 testing:Miniaturized ELISA platforms for emergency department complement activation screening represent an underdeveloped application with clinical validation potential.
- Japan PMDA reagent classification:The distinction between general laboratory use and clinical diagnostic claims creates channel segmentation opportunities for differentiated kit positioning.
Industry Challenges
- IVDR technical documentation:Performance evaluation requirements for clinical evidence generation demand specialized regulatory affairs capacity that smaller manufacturers struggle to staff.
- Analyzer integration complexity:Hospital laboratory information systems require customized protocol development for each automated platform, extending sales cycles and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complement C3 ELISA Kits Market |
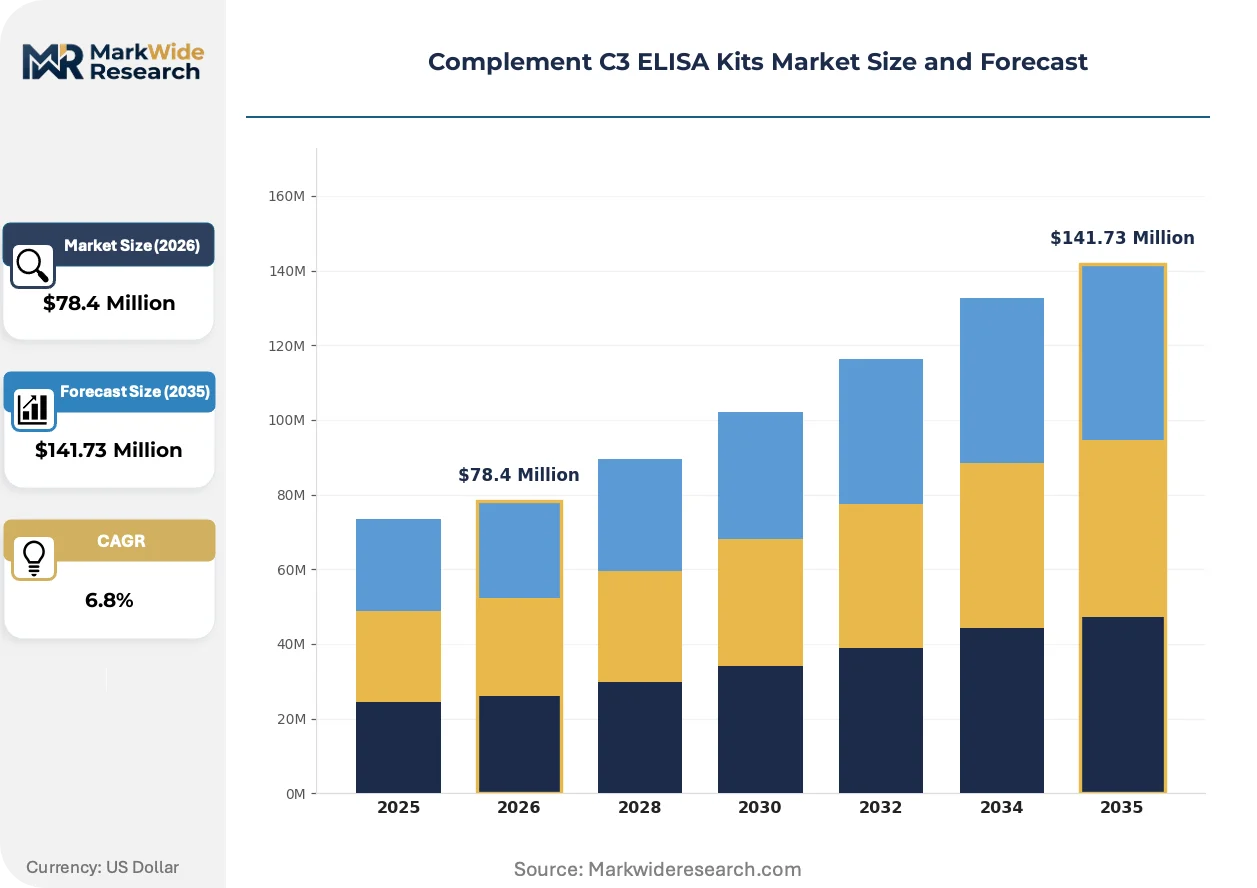
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandwich ELISA Kits, Competitive ELISA Kits, Direct ELISA Kits, Indirect ELISA Kits End User: Clinical Laboratories, Research Institutions, Diagnostic Centers, Pharmaceutical Companies Application: Autoimmune Disorders, Infectious Diseases, Cancer Research, Inflammation Studies Technology: Colorimetric Assays, Fluorescent Assays, Chemiluminescent Assays, Optical Detection |
| Companies Covered | Thermo Fisher, Abcam, Novus Biologicals, Molecular Innovations, Assay Genie, Creative Diagnostics, Abnova, Lepu (Beijing) Diagnostics, Wuhan Life Origin Biotech Joint Stock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complement C3 ELISA Kits Market Trends and Innovations
Detection methodology and regulatory compliance frameworks are actively restructuring competitive positioning in the Complement C3 ELISA Kits market, with technology substitution and jurisdictional divergence creating distinct capability requirements.
Chemiluminescent immunoassay platforms are bifurcating the installed base of clinical laboratories. These systems achieve wider dynamic range and superior sensitivity for C3 detection in nanogram-per-milliliter thresholds. Large hospital networks in Germany and the United States are prioritizing analyzer-compatible chemiluminescent kits for autoimmune panels. The technology is bifurcating procurement decisions between premium integrated platforms and standalone colorimetric alternatives, compressing margins for non-compatible suppliers.
REACH substance restriction updates and EU IVDR performance evaluation mandates are tightening material qualification and clinical evidence requirements for European distribution. Manufacturers must now document antibody reagent stability and lot-to-lot consistency across extended shelf-life claims. Kit suppliers with pre-existing notified body relationships are accelerating registration timelines, while competitors face extended conformity assessment delays that restrict market access through 2026.
Contracted volume commitments through group purchasing organizations are consolidating laboratory procurement decisions in the United States. Academic medical centers and hospital networks are unbundling reagent supply from analyzer maintenance agreements, creating direct negotiation leverage with kit manufacturers. This purchasing pattern shift is most visible in North American clinical laboratories, where integrated delivery networks now dominate C3 assay procurement and price benchmarking.
Complement C3 ELISA Kits Market Segmentation
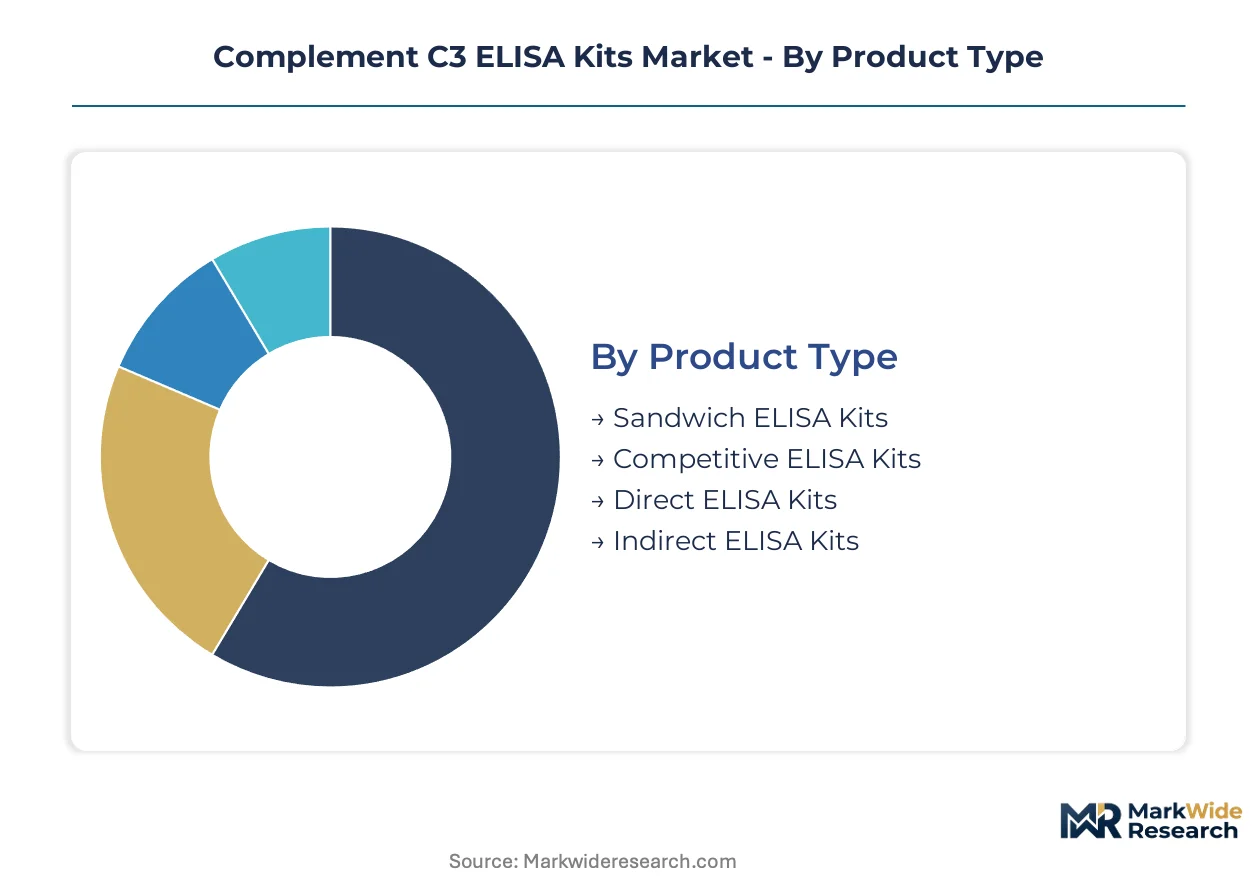
Segmentation in the Complement C3 ELISA Kits market reveals how procurement channels, detection technologies, and end-user workflows fragment demand across distinct capability tiers. Manufacturers must align kit specifications with laboratory infrastructure and regulatory claims to capture volume.
Product Type:
Kit formats flow through different distribution channels based on complexity and certification requirements, with specialized distributors handling high-sensitivity assays and general laboratory suppliers moving standardized formats.
- Sandwich ELISA Kits:These dual-antibody capture systems achieve superior specificity for intact C3 protein versus cleavage products. Demand concentrates in United States and Germany clinical laboratories where autoimmune panel standardization requires reliable quantification thresholds. Hospital networks favor these kits for lupus and rheumatoid arthritis monitoring protocols.
- Competitive ELISA Kits:Single-antibody competitive binding formats suit small-molecule complement metabolite detection. Academic medical centers in North America deploy these for research applications where cost sensitivity outweighs clinical diagnostic claims.
- Direct ELISA Kits:Single-step detection with enzyme-conjugated primary antibodies streamlines workflow for high-throughput screening.
- Indirect ELISA Kits:Secondary antibody amplification provides signal enhancement for low-abundance C3 detection in plasma samples.
By volume, Sandwich ELISA Kits lead. By growth pace, Competitive ELISA Kits are gaining share fastest in research settings.
End User:
Customer type determines margin structure, with contracted hospital networks extracting volume discounts and research buyers accepting premium pricing for specialized antibody portfolios.
- Clinical Laboratories:Hospital-based and independent diagnostic facilities in Germany and the United States drive kit procurement through integrated analyzer compatibility requirements. These laboratories concentrate margin pools through multi-year reagent supply agreements tied to automated platform maintenance contracts.
- Research Institutions:University and academic medical center laboratories represent mature, price-sensitive demand with fragmented purchasing authority across principal investigator grants.
- Diagnostic Centers:Outpatient specialty clinics process complement panels for rheumatology referrals.
- Pharmaceutical Companies:Drug developers use C3 assays for therapeutic mechanism validation and biomarker qualification in clinical trials.
Clinical Laboratories capture the largest revenue share. Research Institutions show the steepest expansion trajectory as grant funding for complement biology increases.
Application:
Disease area focus shapes kit performance requirements, with autoimmune applications demanding clinical-grade precision and cancer research tolerating broader dynamic range.
- Autoimmune Disorders:Systemic lupus erythematosus and rheumatoid arthritis monitoring represents the dominant clinical application. United States hospital laboratories scale C3 testing volumes for disease activity surveillance, with FDA-cleared kits required for diagnostic claims.
- Infectious Diseases:Sepsis and complement-mediated pathogenesis research drives assay development for acute-phase monitoring.
- Cancer Research:Tumor microenvironment studies employ C3 detection for complement evasion mechanism investigation.
- Inflammation Studies:Broad immunology research applications span cardiovascular and metabolic disease models.
Autoimmune Disorders anchor current volume. Infectious Diseases applications are climbing the fastest as sepsis biomarker panels expand.
Technology:
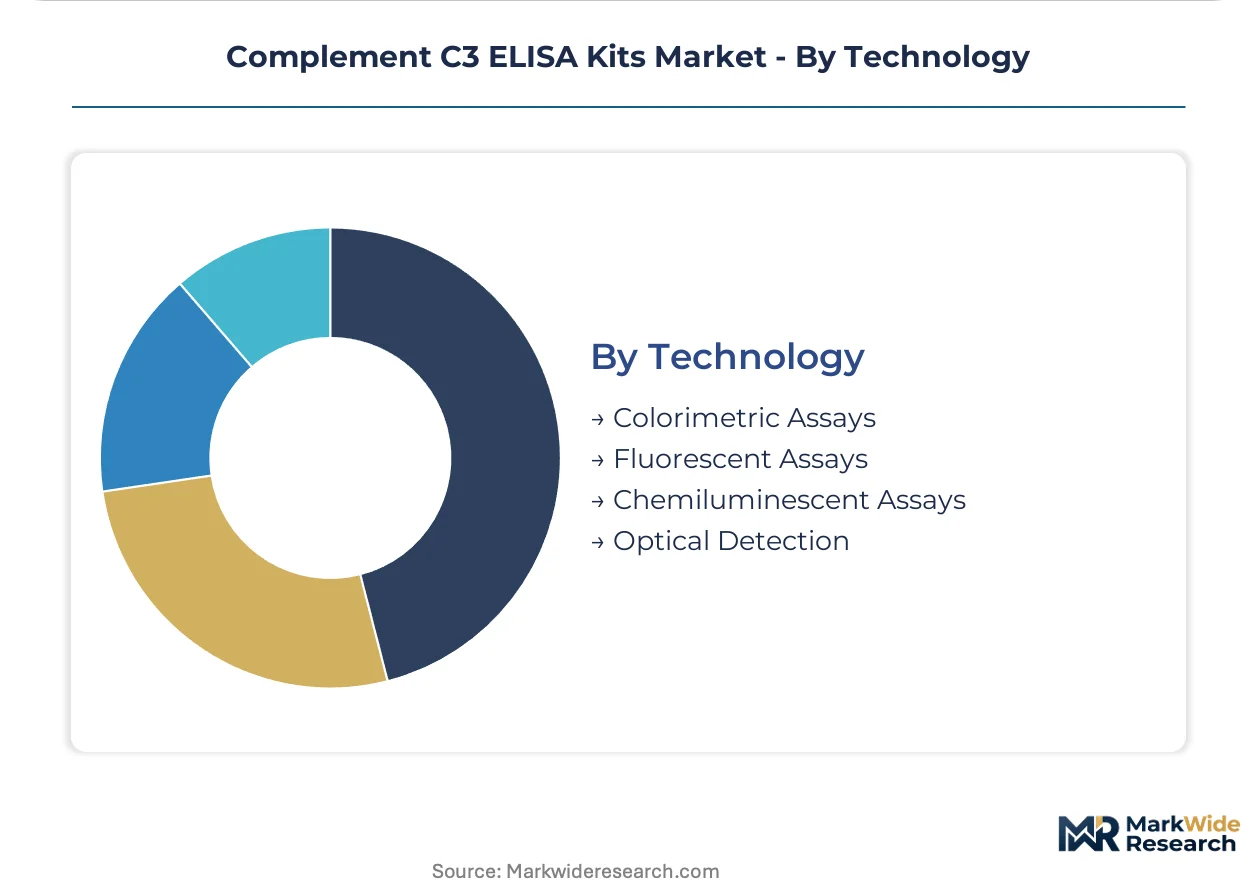
Detection methodology bifurcates procurement between legacy colorimetric installations and chemiluminescent platform upgrades, with fluorescence occupying niche multiplex positions.
- Chemiluminescent Assays:Enzyme-triggered light emission achieves widest dynamic range and lowest detection limits for C3 quantification. Large hospital networks in Germany prioritize analyzer-compatible chemiluminescent kits for autoimmune panel consolidation.
- Colorimetric Assays:Horseradish peroxidase with TMB substrate remains prevalent in research laboratories with legacy microplate readers.
- Fluorescent Assays:Fluorophore-conjugated detection enables multiplex protein array integration.
- Optical Detection:Advanced photomultiplier and CCD-based readout systems support high-density screening formats.
Colorimetric Assays retain installed base leadership. Chemiluminescent Assays represent the fastest-growing trajectory as laboratories replace aging equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution of temperature-sensitive immunoassay reagents, while direct air freight corridors from Shanghai Pudong International Airport sustain Asia-Pacific supply velocity for diagnostic kit manufacturers.
United States
Academic medical centers in Boston and the Research Triangle Park scale C3 testing volumes for lupus monitoring protocols. FDA's 21 CFR Part 820 quality system regulation mandates extensive kit validation documentation for diagnostic claims. The Greater Boston biotech cluster concentrates contract research organizations that generate preclinical demand for complement assays.
Germany
Centralized hospital networks in Baden-Württemberg and Bavaria drive analyzer-compatible chemiluminescent kit procurement for autoimmune panels. EU IVDR performance evaluation requirements extend conformity assessment timelines for notified body certification. The Rhine-Main metropolitan region hosts diagnostic distributors consolidating reagent supply contracts for multi-site laboratory networks.
China
Domestic license holders in Shanghai and Suzhou facilitate NMPA registration for foreign IVD suppliers seeking hospital procurement access. China's tightened import registration rules compel overseas manufacturers to establish local clinical evidence partnerships. The Yangtze River Delta biopharmaceutical corridor concentrates hybridoma facilities producing specialized C3 antibodies.
Japan
Academic research institutes in Osaka and Tokyo deploy C3 assays for complement biology investigations. PMDA's distinct reagent classification rules segment market access between general laboratory use and clinical diagnostic claims. The Kansai Science City cluster anchors translational research programs generating sustained kit demand.
United Kingdom
NHS hospital laboratories in London and the Oxford-Cambridge arc integrate C3 testing into rheumatology referral pathways. MHRA's post-Brexit regulatory framework maintains alignment with EU IVDR technical standards for IVD conformity. The Golden Triangle research cluster sustains pharmaceutical contract research demand for biomarker qualification assays.
Complement C3 ELISA Kits Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification capacity, creating a tiered structure where scale-driven multinationals and antibody-focused boutiques occupy distinct competitive positions. The vendor base concentrates around three strategic archetypes: diversified life science conglomerates with pre-existing notified body relationships, specialized antibody developers with differentiated detection sensitivity, and regional distributors controlling direct-to-laboratory channels. Dominant competitive moves include M&A activity targeting hybridoma technology assets and strategic partnerships with domestic license holders for NMPA market access.
Within the diversified conglomerate tier, Thermo Fisher leverages its established regulatory affairs infrastructure to sustain broad kit registration across EU member states. Abcam occupies a position exemplifying the specialized antibody developer archetype, anchoring competitive differentiation through detection sensitivity portfolios. Novus Biologicals represents the direct-channel distributor model, sitting within North American academic medical center procurement networks. These three patterns illustrate how regulatory capacity, technical specialization, and channel control constitute the primary vectors of competitive positioning.
| Leading Market Players |
|---|
| Thermo Fisher |
| Abcam |
| Novus Biologicals |
| Molecular Innovations |
| Assay Genie |
| Creative Diagnostics |
| Abnova |
| Lepu (Beijing) Diagnostics |
| Wuhan Life Origin Biotech Joint Stock |
| Others |
Pricing and Supply Chain Analysis
Ninety-day notified body backlogs for EU IVDR conformity assessments compress inventory turnover for kit manufacturers and amplify pricing power for suppliers with pre-cleared antibody portfolios. This lead-time environment concentrates margin capture among hybridoma facility operators in Germany and the United States while forcing smaller distributors toward volume-discount surrender.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic kits from research-grade assays and unvalidated bulk formats. Price differentiation rests on CE marking tier and analyzer compatibility certification, with clinical laboratories in Germany extracting steepest volume discounts through GPO-negotiated reagent supply agreements. Cost compression in the research-grade tier intensifies as multiplex protein arrays displace single-analyte workflows. Academic medical centers exhibit highest price sensitivity; hospital networks with integrated analyzer contracts show lowest.
Supply Chain Analysis
Inbound logistics costs from Shanghai Pudong International Airport fluctuate with cold-chain container availability for temperature-sensitive antibody reagents. Manufacturing concentrates in China, Germany, and the United States, with specialized C3 monoclonal antibody production anchored in Yangtze River Delta hybridoma facilities. Raw material dependencies include fetal bovine serum, enzyme conjugates, and microplate substrates. Single-source vulnerability characterizes high-affinity antibody clone supply. Distribution runs through diagnostic distributors with notified body relationships and direct-to-laboratory channel specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory affairs capacity for IVDR performance evaluation documentation represents the critical scarce asset determining market access velocity. Manufacturers without dedicated clinical evidence generation teams face extended conformity assessment delays that compress revenue recognition windows.
For Market Incumbents: Consolidate hybridoma technology assets to secure captive antibody supply and defend against input cost volatility from specialized clone providers. Accelerate notified body relationship investment to sustain broad kit registration across EU member states before backlog compression extends competitor exclusion. Prioritize analyzer protocol development capacity to shorten hospital laboratory implementation timelines. For New Entrants and Emerging Players: Custom protocol development for legacy microplate reader installations offers under-served entry points where incumbents prioritize automated platform compatibility. Target research institutions in Japan with PMDA general laboratory use classification kits as the most penetrable segment avoiding clinical diagnostic claims burden. Deploy direct academic channel relationships to bypass distributor consolidation barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemiluminescent platform development as laboratories demand wider dynamic range detection capabilities. Five-to-ten year viability favors acquisition targets with pre-existing notified body relationships and specialized C3 antibody portfolios over undifferentiated kit assemblers. Monitor EU IVDR certificate issuance velocity as inflection indicator for competitive access windows.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Investment | EU IVDR certificate issuance velocity determines market access timing for kit registration. |
| Hybridoma Technology Acquisition | Specialized C3 monoclonal antibody supply concentrates among limited clone developers. |
| Analyzer Protocol Development | Hospital laboratory information systems require customized integration for each automated platform. |
| Domestic License Holder Partnership | China NMPA registration compels foreign manufacturers to establish local clinical evidence partnerships. |
| Point-of-Care Platform Miniaturization | Emergency department complement activation screening represents underdeveloped application with validation potential. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs directors at IVD manufacturers, hospital laboratory managers, diagnostic distributor procurement leads, and academic principal investigators, then refined against secondary validation from FDA 510(k) filings, EU IVDR technical documentation databases, EMA IVD guidance publications, and customs import records for antibody reagents. Bottom-up kit volume estimates triangulated with top-down market sizing from identified manufacturer revenue disclosures.
Variance decomposition across product type, detection technology, end-user channel, and geographic regulatory cluster shaped the analytical framework. Modeled segmentation captured sandwich versus competitive ELISA formats, chemiluminescent versus colorimetric detection, clinical laboratory versus research institution demand, and EU IVDR versus FDA 21 CFR Part 820 certification pathways. CAGRs derived from segment-level volume projections weighted by price tier concentration.
Forecasts assume regulatory continuity in EU IVDR implementation and FDA quality system enforcement; material policy shifts would require re-modeling. Antibody raw material supply disruptions, notified body capacity constraints, or multiplex platform substitution acceleration represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Diabetes Testing System Market
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Lipid Panel Test Market