
 Dental 3D Scanners Market | 2026-2036
Dental 3D Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Dental 3D Scanners Market Analysis
Subscription-based software tiers for cloud storage and AI-powered treatment planning is expanding the recurring revenue base for hardware vendors. 3Shape A/S leverages its open-platform TRIOS ecosystem to sustain high switching costs among dental clinics. Planmeca anchors the Nordic market through integrated CAD/CAM workflows that combine imaging with chairside milling. Dentsply Sirona dominates the North American installed base with extensive dealer service networks.
Dental 3D scanners are non-contact optical measurement instruments that capture surface geometry of oral structures at resolutions typically below 20 micrometers, generating digital impressions that replace conventional elastomeric molds for restorative and orthodontic fabrication. Intraoral scanners lead product type demand due to chairside convenience and patient comfort advantages, while laboratory scanners retain margin pools in high-volume prosthodontic production. Structured light scanning technology competes with laser triangulation for accuracy in complex subgingival margin capture, and orthodontic practices represent the fastest-growing end user segment as clear aligner therapy expands beyond traditional specialty boundaries.
FDA 510(k) premarket notification and EU MDR conformity assessment shape product development timelines and clinical validation requirements for scanner manufacturers seeking multi-regional market access. ISO 12836 standardization for digitizing accuracy provides the metrological benchmark that purchasers use to compare intraoral and desktop scanner performance claims. Stakeholders must monitor evolving reimbursement codes for digital impression-taking as payors recalibrate fee schedules between conventional and chairside workflows.
Market Dynamics
Orthodontic practices are consolidating around digital workflows, compressing scanner replacement cycles from seven years to four as clear aligner therapy scales beyond traditional specialty boundaries. This demand concentration is reshaping vendor R&D priorities and service model economics.
Growth Catalysts
- Clear Aligner Therapy Expansion:General dentistry practices in the United States and Germany are adopting chairside scanning for in-house aligner production, bypassing traditional orthodontic referrals.
- EU MDR Accuracy Mandates:The Medical Device Regulation's tightened validation requirements for intraoral digitizing precision is elevating ISO 12836 compliance to a competitive differentiator in European procurement decisions.
- Cloud-Enabled Treatment Planning:Subscription software tiers for AI-powered case analysis are converting one-time hardware sales into recurring revenue streams among multi-location dental service organizations.
Market Restraints
- Precision Optics Cost Volatility:Structured light projector components and CMOS sensors face supply concentration in East Asian manufacturing clusters, compressing hardware margins during input price spikes.
- Subgingival Margin Capture Limitations:Laser triangulation systems struggle with bleeding tissue and deep margin lines in complex crown preparations, preserving demand for conventional elastomeric impressions in prosthodontic cases.
- FDA 510(k) Pathway Friction:Premarket notification timelines for novel scanning modalities average eighteen months, delaying revenue recognition for manufacturers pursuing multi-regional clearance strategies.
Strategic Opportunities
- Indian Dental Clinic Modernization:The country's national pharmaceutical regulator CDSCO is streamlining medical device import pathways, opening procurement channels for mid-tier scanner vendors in tier-two cities.
- Teledentistry Integration:Remote orthodontic monitoring platforms are creating demand for patient-owned intraoral scanning peripherals that sync with cloud-based treatment tracking systems.
- Japan's METI Digital Health Incentives:Subsidy programs for small-clinic IT infrastructure are accelerating scanner adoption among independent practitioners in Osaka and Nagoya dental clusters.
Industry Challenges
- Cross-Platform Data Interoperability:Proprietary file formats from dominant hardware ecosystems create friction when integrating scans with third-party CAD/CAM milling systems or aligner fabrication networks.
- Clinical Workflow Retraining Burden:Chairside scanning requires modified moisture control techniques and retraction protocols that extend procedure times during initial adoption phases among established practitioners.
- Cybersecurity Certification Overhead:HIPAA compliance for cloud-connected devices and EU GDPR data localization requirements are extending product development cycles and inflating quality assurance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental 3D Scanners Market |
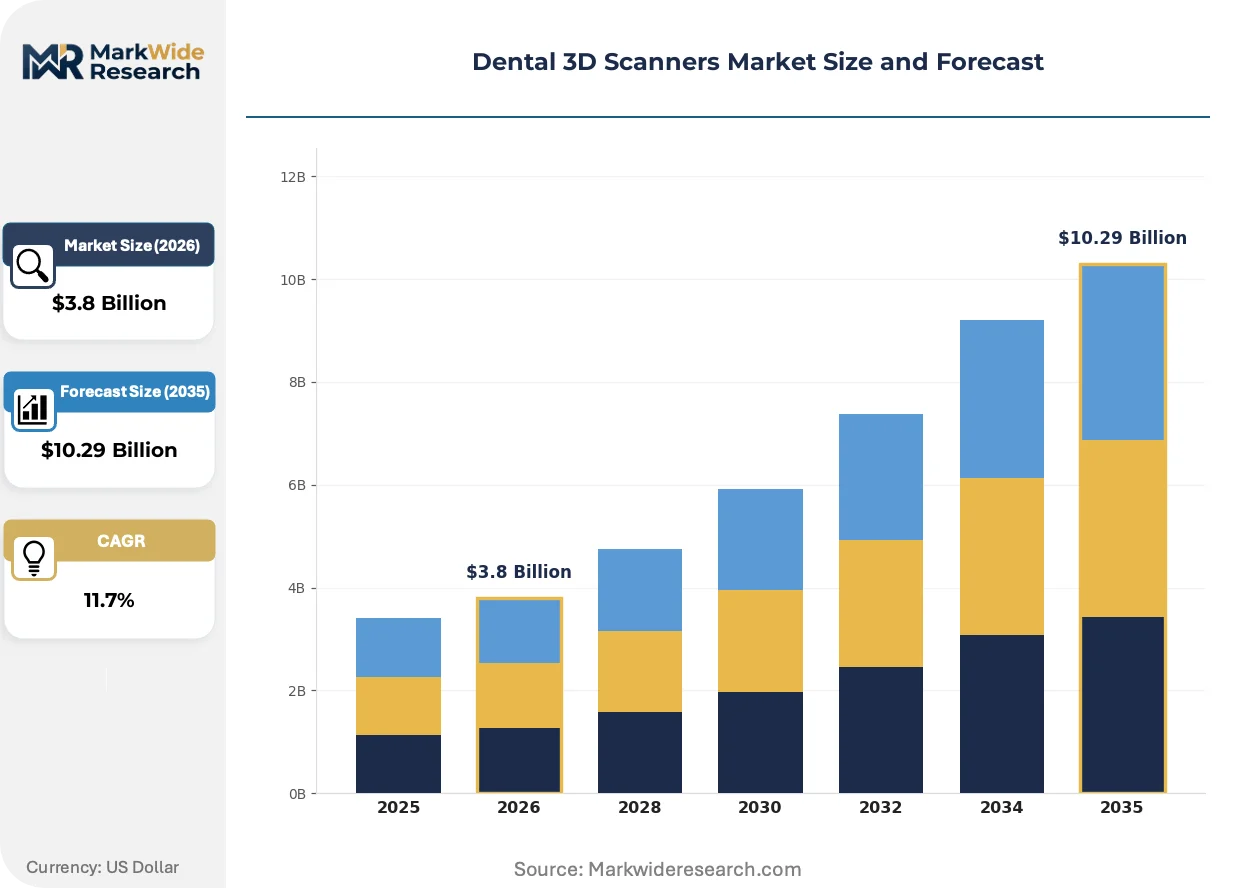
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Scanners, Desktop Scanners, Portable Scanners, Laboratory Scanners Technology: Laser Scanning, Optical Scanning, Structured Light Scanning, Triangulation End User: Dental Clinics, Dental Laboratories, Orthodontic Practices, Research Institutions Application: Crown & Bridge, Implantology, Orthodontics, Prosthodontics |
| Companies Covered | Planmeca, Midmark Corporation, 3Shape A/S, MEDIT Corp., SHINING 3D, Dentsply Sirona, Align Technology, Inc., Amann Girrbach AG, Carestream Dental LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental 3D Scanners Market Emerging Trajectories
Scanner hardware is converging with AI-driven diagnostic software, compressing the traditional separation between impression capture and treatment planning into unified chairside workflows. This integration is redefining competitive differentiation beyond raw digitizing accuracy.
Photogrammetry-based full-arch scanning is absorbing marginal cases that previously required laboratory-grade desktop systems. Large-group orthodontic practices in the United States are deploying these units for same-day aligner fitting, collapsing the traditional two-appointment model into single-visit workflows. The technology is absorbing market share from conventional intraoral scanners in high-volume clear aligner production environments.
The EU MDR's post-market surveillance requirements for active implantable devices are extending to intraoral scanners with integrated diagnostic AI, mandating annual clinical performance reporting. Manufacturers targeting European market access must now maintain vigilance systems that track accuracy degradation in clinical use. German notified bodies are interpreting these provisions most stringently, creating a two-speed regulatory landscape across the continent.
After-sales service unbundling is disrupting traditional hardware-plus-warranty bundling as dental service organizations negotiate direct maintenance contracts with third-party technical providers. Independent repair networks in Texas and Bavaria are capturing calibration and optical cleaning revenue that previously flowed to original equipment manufacturers. This fragmentation is most advanced among multi-location chains operating standardized scanner fleets across fifty-plus practice sites.
Dental 3D Scanners Market Segmentation
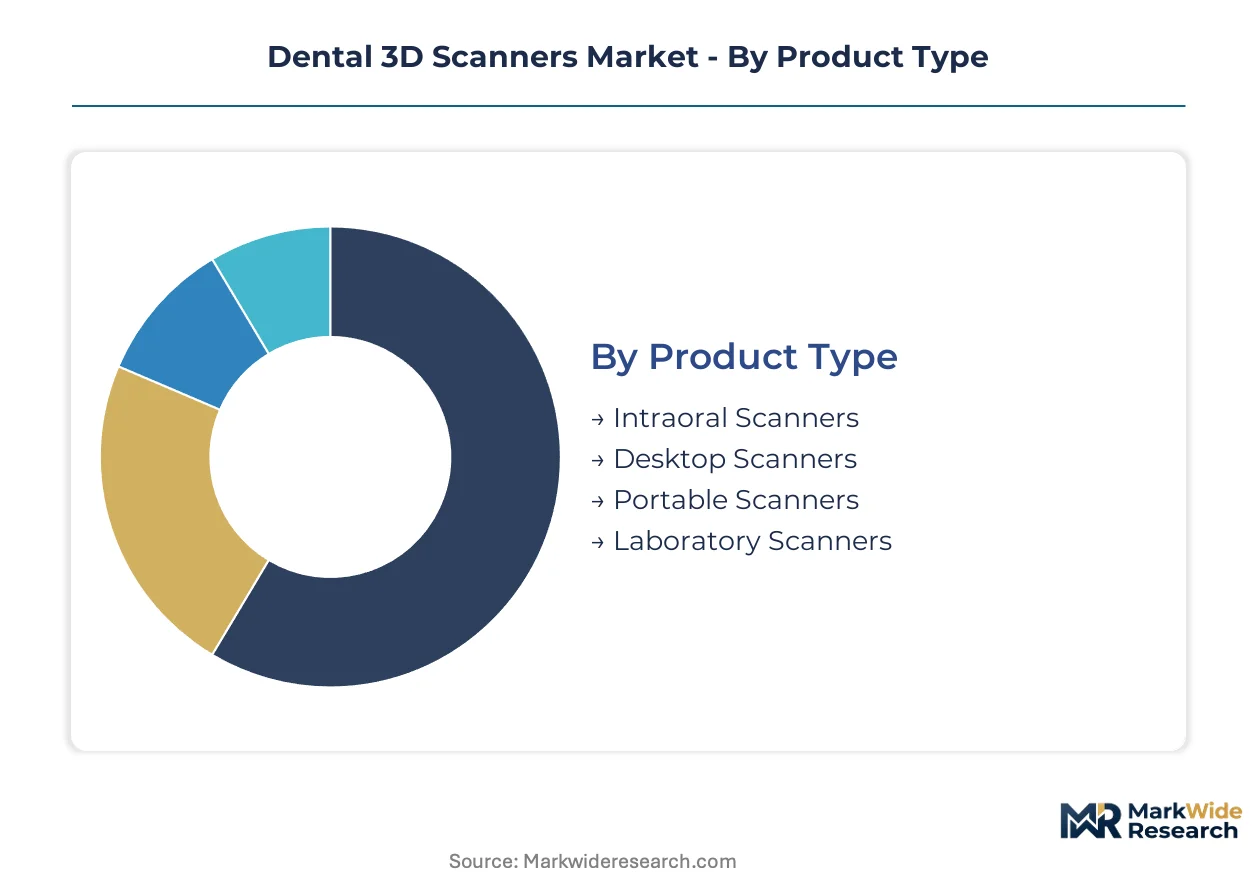
Segmentation in dental 3D scanning reveals divergent margin structures across hardware tiers and clinical workflows. Procurement patterns cluster around chairside convenience versus laboratory throughput, with technology choices directly constraining reimbursement eligibility and service contract economics.
Product Type:
Volume deployment concentrates in mid-range chairside units, while premium pricing attaches to laboratory-grade systems with sub-10-micron accuracy certification.
- Intraoral Scanners:Handheld optical devices capture direct digital impressions at chairside, eliminating elastomeric mold discomfort. Demand concentrates in United States and German dental service organizations consolidating procurement across multi-location orthodontic practices for same-day aligner workflows.
- Desktop Scanners:Laboratory-grade systems process gypsum casts and impression materials with photogrammetric arrays for full-arch prosthodontic production. German and Chinese dental laboratories anchor demand as clear aligner manufacturing scales beyond traditional specialty boundaries.
- Portable Scanners:Battery-powered units enable mobile dentistry deployments in rural United States markets and Indian tier-two cities where fixed infrastructure remains limited.
- Laboratory Scanners:High-throughput systems integrate with CAD/CAM milling workflows for crown-and-bridge fabrication in centralized production facilities.
Mature deployment sits with Laboratory Scanners. Newer deployment is concentrated in Intraoral Scanners.
Technology:
Accuracy certification under ISO 12836 separates premium-validated modalities from cost-optimized alternatives in procurement decisions.
- Laser Scanning:Triangulation-based systems project coherent light patterns for subgingival margin detection in complex crown preparations. United States prosthodontic practices retain demand despite bleeding tissue interference constraints.
- Structured Light Scanning:Pattern projection systems achieve faster capture sequences for orthodontic full-arch scanning. Chinese and German manufacturers dominate component supply for these systems.
- Optical Scanning:Passive stereo vision configurations serve entry-level intraoral devices in price-sensitive Indian and Brazilian clinic markets.
- Triangulation:Active stereo systems with dual-camera arrays support laboratory-grade accuracy requirements for implantology superstructure fabrication.
Established validation sits with Laser Scanning. Expanding most quickly is Structured Light Scanning.
End User:
Customer type determines service contract structures, with dental service organizations negotiating fleet-wide maintenance unbundling.
- Dental Clinics:General practice settings in United States and Germany deploy chairside scanners for in-house aligner production, bypassing traditional orthodontic referrals.
- Orthodontic Practices:Specialty clinics represent the steepest expansion trajectory as clear aligner therapy scales beyond traditional specialty boundaries into general dentistry.
- Dental Laboratories:Centralized production facilities in China and Germany integrate scanning with automated milling for high-volume prosthodontic output.
- Research Institutions:Academic dental schools in Japan and United States drive validation studies for FDA 510(k) and EU MDR compliance pathways.
Volume concentration sits with Dental Clinics. Margin expansion concentrates in Orthodontic Practices.
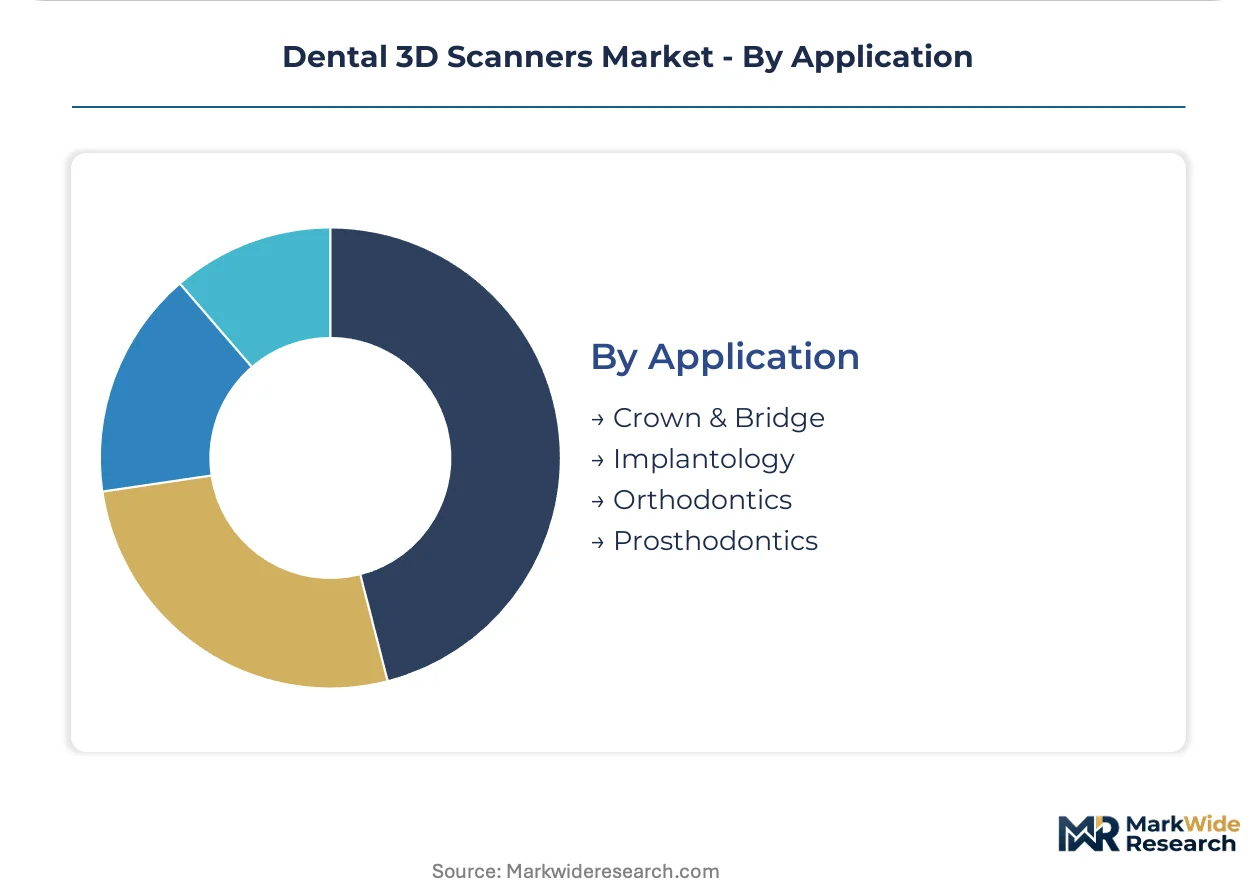
Application:
Clinical indication dictates accuracy thresholds and reimbursement code eligibility in procurement specifications.
- Orthodontics:Full-arch scanning for clear aligner therapy compresses appointment sequences from multiple visits to single-chair workflows. United States and German practices lead deployment.
- Implantology:Sub-10-micron accuracy requirements for abutment and superstructure fabrication preserve premium pricing for validated laboratory systems.
- Crown & Bridge:Single-unit restorative scanning faces reimbursement compression as payors recalibrate fee schedules between conventional and digital impression-taking.
- Prosthodontics:Complex multi-unit cases retain demand for conventional elastomeric impressions where subgingival margin capture exceeds current optical system capabilities.
Revenue scale sits with Crown & Bridge. Gaining share fastest is Orthodontics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in China and Germany supply precision optics to assembly operations in the United States and Western Europe. Consumption concentrates where dental service organizations consolidate procurement across multi-location practices.
United States
Dental service organizations in Texas and Florida negotiate fleet-wide scanner procurement for clear aligner workflows. FDA 510(k) premarket notification timelines average eighteen months for novel scanning modalities. The Dallas-Fort Worth metroplex hosts independent repair networks capturing calibration revenue from standardized scanner fleets.
Germany
German orthodontic practices deploy chairside scanning for in-house aligner production, bypassing traditional referrals. EU MDR conformity assessment mandates ISO 12836 accuracy validation for intraoral digitizing precision. The Bavarian dental cluster around Munich anchors laboratory-grade CAD/CAM integration for high-volume prosthodontic output.
China
Chinese dental laboratories scale clear aligner manufacturing beyond traditional specialty boundaries, driving structured light scanner demand. The country's national pharmaceutical regulator NMPA streamlines medical device import pathways for mid-tier vendors. Shanghai and Shenzhen manufacturing clusters dominate CMOS sensor and projector component supply for global hardware assembly.
Japan
Independent practitioners in Osaka and Nagoya dental clusters accelerate scanner adoption through METI subsidy programs for small-clinic IT infrastructure. PMDA consultation pathways shape clinical validation requirements for manufacturers seeking market access. The Kanto region around Tokyo hosts academic dental schools driving FDA 510(k) and EU MDR compliance validation studies.
India
Tier-two cities see rising procurement of portable battery-powered scanners where fixed infrastructure remains limited. CDSCO streamlines medical device import pathways, opening channels for mid-tier hardware vendors. Maharashtra and Gujarat dental clusters modernize through mobile dentistry deployments serving rural patient populations.
Dental 3D Scanners Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across scanner hardware and software layers. The vendor base organizes around three tiers: integrated imaging-milling ecosystems, standalone intraoral specialists, and laboratory-grade desktop manufacturers. Strategic differentiation flows from open-platform versus closed-system architectures. Competitive moves center on dealer network expansion for aftermarket service capture and subscription software tiering for recurring revenue conversion.
Within the integrated ecosystem tier, Planmeca anchors Nordic market positioning through combined imaging and chairside milling workflows. 3Shape A/S exemplifies the open-platform archetype, sustaining high switching costs among dental clinics through its TRIOS ecosystem breadth. Dentsply Sirona occupies the scale-driven position in North American installed base maintenance through extensive dealer service networks.
| Leading Market Players |
|---|
| Planmeca |
| Midmark Corporation |
| 3Shape A/S |
| MEDIT Corp. |
| SHINING 3D |
| Dentsply Sirona |
| Align Technology, Inc. |
| Amann Girrbach AG |
| Carestream Dental LLC |
| Others |
Supply Flow & Price Mechanics
Optical engineering talent clusters in German precision manufacturing regions and Chinese component hubs, with labor-cost differentials between these centers widening spreads between premium validated systems and mid-tier alternatives. Pricing stratifies across ISO 12836-certified laboratory scanners, chairside intraoral units, and entry-level portable devices as dental service organizations consolidate procurement leverage.
Pricing Analysis
Margin tightening in mid-tier hardware reflects CMOS sensor cost volatility and subscription software unbundling pressures. Three-tier pricing structure across premium, standard, and economy levels separates laboratory-grade photogrammetry systems with sub-10-micron accuracy from chairside structured light scanners and entry-level optical devices. Price differentiation hinges on ISO 12836 certification grade and after-sales service bundling. Cost compression accelerates in standard-tier units as Chinese manufacturers scale component supply. Dental clinics in tier-two Indian cities exhibit highest price sensitivity, while German orthodontic practices demonstrate lowest sensitivity due to METI-equivalent subsidy absorption and aligner workflow revenue offsets.
Supply Chain Analysis
Refurbishment flows for precision optics and calibration services are capturing aftermarket revenue from original equipment manufacturers through independent repair networks in Texas and Bavaria. Component manufacturing concentrates in China, Germany, and Japan, with Shanghai and Shenzhen clusters dominating CMOS sensor and structured light projector supply. Assembly draws from Taiwanese optical foundries and German precision mechanics. Raw material dependencies span rare-earth phosphors for laser diodes, high-purity glass substrates, and specialized polymer housings. Single-source vulnerability concentrates in East Asian semiconductor lithography for sensor fabrication. Distribution runs through dealer service networks in North America and direct procurement channels for European dental service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is racing toward vertical integration as vendors capture cloud-enabled treatment planning revenue and control precision optics supply. Players are pursuing downstream software subscription tiers and upstream component manufacturing to defend margin pools.
For Market Incumbents: Hedge against independent repair network fragmentation by unbundling after-sales service contracts for multi-location dental service organizations. Lock in switching costs through open-platform ecosystem breadth spanning CAD/CAM integration and AI-powered diagnostics. Defend against mid-tier Chinese entrants by accelerating EU MDR compliance investments that elevate validation barriers. For New Entrants and Emerging Players: Enter via India's tier-two dental clinic modernization wave as CDSCO streamlines import pathways for portable battery-powered scanners. Target teledentistry integration for patient-owned peripherals syncing with remote orthodontic monitoring platforms. Pursue white-label partnerships with cloud-based treatment planning software vendors to bypass established dealer networks. For Investors and Strategic Acquirers: Re-rating potential sits with software-forward scanner vendors given recurring revenue conversion and AI diagnostic integration catalysts. Long-term viability favors archetypes controlling both hardware validation pathways and cloud treatment planning infrastructure. Monitor FDA 510(k) clearance velocity and EU MDR notified body backlog as inflection indicators for revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Software Integration | Unifies impression capture and treatment planning into single-chair workflows for orthodontic practices. |
| EU MDR Conformity Investment | Secures market access as German notified bodies interpret accuracy mandates most stringently. |
| Cloud Subscription Tiering | Converts one-time hardware sales into recurring revenue streams among dental service organizations. |
| Independent Service Network Partnership | Captures calibration and refurbishment revenue from standardized scanner fleets in Texas and Bavaria. |
| Portable Scanner Development | Addresses infrastructure gaps in Indian tier-two cities and rural United States mobile dentistry deployments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with orthodontic practice owners, dental laboratory procurement managers, biomedical engineers at academic institutions, GPO contracts specialists, and aftermarket service technicians. Secondary sources encompass FDA 510(k) premarket notification databases, EU MDR notified body conformity assessments, ISO 12836 metrological validation studies, and hospital procurement databases. Bottom-up unit deployment estimates triangulated against top-down market sizing from component supply chain analysis.
Granularity-level modeling addressed product type, technology modality, end-user archetype, and application indication across the projection horizon. The analytical framework incorporated dental service organization consolidation patterns, clear aligner therapy penetration curves, and reimbursement code evolution for digital impression-taking. CAGRs derived from regression analysis of historical scanner replacement cycle compression and orthodontic practice digital workflow adoption rates. Industry-specific inputs included ISO 12836 accuracy certification thresholds and EU MDR post-market surveillance requirements.
Revisions become necessary when regulatory clearance timelines extend beyond historical averages, component supply disruptions alter hardware margin structures, or reimbursement frameworks shift between conventional and digital impression-taking codes. Practitioners should monitor FDA 510(k) backlog indicators, EU MDR notified body capacity constraints, and cloud-connected device cybersecurity certification requirements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
US Orthodontics Market
Dental Devices
Dental Handpieces Market
Dental Devices
Dental Restoration Market
Dental Devices
Dental Impression System Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Chile Dental Devices Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Europe Dental Implants and Prosthetics Market