
 ENT Diagnostic Devices Market | 2026-2036
ENT Diagnostic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
ENT Diagnostic Devices Market Analysis
Hospital procurement consortiums is rewriting how ENT diagnostic devices reach end users, with group purchasing organizations consolidating vendor lists and squeezing out regional distributors. Medtronic plc leverages its broad surgical portfolio to bundle diagnostic and therapeutic systems, securing multi-year supply contracts with integrated delivery networks. Olympus Corporation anchors its position through gastrointestinal endoscopy cross-selling into ENT suites, while Karl Storz SE & Co. KG specializes in rigid endoscope craftsmanship that commands premium placement in academic medical centers.
ENT diagnostic devices comprise instruments for visualizing, measuring, and recording conditions of the ear, nose, and throat, typically incorporating fiber-optic or digital imaging sensors with resolutions exceeding 720p and working channel diameters of 2-4 millimeters for instrument passage. These devices serve otolaryngologists, audiologists, and speech pathologists in identifying structural abnormalities, hearing loss patterns, and airway obstructions that guide surgical planning or medical management. Endoscopes capture the largest revenue pool due to replacement cycles driven by optical degradation and infection control protocols, while wireless technology segments are expanding fastest as battery efficiency and Bluetooth latency improve enough to displace cabled systems in clinic settings. Portable devices concentrate margin in battery and miniaturization engineering, whereas analogue audiometer lines face structural decline as digital platforms integrate with electronic health record systems.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for ENT device manufacturers, with notified body capacity bottlenecks in Europe extending conformity assessment durations. The central bank and national pharmaceutical regulator in India are streamlining import licensing for diagnostic equipment, creating alternative pathways for manufacturers facing Western regulatory congestion. Stakeholders must monitor how FDA software-as-a-medical-device guidance applies to AI-enhanced endoscopy image analysis tools, as algorithm-based diagnostic support functions trigger novel premarket review categories that could reshape competitive entry barriers.
Market Dynamics
Hospital procurement consortiums are consolidating vendor lists and squeezing out regional distributors, while wireless-enabled otoscopes and digital endoscopes displace cabled systems in ambulatory settings. FDA 510(k) clearance pathways and EU MDR conformity requirements are accelerating product registration complexity, compressing development timelines for manufacturers.
Growth Catalysts
- EU MDR technical documentation obligations:European notified body capacity bottlenecks are extending conformity assessment durations, creating first-mover advantages for manufacturers with established quality management systems.
- Ambulatory surgical center densification:Germany, the United States, and Japan are expanding outpatient ENT procedure volumes, driving demand for portable diagnostic platforms with electronic health record integration.
- Battery efficiency improvements:Lithium-polymer cell chemistry advances and Bluetooth latency reductions are enabling wireless endoscope deployments in clinic settings previously served by cabled systems.
Market Restraints
- Optical component supply concentration:High-resolution CMOS sensors and fiber-optic bundles depend on specialized Japanese and German component suppliers, exposing manufacturers to geographic concentration risk.
- Notified body capacity constraints:EU MDR conformity assessment backlogs are extending product registration timelines by 12-18 months for Class IIa diagnostic endoscopes.
- Analogue audiometer substitution:Digital audiology platforms with software-defined testing protocols are rendering standalone analogue equipment obsolete, stranding inventory for distributors.
Strategic Opportunities
- India import licensing streamlining:The country's central bank and national pharmaceutical regulator are creating alternative regulatory pathways for manufacturers facing Western conformity bottlenecks.
- AI-enhanced endoscopy image analysis:FDA software-as-a-medical-device guidance is opening novel premarket review categories for algorithm-based diagnostic support functions in otolaryngology suites.
- Integrated delivery network bundling:Multi-year supply contracts combining diagnostic and therapeutic systems are securing captive placement in academic medical centers and hospital systems.
Industry Challenges
- Software validation expertise scarcity:AI-enabled diagnostic tools require specialized regulatory affairs professionals capable of navigating FDA algorithm change control protocols.
- Legacy system integration friction:Digital endoscope platforms face interoperability challenges with proprietary electronic health record architectures in established hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ENT Diagnostic Devices Market |
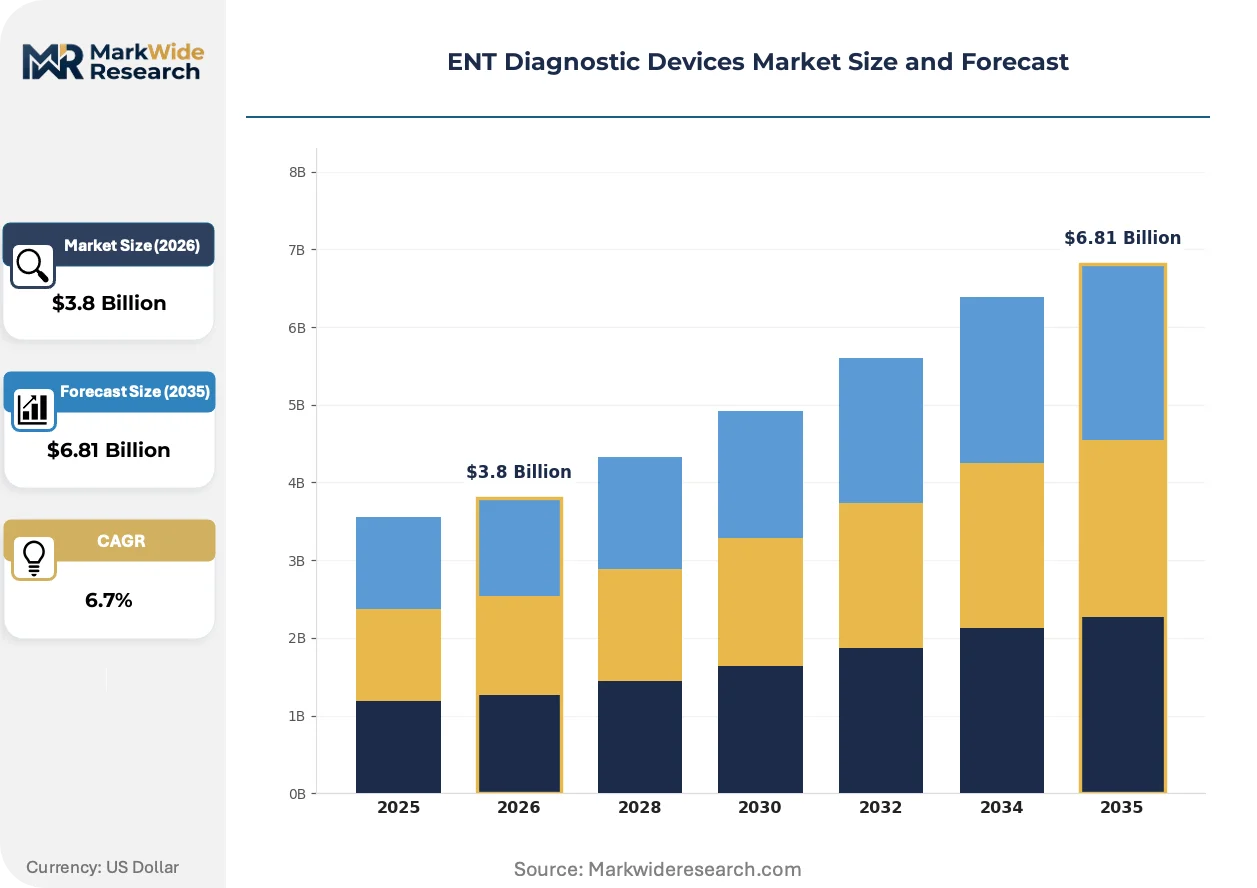
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Otoscopes, Audiometers, Rhinometers Technology: Digital, Analogue, Wireless, Portable Application: Diagnostic, Surgical, Monitoring, Screening End User: Hospitals, Clinics, Diagnostic Laboratories, ENT Practices |
| Companies Covered | Medtronic plc, Olympus Corporation, Stryker Corporation, Karl Storz SE & Co. KG, Cochlear Limited, Richard Wolf GmbH, Pentax Medical, GN Store Nord A/S, Demant A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ENT Diagnostic Devices Market Emerging Trajectories
Wireless connectivity and artificial intelligence are restructuring how ENT diagnostics are performed, distributed, and reimbursed. These shifts are compressing replacement cycles and redefining competitive advantage around software capabilities rather than optical craftsmanship alone.
Digital imaging sensors with resolutions exceeding 720p are migrating from academic medical centers to community otolaryngology practices. Ambulatory surgical centers in the United States and Germany are adopting these platforms to support same-day diagnostic and therapeutic procedures. The technology is migrating from premium-tier equipment to mid-market configurations, eroding price premiums previously commanded by optical resolution specifications.
EU MDR technical documentation requirements are mandating clinical evidence for legacy endoscope designs previously cleared under the Medical Devices Directive. Notified bodies in Germany and the Netherlands are demanding updated biocompatibility and sterilization validation data. Rigid endoscope manufacturers with substantial European revenue exposure are accelerating design dossier remediation to maintain market access.
Group purchasing organizations are consolidating vendor lists and unbundling after-sales service contracts from capital equipment sales. Integrated delivery networks in Japan and the United States are negotiating direct manufacturer relationships, bypassing traditional distributor margins. This concentration is most visible in Germany, where hospital procurement consortiums now control the majority of academic medical center purchasing decisions.
ENT Diagnostic Devices Market Segmentation
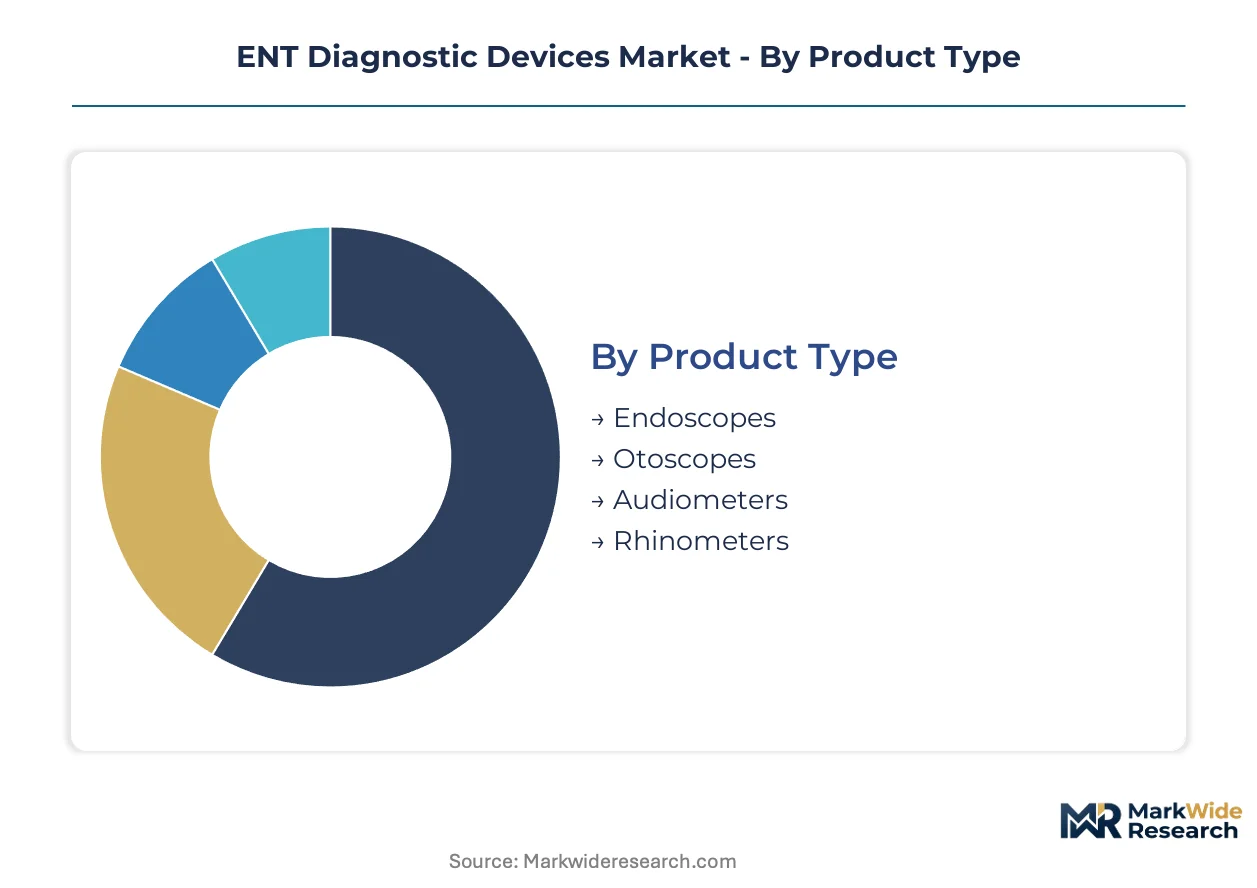
ENT diagnostic device manufacturers configure product portfolios across four intersecting dimensions. Procurement patterns diverge sharply between capital-intensive hospital systems and ambulatory settings with constrained infrastructure budgets.
Product Type:
Cost tier determines replacement cadence and margin structure across the four device categories, with premium optical systems commanding extended service contracts.
- Endoscopes:Rigid and flexible fiber-optic systems with working channels of 2-4 millimeters dominate hospital procurement budgets. Academic medical centers in Germany and the United States concentrate demand for 4K resolution platforms with integrated insufflation pumps.
- Otoscopes:Digital imaging sensors exceeding 720p resolution are displacing traditional halogen bulb designs in community otolaryngology practices. Wireless otoscope deployments are climbing fastest in Japan's dense clinic networks where space constraints favor cable-free examination rooms.
- Audiometers:Pure-tone and speech audiometry platforms serve hearing assessment protocols across diagnostic laboratories.
- Rhinometers:Acoustic rhinometry and rhinomanometry systems measure nasal airway resistance for preoperative planning.
Endoscopes hold installed capacity. Otoscopes are rotating up the share rankings.
Technology:
Application requirements dictate technology selection, with surgical suites demanding tethered reliability while screening programs prioritize field mobility.
- Digital:CMOS sensor-based platforms with direct electronic health record integration are standardizing in hospital networks. FDA 510(k) clearance pathways for software-as-a-medical-device functionality are accelerating algorithm-enhanced image analysis adoption in the United States.
- Wireless:Bluetooth Low Energy protocols with sub-50ms latency are enabling cordless endoscope deployments previously impossible. Battery chemistry advances in lithium-polymer cells are extending procedure duration limits in German ambulatory surgical centers.
- Analogue:Fibre-optic transmission systems without digital conversion persist in price-sensitive procurement environments.
- Portable:Battery-powered diagnostic platforms with integrated displays serve outreach screening programs and resource-limited settings.
Digital platforms anchor revenue contribution. Wireless configurations are expanding most quickly across new installations.
Application:
Customer type determines performance specifications, with surgical applications demanding sterilization durability absent in screening workflows.
- Diagnostic:Visualization and measurement functions for structural assessment and hearing evaluation constitute the core revenue pool. ENT practices in Japan concentrate procurement of multi-function platforms combining endoscopy with integrated suction and irrigation.
- Surgical:Intraoperative guidance systems require sterilization compatibility and instrument passage channels. Academic medical centers demand 4K resolution with near-infrared fluorescence capability for margin assessment.
- Monitoring:Serial assessment protocols for chronic conditions including obstructive sleep apnea and chronic rhinosinusitis.
- Screening:Rapid assessment workflows in school and occupational health settings prioritize throughput over diagnostic depth.
Diagnostic applications hold installed capacity. Surgical applications are rotating up the share rankings.
End User:
Volume concentration varies by geography, with integrated delivery network consolidation reshaping purchasing authority across settings.
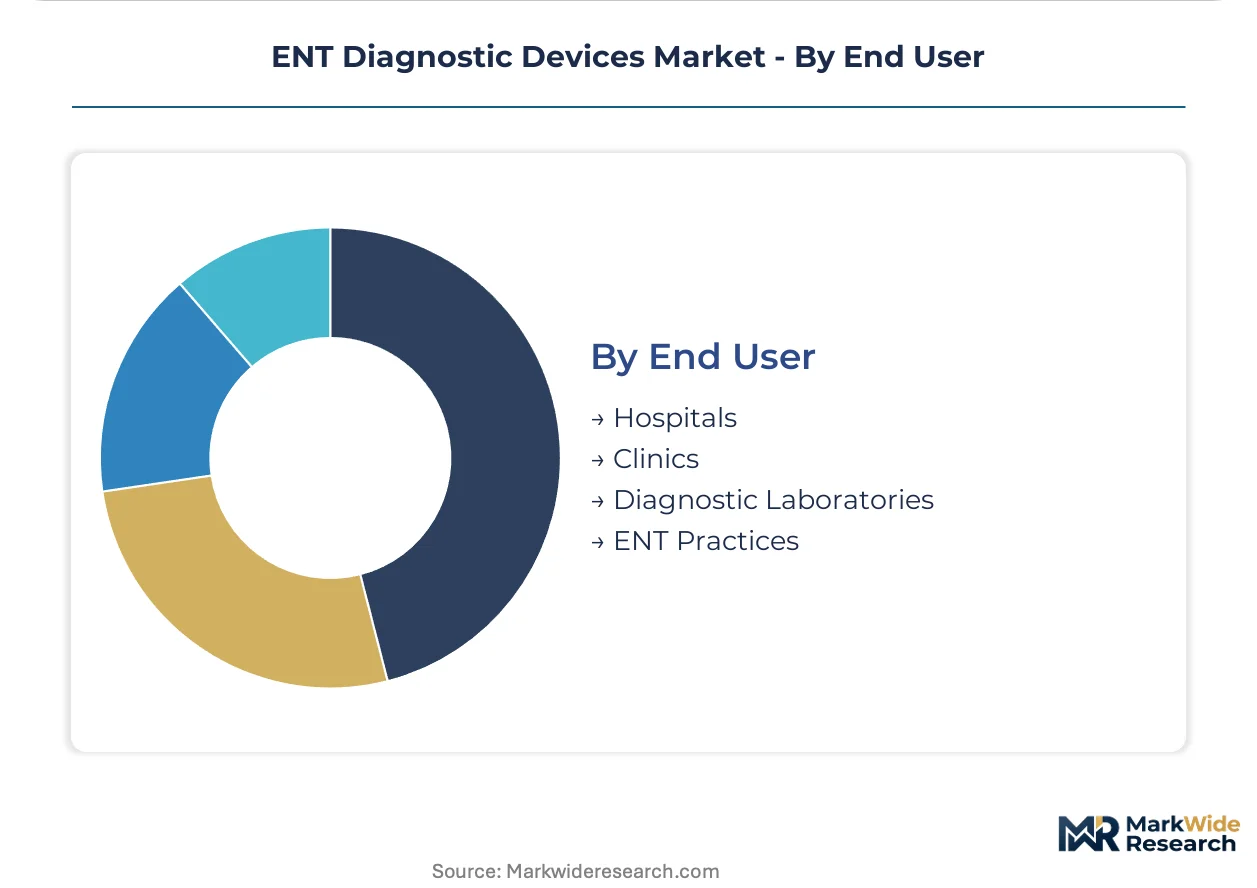
- Hospitals:Inpatient and outpatient surgical departments with centralized sterilization services drive capital equipment procurement. Group purchasing organizations in the United States are consolidating vendor lists and unbundling service contracts from equipment sales.
- Clinics:Community-based otolaryngology and primary care settings with space constraints favor portable and wireless configurations. Ambulatory surgical center densification in Germany is expanding same-day procedure volumes.
- Diagnostic Laboratories:Centralized audiology and imaging facilities serving referral networks with high-throughput protocols.
- ENT Practices:Solo and group specialty practices with direct patient relationships and equipment ownership models.
Hospitals hold installed capacity. Clinics are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortiums in Germany are consolidating vendor lists and reshaping how ENT diagnostic devices reach European end users. The United States Food and Drug Administration is accelerating software-as-a-medical-device guidance for AI-enhanced endoscopy tools. Japan's ambulatory surgical center densification is driving wireless otoscope demand in Tokyo and Osaka clinic networks.
United States
Ambulatory surgical center networks in Texas and Florida are expanding same-day ENT procedure volumes and driving portable diagnostic platform procurement. The FDA 510(k) premarket notification pathway is compressing development timelines for manufacturers seeking clearance for digital endoscope platforms. Integrated delivery networks in the Northeast Corridor are negotiating direct manufacturer relationships and bypassing traditional distributor channels.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia are concentrating demand for 4K resolution endoscope systems with integrated insufflation pumps. The EU MDR technical documentation obligations are extending conformity assessment durations for Class IIa diagnostic endoscopes by 12-18 months. Hospital procurement consortiums in Berlin-Brandenburg now control the majority of purchasing decisions for rigid endoscope placements.
Japan
Community otolaryngology clinics in the Kanto region are adopting wireless otoscope configurations to address space constraints in dense urban examination rooms. The Ministry of Economy, Trade and Industry is streamlining medical device quality management system certifications for domestic manufacturers. ENT practices in Osaka are concentrating procurement of multi-function platforms combining endoscopy with integrated suction and irrigation capabilities.
India
Import licensing streamlining by the Reserve Bank of India and the Central Drugs Standard Control Organization is creating alternative regulatory pathways for manufacturers facing Western conformity bottlenecks. Diagnostic laboratories in Maharashtra and Karnataka are expanding centralized audiology facilities to serve referral networks with high-throughput protocols. Clinic networks in Delhi-NCR are adopting battery-powered portable diagnostic platforms for outreach screening programs.
United Kingdom
Integrated care systems in London and the Southeast are consolidating diagnostic equipment procurement across formerly fragmented hospital trusts. The Medicines and Healthcare products Regulatory Agency is aligning post-market surveillance requirements with EU MDR standards for endoscope manufacturers. ENT practices in the Midlands are rotating toward digital audiometer platforms with electronic health record integration.
ENT Diagnostic Devices Market Vendor Landscape
On the supply side, the industry is consolidating around diversified medical technology conglomerates with broad surgical portfolios and specialized endoscope craftsmen with premium optical capabilities. The vendor base separates into three strategic archetypes: integrated surgical systems providers, rigid endoscope specialists, and audiology platform developers. Dominant competitive moves include multi-year supply contract bundling with integrated delivery networks and cross-selling from gastrointestinal endoscopy into ENT suites.
Among diversified surgical systems providers, Medtronic plc and Stryker Corporation exemplify the archetype of conglomerates leveraging broad product portfolios to secure captive placement in hospital networks. Within the rigid endoscope specialization tier, Karl Storz SE & Co. KG and Richard Wolf GmbH occupy positions anchored in German optical craftsmanship traditions. Olympus Corporation represents the cross-category archetype, utilizing gastrointestinal endoscopy installed bases to expand into ENT diagnostic suites.
| Leading Market Players |
|---|
| Medtronic plc |
| Olympus Corporation |
| Stryker Corporation |
| Karl Storz SE & Co. KG |
| Cochlear Limited |
| Richard Wolf GmbH |
| Pentax Medical |
| GN Store Nord A/S |
| Demant A/S |
| Others |
Supply Flow & Price Mechanics
Japanese and German suppliers of high-resolution CMOS sensors and fiber-optic bundles anchor upstream concentration, feeding margin pools downstream to endoscope manufacturers with captive quality management systems and established hospital procurement relationships. This geographic input concentration amplifies pricing power for component vendors while compressing margins for device assemblers facing group purchasing organization consolidation.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement consortiums, with group purchasing organizations extracting stepped rebates for multi-year commitments above threshold unit volumes. Pricing stratifies across premium optical systems with 4K resolution and integrated insufflation pumps, standard digital platforms with 720p sensors, and economy analogue configurations facing obsolescence pressure. Cost compression in the standard tier is intensifying as digital imaging specifications migrate downward, while academic medical centers show lowest price sensitivity due to bundled service contract preferences and optical craftsmanship premiums.
Supply Chain Analysis
Tariff exposure between component suppliers in Japan and assembly operations in Germany and the United States dominates supply chain risk calculations for rigid endoscope manufacturers. High-resolution imaging sensors draw from specialized Japanese foundries, fiber-optic bundles rest on German glass-drawing expertise, and lithium-polymer cells for wireless configurations source from South Korean battery chemistry specialists. Single-source vulnerability concentrates in CMOS sensor fabrication, where qualified alternative suppliers require 18-24 month validation cycles. Distribution runs through regional distributors facing squeeze-out by direct manufacturer relationships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring competitive advantage around software integration and electronic health record interoperability, as wireless connectivity and AI-enhanced image analysis shift value capture from optical hardware to algorithmic diagnostic support ecosystems.
For Market Incumbents: Pre-empt wireless otoscope commoditization by bundling diagnostic platforms with predictive maintenance software and remote clinical support subscriptions. Secure backward integration into CMOS sensor supply through strategic partnerships with Japanese component houses, insulating against single-source vulnerability while defending margin position against emerging digital-native entrants.
For New Entrants and Emerging Players: Pursue regulatory arbitrage opportunities in India where import licensing streamlining by the Reserve Bank of India and CDSCO creates faster market access than EU MDR conformity bottlenecks. Target clinic networks in Japan's dense urban corridors with space-constrained wireless configurations, leveraging Bluetooth Low Energy latency improvements to displace cabled incumbent systems without matching decades of optical brand equity.
For Investors and Strategic Acquirers: Capital is best deployed toward software-enabled diagnostic platform developers with FDA software-as-a-medical-device clearance pathways and established hospital system pilot contracts, rather than pure-play hardware manufacturers facing analogue substitution headwinds. The signal to watch is FDA algorithm change control protocol finalization, which will clarify competitive moat durability for AI-enhanced endoscopy tools.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | Accelerated design dossier remediation secures German academic medical center access against notified body backlogs. |
| Software-as-a-Medical-Device Development | FDA 510(k) clearance for algorithm-enhanced image analysis opens novel premarket review categories in otolaryngology suites. |
| Hospital System Partnership | Direct manufacturer relationships with integrated delivery networks bypass distributor margin compression in the United States. |
| Wireless Platform Integration | Bluetooth Low Energy deployments in Japanese clinic networks displace cabled systems through space optimization. |
| Reimbursement Strategy | Electronic health record integration protocols align with ambulatory surgical center densification in Germany and Texas. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, otolaryngology clinicians, and group purchasing organization contract specialists and refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement consortium contract records, and medical device trade customs data. Bottom-up unit shipment estimates triangulated with top-down revenue aggregation across product type, technology, application, and end user segmentation dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across endoscope, otoscope, audiometer, and rhinometer product categories intersecting with digital, wireless, analogue, and portable technology tiers. CAGRs were derived from logistic adoption curves fitted to historical replacement cycle data and procurement budget trajectories, incorporating ambulatory surgical center densification patterns and regulatory approval timeline assumptions as industry-specific forecast inputs.
Sensitivities concentrate around notified body capacity resolution in Europe, FDA software-as-a-medical-device guidance finalization, and lithium-polymer cell supply continuity from South Korean manufacturers. Forecasts reflect documented assumptions regarding replacement cycle compression and wireless technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market