
 Acute Ischemic Stroke Diagnosis Market | 2026-2036
Acute Ischemic Stroke Diagnosis Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Ischemic Stroke Diagnosis Market Outlook
The EU Green Deal is recalibrating medical device procurement criteria across European hospital networks, with embedded carbon accounting now influencing capital allocation for diagnostic equipment. Siemens Healthineers leverages its vertically integrated imaging manufacturing to sustain competitive positioning in CT and MRI platforms. GE Healthcare anchors its market presence through deep channel control across North American stroke center networks. Koninklijke Philips differentiates via AI-native digital imaging architectures that reduce contrast agent volumes per scan.
Acute ischemic stroke diagnosis encompasses the rapid identification of cerebral artery occlusion through neuroimaging modalities, functional biomarker assays, and hemodynamic monitoring systems designed to detect salvageable brain tissue within therapeutic time windows. CT perfusion imaging with automated cerebral blood volume mapping enables triage decisions for endovascular thrombectomy candidacy up to 24 hours from symptom onset. MRI diffusion-weighted sequences represent the fastest-growing product type segment as hospitals replace aging scanners with 3 Tesla platforms offering superior posterior circulation sensitivity. AI-based solutions command expanding margin pools through subscription revenue models that integrate directly into radiology workflow orchestration, while wearable devices remain nascent with clinical validation still pending for prehospital stroke detection.
FDA premarket authorization pathways for software-as-a-medical-device shape development timelines and commercialization strategies for AI imaging developers seeking US market access. The EU Medical Device Regulation imposes strengthened clinical evidence requirements on diagnostic algorithms, elevating barriers for smaller technology entrants without prospective validation datasets. Stakeholders must monitor evolving reimbursement frameworks for automated image analysis, as Medicare coverage determinations will dictate adoption velocity across US health systems.
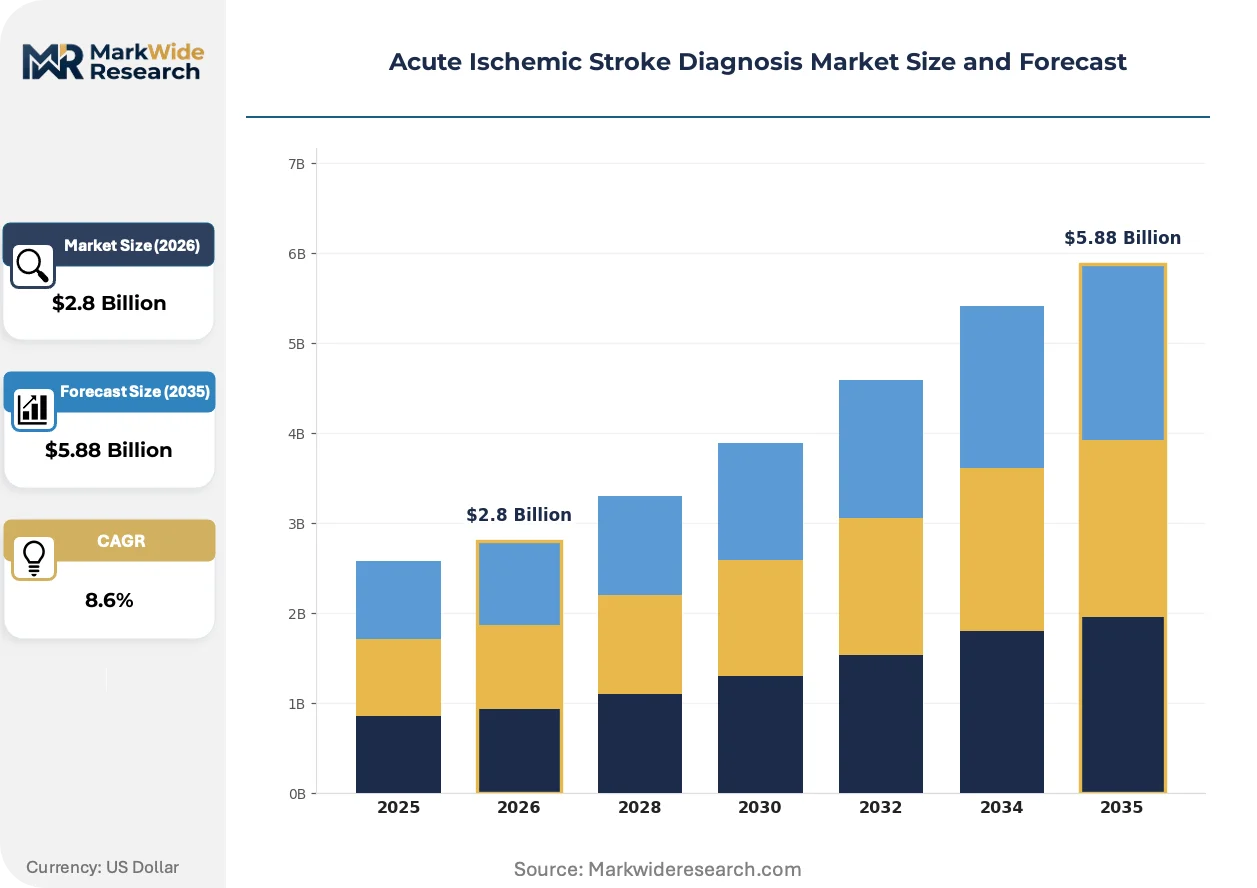
Market Dynamics
FDA premarket authorization pathways for AI-enabled stroke imaging software are compressing commercialization timelines while EU MDR clinical evidence requirements simultaneously elevate barriers for algorithm developers lacking prospective validation datasets.
Growth Catalysts
- Integrated Stroke Center Certification:US hospital networks prioritize capital allocation toward advanced neuroimaging infrastructure to meet Joint Commission certification standards, driving scanner replacement cycles.
- CT Perfusion Automation:Automated cerebral blood volume mapping protocols extend endovascular thrombectomy eligibility windows, expanding addressable patient populations for interventional neuroradiology suites.
- AI Workflow Integration:Subscription-based radiology orchestration platforms embed stroke detection algorithms directly into PACS environments, reducing time-to-diagnosis metrics.
Market Restraints
- Gadolinium Supply Concentration:Contrast agent production concentrates among three European chemical manufacturers, exposing MRI-dependent stroke protocols to raw material volatility.
- 3 Tesla MRI Capex Thresholds:Magnet replacement and cryogen maintenance requirements exceed capital budgets at non-academic community hospitals, constraining diffusion-weighted sequence adoption.
- EU MDR Algorithm Validation:Strengthened clinical evidence requirements for software-as-a-medical-device delay market entry for developers without multi-site prospective datasets.
Strategic Opportunities
- Prehospital Wearable Detection:Ambulatory electrodermal and accelerometric sensors for stroke recognition in emergency medical services transport remain clinically undervalidated, creating first-mover whitespace.
- Carbon Accounting Procurement:EU Green Deal embedded emissions criteria recalibrate European hospital network tender evaluations, favoring domestically manufactured imaging platforms.
- Contrast Agent Reduction:AI-native digital imaging architectures enable diagnostic-quality scans at reduced gadolinium volumes, aligning with nephrology safety protocols.
Industry Challenges
- Neuroradiologist Workforce Density:Fellowship-trained stroke imaging specialists concentrate at academic medical centers, creating interpretation bottlenecks at suburban emergency departments.
- Legacy PACS Interoperability:AI algorithm deployment requires HL7 FHIR interface development with decade-old radiology information systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Ischemic Stroke Diagnosis Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scan, MRI, Ultrasound, Angiography Delivery Mode: Telemedicine, In-Hospital, Home Care, Remote Monitoring End User: Hospitals, Diagnostic Centers, Clinics, Rehabilitation Facilities Technology: Digital Imaging, AI-Based Solutions, Cloud-Based Platforms, Wearable Devices |
| Companies Covered | Fujifilm Holdings Corporation, Abbott Laboratories, Siemens Healthineers, Medtronic, Boston Scientific, GE Healthcare, Samsung Electronics, Stryker Corporation, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Ischemic Stroke Diagnosis Market Strategic Shifts
Neuroimaging modality evolution is bifurcating around speed-versus-sensitivity tradeoffs, with CT perfusion prioritizing emergency department throughput while MRI diffusion sequences capture posterior circulation territory.
CT perfusion imaging with automated cerebral blood volume mapping is integrating into emergency department stroke protocols as the default triage modality for endovascular candidacy assessment. Community hospital networks lacking 24-hour neuroradiology coverage adopt these platforms to reduce transfer delays. The technology is integrating decision-support infrastructure that compresses door-to-puncture intervals without requiring on-site subspecialist interpretation.
EU Medical Device Regulation software-as-a-medical-device classification requirements are reshaping development timelines for stroke detection algorithms. Developers must now compile multi-site prospective validation datasets before CE marking, elevating capital requirements for commercialization. European stroke centers consequently face delayed access to FDA-cleared platforms already deployed in US health systems.
Subscription revenue models for AI image analysis are displacing perpetual license arrangements in radiology department procurement. Hospital systems favor per-scan pricing that aligns diagnostic expenditure with patient volume fluctuations. This shift concentrates most visibly in US integrated delivery networks negotiating enterprise-wide platform agreements.
Acute Ischemic Stroke Diagnosis Market Segmentation
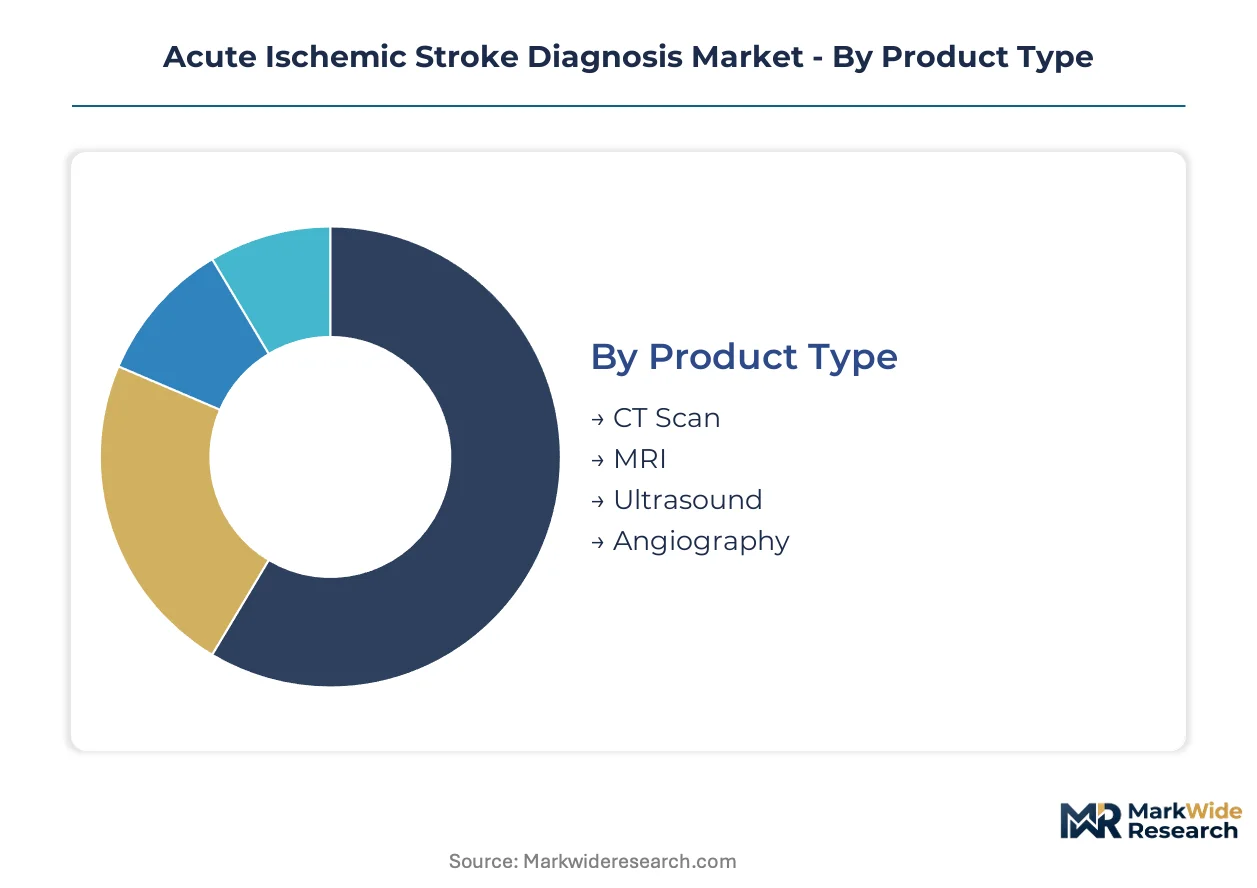
Acute ischemic stroke diagnosis segments around speed-to-treatment hierarchies and capital intensity gradients. Product type and delivery mode splits determine reimbursement pathways, while end-user concentration shapes equipment procurement cycles.
Product Type:
Volume deployment concentrates at community hospitals, while premium platforms anchor academic stroke centers.
- CT Scan:Non-contrast CT remains the emergency department default for hemorrhage exclusion within the first minutes of arrival. Siemens Healthineers and GE Healthcare dominate installed bases across US integrated stroke networks, with automated perfusion software now standard for thrombectomy triage.
- MRI:Diffusion-weighted imaging at 3 Tesla delivers superior posterior circulation sensitivity for wake-up stroke protocols. Magnet replacement costs and cryogen maintenance requirements restrict adoption to academic medical centers and certified comprehensive stroke centers.
- Ultrasound:Transcranial Doppler enables bedside monitoring of vasospasm and microembolic signals in neurocritical care units.
- Angiography:Digital subtraction platforms guide mechanical thrombectomy interventions in interventional neuroradiology suites.
Today's leader: CT Scan. Tomorrow's challenger: MRI.
Delivery Mode:
Capital-light models expand access, while infrastructure-heavy modes capture intervention revenue.
- Telemedicine:Hub-and-spoke networks connect community emergency departments to academic neuroradiologists for real-time image interpretation. Medicare reimbursement parity for telestroke consultations accelerates rural hospital participation in thrombectomy referral chains.
- In-Hospital:On-site neuroimaging infrastructure commands premium reimbursement for comprehensive stroke center certification. Joint Commission standards mandate 24-hour CT and MRI availability, driving capital allocation toward scanner redundancy.
- Home Care:Post-discharge monitoring for secondary prevention remains reimbursement-limited outside clinical trial protocols.
- Remote Monitoring:Wearable electrodermal sensors for prehospital detection lack FDA clearance for stroke-specific indication.
Telemedicine scales fastest where neuroradiologist density falls below intervention thresholds.
End User:
Certification tiers stratify purchasing authority and technology sophistication.
- Hospitals:Emergency departments at primary stroke centers represent the fastest-expanding adoption segment as protocol standardization accelerates. Thrombectomy-capable centers command capital budgets for biplane angiography suites.
- Diagnostic Centers:Outpatient MRI facilities capture elective stroke risk assessment for atrial fibrillation patients prior to cardioversion.
- Clinics:Neurology practices deploy handheld ultrasound for carotid screening in transient ischemic attack follow-up.
- Rehabilitation Facilities:Long-term acute care hospitals utilize portable CT for monitoring hemorrhagic transformation during anticoagulation.
Hospital networks consolidate purchasing through enterprise agreements, squeezing independent diagnostic centers on price.
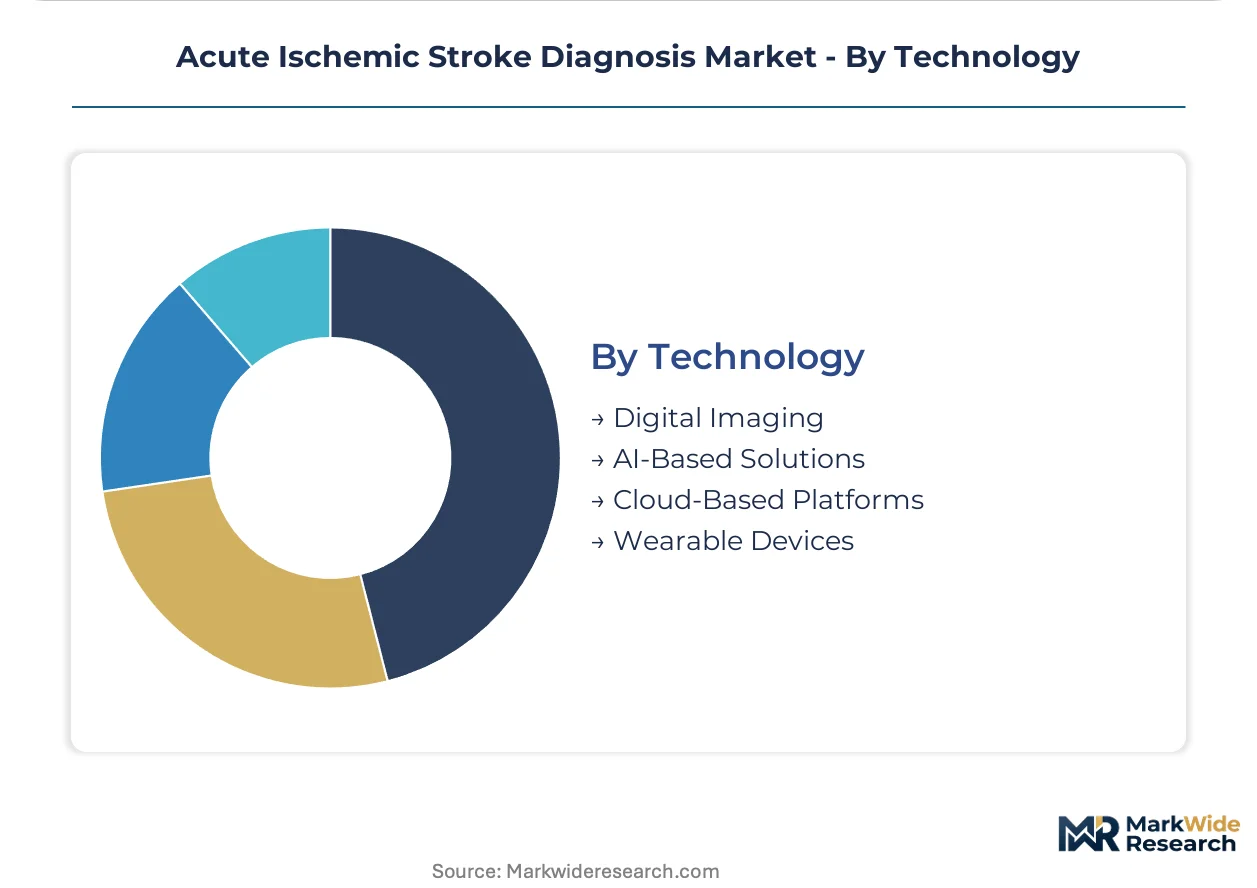
Technology:
Software margins expand while hardware replacement cycles lengthen.
- Digital Imaging:PACS-integrated viewers with automated windowing reduce radiologist interpretation time for non-contrast head CT. FDA 510(k) clearances for stroke detection algorithms now exceed fifty distinct products.
- AI-Based Solutions:Large-vessel occlusion detection algorithms embed directly into radiology workflow orchestration platforms. Subscription pricing per scan aligns vendor revenue with hospital patient volume fluctuations.
- Cloud-Based Platforms:Vendor-neutral archives enable multi-site image sharing for transferred thrombectomy candidates.
- Wearable Devices:Accelerometric and electrodermal sensors for prehospital stroke recognition remain in prospective validation phases without regulatory clearance.
AI-Based Solutions capture expanding margin pools as perpetual licenses give way to recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stroke diagnosis technology first achieved clinical scale in the United States through NIH-funded neuroimaging research at Massachusetts General Hospital and the University of Pittsburgh Medical Center during the 1990s. This foundational work established perfusion imaging protocols that now dominate emergency department triage worldwide.
United States
Joint Commission stroke center certification mandates 24-hour neuroimaging availability, driving capital expenditure at over 1,200 primary stroke centers. FDA 510(k) premarket notification pathways compress commercialization timelines for AI-enabled detection software. The Boston-Cleveland corridor concentrates interventional neuroradiology training programs and thrombectomy-capable hospital networks.
Germany
EU MDR software-as-a-medical-device classification delays market entry for algorithms lacking multi-site prospective validation datasets. The country's statutory health insurance system reimburses CT perfusion imaging for extended-window thrombectomy candidacy assessment. Medical technology manufacturing clusters in Erlangen and Forchheim anchor CT and MRI platform production for European distribution.
Japan
PMDA consultation pathways for AI diagnostic software streamline regulatory review for developers with prior FDA clearance. Super-aging demographics expand addressable patient populations for stroke detection platforms. The Kansai region's Osaka-Kobe medical device corridor hosts manufacturing facilities for digital subtraction angiography systems.
China
NMPA innovation approval pathways for AI-enabled medical software accelerate domestic product registration for stroke imaging algorithms. Hospital procurement reform concentrates diagnostic equipment purchasing at provincial-level centralized tender platforms. The Yangtze River Delta's Shanghai-Suzhou corridor concentrates radiology AI development startups and venture capital deployment.
United Kingdom
NHS England's stroke service specification mandates mechanical thrombectomy availability at designated neuroscience centers by 2025. MHRA recognition of FDA and CE marking for software devices reduces duplicate regulatory burden for imported platforms. The Oxford-Cambridge-London golden triangle concentrates academic neuroradiology research and translational imaging science.
Acute Ischemic Stroke Diagnosis Market Competitive Environment
Capital-heavy imaging equipment manufacturers compete with asset-light AI software developers for margin capture across the stroke diagnosis value chain. The market structure concentrates around three durable equipment platforms while algorithm vendors fragment across fifty-plus FDA-cleared products. Strategic archetypes include vertically integrated modality producers, workflow-embedded AI specialists, and point-solution algorithm developers. Dominant competitive moves encompass enterprise subscription pricing for software and backward integration into cloud-native imaging architectures.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare occupy positions reflecting decades of CT and MRI platform installed base accumulation. Koninklijke Philips represents the AI-native imaging architecture approach with digital workflow integration capabilities. These three entities exemplify the capital-intensive tier where equipment financing relationships and service contract renewals defend competitive position against software-only entrants seeking radiology department procurement access.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Abbott Laboratories |
| Siemens Healthineers |
| Medtronic |
| Boston Scientific |
| GE Healthcare |
| Samsung Electronics |
| Stryker Corporation |
| Koninklijke Philips |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States negotiate enterprise-wide platform agreements that compress per-scan pricing for AI-enabled stroke detection algorithms while favoring subscription models over perpetual licenses. This buyer concentration shifts margin capture toward vendors with workflow-embedded architectures and deep PACS integration capabilities.
Pricing Analysis
Subscription-based SaaS tiering dominates AI stroke imaging procurement, with pricing stratifying across comprehensive stroke centers, primary stroke centers, and community emergency departments based on Joint Commission certification tier and annual scan volume. Siemens Healthineers and GE Healthcare leverage equipment financing relationships to bundle hardware with algorithm access, while pure-play AI developers compete on per-study economics. Cost compression in community hospital tiers intensifies as telemedicine networks aggregate purchasing power across multi-site hub-and-spoke arrangements. Price sensitivity peaks at non-academic community hospitals facing 3 Tesla MRI capex thresholds, while academic medical centers prioritize posterior circulation sensitivity over unit economics.
Supply Chain Analysis
Regional distribution centers in Erlangen, Forchheim, and Milwaukee anchor CT and MRI platform fulfillment for North American and European stroke center networks. Superconducting magnet production concentrates in Germany, Japan, and the United States, with cryogen supply chains drawing from industrial gas producers in Belgium and the Gulf Coast. Single-source vulnerability in gadolinium-based contrast agents exposes MRI-dependent protocols to raw material volatility from European chemical manufacturers. Distribution runs through manufacturer-direct service organizations that maintain installed bases through multi-year equipment and software maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in acute ischemic stroke diagnosis hinges on AI workflow integration displacing hardware-centric revenue models, with subscription pricing capturing recurring value from software deployment density.
For Market Incumbents: Anchor competitive position through backward integration into cloud-native imaging architectures that reduce third-party PACS dependency. Deepen channel control across certified stroke center networks by embedding AI algorithms directly into CT perfusion platforms. Siemens Healthineers and GE Healthcare must defend against pure-play AI developers by expanding subscription revenue from automated cerebral blood volume mapping protocols. For New Entrants and Emerging Players: FDA 510(k) premarket notification pathways in the United States open a window for algorithm developers to compress commercialization timelines relative to EU MDR requirements. Target community hospital emergency departments lacking 24-hour neuroradiology coverage with telemedicine-integrated stroke detection platforms. Pursue hub-and-spoke network partnerships that aggregate rural hospital purchasing into enterprise agreements with per-scan pricing models. For Investors and Strategic Acquirers: Health technology conglomerates with imaging equipment installed bases represent the most active acquirer in this space, seeking AI capabilities to differentiate hardware platforms. Long-term viability favors developers with multi-site prospective validation datasets that satisfy both FDA and EU MDR requirements. Monitor Medicare coverage determinations for automated image analysis as the inflection indicator for adoption velocity across US health systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates US market entry for AI-enabled large-vessel occlusion detection algorithms ahead of EU MDR timelines. |
| CE Marking Pathway | Multi-site prospective validation datasets satisfy EU Medical Device Regulation requirements for software-as-a-medical-device classification. |
| Hospital System Partnership | Enterprise agreements with integrated delivery networks lock in recurring subscription revenue for stroke detection platforms. |
| Software Companion Development | PACS-embedded viewers with automated windowing reduce radiologist interpretation time and differentiate CT perfusion offerings. |
| Reimbursement Strategy | Medicare coverage parity for telestroke consultations expands addressable market for hub-and-spoke network participants. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with neuroradiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU Medical Device Regulation guidance documents. Bottom-up scanner shipment tracking and top-down health system capital expenditure analysis provided cross-referenced market sizing.
Segment-weighting approaches modeled technology adoption across product type, delivery mode, end user, and certification tier dimensions over the projection horizon. CAGRs derived from equipment replacement cycle analysis and AI software penetration curves within stroke center networks. Forecast inputs incorporated Joint Commission certification standards, EU Green Deal procurement criteria, and PMDA consultation pathway timelines for algorithm developers.
Revisions become necessary when FDA premarket authorization pathways shift, EU MDR clinical evidence requirements tighten, or Medicare coverage determinations for automated image analysis change materially. Forecasts reflect documented assumptions regarding neuroradiologist workforce density and legacy PACS interoperability constraints. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Pathogen Detection Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Veterinary Chemistry Analyzers Market
Diagnostics
Global Companion Animal Diagnostics Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
North America Antinuclear Antibody Test Market