
 HDL Cholesterol Kits Market | 2026-2036
HDL Cholesterol Kits Market Size, Share, and Industry Trends Forecast 2026-2036
HDL Cholesterol Kits Market Outlook
Market Context
Clinical laboratory technologist shortages in North America and Western Europe is rotating procurement priorities toward automated HDL assay systems that reduce manual pipetting steps. Abbott Laboratories leverages its Alinity platform architecture to sustain installed-base loyalty across integrated delivery networks. Thermo Fisher Scientific anchors its position through consumable pull-through from a broad reagent catalog spanning enzymatic and spectrophotometric chemistries. Randox Laboratories Ltd competes on specialized high-density lipoprotein subfractionation assays that differentiate its offering from standard homogeneous methods.
Technical Definition and Segment Structure
HDL cholesterol kits are in vitro diagnostic reagent systems designed to quantify high-density lipoprotein cholesterol in serum or plasma, typically employing polyethylene glycol-modified enzymes or antibody-separation techniques with analytical specificity thresholds of ±3% coefficient of variation. These kits serve cardiology diagnostics, metabolic syndrome screening, and pharmaceutical trial endpoints where precise lipid profiling guides therapeutic intervention. Lab Kits dominate current volume owing to hospital central laboratory throughput requirements, while Home Test Kits represent the fastest-expanding segment as direct-to-consumer preventive care models gain reimbursement traction in select markets. Electrochemical technology occupies emerging positioning for point-of-care lipid panels, though colorimetric and enzymatic methods retain margin concentration through reagent recurring revenue.
Regulatory Framework and Outlook
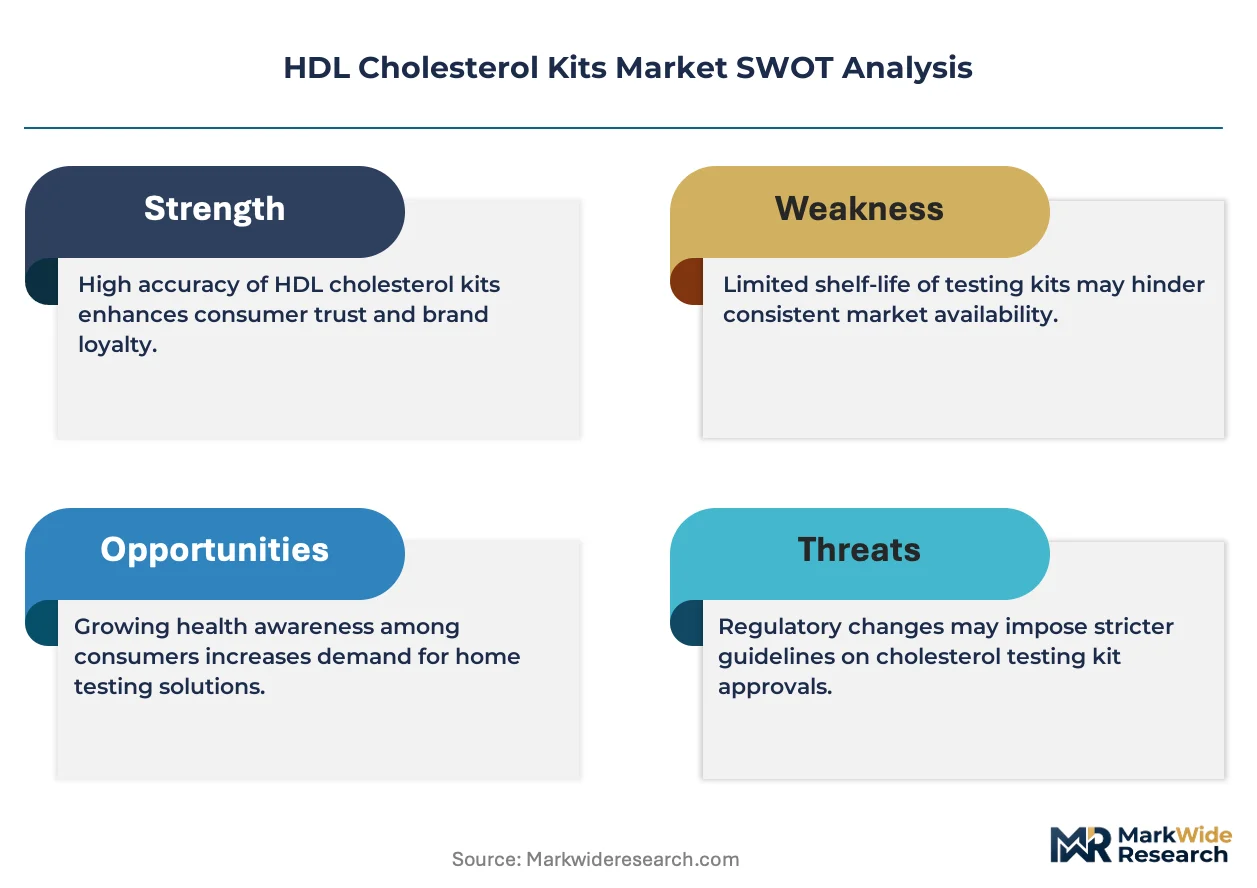
The US FDA classifies HDL cholesterol assays as Class II medical devices requiring 510(k) premarket notification with clinical accuracy validation against CDC reference methods. European EMA oversight through the In Vitro Diagnostic Regulation mandates notified body conformity assessment for CE marking, while Japan's PMDA enforces Ministry of Health, Labour and Welfare quality standards for imported diagnostic reagents. China's NMPA has accelerated review timelines for innovative IVD products under its priority review pathway, reshaping market access strategy for multinational manufacturers. Stakeholders must monitor evolving harmonization between FDA and EMA performance criteria for lipid assay standardization, as divergence in acceptable bias limits would fragment product development roadmaps and regional registration investments.
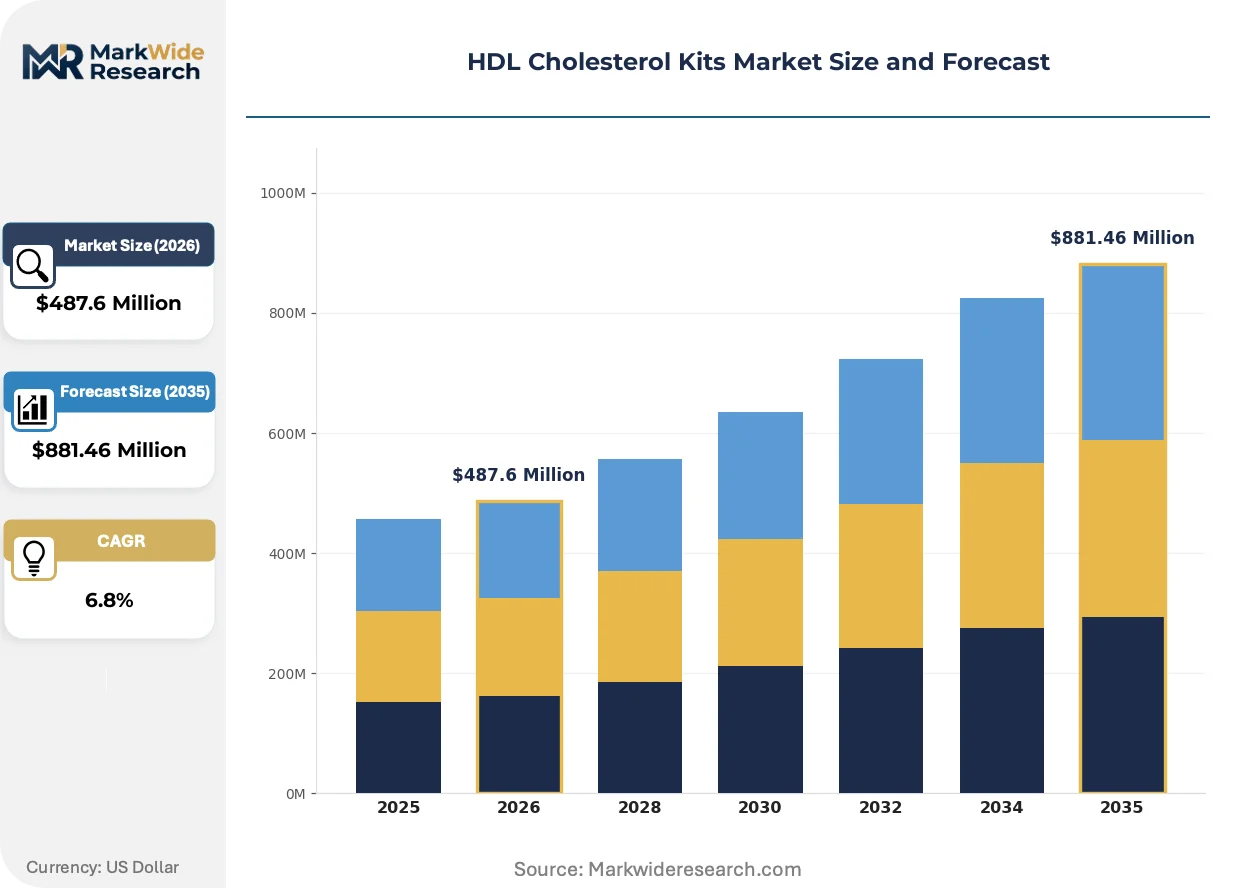
Market Dynamics
Automated liquid handling systems are compressing turnaround times in hospital central laboratories, forcing kit manufacturers to reformulate reagents for compatibility with closed-system analyzers while preserving analytical accuracy against CDC reference standards.
Growth Catalysts
- Preventive cardiology mandates:Medicare coverage expansion for annual lipid panels in the United States is pulling screening volumes into diagnostic networks.
- Enzymatic assay advancement:Direct clearance methods eliminate pretreatment steps, reducing labor costs for high-throughput laboratories.
- Aging demographics in Japan:Ministry of Health, Labour and Welfare screening programs target metabolic syndrome detection in adults over 40.
Market Restraints
- Reagent raw material concentration:Polyethylene glycol enzyme suppliers cluster in Germany and Switzerland, creating single-source vulnerability.
- Reference method stringency:CDC cholesterol standardization program requirements extend validation timelines for new assay launches.
- Point-of-care substitution:Electrochemical lipid panels bypass laboratory infrastructure for urgent care settings.
Strategic Opportunities
- Home test kit reimbursement:Select United States private payers now cover direct-to-consumer HDL screening under wellness benefit riders.
- AI-assisted result interpretation:Machine learning integration with smartphone-connected readers enables risk stratification without physician consultation.
- Subfractionation assay demand:Cardiology research centers seek HDL2b and HDL3 quantification for atherosclerosis progression studies.
Industry Challenges
- Clinical laboratory technologist shortages:North American and Western European staffing gaps limit assay volume expansion regardless of kit availability.
- Cross-platform reagent validation:Each automated analyzer requires distinct stability testing, fragmenting manufacturing runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDL Cholesterol Kits Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Lab Kits, Home Test Kits, Reagent Strips Technology: Electrochemical, Spectrophotometric, Colorimetric, Enzymatic End User: Hospitals, Diagnostic Laboratories, Clinics, Pharmacies Application: Screening, Monitoring, Research, Preventive Care |
| Companies Covered | Abbott Laboratories, Randox Laboratories Ltd, Thermo Fisher Scientific, Abcam plc, Merck KGaA, PerkinElmer Inc, Diazyme Laboratories Inc, Roche Diagnostics, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDL Cholesterol Kits Market Strategic Shifts
Reagent chemistry, regulatory harmonization, and procurement centralization are converging to reshape competitive positioning in lipid diagnostics. Manufacturers must now optimize for closed-system compatibility while navigating divergent accuracy standards across major markets.
Microfluidic cartridge technology is miniaturizing HDL quantification into handheld devices. Community health clinics in rural United States counties are piloting these systems for same-result consultation. The technology is compressing the traditional laboratory-to-physician workflow into single-visit encounters, displacing venipuncture-dependent models.
EMA's In Vitro Diagnostic Regulation is mandating notified body conformity assessment for all new CE-marked lipid assays. Manufacturers face expanded clinical evidence requirements for Class B devices. European diagnostic networks are consolidating procurement around suppliers with established IVDR technical documentation, favoring incumbents with regulatory affairs infrastructure.
Integrated delivery networks are consolidating reagent purchasing through single-source contracts. Hospital systems in Germany and Japan now demand decade-long supply guarantees with locked pricing tiers. This behavior is squeezing mid-tier kit manufacturers without balance sheet capacity for long-term liability absorption, concentrating volume among diversified chemical suppliers.
HDL Cholesterol Kits Market Segmentation
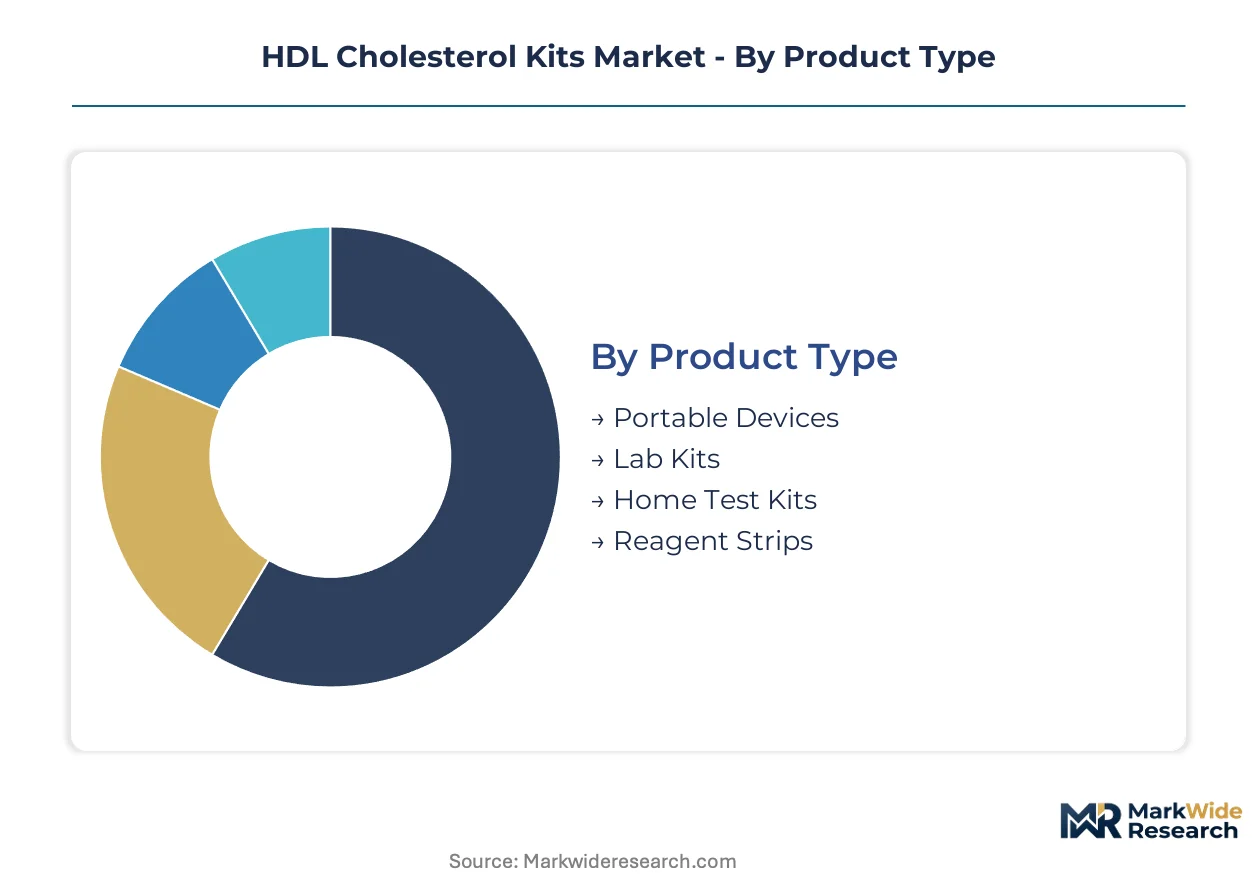
HDL cholesterol kits fragment across four distinct axes that determine pricing power, channel access, and regulatory burden. Product type and technology choices lock manufacturers into specific customer relationships, while end-user concentration and application scope dictate volume scalability and margin profiles.
Product Type:
Channel strategy bifurcates sharply between institutional procurement and direct-to-consumer routes, with reimbursement status determining viable price points.
- Lab Kits:High-throughput enzymatic reagent systems designed for automated analyzers with closed-system compatibility requirements. Hospital central laboratories in the United States and Germany concentrate procurement through decade-long supply contracts with locked pricing tiers, favoring manufacturers with balance sheet capacity for long-term liability absorption.
- Home Test Kits:Single-use cartridge-based systems enabling capillary blood sampling with smartphone-connected result interpretation. Select United States private payers now cover these under wellness benefit riders, accelerating direct-to-consumer preventive care models.
- Portable Devices:Handheld electrochemical analyzers for point-of-care lipid panels in urgent care settings.
- Reagent Strips:Disposable consumables for integrated multi-analyte testing platforms.
Lab Kits dominate installed base. Home Test Kits are where expansion concentrates.
Technology:
Margin concentration tracks reagent recurring revenue versus capital equipment sales, with chemistry choice determining regulatory validation burden.
- Enzymatic:Polyethylene glycol-modified enzyme methods achieving ±3% coefficient of variation against CDC reference standards. Direct clearance formulations eliminate pretreatment steps, reducing labor costs for high-throughput diagnostic laboratories in Japan and Germany.
- Colorimetric:Homogeneous assays employing antibody-separation techniques with established IVDR technical documentation. European diagnostic networks consolidate procurement around suppliers with notified body conformity assessments, favoring incumbents with regulatory affairs infrastructure.
- Electrochemical:Emerging positioning for handheld point-of-care devices with microfluidic cartridge miniaturization.
- Spectrophotometric:Traditional absorbance-based detection retained for research laboratory applications.
Enzymatic methods capture the bulk of recurring revenue. Electrochemical platforms are climbing the fastest.
End User:
Customer concentration patterns reflect staffing constraints and reimbursement structures across healthcare delivery systems.
- Diagnostic Laboratories:Automated liquid handling systems compress turnaround times, forcing reagent reformulation for closed-system analyzer compatibility. Clinical laboratory technologist shortages in North America and Western Europe rotate procurement priorities toward systems that reduce manual pipetting steps.
- Hospitals:Integrated delivery networks consolidate reagent purchasing through single-source contracts with supply guarantee demands.
- Clinics:Community health facilities in rural United States counties pilot microfluidic cartridge systems for same-result consultation workflows.
- Pharmacies:Retail health settings with limited laboratory infrastructure seeking waived-test classification for lipid screening.
Diagnostic Laboratories anchor volume commitment. Clinics represent the steepest expansion trajectory.
Application:
Use case differentiation separates commodity screening from specialized research with distinct margin and validation requirements.
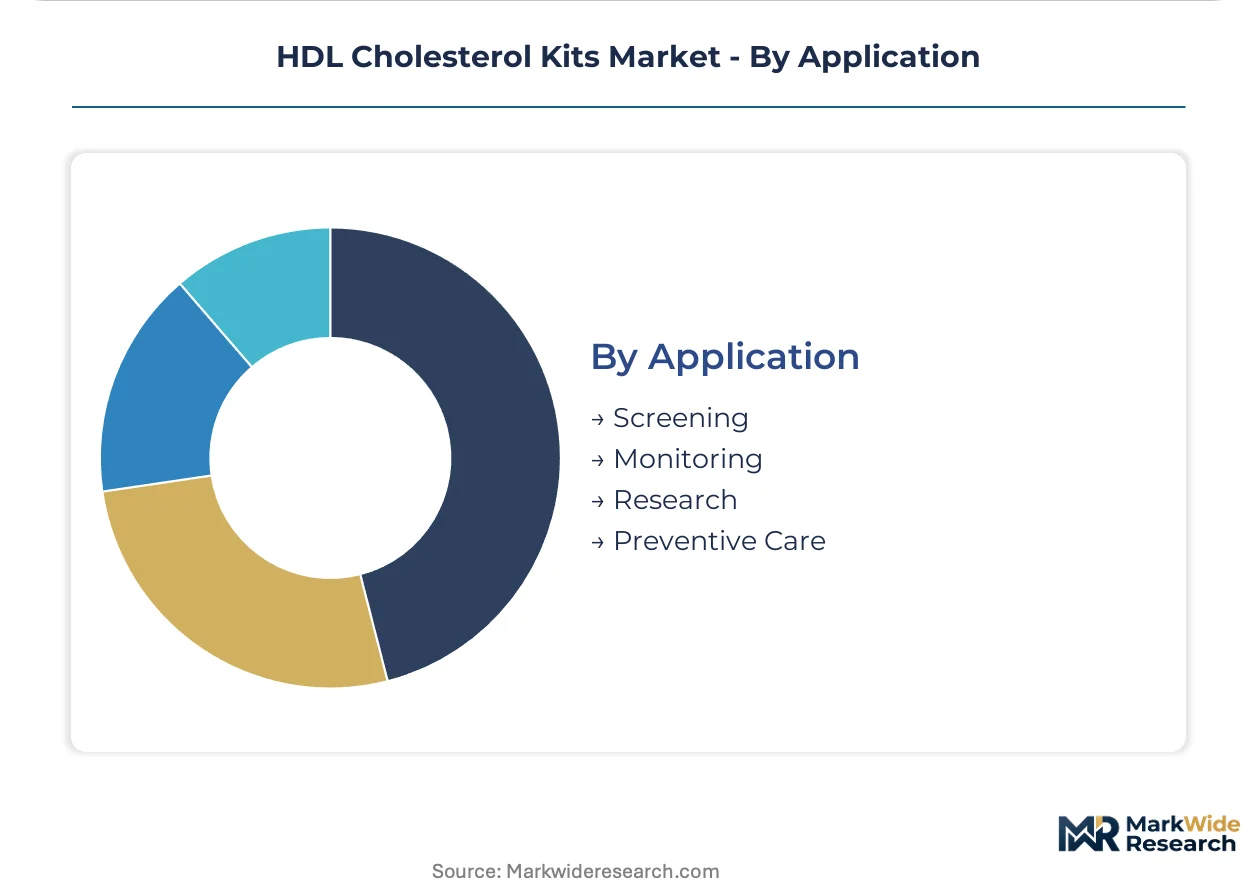
- Screening:Population-level lipid panel testing driven by Medicare coverage expansion for annual assessments in the United States and Ministry of Health, Labour and Welfare metabolic syndrome programs in Japan.
- Monitoring:Therapeutic intervention tracking for statin therapy management in cardiology practices.
- Research:HDL2b and HDL3 subfractionation assays for atherosclerosis progression studies at specialized cardiology research centers.
- Preventive Care:Direct-to-consumer risk stratification without physician consultation through AI-assisted result interpretation.
Screening commands the largest addressable base. Research commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cholesterol standardization requirements anchor procurement decisions in the United States, while EMA IVDR implementation reshapes European market access. Japan's PMDA enforces Ministry of Health quality benchmarks that filter supplier eligibility. These regulatory architectures concentrate kit validation investments in three dominant geographies.
United States
Medicare coverage expansion for annual lipid panels pulls screening volumes into hospital networks and diagnostic laboratories. FDA Class II device classification with 510(k) premarket notification mandates clinical accuracy validation against CDC reference methods. The Boston-Cambridge corridor hosts specialized cardiology research centers driving subfractionation assay demand for atherosclerosis studies.
Germany
Integrated delivery networks consolidate reagent purchasing through decade-long supply contracts with locked pricing tiers. EMA In Vitro Diagnostic Regulation mandates notified body conformity assessment for CE marking of new lipid assays. The Rhine-Ruhr industrial cluster concentrates polyethylene glycol enzyme suppliers, creating single-source vulnerability for raw material procurement.
Japan
Ministry of Health, Labour and Welfare metabolic syndrome screening programs target adults over 40, accelerating preventive cardiology volumes. PMDA enforces quality standards for imported diagnostic reagents that extend registration timelines for multinational manufacturers. The Kanto region around Tokyo anchors diagnostic laboratory concentration with automated liquid handling system deployment.
China
NMPA priority review pathway accelerates timelines for innovative IVD products, reshaping market access strategy for lipid assay manufacturers. Aging demographics and urban hospital expansion drive central laboratory throughput requirements. The Yangtze River Delta industrial corridor concentrates domestic reagent producers seeking import substitution for enzymatic chemistry components.
Switzerland
Swissmedic oversight aligns with EMA performance criteria while maintaining distinct notification procedures for lipid panel accuracy standards. Precision diagnostics clusters in Basel and Zurich support pharmaceutical trial endpoint applications for HDL quantification. The country's chemical manufacturing base supplies specialized polyethylene glycol-modified enzymes to global kit manufacturers.
HDL Cholesterol Kits Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with consolidated procurement contracts favoring diversified chemical suppliers over pure-play reagent vendors. The installed-base loyalty dynamics of automated analyzer platforms create switching costs that protect incumbent positions. Three archetypes dominate: diversified life science conglomerates with broad reagent catalogs, specialized in vitro diagnostic manufacturers with regulatory affairs infrastructure, and emerging point-of-care device developers with microfluidic technology. Competitive moves concentrate on strategic partnerships for closed-system compatibility and portfolio diversification into subfractionation assays.
Among diversified conglomerates, Abbott Laboratories and Thermo Fisher Scientific exemplify the integrated platform archetype, leveraging analyzer installed bases to sustain consumable pull-through. Randox Laboratories Ltd occupies a position within the specialist tier, differentiated by subfractionation assay capabilities that serve cardiology research applications. These three anchors illustrate how regulatory documentation depth and supply guarantee capacity determine contract eligibility in consolidated procurement environments.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Randox Laboratories Ltd |
| Thermo Fisher Scientific |
| Abcam plc |
| Merck KGaA |
| PerkinElmer Inc |
| Diazyme Laboratories Inc |
| Roche Diagnostics |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day enzyme lead times from German and Swiss suppliers compress pricing power for mid-tier kit manufacturers while locking in decade-long supply guarantees for diversified chemical conglomerates. This inventory bandwidth differential separates balance-sheet-heavy incumbents from pure-play reagent vendors in consolidated procurement environments.
Pricing Analysis
Contract pricing for enzymatic reagents spreads by tier across the United States, Germany, and Japan, with hospital systems demanding locked pricing tiers over multi-year supply agreements. Three-tier pricing structure across premium, standard, and economy levels tracks IVDR documentation depth and closed-system compatibility certification. Cost compression in mid-tier segments is intensifying because integrated delivery networks consolidate purchasing through single-source contracts. Diagnostic laboratories with automated analyzer installed bases show lowest price sensitivity, while community health clinics in rural United States counties exhibit highest sensitivity to per-test consumable costs.
Supply Chain Analysis
Germany and Switzerland anchor polyethylene glycol-modified enzyme production for homogeneous assay chemistries, with the Rhine-Ruhr industrial cluster hosting specialized biochemical manufacturers. Kit assembly draws from antibody-separation components sourced through European notified body-certified suppliers and plastic consumables from East Asian molders. Single-source vulnerability concentrates in enzyme substrate supply, where two German suppliers control bulk fermentation capacity. Distribution runs through diagnostic distributor networks serving hospital central laboratories, with direct procurement channels expanding for integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-system analyzer platforms are reshaping competitive economics around installed-base loyalty and consumable pull-through, with interoperability requirements for CDC-standardized assays creating ecosystem lock-in effects.
For Market Incumbents: Compound analyzer platform dominance through backward integration into polyethylene glycol enzyme production, securing captive supply against raw material concentration risk. Deepen regulatory affairs infrastructure for IVDR technical documentation to maintain contract eligibility in European diagnostic network consolidations. Prioritize subfractionation assay R&D to defend margin position against emerging point-of-care electrochemical substitutes. For New Entrants and Emerging Players: Differentiate on microfluidic cartridge miniaturization for community health clinic and urgent care white-space, where waived-test classification bypasses laboratory infrastructure requirements. Target United States private payer wellness benefit riders for home test kit reimbursement traction. Pursue strategic partnerships with smartphone-connected reader developers for AI-assisted result interpretation capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue consumables play because enzymatic reagent pull-through from installed analyzer bases generates predictable cash flows across screening volume cycles. Acquisition candidates with established IVDR documentation and closed-system compatibility certifications command premium positioning. Monitor FDA cholesterol standardization program updates as signal for assay reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR notified body conformity assessment secures European diagnostic network procurement eligibility. |
| Hospital System Partnership | Decade-long supply contracts with locked pricing tiers anchor volume commitment from integrated delivery networks. |
| Backward Integration | In-house polyethylene glycol enzyme production mitigates single-source vulnerability from German-Swiss suppliers. |
| Software Companion Development | AI-assisted smartphone result interpretation enables direct-to-consumer risk stratification without physician consultation. |
| Reimbursement Strategy | Wellness benefit rider coverage expansion accelerates home test kit adoption in United States private payer markets. |
Study Parameters
A standing panel of clinical laboratory directors, hospital procurement managers, diagnostic reagent R&D leads, and regulatory affairs specialists provided ongoing calibration against secondary validation sources. Primary fieldwork combined structured interviews with GPO contracts managers and biomedical engineers at integrated delivery networks with trade data from FDA 510(k) filings, EMA IVDR technical documentation databases, and hospital procurement records. Bottom-up reagent volume estimates triangulated against top-down screening program enrollment data from Medicare and Japan's Ministry of Health, Labour and Welfare.
Model outputs were validated against external benchmarks including CDC cholesterol standardization program participation rates and automated analyzer installed base disclosures from major platform manufacturers. Segmentation modeling across product type, technology chemistry, end-user concentration, and application scope generated volume and value trajectories over the projection horizon. CAGRs were derived from fitted growth curves incorporating preventive cardiology mandate expansion, enzymatic assay advancement, and point-of-care substitution effects.
Material uncertainties — regulatory divergence between FDA and EMA performance criteria, clinical laboratory technologist shortage severity, and polyethylene glycol enzyme supply disruption — sit outside the modeled envelope. Forecasts reflect assumptions about screening volume continuity and reimbursement stability that may require revision upon material shifts in healthcare policy or diagnostic platform technology. Recalibration cycles align with material shifts in regulatory harmonization, procurement consolidation behavior, and point-of-care technology adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Population Screening Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Global Liver Cancer Diagnostics Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
Inflammatory Markers Market